
 China Major Home Appliances Market | 2026-2036
China Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
China Major Home Appliances Market Outlook
Premium energy-efficiency certification is reorganizing competitive dynamics in China's major home appliance sector. Haier Group leverages its smart factory network to sustain leadership in connected refrigeration systems. Midea Group anchors its position through in-house compressor production and scale advantages across southern manufacturing clusters. Gree Electric Appliances Inc. specializes in high-performance inverter air conditioning technology that dominates commercial specification channels.
China major home appliances comprise large-format domestic equipment including refrigerators, washing machines, air conditioners, and microwaves, typically exceeding 50 liters capacity or 1,000 watts power draw, manufactured through stamped steel forming, refrigerant charging, and automated assembly processes designed for continuous residential and commercial use. Refrigerators and air conditioners command the largest revenue pools, with inverter compressor technology and variable-speed drives capturing disproportionate margin share. Smart Appliances and IoT-Enabled segments are expanding fastest as MIIT's digital infrastructure standards push connectivity into baseline specifications, while Standard Appliances face pricing pressure in rural distribution channels.
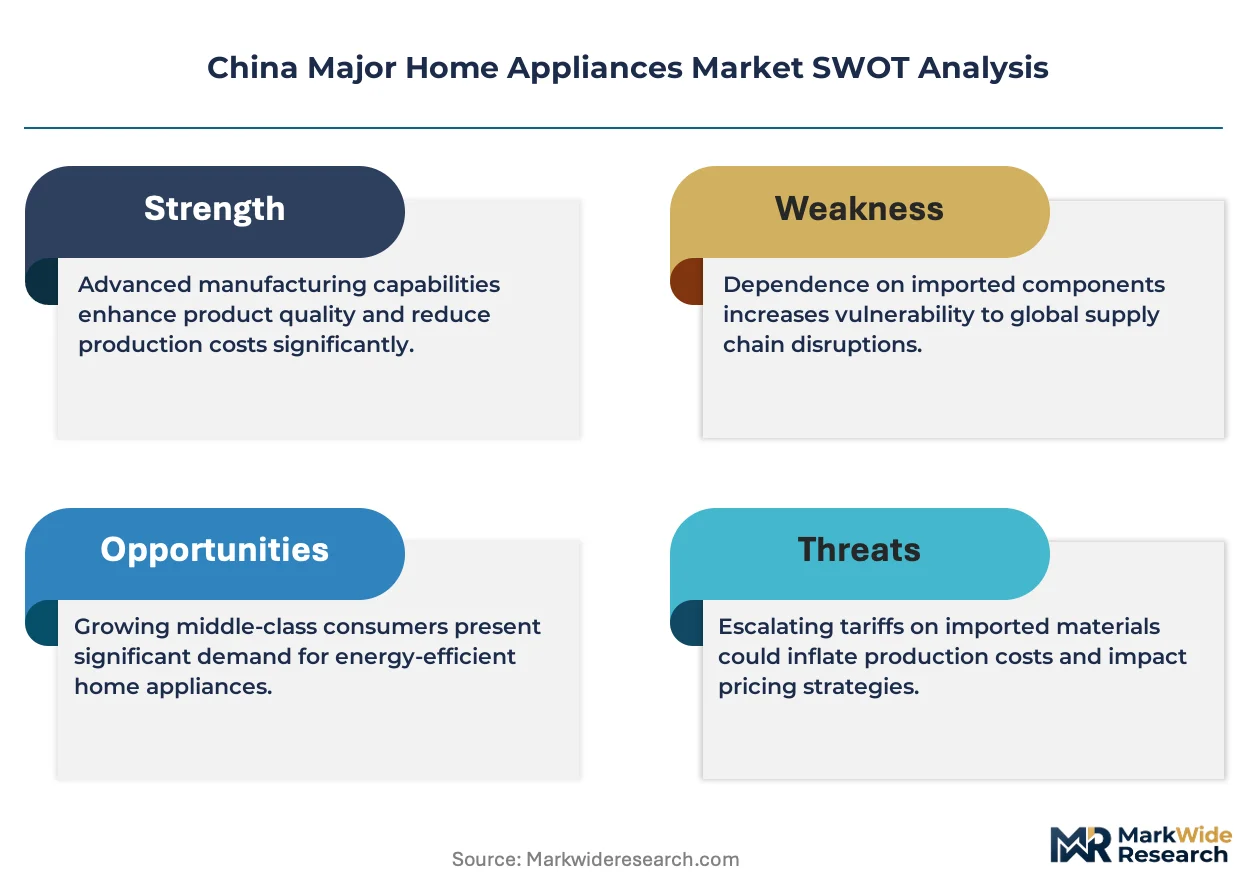
MIIT enforces GB energy-efficiency grades that directly restrict market access for products below tier-3 ratings, compressing legacy manufacturer margins. SAMR monitors labeling compliance and anti-competitive practices across online and offline distribution channels, reshaping how brands structure channel partnerships. China's dual carbon goals from MEE impose escalating refrigerant transition requirements that force R&D prioritization toward low-GWP alternatives. Stakeholders must weigh captive component production against modular sourcing strategies as efficiency regulations tighten and smart connectivity becomes a baseline purchase criterion rather than a premium differentiator.
Market Dynamics
MIIT's smart manufacturing mandates and GB energy-efficiency grades are compressing legacy product lines while forcing manufacturers to reconfigure factory automation and refrigerant portfolios simultaneously.
Growth Catalysts
- Urban household upgrade cycles:Coastal provinces including Guangdong, Jiangsu, and Zhejiang are accelerating replacement demand for connected refrigeration and climate systems as residential renovation activity intensifies.
- MIIT digital infrastructure standards:Mandatory IoT connectivity protocols are elevating baseline specifications across air conditioning and washing machine categories, creating pull-through for smart factory investments.
- R-32 and R-290 refrigerant transition:MEE dual carbon goals are mandating low-GWP alternatives that favor manufacturers with captive compressor R&D capabilities.
Market Restraints
- Copper and steel input volatility:Stamped steel forming and refrigerant charging processes expose margins to commodity price swings that compress tier-3 product economics.
- Compressor supply concentration:Southern manufacturing clusters dominate variable-speed drive production, creating geographic dependency for brands without in-house motor manufacturing.
- GB tier-3 efficiency floor:SAMR labeling compliance restricts market access for legacy product architectures, forcing inventory write-downs among distributors.
Strategic Opportunities
- Western province penetration:Sichuan and Shaanxi demonstrate underpenetrated demand for inverter air conditioning as household income thresholds cross appliance ownership tipping points.
- Commercial specification channels:High-performance inverter systems are capturing specification-driven projects in hospitality and healthcare verticals.
- Modular smart home integration:Convergence between appliance connectivity protocols and residential energy management systems is opening bundled service models.
Industry Challenges
- Refrigerant chemist talent scarcity:Low-GWP alternative development requires specialized thermal engineering expertise that concentrates in state-affiliated research institutes.
- Smart factory capex intensity:Automated assembly line reconfiguration for connected product variants demands capital deployment that strains mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Major Home Appliances Market |
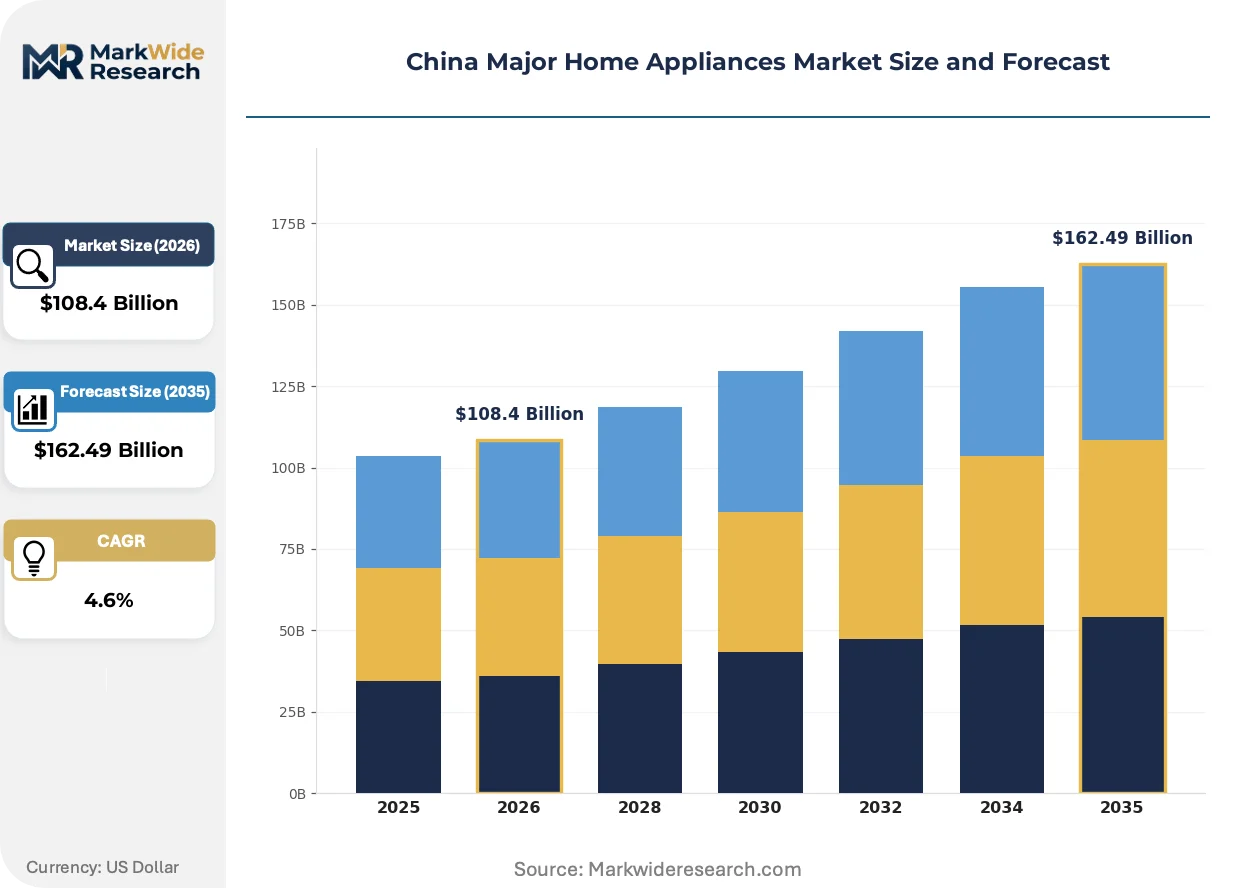
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $162.49 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Standard Appliances End User: Residential, Commercial, Institutional, Retail Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Haier Group, Midea Group, Gree Electric Appliances Inc., Hisense Group, TCL Technology, Aux Group, Galanz, Changhong, Skyworth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Major Home Appliances Market Strategic Shifts
Connectivity integration and refrigerant chemistry are converging to redefine product architecture, with efficiency certification and procurement patterns shifting in parallel.
Inverter compressor technology with variable-speed drives is fragmenting traditional fixed-speed product hierarchies. Urban residential buyers in coastal provinces are specifying variable-speed refrigeration and climate systems as baseline requirements. This fragmentation is compressing margin pools for manufacturers dependent on legacy single-speed motor platforms.
MEE refrigerant transition mandates under China's dual carbon goals are accelerating R-32 and R-290 adoption timelines. Compressor manufacturers must revalidate thermal performance curves and safety protocols for flammable alternatives. Air conditioning categories face the steepest compliance curves, with Gree and Midea restructuring southern manufacturing clusters around low-GWP charging infrastructure.
Household procurement is compressing replacement cycles as GB energy-efficiency grades reshape purchase criteria. Retail channels in Guangdong and Zhejiang are unbundling installation services from hardware transactions. This behavioral shift is most visible in tier-1 cities where specification-driven buyers prioritize tier-1 and tier-2 efficiency ratings over brand loyalty.
China Major Home Appliances Market Segmentation
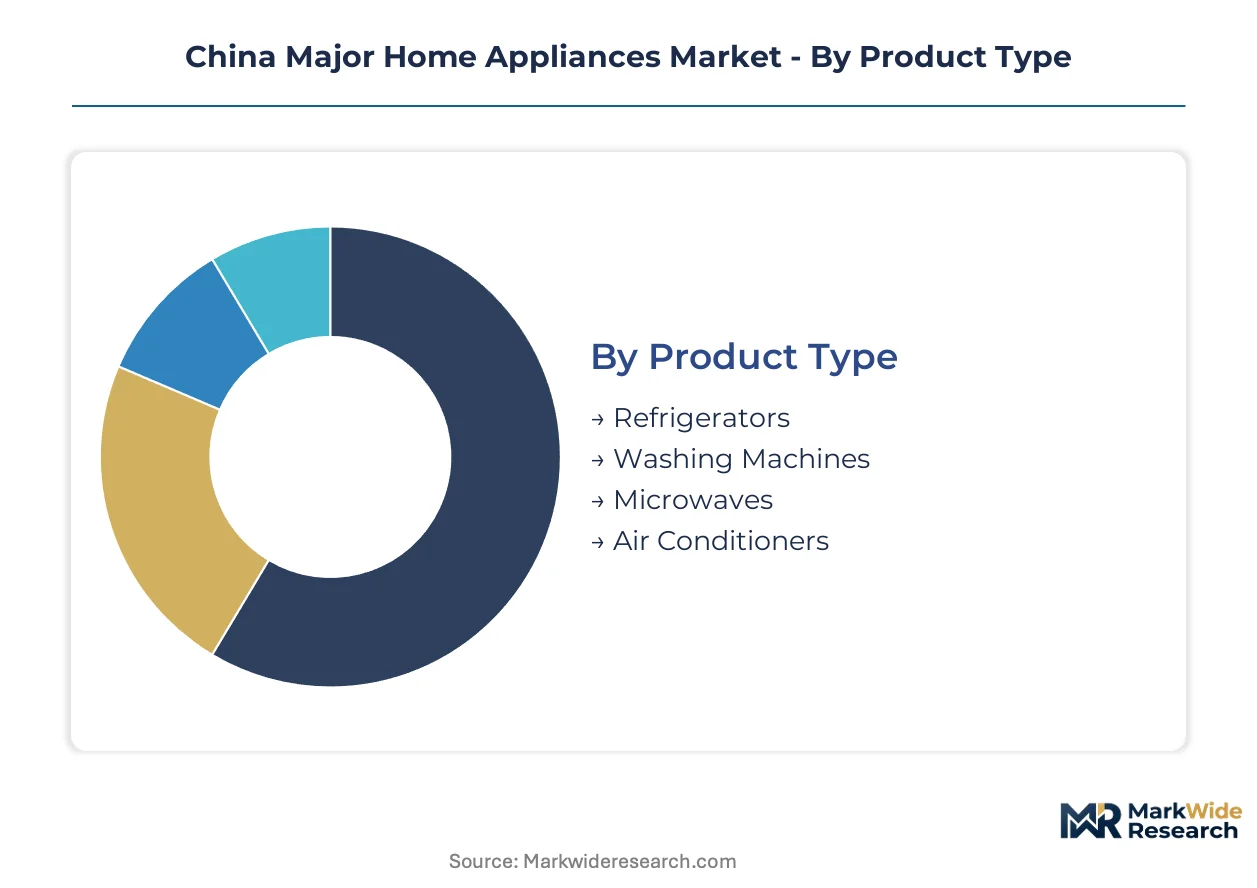
Segmentation in China's major home appliance sector tracks how GB energy-efficiency grades and MIIT connectivity mandates split demand across technical specifications and procurement channels. Manufacturers align product portfolios to these regulatory tiers while coastal urban buyers accelerate upgrade cycles.
Product Type:
MIIT's tiered efficiency certification creates divergent margin structures across equipment categories, with inverter-capable systems commanding specification premiums in renovation-driven procurement.
- Refrigerators:Variable-speed compressor architectures with connected temperature management dominate coastal urban replacement cycles. Guangdong and Jiangsu households specify tier-1 and tier-2 efficiency ratings as baseline requirements during residential renovation.
- Air Conditioners:Inverter-driven climate systems with R-32 refrigerant charging capture disproportionate margin share in commercial specification channels. MEE dual carbon goals are compressing fixed-speed product lines while Gree and Midea restructure southern manufacturing clusters around low-GWP infrastructure.
- Washing Machines:Drum-format units with variable-speed motor drives address water-efficiency mandates in tier-1 cities.
- Microwaves:Magnetron-based heating platforms face pricing pressure as connectivity features fail to differentiate utility in residential kitchens.
Established volume favors Air Conditioners; emerging adoption favors connected Refrigeration systems.
Technology:
Cost tier stratification separates captive R&D investments from modular sourcing strategies as baseline specifications absorb features previously sold as premiums.
- Smart Appliances:MIIT-mandated IoT protocols now embed connectivity as standard rather than differentiated functionality. Haier's smart factory network produces refrigeration systems with integrated energy management interfaces specified by Zhejiang renovation contractors.
- IoT-Enabled:Cloud-connected diagnostic and predictive maintenance capabilities are climbing the fastest as SAMR labeling compliance elevates digital traceability requirements across distribution channels.
- Energy-Efficient:GB tier-1 and tier-2 certified products concentrate procurement in coastal provinces where electricity tariffs accelerate payback calculations.
- Standard Appliances:Fixed-speed motor platforms without connectivity face inventory write-downs as SAMR restricts market access below tier-3 ratings.
Procurement gravity centers on Smart Appliances in tier-1 cities; rural channels retain Standard Appliance liquidation.
End User:
Application-specific thermal loads and duty-cycle requirements determine compressor specification and warranty structuring across procurement segments.
- Residential:Household upgrade cycles in Guangdong, Jiangsu, and Zhejiang drive specification-driven replacement of fixed-speed refrigeration and climate systems with connected inverter alternatives.
- Commercial:Hospitality and healthcare verticals specify high-performance inverter air conditioning with extended warranty terms and predictive maintenance contracts.
- Institutional:Government and educational procurement favors tier-1 efficiency ratings with centralized maintenance protocols.
- Retail:Channel inventory requirements expose distributors to GB compliance transition risks as legacy product architectures face write-downs.
Residential replacement sustains volume concentration; Commercial specification channels deliver margin expansion.
Distribution Channel:
Geographic concentration of manufacturing clusters shapes fulfillment economics and installation service bundling across procurement pathways.
- Online Retailers:E-commerce platforms in Guangdong and Zhejiang are unbundling installation services from hardware transactions, compressing bundled-margin models.
- Specialty Stores:Specification-driven buyers in tier-1 cities prioritize efficiency ratings over brand loyalty through dedicated appliance retail networks.
- Hypermarkets:Volume-oriented distribution concentrates tier-3 certified inventory in price-sensitive procurement segments.
- Direct Sales:Manufacturer-controlled channels capture commercial project specifications with customized compressor configurations and service bundling.
Online Retailers gain share fastest in coastal provinces; Direct Sales anchor commercial specification capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's major home appliances sector maintains a substantial export surplus in refrigeration and climate equipment, though rising domestic upgrade cycles are redirecting capacity toward coastal urban replacement demand. Import dependency concentrates in high-efficiency compressor components and specialized refrigerant chemistries. Regional production clusters align with MIIT's smart manufacturing corridors and MEE's dual carbon compliance zones.
Guangdong Province
Household renovation activity in Shenzhen and Guangzhou accelerates replacement demand for connected inverter air conditioners. SAMR's labeling compliance enforcement reshapes distributor inventory requirements across Pearl River Delta retail networks. Midea Group anchors manufacturing scale in Foshan through in-house compressor production and automated assembly reconfiguration for low-GWP refrigerant charging.
Jiangsu Province
Nanjing and Suzhou households specify tier-1 and tier-2 GB efficiency ratings as baseline procurement criteria during residential upgrades. MIIT's mandatory IoT connectivity protocols elevate smart refrigerator specifications across Nantong manufacturing clusters. Haier Group leverages smart factory networks in Changzhou to produce integrated energy management interfaces for Zhejiang renovation contractors.
Zhejiang Province
Hangzhou and Ningbo buyers prioritize efficiency certification over brand loyalty in specification-driven procurement channels. GB standards for energy efficiency compress margins on legacy fixed-speed product lines through Taizhou distribution hubs. Gree Electric Appliances Inc. specializes high-performance inverter systems from Zhuhai-adjacent southern clusters serving commercial specification verticals.
Sichuan-Chongqing Region
Chengdu and Chongqing household income thresholds cross appliance ownership tipping points for inverter air conditioning penetration. Western province underpenetration creates pull-through for variable-speed drive distribution networks extending from coastal manufacturing bases. Local distributor partnerships restructure around unbundled installation services and tier-1 efficiency rating procurement.
Shandong Peninsula
Qingdao's refrigeration equipment production concentrates export-oriented capacity alongside domestic smart factory investments. Shandong households demonstrate accelerating replacement cycles for connected washing machines with variable-speed motor drives. Regional manufacturing aligns with MIIT's digital infrastructure standards for cloud-connected diagnostic capabilities across drum-format unit production.
China Major Home Appliances Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and captive R&D depth. The vendor base concentrates around three structural tiers: integrated conglomerates with smart factory networks, compressor specialists with in-house motor manufacturing, and modular assemblers dependent on southern component clusters. Strategic archetypes separate captive refrigerant charging capability from outsourced low-GWP transition compliance. Competitive moves center on automated assembly line reconfiguration and direct sales channel expansion into commercial specification verticals.
Within the integrated conglomerate tier, Haier Group and Midea Group occupy positions defined by smart factory network scale and in-house component production. Gree Electric Appliances Inc. exemplifies the compressor-specialist archetype through concentrated southern manufacturing cluster control. These three listed entities represent divergent responses to MIIT's connectivity mandates and MEE's refrigerant transition timelines.
| Leading Market Players |
|---|
| Haier Group |
| Midea Group |
| Gree Electric Appliances Inc. |
| Hisense Group |
| TCL Technology |
| Aux Group |
| Galanz |
| Changhong |
| Skyworth |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with southern manufacturing clusters lock in compressor supply access and price visibility for tier-1 efficiency products, insulating procurement teams from copper and steel input volatility that destabilizes spot-market tier-3 inventory economics.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with GB tier-1 certification and captive compressor production as primary differentiation drivers. Cost compression in economy-tier fixed-speed platforms is intensifying because SAMR labeling compliance restricts market access below tier-3 ratings. Specification-driven commercial buyers demonstrate lowest price sensitivity, while rural distribution channels face acute margin pressure from unbundled installation services.
Supply Chain Analysis
China anchors stamped steel forming and refrigerant charging infrastructure, with South Korea and Japan feeding specialized variable-speed drive components and magnetron assemblies. Raw material draws from copper concentrate imports, cold-rolled steel coil, and low-GWP refrigerant chemistries. Single-source vulnerability concentrates in southern compressor manufacturing clusters. Distribution runs through Pearl River Delta logistics hubs into unbundled online retail and direct commercial specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's major home appliance sector operates as a substitution defense against modular smart home ecosystems that threaten to disaggregate appliance control interfaces into third-party platforms.
For Market Incumbents: Compound smart factory network scale with captive low-GWP refrigerant charging infrastructure to defend against emerging modular assemblers. Prioritize MIIT-mandated IoT protocol integration as a defensive moat. Channel control through direct sales into commercial specification verticals anchors margin pools.
For New Entrants and Emerging Players: GB tier-1 efficiency fast-track certification opens procurement access in Sichuan and Shaanxi where household income thresholds cross appliance ownership tipping points. Target western province inverter air conditioning penetration with unbundled installation service models. Go-to-market through local distributor partnerships restructuring around tier-1 rating procurement.
For Investors and Strategic Acquirers: Capital is best deployed toward compressor specialists with in-house motor manufacturing and low-GWP R&D capabilities. Long-term viability hinges on refrigerant chemistry talent access and southern manufacturing cluster control. Watch MEE dual carbon goal enforcement timelines as inflection signal for stranded fixed-speed asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Factory Network Expansion | MIIT connectivity mandates elevate automated assembly line reconfiguration as baseline competitive requirement. |
| Low-GWP Refrigerant Transition | MEE dual carbon goals force R-32 and R-290 adoption timelines that favor captive R&D investments. |
| Direct Commercial Channel Buildout | Hospitality and healthcare specification verticals deliver extended warranty and predictive maintenance contract premiums. |
| Western Province Distribution Partnerships | Sichuan and Shaanxi underpenetration creates pull-through for variable-speed drive distribution network extension. |
| Modular Smart Home Integration | Convergence with residential energy management systems opens bundled service models beyond hardware transactions. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with appliance manufacturing executives, MIIT regulatory affairs leads, commercial procurement managers at hospitality chains, and compressor R&D directors; and secondary validation through SAMR labeling compliance databases, MIIT smart manufacturing corridor disclosures, MEE refrigerant transition filings, and customs trade records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Across the projection horizon, the analytical framework modeled demand by product type, technology tier, end-user application, and distribution channel, with CAGRs derived from regression analysis against household renovation expenditure indices and electricity tariff trajectories. Industry-specific inputs incorporated GB energy-efficiency grade adoption curves and MIIT IoT protocol penetration assumptions.
Underlying assumptions cover regulatory enforcement consistency and refrigerant chemistry talent availability, with deviation risk concentrated in MEE dual carbon timeline acceleration and copper price volatility spikes. Recalibration cycles align with material shifts in MIIT mandate enforcement and MEE low-GWP compliance deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Home Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Small Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
UAE Small Home Appliances Market
Home Appliances
Europe Home Appliances Market
Home Appliances
Australia Home Appliances Market