
 UK Facility Management Market | 2026-2036
UK Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
UK Facility Management Market Analytics
Buyer concentration among healthcare estates is expanding as NHS trusts consolidate facilities contracts into fewer, larger integrated service agreements. Mitie Group PLC leverages its technology-led service platform to capture these bundled contracts. ISS Facility Services anchors its position through deep cleaning and security specializations. Serco Group PLC competes aggressively in the public sector infrastructure segment.
Facility management encompasses the coordination of hard services, soft services, and building technology to maintain operational continuity of physical assets. The discipline integrates mechanical and electrical maintenance, workspace provisioning, and environmental control systems to sustain building performance across commercial, institutional, and residential portfolios. Maintenance Services commands the largest share of contract value due to regulatory compliance mandates and lifecycle asset preservation requirements. Energy Management Software within the Technology segment represents the fastest-expanding margin pool as clients prioritize carbon reporting and consumption optimization. Cleaning Services remains structurally mature with intense price competition and thin margins.
The Health and Safety Executive enforces workplace welfare standards that directly shape service scope and staffing ratios across UK contracts. BSI Group publishes PAS 1192 and ISO 41000-series standards that govern facilities management quality frameworks and building information modeling integration. The UK's Building Safety Regulator, established under the Building Safety Act, imposes stricter accountability on dutyholders for high-rise residential and commercial building maintenance. Stakeholders must monitor how the regulator's gateway compliance deadlines reshape capital maintenance planning and long-term service contracting structures.
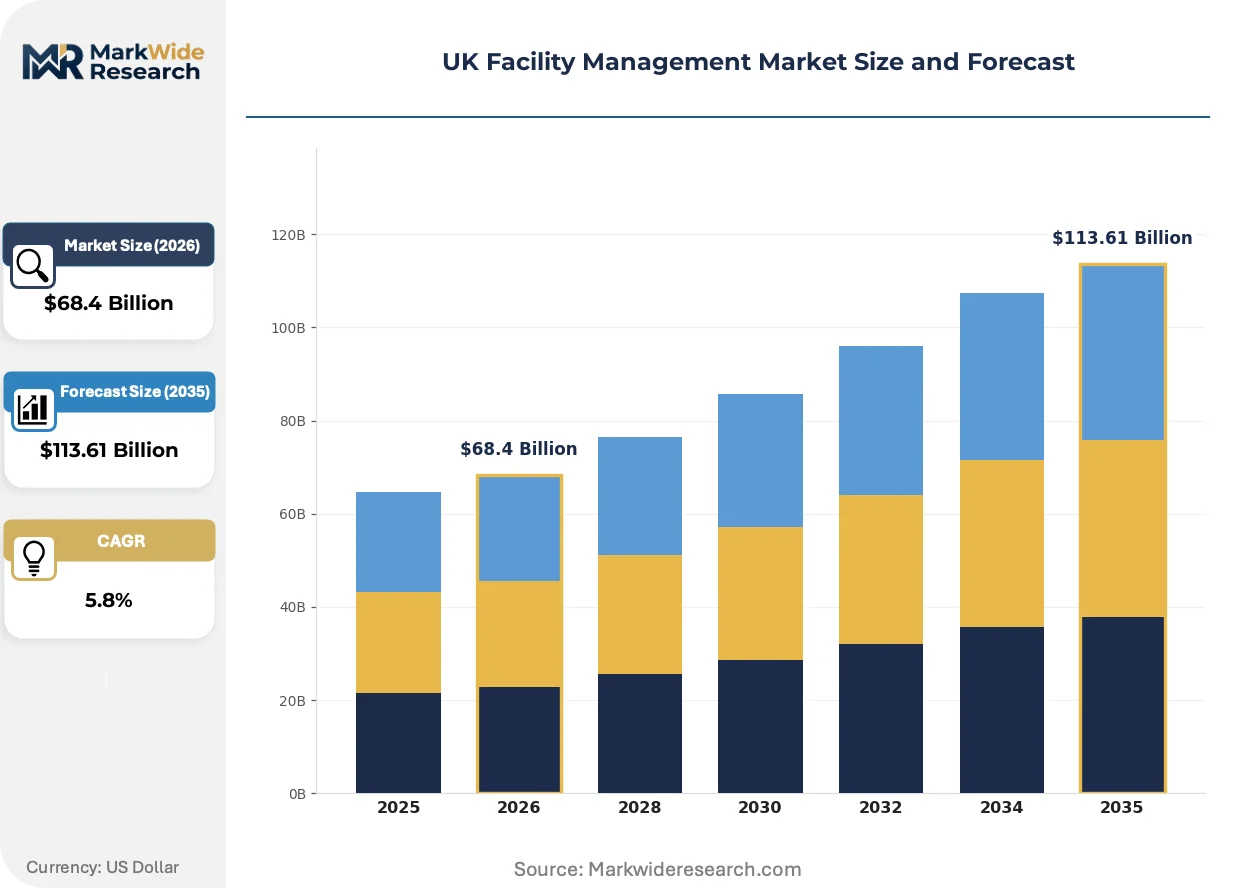
Market Dynamics
The UK's net-zero building regulations are compressing procurement cycles as NHS trusts and commercial landlords race to retrofit estates before 2030 compliance deadlines. This regulatory pressure is bundling previously separate service contracts into integrated facilities management agreements.
Growth Catalysts
- Building Safety Act implementation:The UK's Building Safety Regulator mandates stricter accountability for high-rise maintenance, expanding the scope and duration of contracted FM services.
- NHS estates consolidation:Healthcare trusts are merging facilities contracts into fewer integrated agreements covering hard services, soft services, and building technology.
- Energy Management Software:Carbon reporting requirements under the Streamlined Energy and Carbon Reporting framework are pulling investment into consumption optimization platforms.
Market Restraints
- Skilled technician scarcity:Brexit-related labor mobility restrictions have tightened the supply of certified mechanical and electrical maintenance engineers.
- Input cost volatility:Energy price fluctuations directly compress margins on fixed-price cleaning and security contracts.
- Legacy infrastructure fragmentation:Victorian-era building stock across Northern England and Scotland resists standardized technology retrofitting.
Strategic Opportunities
- Decarbonization retrofit wave:The UK government's Heat and Buildings Strategy creates mandated demand for integrated energy efficiency upgrades across public sector portfolios.
- Technology convergence:Building information modeling integration with Internet of Things sensor networks enables predictive maintenance contracts.
- Integrated service bundling:Procurement frameworks are consolidating hard FM, soft FM, and workplace experience services into single-source agreements.
Industry Challenges
- Gateway compliance timelines:The Building Safety Regulator's phased gateway deadlines force capital maintenance planning acceleration that outpaces contractor capacity scaling.
- Workforce certification gaps:PAS 1192 and ISO 41000-series standards require upskilling programs that FM providers struggle to fund at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Facility Management Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Commercial Buildings, Residential Complexes, Educational Institutions, Healthcare Facilities Technology: Building Automation Systems, IoT Solutions, Energy Management Software, CMMS Tools Pricing Model: Fixed Price, Variable Pricing, Service Level Agreements, Hybrid Models |
| Companies Covered | Mitie Group PLC, ISS Facility Services, CBRE Group Inc., OCS Group UK Ltd., Sodexo SA, G4S Facilities Management UK, Serco Group PLC, Kier Group PLC, Amey Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Facility Management Market Evolving Landscape
Digital twin technology and predictive analytics are compressing the traditional reactive maintenance model across UK commercial and healthcare estates. These innovations are reshaping how asset performance is monitored and how service contracts are structured.
Internet of Things sensor networks deployed across HVAC and electrical systems are consolidating multiple point-solution vendors into unified building technology platforms. NHS trusts in London and the South East corridor are adopting these integrated systems fastest. This consolidation is compressing the addressable market for standalone building automation providers.
The Building Safety Act's gateway compliance regime is forcing dutyholders to document maintenance histories with unprecedented granularity. High-rise residential and commercial building owners must now retain digital records spanning decades. Scotland's devolved building standards are creating regulatory divergence that complicates national contract standardization.
Buyer concentration among consolidated NHS trusts and local authorities is compressing vendor negotiation cycles and demanding outcome-based performance metrics. Traditional input-based contracts covering headcount and hours are yielding to uptime guarantees and energy efficiency targets. London-based healthcare estates are leading this procurement evolution.
UK Facility Management Market Segmentation
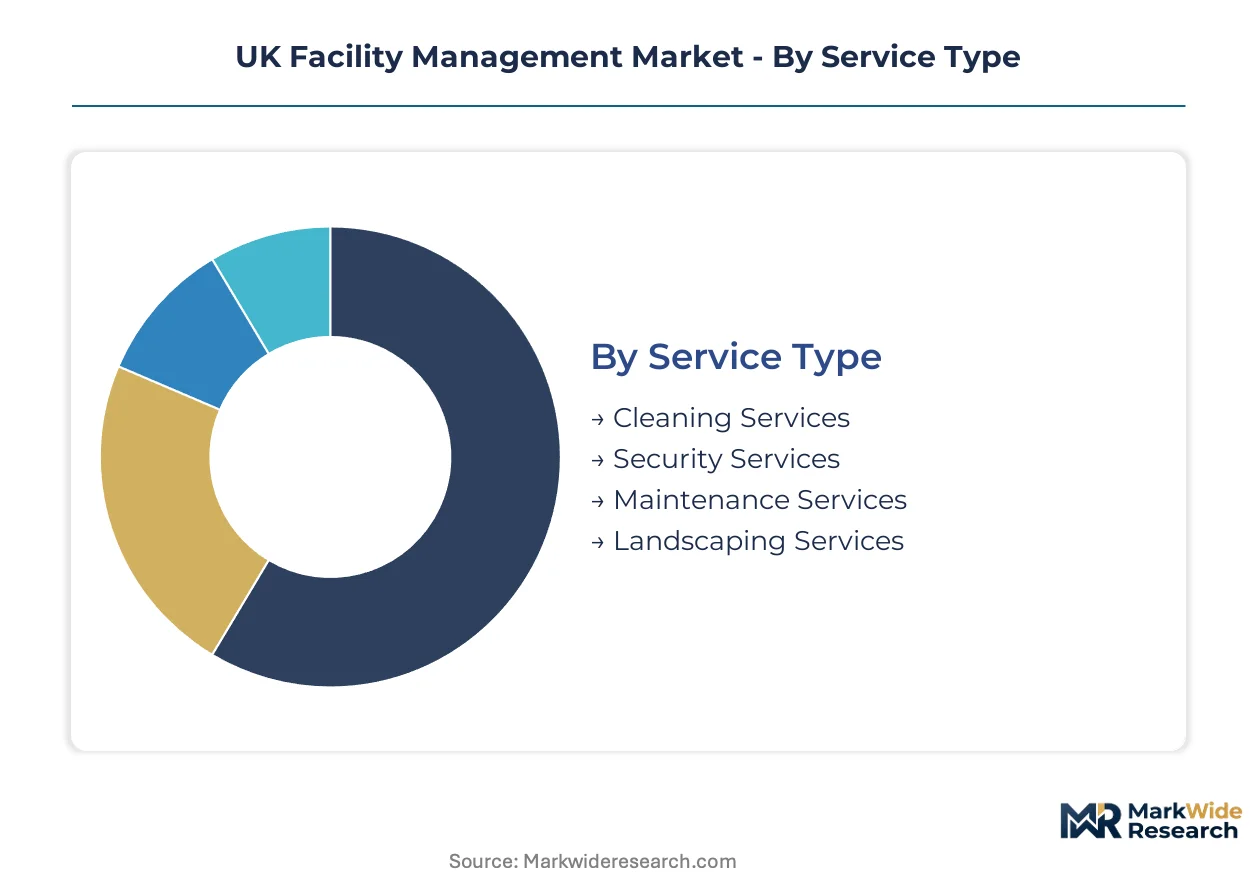
Service bundling across hard and soft FM disciplines is compressing traditional category boundaries as NHS trusts and commercial landlords consolidate procurement. Segmentation clarity enables vendors to align capital deployment with contract profitability and regulatory compliance intensity.
Service Type:
Capital intensity varies sharply across service categories, with hard FM demanding specialized equipment fleets and certified technician benches while soft services require lower fixed asset bases.
- Maintenance Services:Mechanical and electrical systems upkeep requiring mobile engineering units, diagnostic tooling, and compliance documentation for Building Safety Act gateway obligations. NHS estates in London and the South East corridor are consolidating these contracts into decade-long integrated agreements to secure lifecycle asset coverage.
- Cleaning Services:Daily hygiene operations, periodic deep cleans, and infection control protocols across healthcare and commercial portfolios. Victorian-era building stock across Northern England resists standardized service scheduling due to fragmented floorplates and heritage material constraints.
- Security Services:Manned guarding, access control, and surveillance technology deployment with lower capital barriers but intense labor compliance under Health and Safety Executive welfare standards.
- Landscaping Services:Grounds maintenance, seasonal planting, and exterior asset preservation with seasonally variable labor requirements and minimal technology integration.
Maintenance Services absorbs the bulk of installed capacity; Energy Management Software within technology segments is expanding most quickly.
End User:
Application complexity and regulatory exposure determine service customization depth, with healthcare and education commanding the most stringent compliance architectures.
- Healthcare Facilities:NHS trusts requiring 24/7 operational continuity, infection control protocols, and Building Safety Regulator documentation for high-rise clinical buildings. Consolidated procurement frameworks across London and South East trusts are bundling hard FM, soft FM, and building technology into single-source contracts.
- Commercial Buildings:Office portfolios and retail spaces prioritizing workspace experience metrics and net-zero retrofit timelines under Streamlined Energy and Carbon Reporting mandates.
- Educational Institutions:Universities and school estates with seasonal occupancy patterns and capital maintenance backlogs complicating service standardization.
- Residential Complexes:High-rise developments falling under Building Safety Act dutyholder obligations with intensified maintenance record granularity requirements.
Healthcare Facilities commands the deepest contract integration; Commercial Buildings is climbing the fastest as net-zero retrofit deadlines accelerate procurement cycles.
Technology:
Margin profiles diverge between capital-intensive building automation hardware and software platforms with recurring revenue characteristics.
- Energy Management Software:Carbon reporting dashboards, consumption analytics, and efficiency optimization tools for Streamlined Energy and Carbon Reporting compliance. NHS trusts are deploying these platforms fastest to meet 2030 public sector decarbonization targets.
- Building Automation Systems:Integrated HVAC, lighting, and security control infrastructure requiring substantial upfront installation investment and long-term maintenance partnerships.
- IoT Solutions:Sensor networks for predictive maintenance and asset performance monitoring with deployment complexity varying across Victorian-era and modern building stock.
- CMMS Tools:Computerized maintenance management systems for work order tracking and asset lifecycle documentation under Building Safety Regulator record-keeping mandates.
Building Automation Systems retains the largest installed base; Energy Management Software is gaining share fastest through carbon compliance pull-through.
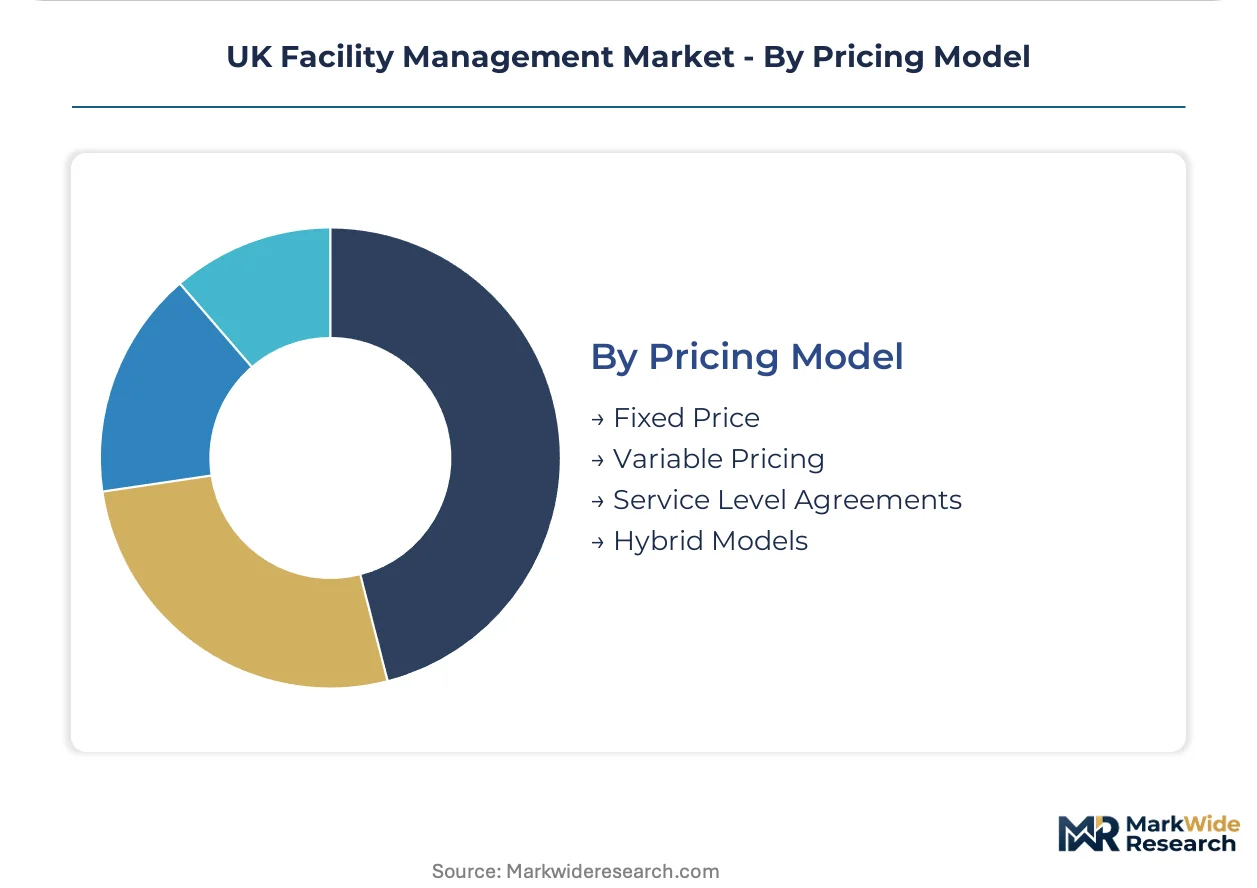
Pricing Model:
Customer risk tolerance and outcome measurability shape pricing structure selection across public and private sector procurement.
- Service Level Agreements:Outcome-based contracts with uptime guarantees and energy efficiency targets replacing input-based headcount metrics. NHS consolidated frameworks are mandating this structure for integrated FM agreements.
- Fixed Price:Predictable cost structures for standardized service scopes with margin compression during energy price volatility periods.
- Variable Pricing:Consumption-linked or index-adjusted terms aligning costs with actual service intensity and input cost movements.
- Hybrid Models:Blended structures combining baseline fixed fees with performance-adjusted variable components for complex multi-service contracts.
Service Level Agreements is capturing the most procurement volume; Hybrid Models is expanding most quickly as buyers seek risk transfer flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for integrated facilities management concentrates in England's southern corridor, where NHS trust consolidation and commercial retrofit deadlines are compressing procurement cycles into multi-service bundled agreements.
London and South East
NHS trusts across London, Kent, and Surrey are merging hard FM, soft FM, and building technology contracts into decade-long single-source agreements. The Building Safety Regulator's gateway compliance deadlines for high-rise clinical buildings are forcing capital maintenance planning acceleration. Canary Wharf and the Thames Valley office corridor are deploying energy management software fastest to meet Streamlined Energy and Carbon Reporting mandates.
Midlands
Manufacturing estates and logistics hubs around Birmingham and Leicester are driving demand for predictive maintenance contracts linked to IoT sensor networks. The Health and Safety Executive enforces stricter welfare standards across these industrial concentrations. Victorian-era building stock in Birmingham's city center resists standardized technology retrofitting, fragmenting service provider portfolios.
North England
Healthcare facilities in Manchester, Leeds, and Newcastle are consolidating procurement frameworks following NHS estates rationalization programs. The Building Safety Act's dutyholder obligations apply to high-rise residential developments across Liverpool and Sheffield. Northern Powerhouse infrastructure commitments are pulling integrated FM contracts into bundled public sector agreements.
Scotland
Devolved building standards under Scottish building regulations are creating compliance divergence from England and Wales. NHS Scotland trusts in Glasgow and Edinburgh are adopting integrated service models at slower rates due to separate procurement frameworks. Historic building concentrations in Edinburgh's Old Town impose heritage material constraints on maintenance scheduling.
Wales
Public sector estates in Cardiff and Swansea are consolidating cleaning and security contracts under Welsh Government procurement frameworks. The Senedd's decarbonization targets for public buildings are accelerating energy management software adoption. Rural healthcare facilities across North Wales face technician scarcity due to geographic dispersion.
UK Facility Management Market Competitive Landscape
London-headquartered providers anchor the premium integrated services tier; regional specialists hold position in single-service maintenance and cleaning segments. The vendor base compresses into three tiers: technology-led bundlers capturing NHS consolidated frameworks, security and hygiene specialists defending narrow verticals, and public sector infrastructure contractors competing on compliance documentation. Dominant competitive moves include strategic partnerships for building technology integration and portfolio diversification into decarbonization retrofit services.
Within the technology-led bundler tier, Mitie Group PLC and Serco Group PLC exemplify providers positioned to capture outcome-based contracts with uptime guarantees. ISS Facility Services anchors the specialist tier through deep cleaning and security competencies. These three names sit within a competitive set where procurement concentration among consolidated NHS trusts is compressing vendor negotiation cycles and demanding performance metrics tied to energy efficiency targets rather than input-based headcount.
| Leading Market Players |
|---|
| Mitie Group PLC |
| ISS Facility Services |
| CBRE Group Inc. |
| OCS Group UK Ltd. |
| Sodexo SA |
| G4S Facilities Management UK |
| Serco Group PLC |
| Kier Group PLC |
| Amey Ltd. |
| Others |
Value Network & Pricing Analysis
Building information modeling integration with IoT sensor networks is compressing cost economics for predictive maintenance contracts while concentrating supply power among certified technology platforms. This convergence simultaneously raises entry barriers for uncertified providers and reshapes how NHS trusts and commercial landlords negotiate bundled service agreements.
Pricing Analysis
Volume concentrates in fixed-price cleaning and security contracts where margins compress under energy price volatility, while margin pools expand fastest in outcome-based service level agreements with uptime guarantees. Three-tier pricing structure across integrated FM platforms, specialist single-service contracts, and regional maintenance providers reflects certification intensity under PAS 1192 and ISO 41000-series standards. Price differentiation hinges on Building Safety Act compliance documentation and gateway readiness. NHS consolidated frameworks show lowest price sensitivity; standalone commercial landlords in Northern England exhibit highest.
Supply Chain Analysis
Certification gating under Health and Safety Executive welfare standards and BSI Group PAS 1192 frameworks restricts technician supply to accredited training programs. Labor supply concentrates in Poland, Romania, and Portugal for mobile engineering units following Brexit mobility restrictions. Raw material dependencies span HVAC components from Germany, electrical diagnostic tooling from Japan, and cleaning chemicals from domestic UK formulation plants. Single-source vulnerability runs through certified mechanical and electrical engineer pools. Distribution feeds from London-based technology platforms to regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Facility Management Market functions as a cost-of-compliance story where the Building Safety Regulator's gateway deadlines erect barrier-to-entry moats for dutyholders with documented maintenance histories.
For Market Incumbents: Anticipate procurement concentration among consolidated NHS trusts by securing decade-long integrated FM agreements before 2030 compliance deadlines. Invest in PAS 1192 certification upskilling programs to defend against technology-led bundlers capturing outcome-based contracts. Prioritize backward integration into energy management software platforms to control carbon reporting capabilities.
For New Entrants and Emerging Players: Digital-channel routes through IoT sensor network partnerships offer lowest-friction entry into predictive maintenance segments. Target Victorian-era building stock across Northern England where standardized service scheduling gaps persist. Pursue white-space in Welsh rural healthcare facilities facing technician scarcity. Lead with CMMS tools for Building Safety Regulator record-keeping mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to technology-led bundlers seeking compliance documentation capabilities. Long-term viability favors platforms with integrated hard FM, soft FM, and building technology stacks under single-source NHS frameworks. Watch NHS estates rationalization velocity as inflection indicator for contract consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Integration | Unifies IoT sensor networks with CMMS tools for predictive maintenance contracts under NHS consolidated frameworks. |
| Certification Investment Program | Secures PAS 1192 and ISO 41000-series credentials required for Building Safety Act gateway compliance documentation. |
| Energy Management Software Deployment | Captures carbon reporting mandates under Streamlined Energy and Carbon Reporting for public sector decarbonization targets. |
| Regional Hub Consolidation | Compresses service delivery costs across London and South East corridor where NHS trust bundling concentrates demand. |
| Decarbonization Retrofit Partnership | Aligns with UK government's Heat and Buildings Strategy for mandated energy efficiency upgrades across public portfolios. |
Research Methodology
Independent corroboration across facilities management executives, NHS estates directors, building technology integration specialists, and Health and Safety Executive compliance officers underwrites the qualitative findings. Primary fieldwork with contract procurement managers at consolidated trusts, mobile engineering unit supervisors, and energy management software vendors combined with secondary validation through NHS procurement framework disclosures, Building Safety Regulator guidance documents, BSI Group standards publications, and SEC filings from listed FM providers. Bottom-up service line sizing and top-down market aggregation triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments growth by service type, end user, technology deployment, and pricing model maturity. The analytical framework models mechanical and electrical maintenance intensity, infection control protocol evolution, carbon reporting adoption curves, and integrated FM bundling velocity. CAGRs derive from contract value analysis, technician bench scaling patterns, and technology platform penetration trajectories. Forecast inputs incorporate NHS estates consolidation timelines and Building Safety Act gateway compliance phasing.
The model holds under sustained regulatory enforcement of PAS 1192 and ISO 41000-series standards; deviation in Building Safety Regulator deadline extensions or Brexit labor mobility policy shifts would revise trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Sweden Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Denmark Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Switzerland Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Singapore Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
Hungary Facility Management Market