
 Italy Office Real Estate Market | 2026-2036
Italy Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Office Real Estate Market Foresight
Class A sustainability certification is bifurcating the Italy office real estate market into premium and secondary tiers. CBRE leverages its pan-European platform to anchor large-scale Milan transactions, while Savills competes through specialized advisory on energy-efficient retrofits. Gabetti Property Solutions dominates domestic mid-market distribution with deep knowledge of Rome and Turin submarkets.
Italy office real estate encompasses commercial buildings designed for administrative, professional, and service-sector operations, typically featuring floor plates of 500–5,000 square meters, HVAC systems meeting Class A or B energy ratings, and fiber-optic connectivity infrastructure. Its primary purpose is to house knowledge-work functions across financial services, technology, and professional consulting sectors. The lease structure dimension reveals long-term contracts still capturing the largest value share, though flexible lease arrangements are expanding fastest among SME and startup client types. Hybrid office property types command margin premiums where landlords bundle managed services with physical space.
Italy's CENED energy certification framework, the EU Taxonomy for sustainable activities, and local building codes enforced by municipal technical offices collectively mandate efficiency upgrades before lease renewal. These standards reshape demand by disqualifying Class E and F stock from institutional capital allocation. Stakeholders must monitor how Rome's pending seismic retrofit requirements interact with energy mandates to determine viable hold periods for aging inventory.
Market Dynamics
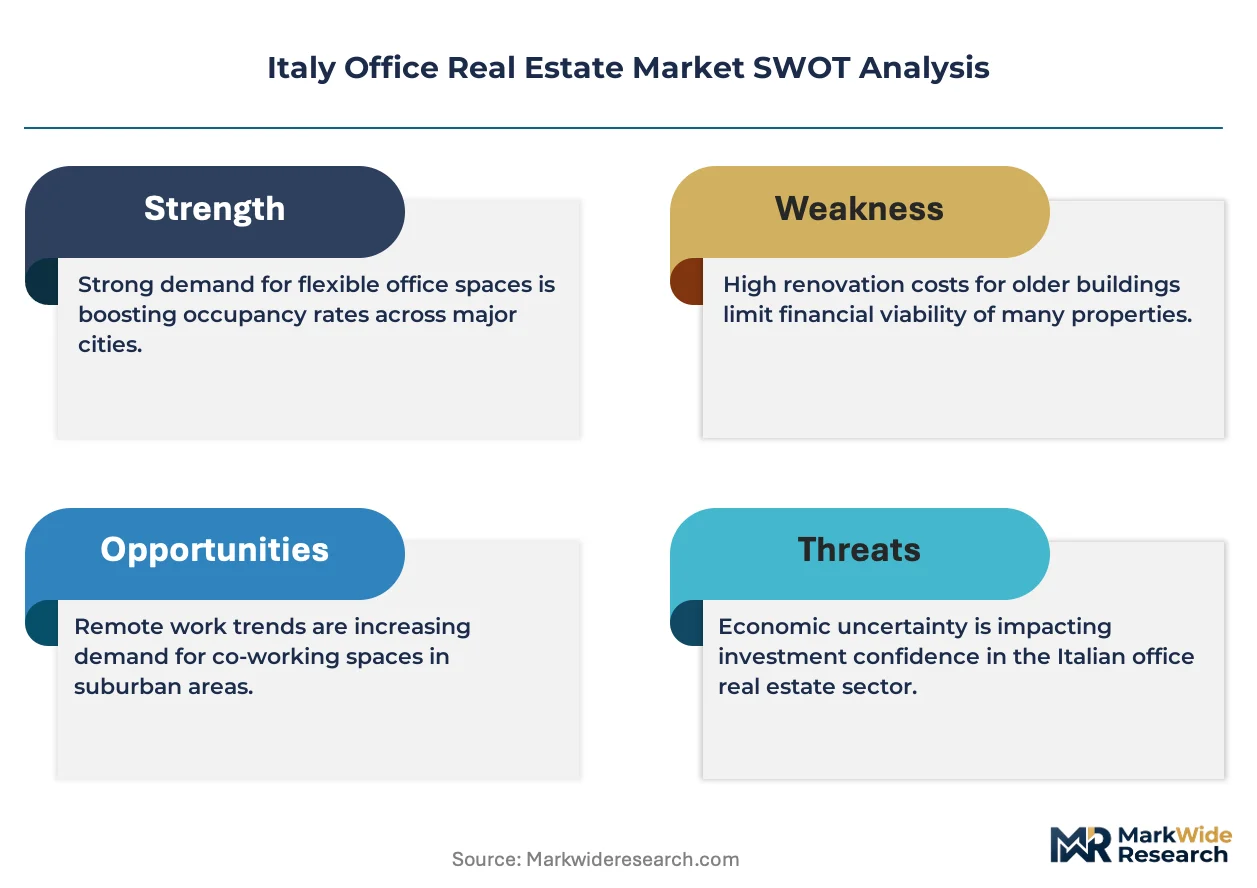
Italy's Superbonus 110% energy retrofit incentive is compressing capital cycles by forcing landlords to upgrade Class E and F stock before lease renewal or face institutional capital exclusion. This policy mechanism is bifurcating the market into premium certified assets and stranded secondary inventory.
Growth Catalysts
- Superbonus 110% framework:Italy's tax credit mechanism covers 110% of energy upgrade costs, accelerating Class A certification timelines for aging Milan and Rome office stock.
- Tech startup clustering:Flexible workspace demand from Italian fintech and SaaS ventures is expanding short-term lease volumes in Turin and Bologna innovation districts.
- CENED energy certification:Mandatory disclosure requirements under this national database are redirecting tenant preference toward verified low-carbon buildings.
Market Restraints
- Construction input volatility:Steel and HVAC equipment cost fluctuations are compressing developer margins on Milan retrofit projects.
- Seismic retrofit uncertainty:Pending Rome municipal requirements for earthquake-resistant upgrades create hold-period risk for 1970s inventory.
- Secondary stock obsolescence:Class E and F buildings face accelerating tenant exit as EU Taxonomy alignment becomes mandatory for institutional leases.
Strategic Opportunities
- Hybrid service bundling:Landlords combining physical space with managed IT and hospitality services capture margin premiums in Milan Porta Nuova.
- CityLife district expansion:Unbuilt parcels within this master-planned zone offer development rights for trophy assets with integrated sustainability systems.
- EU Taxonomy alignment services:Advisory capabilities verifying green asset classification are becoming essential for capital deployment decisions.
Industry Challenges
- Energy engineering talent scarcity:Specialized skills for integrated HVAC and building envelope retrofits command premium wages, constraining project velocity.
- Dual compliance timelines:Simultaneous CENED certification and seismic upgrade requirements create coordination complexity for Rome and Naples assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Office Real Estate Market |
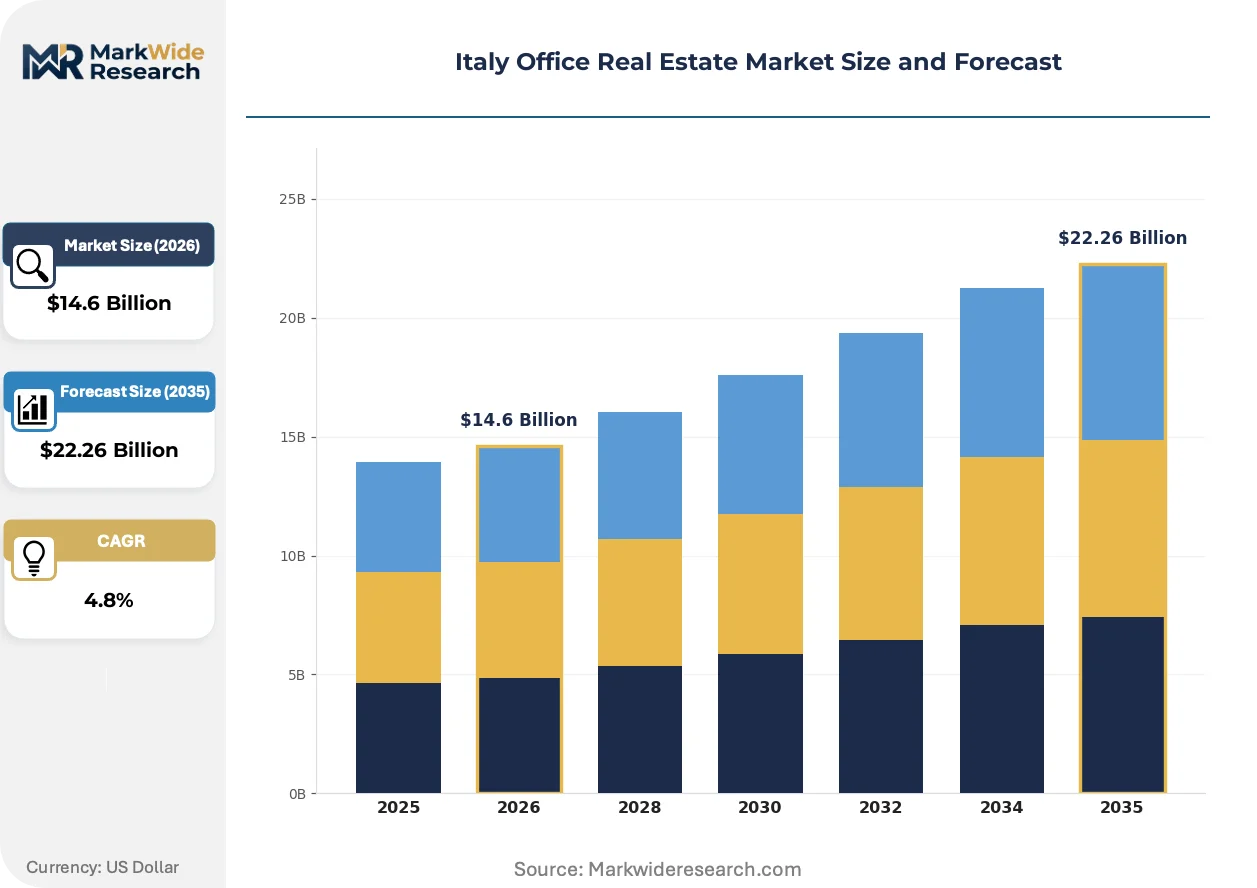
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $22.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Traditional Office, Coworking Space, Hybrid Office, Executive Suites Client Type: Corporates, SMEs, Startups, Freelancers Lease Structure: Long-Term Lease, Short-Term Lease, Flexible Lease, Month-to-Month Office Size: Small Offices, Medium Offices, Large Offices, Enterprise Solutions |
| Companies Covered | Savills, Knight Frank, CBRE, Gabetti Property Solutions, Coima Res, Jones Lang LaSalle IP, Colliers, Prelios SGR, Cushman & Wakefield, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Office Real Estate Market Shifts & Advancements
Smart building infrastructure is fragmenting traditional landlord-tenant relationships by embedding performance-based service level agreements into lease structures. This technological shift is compressing the distinction between physical space provision and operational management.
Sensor-integrated building management systems are fragmenting conventional facility management models. Milan's premium landlords are deploying IoT-enabled HVAC and lighting controls to offer real-time energy performance guarantees. This technology is fragmenting standard triple-net lease structures into dynamic service contracts where rent adjusts based on actual consumption metrics.
Italy's transposition of the EU Energy Performance of Buildings Directive is mandating zero-emission readiness for new construction and major renovations. The directive requires Milan and Rome developments to install solar-ready infrastructure and EV charging capacity. Class A office projects in Porta Nuova are responding by integrating photovoltaic facades and battery storage into base building specifications.
Tenant procurement patterns are favoring fitted space over shell-and-core deliveries. Italian professional services firms are negotiating turnkey packages including furniture, IT infrastructure, and flexible term structures. This preference shift is most visible in Turin's automotive corridor, where engineering consultancies are consolidating into managed flexible offices rather than traditional long-term leases.
Italy Office Real Estate Market Segmentation
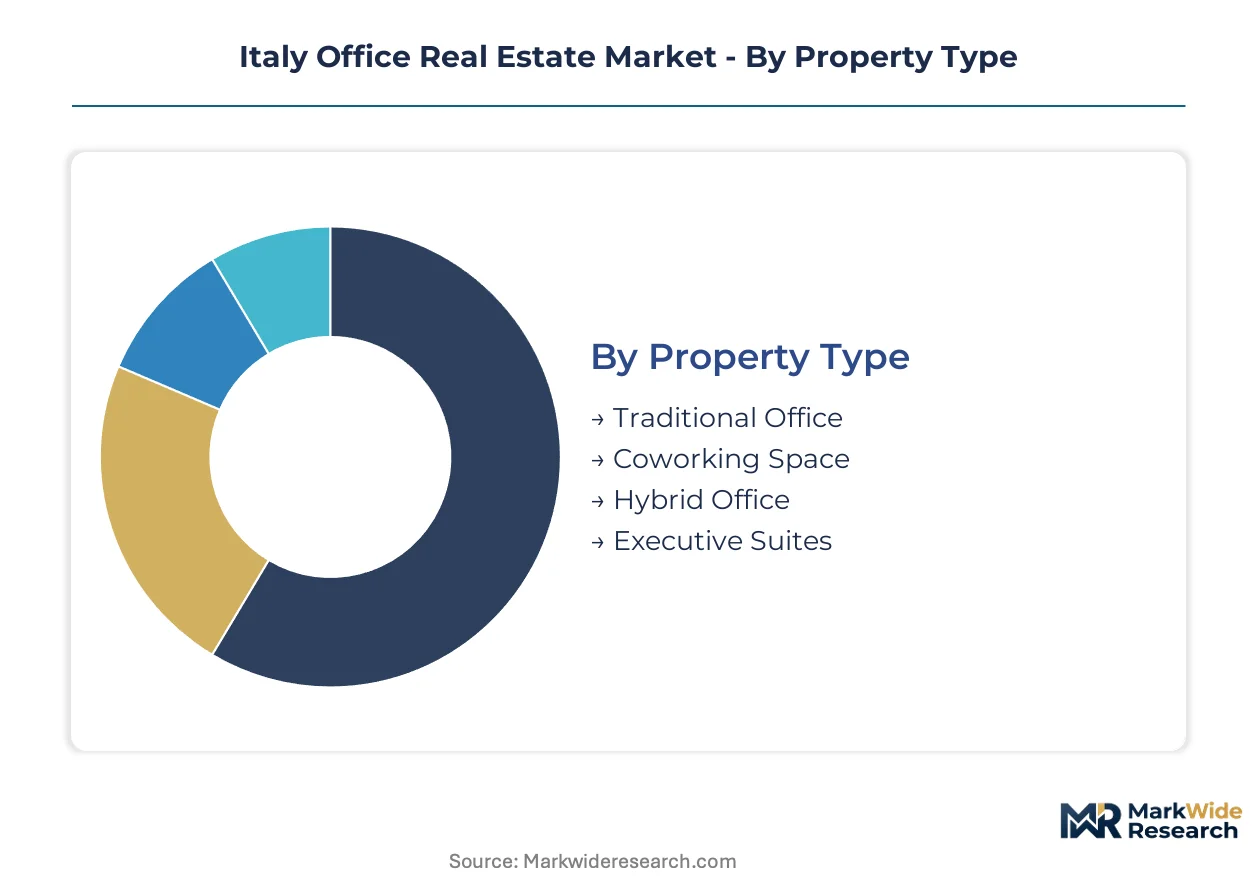
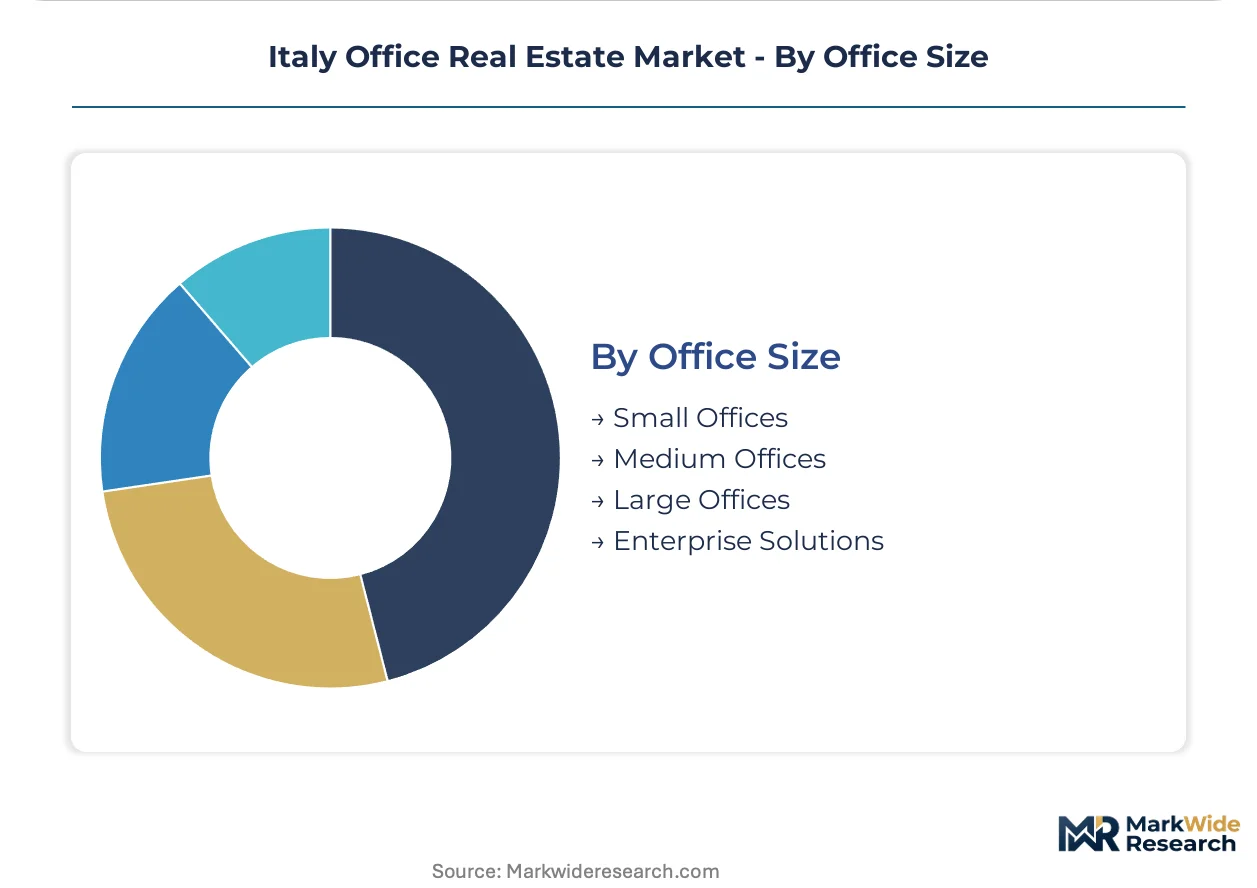
The Italy office real estate market fragments along operational and contractual dimensions that determine capital deployment strategies. CENED certification requirements and Superbonus 110% eligibility criteria create divergent investment profiles across each segment category.
Property Type:
Regulatory differentiation under Italy's energy retrofit framework creates distinct compliance obligations across building classifications.
- Traditional Office:Purpose-built administrative buildings with floor plates of 500–5,000 square meters and fixed infrastructure configurations. Milan's Porta Nuova district concentrates institutional demand for Class A certified traditional stock as pension funds exit secondary assets.
- Coworking Space:Multi-tenant environments with shared amenities and hot-desking arrangements operated by specialized providers. Turin and Bologna innovation districts are absorbing expanding volumes from fintech and SaaS ventures seeking short-term scalability.
- Hybrid Office:Buildings combining dedicated suites with on-demand workspace access and bundled hospitality services. Landlords in CityLife capture margin premiums by integrating managed IT and concierge functions.
- Executive Suites:Premium furnished environments targeting senior management and board functions with high service intensity. Rome's EUR district maintains stable occupancy among professional services firms requiring representative addresses.
Traditional office handles the majority of throughput; hybrid office is expanding most quickly on share.
Client Type:
Procurement scale and contract duration vary systematically across organizational maturity stages.
- Corporates:Established enterprises negotiating 5–10 year leases with full repair obligations and bespoke fit-out specifications. Financial services tenants in Milan dominate Class A absorption as EU Taxonomy alignment becomes mandatory.
- SMEs:Mid-sized enterprises seeking 3–5 year terms with partial service bundling and moderate customization rights. Engineering consultancies in Turin's automotive corridor favor turnkey packages over shell-and-core deliveries.
- Startups:Early-stage ventures requiring sub-12 month commitments with expansion options and minimal capital expenditure. Italian tech clusters in Bologna and Padua are driving flexible workspace adoption.
- Freelancers:Individual professionals purchasing hot-desk or private office memberships on rolling monthly contracts. Demand concentrates in central Milan and Rome locations with transit accessibility.
Corporates anchor institutional lease volumes; startups are gaining share fastest.
Lease Structure:
Contract flexibility determines revenue stability and tenant mix optimization for landlords.
- Long-Term Lease:Conventional 6+ year agreements with fixed escalations and tenant responsible for operating expenses. Institutional capital in Milan prioritizes these structures for yield security.
- Short-Term Lease:1–3 year commitments with limited renewal options and landlord-retained service control. SMEs in Rome and Turin utilize these for expansion phase uncertainty.
- Flexible Lease:Contracts incorporating expansion/contraction rights, service bundling, and performance-adjusted terms. CityLife landlords deploy these to capture tech sector demand.
- Month-to-Month:Minimal commitment arrangements with premium pricing and immediate termination clauses. Freelancers and project-based teams absorb this inventory in prime Milan submarkets.
Long-term lease underwrites the bulk of asset financing; flexible lease shows the steepest expansion trajectory.
Office Size:
Spatial configuration aligns with organizational headcount and collaboration requirements.
- Small Offices:Units under 200 square meters accommodating 5–15 employees with limited meeting infrastructure. Professional services partnerships in Rome favor these for cost control.
- Medium Offices:200–1,000 square meter suites supporting 15–75 staff with dedicated support zones. Regional headquarters in Turin and Florence concentrate in this bracket.
- Large Offices:1,000–5,000 square meter floors enabling 75–300 person operations with integrated amenities. Milan corporates absorb these for consolidated functions.
- Enterprise Solutions:Campus-style or multi-floor configurations exceeding 5,000 square meters with customized infrastructure. Trophy assets in Porta Nuova and CityLife target this segment.
Medium offices transact the highest deal frequency; enterprise solutions command the largest capital commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment-grade office stock concentrates in northern Italian metropolitan corridors where energy retrofit incentives intersect with established corporate demand. Milan anchors institutional capital deployment, while secondary cities capture spillover from constrained prime supply.
Lombardy
Milan's Porta Nuova and CityLife districts command sustained pension fund interest for Class A certified assets. The Superbonus 110% framework accelerates upgrade timelines for aging stock across the metropolitan area. Tech startup clustering in the innovation district drives flexible workspace absorption.
Piedmont
Turin's automotive corridor generates engineering consultancy demand for medium-format office suites with turnkey fit-outs. CENED certification requirements redirect tenant preference toward verified low-carbon buildings in the metropolitan core. The Lingotto and Aurora districts concentrate retrofit activity.
Lazio
Rome's EUR district maintains stable occupancy among professional services firms requiring representative addresses. Pending municipal seismic retrofit requirements create hold-period risk for 1970s inventory in the capital. The Tiburtina corridor attracts SME demand for short-term lease structures.
Emilia-Romagna
Bologna's innovation district absorbs expanding flexible workspace volumes from fintech and SaaS ventures. EU Taxonomy alignment mandates reshape institutional lease requirements across the metropolitan area. The Fiera district anchors hybrid office development.
Veneto
Padua's tech clusters drive startup demand for sub-12 month commitments with expansion options. Energy engineering talent scarcity constrains project velocity for integrated HVAC retrofits. The metropolitan area captures spillover demand from constrained Milan supply.
Italy Office Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Italy office real estate advisory landscape. Pan-European platforms with integrated data capabilities compete against domestic specialists with deep submarket knowledge. Two strategic archetypes dominate: scale-driven transaction advisors and retrofit-focused sustainability consultants. Competitive moves center on portfolio diversification into energy advisory services and geographic expansion into secondary city markets.
Within the scale-driven tier, CBRE and Jones Lang LaSalle IP occupy positions as pan-European transaction anchors for large-scale Milan deals. Savills exemplifies the specialization archetype through advisory capabilities on energy-efficient retrofits. Gabetti Property Solutions represents domestic mid-market distribution with concentrated knowledge of Rome and Turin submarkets.
| Leading Market Players |
|---|
| Savills |
| Knight Frank |
| CBRE |
| Gabetti Property Solutions |
| Coima Res |
| Jones Lang LaSalle IP |
| Colliers |
| Prelios SGR |
| Cushman & Wakefield |
| Others |
Supply & Pricing Matrix
Photovoltaic facade integration replacing conventional curtain wall systems is redrawing procurement geography toward Lombardy-based engineering clusters while compressing installed-cost premiums for Class A certification. This substitution dynamic concentrates supplier leverage with firms holding integrated building envelope capabilities and reshapes how landlords negotiate fixed-price retrofit contracts.
Pricing Analysis
Italy's Superbonus 110% framework dictates the pricing tier structure across the office real estate market. Three-tier pricing stratifies across premium Class A certified assets, standard Class B-C inventory, and economy-grade secondary stock facing obsolescence. Price differentiation hinges on CENED certification level and bundled service intensity, with hybrid office offerings in Milan Porta Nuova commanding sustained premiums. Cost compression in standard-tier retrofits is intensifying because steel and HVAC equipment input volatility erodes developer margins. SMEs and engineering consultancies exhibit highest price sensitivity, while institutional pension fund capital tolerates premium pricing for yield security.
Supply Chain Analysis
Specialized energy engineering talent scarcity in northern Italy constrains project velocity for integrated HVAC and building envelope retrofits. Supply concentration centers on Germany, China, and domestic Lombardy-based manufacturers for high-efficiency HVAC systems, smart building sensors, and photovoltaic components. Raw material dependencies span steel for structural reinforcement, copper for electrical infrastructure, and engineered glass for facade systems. Single-source vulnerability runs through German heat pump manufacturers serving Milan's premium retrofit pipeline. Distribution runs through pan-European facility management platforms and domestic mid-market brokers with deep submarket knowledge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across CENED certification tiers and seismic retrofit timelines fragments competitive space, creating service-layer niches where specialized advisors capture margin premiums from landlords navigating dual compliance requirements.
For Market Incumbents: Compound defensive positioning by acquiring energy engineering capabilities to capture Superbonus 110% advisory fees and securing exclusive distribution rights for Class A building technologies in Milan's constrained prime submarkets. Vertical integration into retrofit project management insulates margins from input cost volatility threatening developer returns. For New Entrants and Emerging Players: EU Taxonomy alignment advisory services represent an under-served layer where incumbents lack certified verification capabilities, creating entry space for sustainability-focused consultancies. Target Rome's seismic retrofit uncertainty as the most penetrable geography, where dual compliance complexity strands aging inventory and landlords demand specialized coordination services. Go-to-market positioning should emphasize integrated CENED-seismic retrofit project management. For Investors and Strategic Acquirers: The market sits at a policy-driven upgrade phase that favors trophy asset accumulation and energy advisory platform builds over speculative development. Long-term viability over the coming decade hinges on securing income streams from certified Class A stock with embedded service contracts. Acquisition target archetype: mid-market domestic brokers with concentrated Rome or Turin submarket knowledge and existing landlord relationships. The signal to watch is Superbonus 110% extension or modification timelines, which would abruptly reprice retrofit economics and stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Advisory Platform Buildout | Captures Superbonus 110% compliance fees from landlords facing CENED certification deadlines. |
| Class A Asset Accumulation | Positions portfolios for institutional capital allocation as EU Taxonomy alignment becomes mandatory. |
| Seismic Retrofit Capability Acquisition | Addresses Rome-specific compliance risk creating hold-period uncertainty for 1970s inventory. |
| Hybrid Service Bundling Expansion | Milan CityLife landlords deploy managed IT and concierge functions to capture tech sector premiums. |
| Secondary City Geographic Expansion | Turin and Bologna innovation districts absorb spillover demand from constrained Milan supply. |
Research Methodology
The analysis maps traditional office, coworking space, hybrid office, and executive suite sub-sectors, each validated through facility managers, landlord asset directors, tenant procurement leads, and energy retrofit engineers. Primary interviews with these stakeholders combined with secondary validation from CENED certification databases, municipal building permit records, and pan-European real estate investment flow reports. Bottom-up lease transaction analysis and top-down capital deployment tracking triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across property type, client organizational maturity, lease structure flexibility, and office spatial configuration. CAGRs derive from fitted trend analysis incorporating Superbonus 110% policy trajectory assumptions and EU Taxonomy implementation pacing. Industry-specific forecast inputs include energy certification upgrade timelines and seismic retrofit regulatory development.
Forecasts assume regulatory continuity in Italy's national energy retrofit framework and municipal building codes; material policy shifts would require re-modeling of capital cycle assumptions and stranded asset valuations. Practitioners should keep alternative scenarios live as Rome seismic requirements and Superbonus extension negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Office Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Flexible Office Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market