
 Automotive Pneumatic Seat System Market | 2026-2036
Automotive Pneumatic Seat System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pneumatic Seat System Market Analysis
The capital-intensity divergence between integrated seat system producers and component specialists is bifurcating competitive outcomes. Lear Corporation leverages captive air bladder manufacturing across North American assembly corridors. Adient plc anchors European premium programs through vertically controlled pneumatic module production.
Automotive pneumatic seat systems employ compressed air chambers, silicone elastomer bladders, and proportional valve manifolds to deliver programmable pressure profiling for occupant support and vibration isolation. Active suspension seats integrate accelerometer-fed electronic control loops that adjust inflation rates in real time to road surface inputs. Power seats command the dominant value share among product types due to bundled electronic architecture, while pneumatic technology leads the technology dimension as OEMs phase out pure mechanical adjusters. Luxury vehicles generate the fastest application growth because adaptive massage and posture-correction features have become standard equipment in flagship sedans.
NHTSA Federal Motor Vehicle Safety Standards, EU MDR-adjacent ergonomic frameworks, and China's GB/T automotive seat strength standards collectively elevate validation burdens for pneumatic subsystem suppliers. The EPA's embedded emissions tracking under IRA domestic content rules further complicates material sourcing for US-bound production. Stakeholders must monitor how regional certification divergence affects platform-common component strategies.
Market Dynamics
Electronically controlled pneumatic lumbar systems are bifurcating supplier capabilities as luxury OEMs demand integrated pressure profiling modules rather than discrete bladder components. This shift concentrates procurement leverage with vertically integrated seat manufacturers while fragmenting component specialists.
Growth Catalysts
- EU MDR-adjacent ergonomic frameworks:Posture-correction mandates for commercial vehicle operators are accelerating fitment of adaptive pneumatic supports in heavy-duty cab seating.
- Silicone elastomer bladder technology:Enhanced durability and temperature stability enable extended warranty coverage, reducing total cost of ownership for fleet operators.
- South Korean premium passenger car segment:Domestic OEMs are standardizing 16-way pneumatic adjustment as a competitive differentiator against German and Japanese flagships.
Market Restraints
- Proportional valve manifold cost structure:Precision machining requirements for miniature solenoid assemblies inflate subsystem pricing relative to electromechanical alternatives.
- Supply concentration in German pneumatic component manufacturing:Dependency on Mittelstand specialists for high-pressure sealing technology creates vulnerability to energy cost volatility.
- Technical limitation in accelerometer-fed control loop latency:Real-time vibration isolation performance gaps persist against hydraulic active suspension alternatives in severe duty cycles.
Strategic Opportunities
- Underpenetrated Chinese domestic brand segment:Mid-tier SUV producers lack pneumatic seat sourcing relationships, creating first-mover advantage for module suppliers establishing joint ventures.
- Technology convergence of pneumatic and thermal systems:Integrated climate-controlled bladders combining pressure profiling with heating/cooling functions command premium positioning.
- IRA domestic content rules:EPA embedded emissions tracking incentivizes North American bladder manufacturing investment for US-bound luxury electric vehicle programs.
Industry Challenges
- Embedded software validation timelines:NHTSA Federal Motor Vehicle Safety Standards for occupant restraint integration extend pneumatic control unit certification cycles.
- Cross-functional talent scarcity:Mechatronics engineers capable of bridging pneumatic hardware and electronic control loop development command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pneumatic Seat System Market |
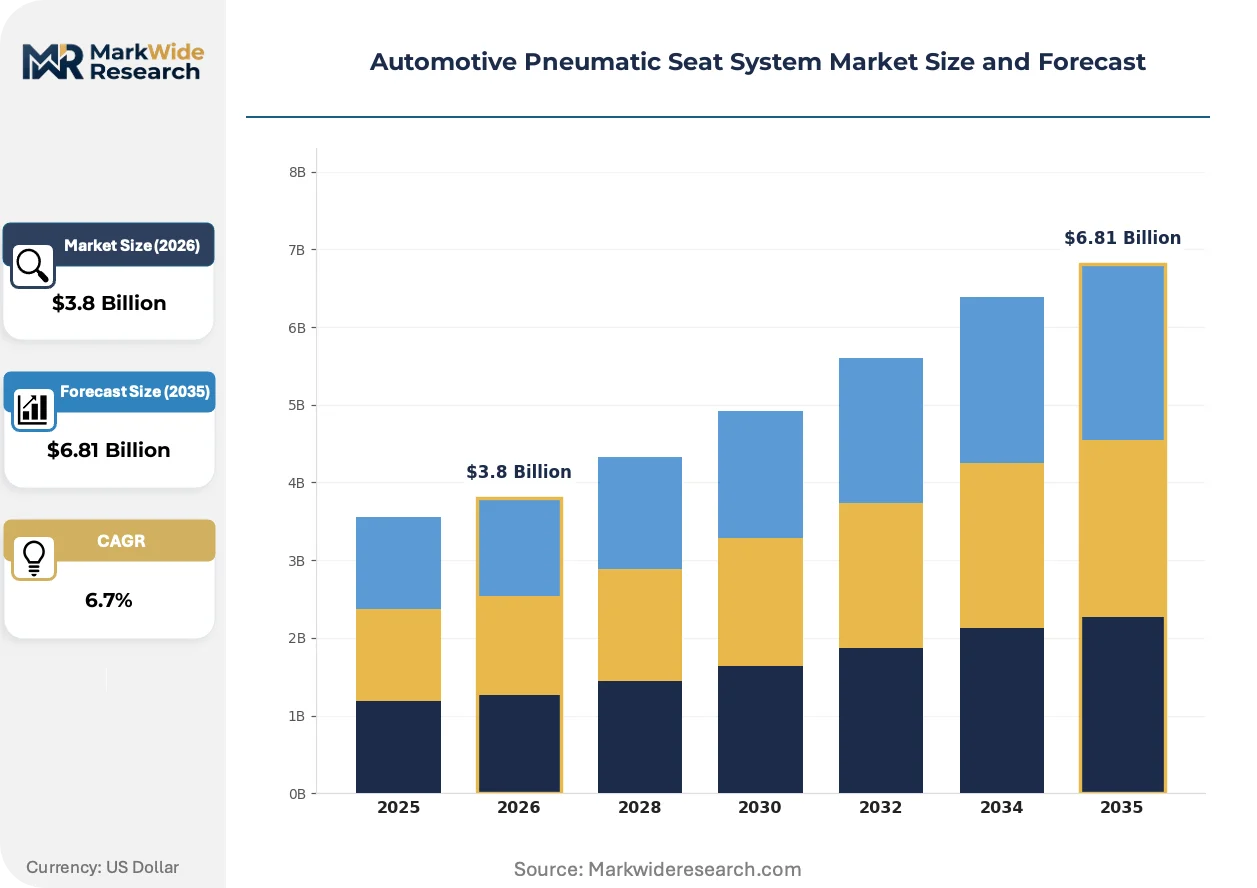
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Suspension Seats, Passive Seats, Manual Seats, Power Seats Technology: Pneumatic Technology, Hydraulic Technology, Electronic Control, Mechanical Control Application: Passenger Cars, Commercial Vehicles, Luxury Vehicles, Sports Cars End User: OEMs, Aftermarket Suppliers, Vehicle Manufacturers, Importers |
| Companies Covered | Adient plc, Toyota Boshoku Corporation, Lear Corporation, Gentherm, Brose Fahrzeugteile, Faurecia, Magna International, ZF Friedrichshafen AG, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pneumatic Seat System Market Emerging Trajectories
Active suspension seat architectures are compressing the boundary between chassis and cabin comfort systems. This convergence demands new supplier competencies in real-time sensor fusion and predictive pressure algorithms.
Multi-chamber silicone bladder arrays are decomposing the traditional single-zone pneumatic support model. Luxury OEMs in Germany and Japan are adopting 8 to 12 independent pressure zones for granular lumbar and thigh contouring. This granularity is decomposing standardized seat platform strategies into vehicle-specific pressure mapping configurations.
REACH substance restrictions on phthalate plasticizers are forcing reformulation of traditional bladder elastomers. European suppliers are accelerating bio-based silicone alternatives through ECHA pre-registration pathways. Premium seating programs face 18 to 24 month material qualification timelines, compressing model-year refresh cycles.
Fleet procurement of heavy-duty commercial vehicles is consolidating around total cost of ownership metrics rather than upfront equipment pricing. Long-haul operators in the United States are specifying pneumatic seat durability guarantees as contract terms. This behavioral shift elevates aftermarket service network coverage as a competitive determinant in specification decisions.
Automotive Pneumatic Seat System Market Segmentation
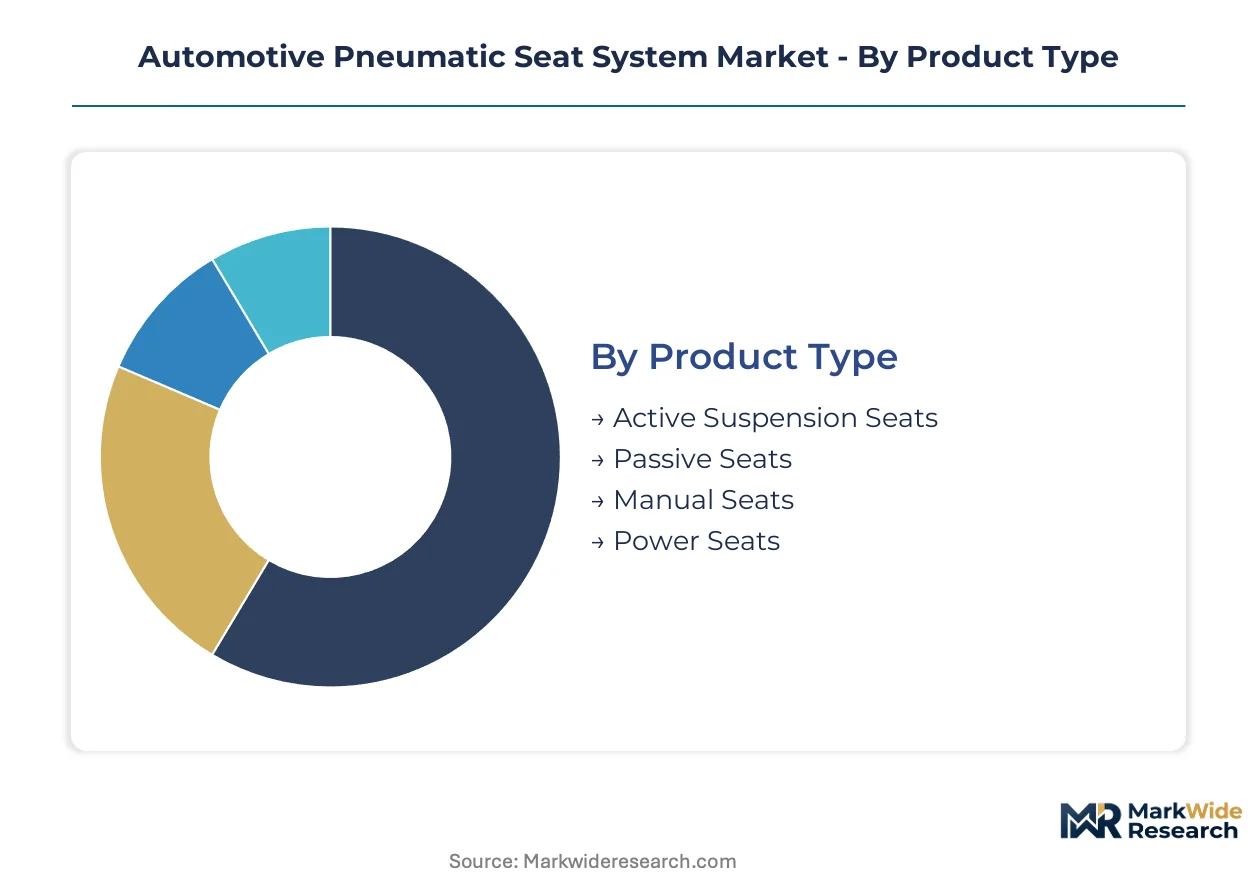
Pneumatic seat systems flow through divergent channel economics depending on integration depth. Product type and technology choices determine whether suppliers capture value through module sales to tier-one integrators or direct OEM relationships.
Product Type:
Channel economics bifurcate between integrated seat manufacturers and component specialists based on system complexity and electronic content.
- Power Seats:Bundled electronic architecture with pneumatic lumbar and multi-zone pressure profiling commands premium positioning in OEM direct supply. German and Japanese luxury marques concentrate procurement here for flagship sedan programs.
- Active Suspension Seats:Accelerometer-fed control loops with real-time inflation adjustment integrate chassis and cabin comfort functions. Demand clusters in heavy-duty commercial vehicle specifications across the United States where NHTSA vibration exposure limits apply.
- Passive Seats:Fixed-pressure pneumatic supports without electronic modulation serve cost-sensitive vehicle tiers through tier-one seat assembler channels.
- Manual Seats:Mechanical pump-actuated bladders with discrete adjustment zones flow primarily through aftermarket replacement channels.
By volume, Power Seats leads. By growth pace, Active Suspension Seats is gaining share fastest.
Technology:
Cost tier stratification separates premium electronic architectures from commodity mechanical alternatives.
- Pneumatic Technology:Compressed air chambers with silicone elastomer bladders and proportional valve manifolds enable programmable pressure profiling. South Korean OEMs are standardizing this across premium passenger car segments as competitive differentiation.
- Electronic Control:Sensor fusion architectures with predictive pressure algorithms concentrate in luxury vehicle applications where multi-zone lumbar and thigh contouring is standard equipment.
- Hydraulic Technology:Fluid-based actuation persists in severe-duty commercial applications where vibration isolation performance requirements exceed pneumatic latency limitations.
- Mechanical Control:Manual pump and valve systems serve economy vehicle tiers and aftermarket price-sensitive replacement demand.
By installed base, Pneumatic Technology dominates. By technology transition velocity, Electronic Control is climbing the fastest.
Application:
Customer type and margin structure vary sharply across vehicle category purchasing protocols.
- Luxury Vehicles:Adaptive massage and posture-correction features with 8 to 12 independent pressure zones are standard equipment. German OEMs drive specification intensity here.
- Passenger Cars:Mid-tier SUV and sedan producers in China lack established pneumatic seat sourcing, creating first-mover opportunity for module suppliers.
- Commercial Vehicles:Fleet procurement around total cost of ownership metrics elevates durability guarantees and aftermarket service coverage as contract determinants in US long-haul operator specifications.
- Sports Cars:Lightweight bladder materials with rapid pressure response characteristics serve performance-oriented seating positions.
By revenue concentration, Luxury Vehicles leads. By expansion opportunity, Passenger Cars shows the steepest trajectory.
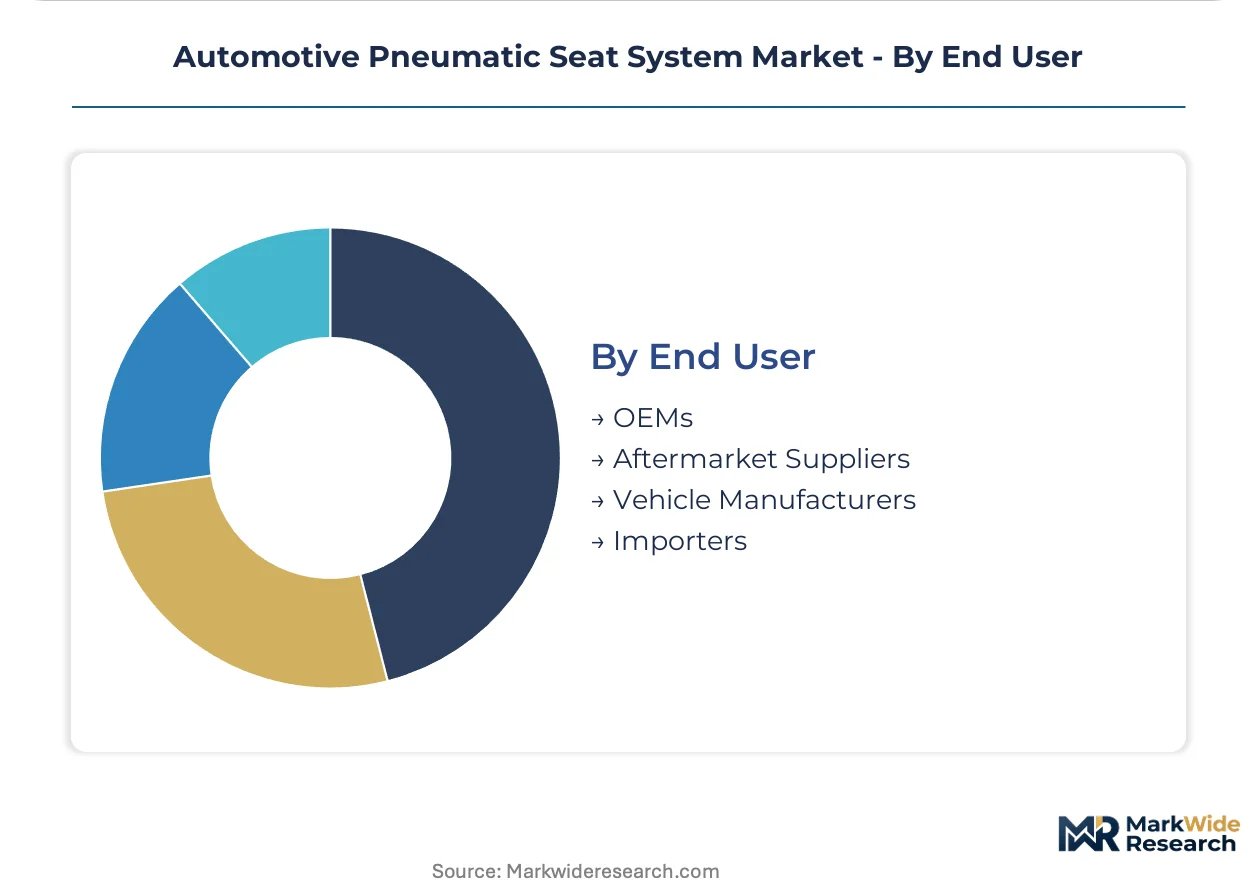
End User:
Supply concentration and procurement leverage distribute differently across direct and indirect channels.
- OEMs:Direct platform specification for luxury and premium vehicle programs with multi-year contract horizons and integrated electronic architecture requirements.
- Vehicle Manufacturers:Mid-tier producers sourcing complete seat systems from tier-one integrators rather than discrete pneumatic components.
- Aftermarket Suppliers:Independent service networks and fleet maintenance operations specifying replacement bladders and valve manifolds.
- Importers:Regional distributors serving secondary markets with localized inventory and technical support capabilities.
By contract value, OEMs leads. By channel expansion, Aftermarket Suppliers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in the United States prioritize durability guarantees over upfront cost, while Chinese domestic brands remain acutely price-sensitive. German luxury OEMs absorb premium pricing for multi-zone pneumatic architectures without volume elasticity.
United States
Long-haul commercial fleet operators specify pneumatic seats with extended warranty coverage as contract terms. NHTSA Federal Motor Vehicle Safety Standards govern occupant restraint integration for adaptive seating systems. Michigan-based seat assembly corridors concentrate production for Detroit Three premium truck and SUV programs.
Germany
Luxury marques mandate 8 to 12 independent pressure zones as standard equipment in flagship sedans. EU MDR-adjacent ergonomic frameworks impose posture-correction performance thresholds for commercial vehicle seating. Stuttgart and Munich industrial clusters host vertically integrated pneumatic module production for OEM direct supply.
China
Mid-tier SUV producers lack established pneumatic seat sourcing relationships, creating first-mover opportunity for module suppliers. GB/T automotive seat strength standards elevate validation burdens for pneumatic subsystem certification. Yangtze River Delta manufacturing bases are attracting joint venture investment for domestic bladder production.
Japan
Domestic OEMs are standardizing 16-way pneumatic adjustment as competitive differentiation against German flagships. METI industrial policy supports advanced seating technology development through targeted R&D incentives. Toyota City and Nagoya production corridors anchor regional supply chain concentration for premium passenger programs.
South Korea
Hyundai and Kia are bundling pneumatic lumbar and massage functions across mid-premium sedan tiers. MFDS-equivalent automotive component safety protocols align with international ergonomic certification standards. Gyeonggi-do assembly complexes source silicone bladder arrays from domestic specialty chemical producers.
Automotive Pneumatic Seat System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with seat system manufacturers controlling captive pneumatic module production while component suppliers fragment across bladder and valve niches. The competitive structure rewards backward integration into elastomer manufacturing and electronic control unit development. Three archetypes dominate: vertically integrated seat assemblers with in-house pneumatic capabilities, German Mittelstand specialists in high-pressure sealing technology, and Asian diversified component conglomerates. Capacity expansion in North American bladder manufacturing and technology licensing for multi-zone pressure algorithms represent the dominant competitive moves.
Among the integrated seat assemblers, Lear Corporation and Adient plc exemplify the vertically controlled production model, with Lear anchoring North American supply corridors and Adient occupying a position in European premium programs. Toyota Boshoku Corporation represents the Asian diversified archetype, sitting within a broader vehicle interior component portfolio that spans multiple seating technologies. These three companies illustrate how geographic production concentration and captive supply chain control differentiate competitive outcomes in pneumatic seat system procurement.
| Leading Market Players |
|---|
| Adient plc |
| Toyota Boshoku Corporation |
| Lear Corporation |
| Gentherm |
| Brose Fahrzeugteile |
| Faurecia |
| Magna International |
| ZF Friedrichshafen AG |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month material qualification timelines for silicone elastomer alternatives compress model-year refresh cycles and concentrate pricing power with European suppliers holding ECHA pre-registration pathways. This lead-time band ties supply chain rigidity directly to premium-tier margin capture, while cost-sensitive Chinese domestic brands face sourcing bottlenecks that inflate subsystem pricing relative to electromechanical alternatives.
Pricing Analysis
After-sales service revenue from extended warranty coverage and bladder replacement programs drives lifetime value for pneumatic seat system suppliers. Three-tier pricing structure across premium, standard, and economy levels separates flagship sedan multi-zone architectures from mid-tier SUV bundled offerings and aftermarket mechanical pump systems. Price differentiation hinges on certification grade for NHTSA occupant restraint integration and geographic delivery cost from German Mittelstand sealing specialists. Cost compression in mid-tier passenger car segments is intensifying because South Korean OEMs standardize 16-way pneumatic adjustment without commensurate volume scale. Fleet operators in US long-haul commercial vehicles exhibit lowest price sensitivity due to total cost of ownership procurement protocols, while Chinese domestic SUV producers remain acutely price-sensitive.
Supply Chain Analysis
Inventory concentration in German Mittelstand high-pressure sealing technology creates 18-to-24 month qualification exposure for REACH-compliant silicone alternatives. Geographic supply concentration centers on Germany for precision valve manifolds, China for Yangtze River Delta bladder manufacturing investment, and South Korea for domestic specialty chemical silicone arrays. Raw material dependencies rest on silicone elastomer feedstocks, miniature solenoid assemblies, and accelerometer sensor modules. Single-source vulnerability in German pneumatic component manufacturing exposes suppliers to energy cost volatility. Distribution runs through tier-one seat assembler channels for mid-tier vehicle programs and direct OEM relationships for luxury marques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive pneumatic seat system market represents an early-cycle expansion story as adaptive massage and posture-correction features penetrate from flagship sedans into mid-premium tiers. South Korean OEM standardization of 16-way pneumatic adjustment signals accelerating technology democratization.
For Market Incumbents: Fortify backward integration into silicone elastomer manufacturing to secure REACH-compliant material pathways and compress 18-to-24 month qualification timelines. Captive supply of proportional valve manifolds defends margin position against electromechanical substitute pricing pressure. Prioritize certification investment for NHTSA Federal Motor Vehicle Safety Standards occupant restraint integration to extend pneumatic control unit certification cycles as a competitive moat. For New Entrants and Emerging Players: Anchor in Chinese domestic brand mid-tier SUV segments where established pneumatic seat sourcing relationships remain absent. Joint venture structures with Yangtze River Delta manufacturing bases unlock first-mover positioning before German and Japanese tier-one integrators consolidate procurement. Technology licensing for multi-zone pressure algorithms offers a capital-light go-to-market angle against vertically integrated incumbent R&D scale. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic control unit development as multi-chamber silicone bladder arrays decompose standardized seat platform strategies. Long-term viability over a 5-to-10 year window favors suppliers with proven software validation timelines and aftermarket service network coverage. Acquisition target archetype: German Mittelstand specialists in high-pressure sealing technology with ECHA pre-registration assets. Signal to watch: IRA domestic content rules triggering North American bladder manufacturing investment announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Elastomer Manufacturing | REACH pre-registration pathways compress material qualification timelines for European premium programs. |
| Multi-Zone Pressure Algorithm Licensing | Predictive pressure software enables 8-to-12 independent zone configurations for German luxury marques. |
| North American Bladder Manufacturing Investment | IRA domestic content rules incentivize captive production for US-bound luxury electric vehicle programs. |
| Aftermarket Service Network Expansion | Extended warranty coverage elevates fleet procurement decisions for US long-haul commercial operators. |
| Joint Venture Formation in China | Yangtze River Delta manufacturing bases attract module suppliers targeting underpenetrated domestic SUV tiers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tier-one seat assembler procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance operators; and secondary validation through vehicle production databases, IHS Markit registration data, NHTSA Federal Motor Vehicle Safety Standards filings, and ECHA REACH substance restriction updates. Bottom-up triangulation across pneumatic subsystem bill-of-materials costing converged with top-down market sizing from luxury vehicle content-per-vehicle assumptions.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from installed base penetration curves for pneumatic versus mechanical adjustment technologies, cross-referenced with South Korean and German OEM specification timelines. Forecast inputs incorporated REACH substance restriction phase-out schedules and IRA domestic content compliance thresholds.
Material uncertainties — REACH reformulation delays, German energy cost volatility, and accelerometer-fed control loop latency gaps against hydraulic alternatives — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market