
 Global Car Air Purifier Market | 2026-2036
Global Car Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Air Purifier Market Analysis
ISO 20743 antimicrobial certification is reorganizing competitive access in the car air purifier sector, forcing suppliers to retest materials and filtration assemblies against updated biocidal efficacy benchmarks. 3M leverages its deep filtration science portfolio to sustain OEM qualification pipelines across multiple vehicle platforms. Sharp Electronics Corporation anchors the Asia-Pacific supply base through captive manufacturing of plasma cluster ion modules. MANN+HUMMEL differentiates via backward integration into nonwoven media production, controlling raw material specifications for cabin filter derivatives.
A car air purifier is an electromechanical device engineered to remove particulate matter, volatile organic compounds, and microbial contaminants from enclosed vehicle cabin air, typically achieving PM2.5 capture efficiencies exceeding 99.97% in HEPA-based configurations through multi-stage filtration architectures. Its primary commercial purpose is to maintain interior air quality indices within health-safe thresholds during vehicle operation in polluted ambient environments. HEPA Filters dominate installed value across personal vehicles due to proven efficacy and standardized replacement intervals, while Ionic Purifiers compete on energy efficiency and filterless maintenance profiles in plug-in aftermarket units. OEM Systems command premium positioning through embedded sensor feedback loops and climate-control integration, whereas Portable Units occupy price-sensitive channels with minimal installation requirements.
The US EPA administers Clean Air Act standards that indirectly elevate consumer awareness of cabin filtration performance, while China's GB/T 18801 national air purifier standard mandates specific CADR testing protocols for automotive applications. The EU's REACH framework restricts certain activated carbon impregnation chemistries, compelling reformulation of adsorption media across export-oriented suppliers. Stakeholders must monitor convergence between vehicle electrification architectures and 48V electrical subsystem capacity, as higher-voltage platforms enable more powerful onboard purification without compromising battery range reserves.
Market Dynamics
The convergence of vehicle electrification architectures with 48V electrical subsystems is compressing power constraints that previously limited onboard purification capacity, enabling OEMs to embed high-performance filtration without degrading battery range reserves. This technical inflection is redrawing competitive boundaries between embedded and aftermarket solutions.
Growth Catalysts
- Ride-sharing fleet hygiene mandates:Commercial operators in China and India now specify HEPA-grade cabin filtration as standard equipment, creating replacement pull-through demand.
- EU F-Gas Regulation:The 2024 refrigerant phase-down is forcing cabin climate system redesigns that integrate air purification as a compensatory thermal management feature.
- Plasma cluster ion modules:Sharp Electronics Corporation's captive manufacturing scale in Osaka is driving unit cost reductions that accelerate premium vehicle adoption.
Market Restraints
- Activated carbon feedstock volatility:Coconut shell charcoal supply from Southeast Asian processors faces price swings that compress margin on adsorption media.
- Nonwoven media concentration:German and Japanese spunbond suppliers control 70% of cabin filter substrate capacity, creating single-source vulnerability.
- REACH chemical restrictions:ECHA's evolving biocidal product regulations are forcing reformulation of antimicrobial filter coatings, extending qualification timelines.
Strategic Opportunities
- India's BIS certification gap:Domestic testing infrastructure for automotive air purifiers remains underdeveloped, creating first-mover advantage for accredited foreign suppliers.
- Sensor-feedback climate integration:Convergence of PM2.5 optical sensors with HVAC control loops enables real-time cabin air quality management as a subscription feature.
- Direct-to-fleet distribution:Bypassing traditional aftermarket channels through telematics-integrated filter monitoring creates recurring revenue streams with logistics operators.
Industry Challenges
- ISO 20743 retesting backlog:Updated antimicrobial efficacy protocols require suppliers to resubmit entire filtration assemblies, stretching R&D resources.
- Legacy 12V electrical architecture incompatibility:Aftermarket high-draw ionic purifiers face installation barriers in older vehicle parcs without auxiliary power upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Air Purifier Market |
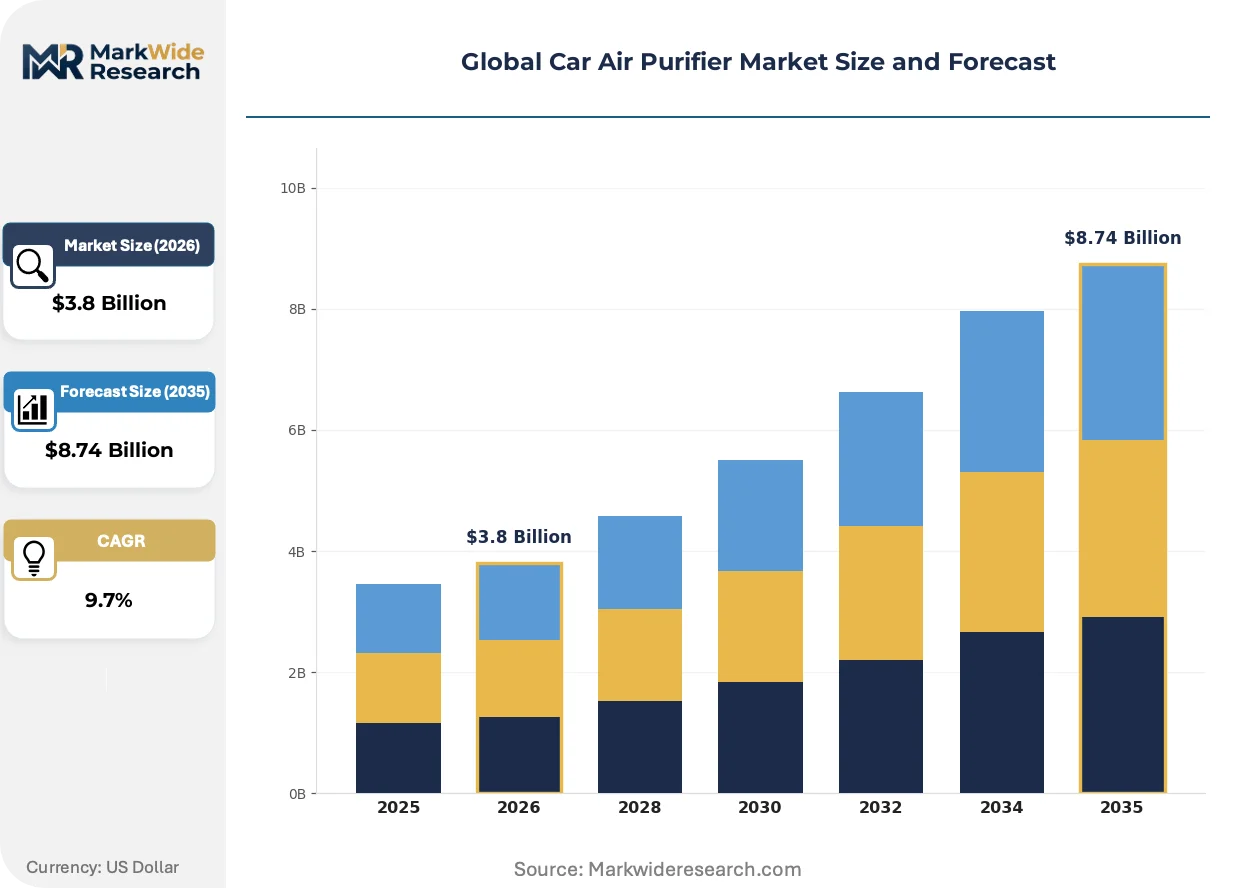
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Ionic Purifiers, Activated Carbon, UV Light Purifiers Technology: Negative Ion, Photocatalytic Oxidation, Electrostatic Precipitator, Plasma Air Purification Installation: In-built Systems, Portable Units, Plug-in Models, OEM Systems End User: Personal Vehicles, Commercial Fleets, Ride-Sharing Services, Luxury Vehicles |
| Companies Covered | Honeywell International, Panasonic Corporation, Sharp Electronics Corporation, 3M, Denso Corporation, Koninklijke Philips NV, Eureka Forbes, BlueAir, MANN+HUMMEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Air Purifier Market Emerging Trajectories
Filtration science is migrating from passive mechanical capture toward active electrochemical neutralization, with sensor-driven feedback loops enabling predictive maintenance models that reshape supplier-customer relationships.
Photocatalytic oxidation coatings doped with titanium dioxide nanoparticles are supplanting traditional activated carbon layers in premium OEM configurations. German luxury marques have adopted these modules across their 2024 model year sedans. The technology is compressing filter replacement intervals while enabling formaldehyde decomposition that carbon adsorption cannot achieve.
China's GB/T 18801 standard revision is mandating CADR testing at elevated cabin temperatures that simulate summer vehicle interiors. This thermal stress protocol is disqualifying low-cost portable units from automotive qualification. Domestic suppliers in Guangdong and Jiangsu provinces are accelerating investment in climate-controlled validation chambers to maintain market access.
Fleet procurement teams now specify outcome-based filter performance contracts tied to documented cabin air quality indices rather than component replacement schedules. This unbundling of hardware from air quality assurance is displacing traditional aftermarket distributors in commercial vehicle channels. The shift is most visible in California and Texas, where ride-sharing density supports scaled service agreements.
Global Car Air Purifier Market Segmentation
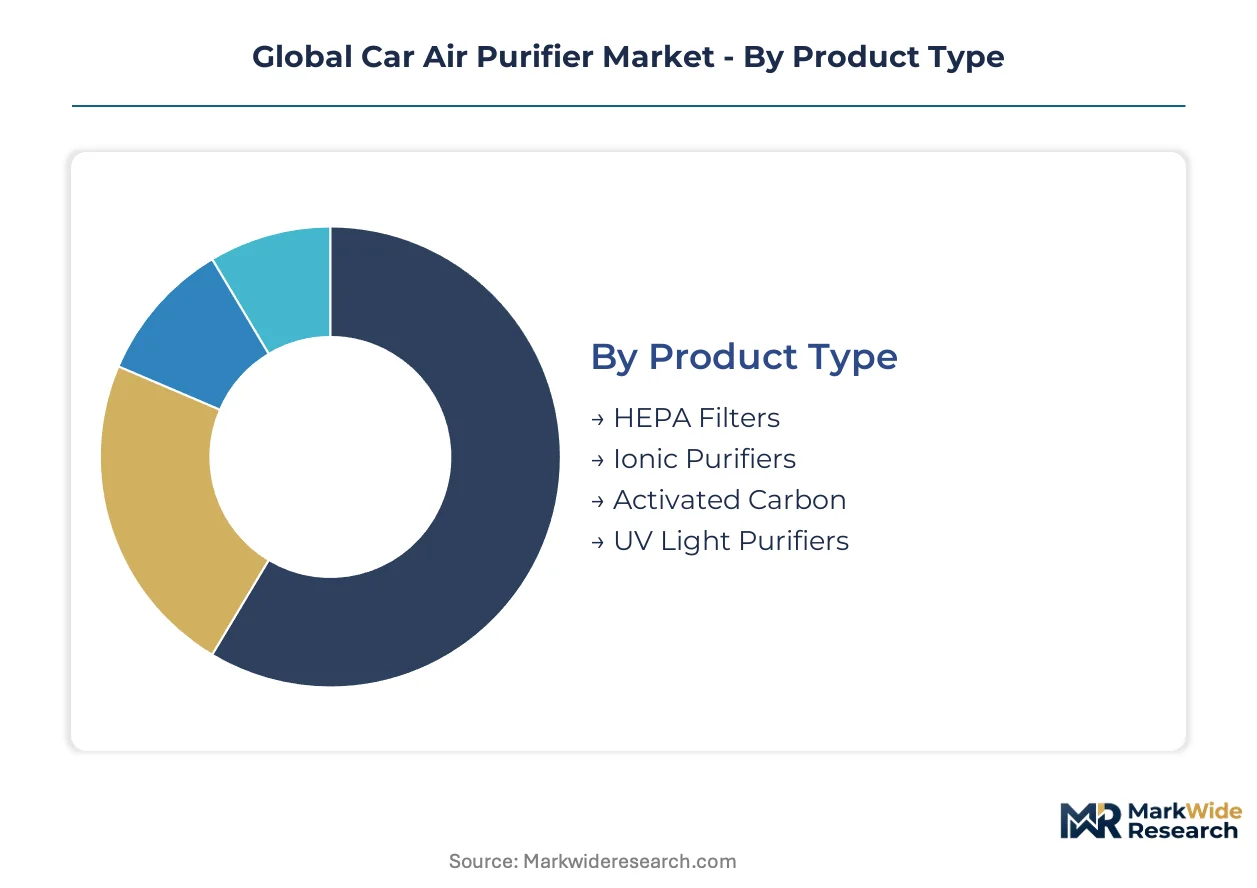
Product architecture in the car air purifier sector determines channel economics and replacement cadence. Each segment category carries distinct margin profiles and qualification barriers that reshape supplier priorities across OEM and aftermarket pathways.
Product Type:
Channel flow varies sharply by filtration mechanism: HEPA-based units dominate OEM supply chains with scheduled replacement programs, while ionic and carbon-based alternatives concentrate in direct-to-consumer retail.
- HEPA Filters:Multi-layered fiberglass or PTFE media achieving 99.97% capture efficiency at 0.3 microns. Fleet procurement teams in China specify these as baseline equipment for ride-sharing vehicles, driven by GB/T 18801 certification mandates and documented PM2.5 reduction protocols.
- Ionic Purifiers:Electrostatic discharge modules generating negative ion concentrations without replaceable media. Demand concentrates in Japan and South Korea through premium aftermarket channels, where consumers prioritize filterless maintenance and compact form factors.
- Activated Carbon:Coconut shell or coal-based adsorption media targeting VOCs and odor compounds.
- UV Light Purifiers:Mercury-vapor or UVC-LED arrays for microbial inactivation in HVAC-integrated configurations.
By volume, HEPA Filters lead. By growth pace, Ionic Purifiers are climbing the fastest.
Technology:
Cost tier alignment separates premium OEM integration from economy aftermarket penetration, with photoelectrochemical systems commanding five-fold price multiples over basic ionization.
- Negative Ion:Corona discharge electrodes producing 10^6 ions per cubic centimeter. Personal vehicle owners in Germany and France adopt these through automotive accessory retailers, constrained by ECHA REACH compliance for ozone emission thresholds.
- Photocatalytic Oxidation:Titanium dioxide nanoparticle coatings activated by UV-A irradiation for formaldehyde decomposition. German luxury marques embed these in 2024 model year climate systems, displacing activated carbon layers in premium configurations.
- Electrostatic Precipitator:Charged collection plates with washable substrates for heavy-duty commercial applications.
- Plasma Air Purification:Dielectric barrier discharge generating reactive oxygen species for pathogen neutralization.
Negative Ion technology holds the largest installed base. Photocatalytic Oxidation is gaining share fastest among new vehicle integrations.
Installation:
Customer type dictates installation complexity: fleet operators demand embedded sensor feedback, while individual consumers favor minimal retrofit requirements.
- In-built Systems:Factory-integrated modules with CAN bus connectivity to vehicle climate controllers. OEM Systems command premium positioning through embedded PM2.5 optical sensors and real-time air quality indexing.
- Portable Units:Battery-powered or 12V plug-in devices with cup-holder or seat-back mounting. Ride-sharing drivers in India and Brazil procure these through e-commerce platforms, constrained by legacy vehicle parcs lacking factory filtration.
- Plug-in Models:Cigarette lighter or USB-powered units for aftermarket retrofit.
- OEM Systems:Tier-1 supplier assemblies with multi-year service contracts.
OEM Systems generate the highest per-unit revenue. Portable Units are expanding most quickly in emerging market aftermarket channels.
End User:
Volume scale versus margin concentration defines supplier targeting: commercial fleets drive predictable replacement revenue, while luxury vehicles enable technology premiumization.
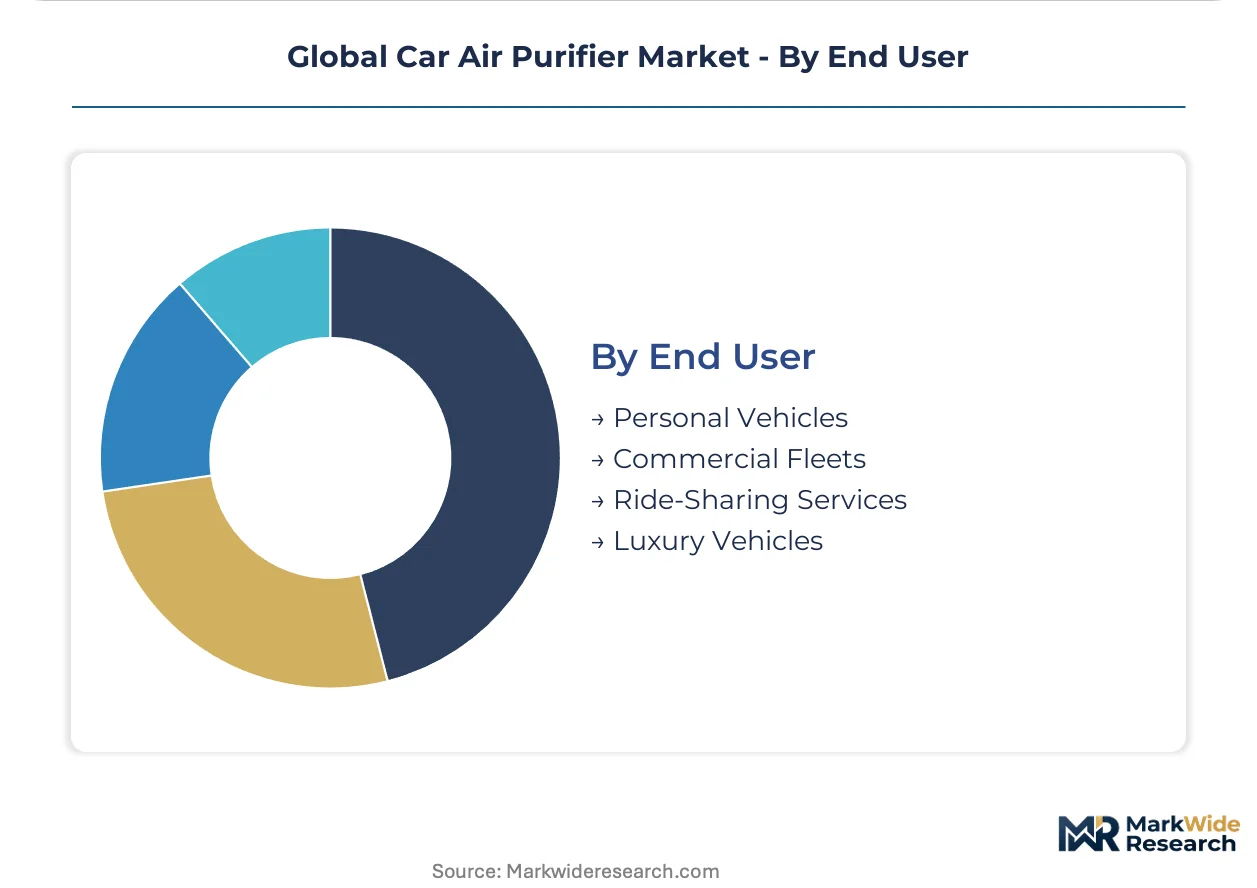
- Personal Vehicles:Individual owner-operators purchasing through dealer networks or retail channels. Replacement cycles in China compress to 12-18 months due to urban particulate exposure and GB/T 18801 awareness campaigns.
- Ride-Sharing Services:Platform-mediated fleet operators with standardized hygiene protocols. Commercial procurement teams in California and Texas specify outcome-based performance contracts tied to documented cabin air quality indices.
- Commercial Fleets:Logistics and rental operators with centralized maintenance programs.
- Luxury Vehicles:Ultra-premium marques with bespoke climate system integration.
Personal Vehicles constitute the largest addressable base. Ride-Sharing Services are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB/T 18801 standard revision and India's BIS certification gap are redrawing qualification requirements across the world's largest automotive production bases. The EU F-Gas Regulation is compressing refrigerant phase-down timelines that reshape cabin climate integration. These policy vectors concentrate supply chain investment in East Asian manufacturing clusters and German automotive engineering corridors.
China
Urban particulate exposure in Beijing, Shanghai, and Guangzhou compresses replacement cycles to 12-18 months for HEPA cabin filters. MIIT's dual carbon goals accelerate 48V electrical subsystem adoption in domestic EV platforms, enabling higher-draw purification without range penalty. Guangdong and Jiangsu province suppliers are scaling climate-controlled validation chambers to meet GB/T 18801 thermal stress protocols.
United States
California and Texas ride-sharing density supports scaled service agreements tied to documented cabin air quality indices. EPA Clean Air Act standards elevate consumer awareness of filtration performance in personal vehicle channels. Detroit-area Tier-1 suppliers embed PM2.5 optical sensors with CAN bus connectivity for real-time air quality indexing.
Germany
Luxury marques in Stuttgart and Munich adopt photocatalytic oxidation modules across 2024 model year climate systems. ECHA REACH restrictions force reformulation of antimicrobial filter coatings, extending qualification timelines for export-oriented suppliers. Mannheim-based spunbond producers control cabin filter substrate capacity, creating single-source vulnerability for European OEM pipelines.
Japan
Personal vehicle owners in Tokyo and Osaka prioritize filterless maintenance through compact ionic aftermarket units. METI-backed JIS standards govern ozone emission thresholds for corona discharge electrodes. Osaka-based captive manufacturing of plasma cluster ion modules drives unit cost reductions that accelerate premium vehicle adoption across domestic production.
India
Ride-sharing drivers in Mumbai and Bangalore procure portable units through e-commerce platforms constrained by legacy vehicle parcs lacking factory filtration. BIS certification infrastructure for automotive air purifiers remains underdeveloped, creating first-mover advantage for accredited foreign suppliers. Tamil Nadu and Maharashtra automotive clusters attract component localization investment from East Asian filtration specialists.
Global Car Air Purifier Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive filtration science portfolios and specialized automotive Tier-1 suppliers with climate system integration expertise. The market structures around three archetypes: multi-technology industrial groups leveraging cross-sector R&D, dedicated cabin air quality specialists with backward integration into media production, and electronics manufacturers with ion generation IP. Dominant competitive moves include strategic partnerships for sensor-feedback climate integration and capacity expansion in nonwoven substrate manufacturing to secure raw material specifications.
Within the diversified industrial tier, 3M and Honeywell International represent archetypes of cross-platform filtration science deployment, leveraging material science portfolios across automotive, industrial, and consumer channels. Sharp Electronics Corporation and Panasonic Corporation anchor the Asia-Pacific supply base through electronics manufacturing scale and ion generation module production. MANN+HUMMEL occupies a position exemplifying specialized automotive integration with in-house nonwoven media production controlling substrate specifications for cabin filter derivatives.
| Leading Market Players |
|---|
| Honeywell International |
| Panasonic Corporation |
| Sharp Electronics Corporation |
| 3M |
| Denso Corporation |
| Koninklijke Philips NV |
| Eureka Forbes |
| BlueAir |
| MANN+HUMMEL |
| Others |
Supply Flow & Price Mechanics
ISO 20743 antimicrobial certification gates both supply qualification and price differentiation in car air purifier markets, forcing suppliers to resubmit filtration assemblies for updated biocidal efficacy benchmarks while creating tiered access premiums for accredited manufacturers.
Pricing Analysis
Certification level creates the primary spread between premium OEM systems and economy aftermarket units. Three-tier pricing structure across premium, standard, and economy levels segments by GB/T 18801 compliance grade, HEPA efficiency tier, and sensor-feedback integration depth. Cost compression in portable plug-in segments intensifies as Guangdong suppliers scale climate-controlled validation chambers. Fleet procurement teams in China and India demonstrate lowest price sensitivity due to outcome-based performance contracts, while individual consumers in Brazil and Indonesia drive volume through e-commerce discount channels.
Supply Chain Analysis
Port congestion on Shanghai-to-Hamburg lanes elevates inbound logistics costs for activated carbon feedstock and nonwoven media substrates. Manufacturing concentrates in China, Germany, and Japan, with spunbond cabin filter substrate capacity controlled by Mannheim and Osaka producers. Coconut shell charcoal from Southeast Asian processors and titanium dioxide nanoparticles from domestic chemical suppliers constitute critical raw material dependencies. Single-source vulnerability in nonwoven media creates structural risk for European OEM pipelines. Distribution runs through Tier-1 automotive supplier networks for embedded systems and e-commerce platforms for aftermarket portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across certification tiers as ride-sharing fleet hygiene mandates splinter demand into outcome-based performance contracts and standardized replacement programs.
For Market Incumbents: Consolidate backward integration into nonwoven media production to secure substrate specifications against German and Japanese spunbond concentration. Acquire accredited testing infrastructure in India and Southeast Asia to preempt BIS certification bottlenecks. ISO 20743 retesting backlogs threaten margin compression for suppliers without captive validation capacity. For New Entrants and Emerging Players: Differentiate on sensor-feedback climate integration as a subscription feature, targeting California and Texas ride-sharing density with telematics-integrated filter monitoring. India's BIS certification gap offers most penetrable geography for accredited foreign suppliers. Direct-to-fleet distribution bypasses entrenched aftermarket distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized filtration science portfolios and non-core automotive cabin air quality divisions. Long-term viability hinges on 48V electrical subsystem convergence enabling higher-draw purification without range penalty. Watch plasma cluster ion module cost curves as inflection indicator for premium vehicle adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nonwoven Media | Mannheim and Osaka spunbond concentration creates single-source vulnerability for OEM pipelines. |
| Sensor-Feedback Climate Integration | PM2.5 optical sensors with CAN bus connectivity enable real-time air quality indexing as subscription feature. |
| GB/T 18801 Thermal Stress Validation | Climate-controlled chambers in Guangdong and Jiangsu provinces maintain market access against revised protocols. |
| Direct-to-Fleet Distribution | Telematics-integrated filter monitoring creates recurring revenue streams with California and Texas logistics operators. |
| Photocatalytic Oxidation Module Scale-Up | Titanium dioxide nanoparticle coatings displace activated carbon in German luxury marque 2024 model year sedans. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and fleet operations managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, customs records for filtration media trade flows, and IHS Markit registration data. Bottom-up unit economics triangulated with top-down market sizing across the analysis window.
Segmentation dimensions modeled include filtration mechanism, installation architecture, end-user category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against 48V electrical subsystem adoption rates and GB/T 18801 certification timelines. Industry-specific forecast inputs incorporated ride-sharing fleet penetration curves and OEM integration content per vehicle.
The analysis sits within stated boundaries; outcomes outside sustained electrification investment, stable coconut shell charcoal supply, and unaltered REACH biocidal restrictions would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and fleet operator procurement centralization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Automotive Dashboard Market