
 Automotive Passive Safety System Market | 2026-2036
Automotive Passive Safety System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Passive Safety System Market Analysis
Asset-light manufacturing partnerships and contract assembly models are tilting capital requirements downward, enabling tier-two suppliers to challenge incumbents. Autoliv Inc. leverages its vertical integration in inflator production to sustain margin control across North American and European supply chains. ZF Friedrichshafen AG anchors its position through proprietary sensor-restraint integration, while Hyundai Mobis Co. Ltd. competes aggressively on Korean OEM captive demand and expanding Chinese joint ventures.
Automotive passive safety systems encompass engineered restraint and structural energy-absorption components—airbags with multi-stage pyrotechnic deployment, pretensioning seatbelts with force limiters, and crumple zones designed around specific deformation kinematics—whose primary purpose is to reduce occupant injury severity during collisions without requiring active driver intervention. Airbags and seatbelts occupy the mature volume core where OEM price-down pressure compresses margins, while sensor technology and active smart restraints capture expanding value pools as semi-autonomous architectures demand predictive deployment algorithms. Composite materials in deployable structures represent the fastest-growing technology segment, driven by weight-reduction mandates that intersect with crash-performance targets.
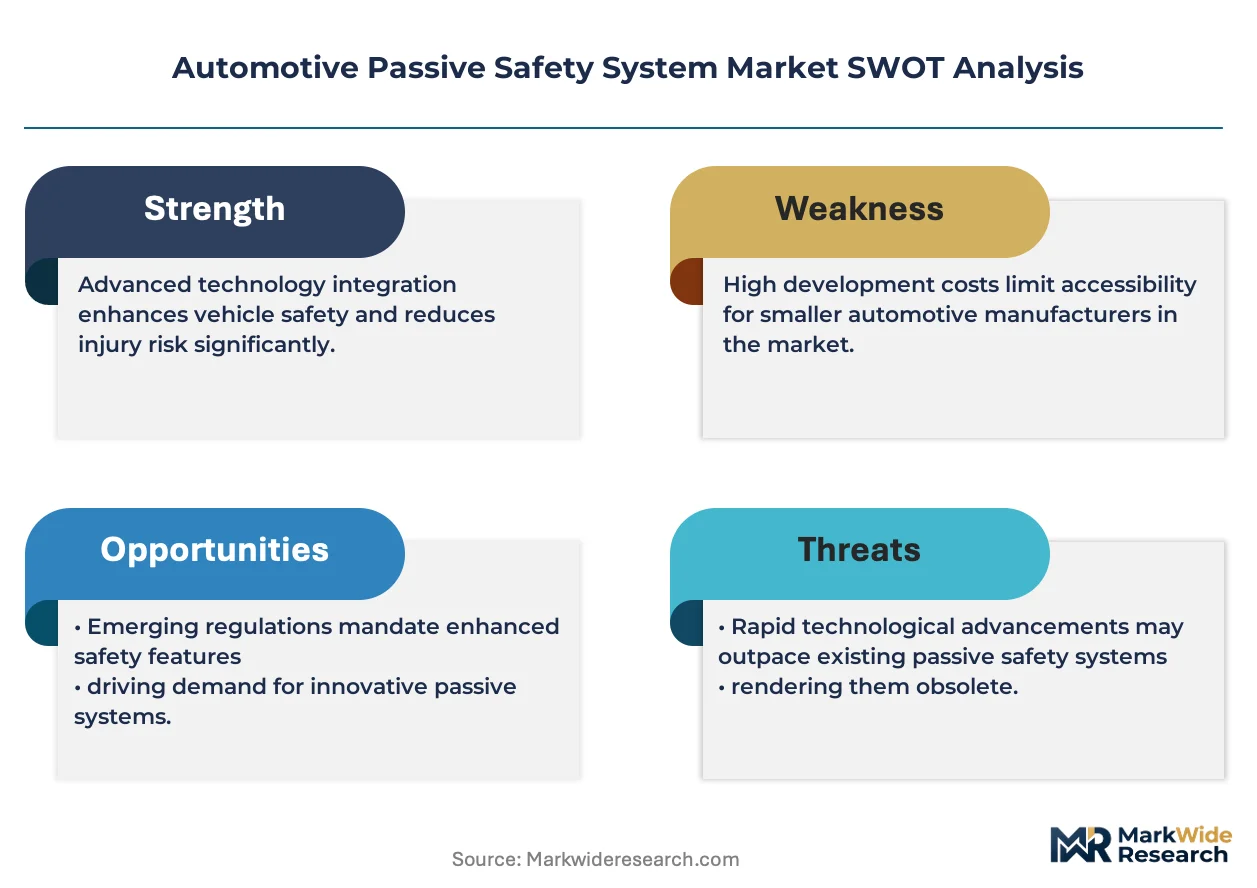
NHTSA Federal Motor Vehicle Safety Standards, EU General Safety Regulation with its revised occupant-protection requirements, and China's GB standards administered by MIIT collectively tighten test-protocol severity and expand protection mandates to vulnerable road users. These frameworks force redesign cycles that accelerate replacement demand for certified subsystems and raise barriers for uncertified aftermarket entrants. Stakeholders must monitor divergence between UN R94/R95 harmonization efforts and unilateral national rulemaking that could fragment homologation pathways.
Market Dynamics
NCAP protocol escalation is compressing design cycles for restraint systems, forcing OEMs to recertify platforms every 24-36 months rather than the traditional 5-year model cycles. This regulatory cadence is redistributing value toward sensor-integrated smart restraints and away from commodity airbag modules.
Growth Catalysts
- EU General Safety Regulation expansion:Mandates for vulnerable road user protection are driving bumper-to-pillar sensor deployment across C-segment vehicles and above.
- China MIIT GB standard convergence:Harmonization with UN R94/R95 protocols is unlocking export certification for domestic suppliers serving joint-venture OEMs.
- Multi-stage pyrotechnic algorithms:Predictive deployment based on occupant position and crash severity is capturing value in semi-autonomous vehicle architectures.
Market Restraints
- Inflator supply concentration:Three suppliers control 80% of global sodium azide and guanidine nitrate propellant capacity, creating single-source vulnerability.
- Homologation fragmentation:Divergence between NHTSA FMVSS 208 and UN R94 test protocols forces parallel certification tracks for North American and European variants.
- Steel price volatility:High-strength boron and press-hardened grades in seatbelt anchorages and steering columns transmit raw material swings directly to subsystem costs.
Strategic Opportunities
- India PLI scheme for auto components:Localized airbag module assembly for Maruti Suzuki and Hyundai Motor India is attracting tier-two contract manufacturers.
- Composite deployable structures:Carbon fiber-reinforced plastic knee bolsters and B-pillar reinforcements are hybridizing with metal substrates for 30-40% mass reduction.
- Over-the-air calibration:Cloud-based restraint parameter updates are enabling post-sale algorithm refinement without physical recall campaigns.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for pyrotechnic control units is concentrated among German and Japanese specialist firms.
- Legacy platform integration:12V electrical architectures in emerging-market vehicle lines cannot support the current draw of advanced multi-point firing circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Passive Safety System Market |
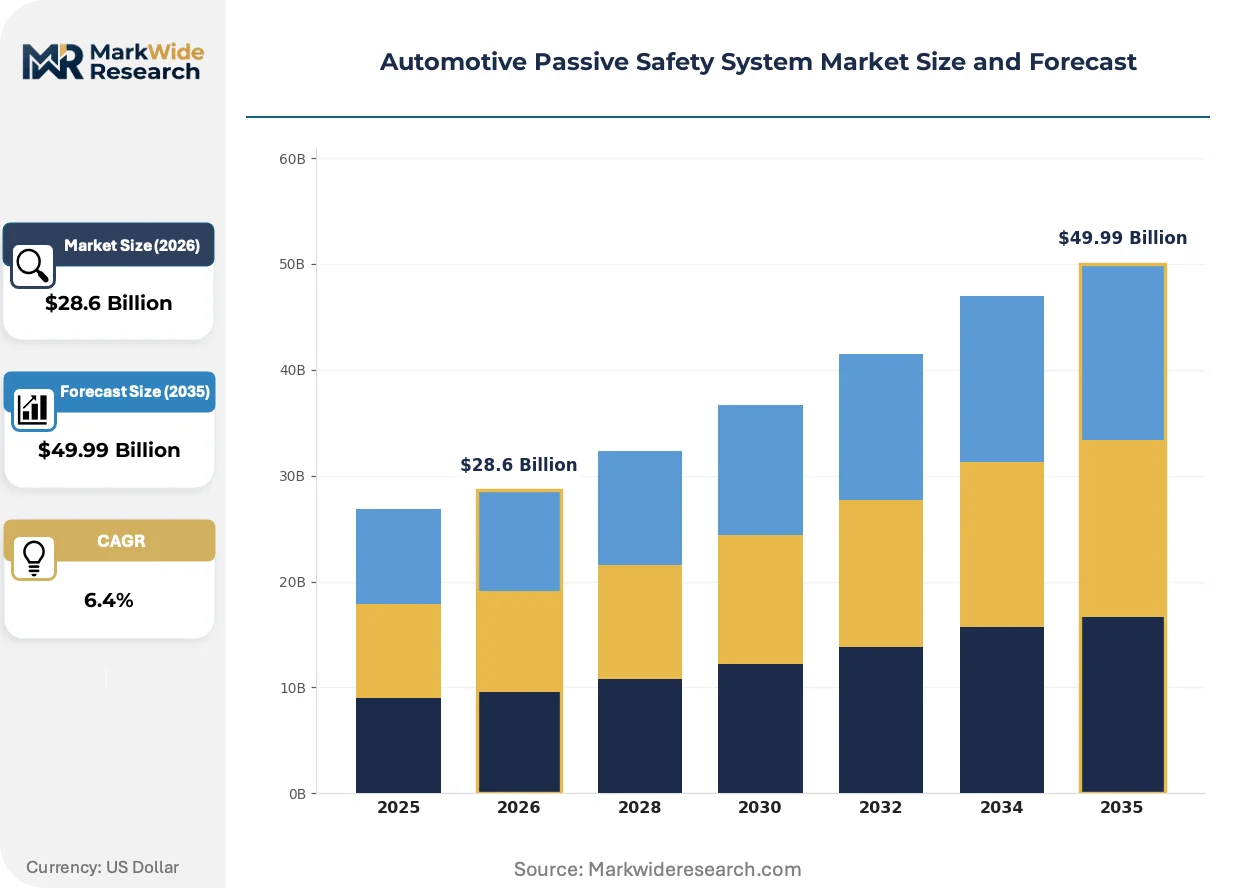
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airbags, Seatbelts, Crumple Zones, Safety Cells Technology: Sensor Technology, Active Smart Restraints, Composite Materials, Deployable Structures End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Owners Application: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Two-Wheelers |
| Companies Covered | Faurecia SE, DENSO Corporation, Autoliv Inc., Hyundai Mobis Co. Ltd., Toyoda Gosei Co. Ltd., ZF Friedrichshafen AG, Continental AG, Magna International Inc., Joyson Safety Systems Aschaffenburg GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Passive Safety System Market Emerging Trajectories
Passive safety engineering is migrating from mechanical energy absorption toward software-defined deployment timing. Algorithmic control of restraint activation is displacing fixed-threshold pyrotechnic systems across premium and mass-market segments alike.
Far-side airbag modules positioned between front occupants are hybridizing with center console structural elements to address oblique pole-impact scenarios. BMW and Volvo have deployed these systems in 2024 model year vehicles, with Korean OEMs adopting the architecture for 2026 launches. The technology is hybridizing seat-mounted and overhead restraint categories that previously operated as separate procurement lines.
NHTSA's proposed updates to FMVSS 214 side-impact testing will introduce a moving deformable barrier angled at 27 degrees, replacing the perpendicular pole test. This protocol change will force redesign of door-mounted thorax and pelvis airbags to address intrusion vectors from forward-of-B-pillar impacts. Suppliers serving the US market are pre-certifying modules against the draft standard to secure 2027 platform awards.
Fleet operators and insurance underwriters are demanding event data recorder transparency as a procurement precondition. Rental car companies and ride-hail platforms in California and Germany now require standardized EDR output formats for liability adjudication. This behavioral shift is compressing supplier differentiation around proprietary crash-signature algorithms into commodity hardware-plus-software bundles.
Automotive Passive Safety System Market Segmentation
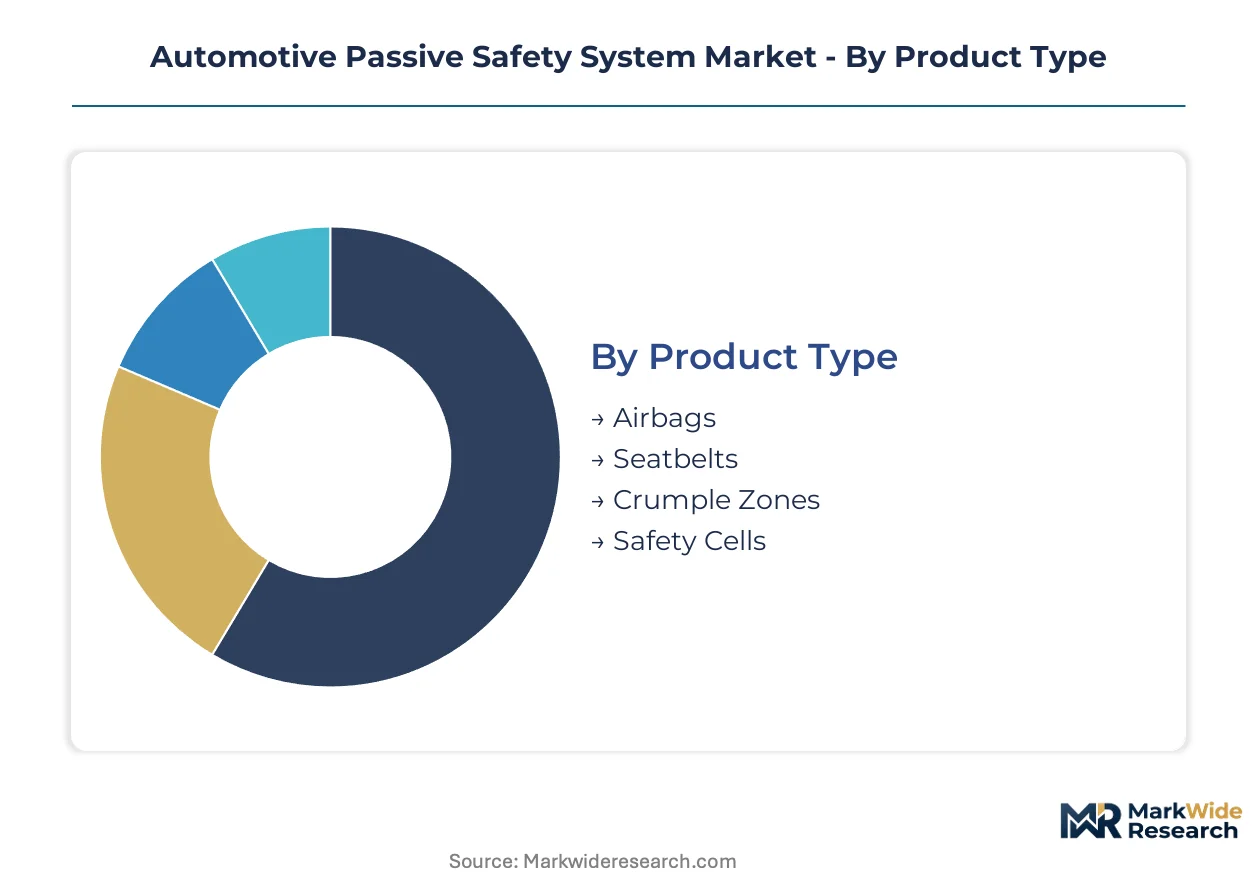
Passive safety procurement divides along technology maturity curves and regulatory certification tiers. OEMs source commodity restraints through consolidated supply agreements while advanced sensor-integrated systems command separate development contracts.
Product Type:
Mature mechanical components dominate installed volume while emerging structural designs capture redesign cycles.
- Airbags:Multi-stage pyrotechnic modules with variable inflation rates based on occupant position sensing. Frontal and side-curtain configurations absorb the majority of OEM price-down pressure in China and Germany as NCAP protocols tighten every 24-36 months.
- Seatbelts:Pretensioning retractors with force limiters and webbing clamp mechanisms. Korean and Japanese OEMs drive specification escalation toward active buckle presenters and integrated load sensors.
- Crumple Zones:Engineered deformation structures in front and rear longitudinal members.
- Safety Cells:Rigid passenger compartment enclosures using high-strength steel and aluminum extrusions.
Airbags handle the majority of throughput; active seatbelt variants are climbing the fastest on specification intensity.
Technology:
Cost tiers separate legacy pyrotechnic systems from premium predictive deployment architectures.
- Sensor Technology:Accelerometers, pressure sensors, and radar-fusion modules enabling crash severity prediction. German suppliers anchor development for EU General Safety Regulation mandates requiring vulnerable road user detection.
- Active Smart Restraints:Algorithm-controlled deployment timing with occupant classification and position tracking. US and European semi-autonomous platforms drive adoption as 48V electrical architectures proliferate.
- Composite Materials:Carbon fiber and glass-reinforced polymers in structural reinforcements.
- Deployable Structures:Active hood lifters and exterior airbags for pedestrian protection.
Sensor Technology commands the largest development budgets; Active Smart Restraints are expanding most quickly on platform penetration.
End User:
Customer type determines procurement leverage and certification burden intensity.
- OEMs:Direct platform integration with full homologation responsibility. Volkswagen, Toyota, and Stellantis concentrate volume awards through multi-year blanket orders with tier-one suppliers.
- Aftermarket Providers:Replacement module distribution for collision repair and recall fulfillment. US and European channels face rising barriers as NHTSA and UN R94 certification requirements extend to service-installed components.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging market production.
- Fleet Owners:Bulk procurement for rental, ride-hail, and commercial vehicle operators demanding standardized EDR transparency.
OEMs handle the majority of throughput; Fleet Owners are gaining share fastest on telematics integration requirements.
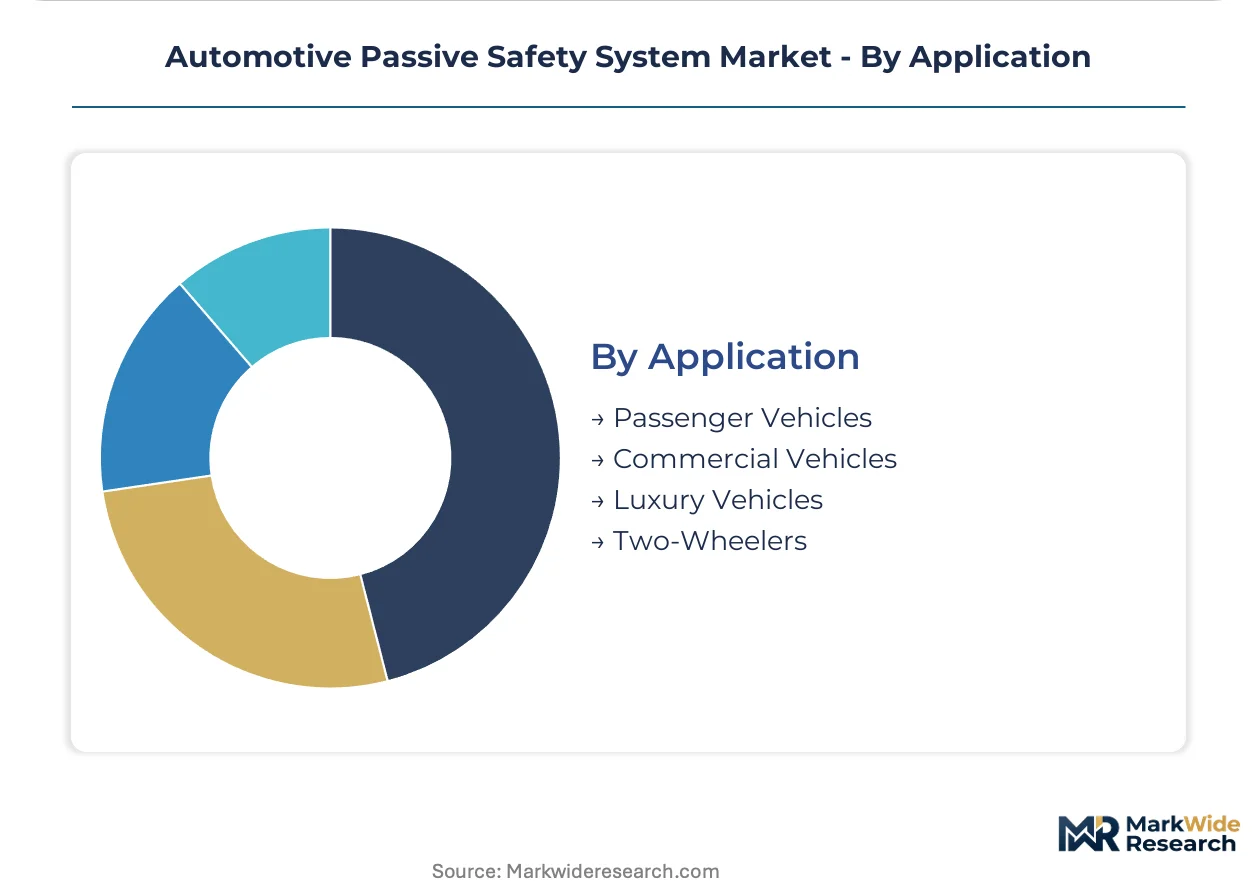
Application:
Vehicle category dictates restraint system complexity and unit economics.
- Passenger Vehicles:C-segment and above carry multi-chamber airbag arrays, far-side modules, and center console-integrated restraints. BMW and Volvo deployments are pressuring mass-market adoption timelines.
- Commercial Vehicles:Heavy-duty cab structures with rollover-optimized curtain systems. European and North American mandates for electronic stability control are cascading into enhanced restraint requirements.
- Luxury Vehicles:Rear-seat passenger airbags and active knee bolsters with composite substrates.
- Two-Wheelers:Airbag-equipped jackets and wearable restraints for premium motorcycle segments.
Passenger Vehicles handle the majority of throughput; Commercial Vehicles are expanding most quickly on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in passive safety systems favor manufacturing jurisdictions with integrated propellant chemistry and steel-forming capabilities. Germany and China run structural surpluses in airbag module shipments, while the United States and Japan remain net importers of sodium azide-based inflator assemblies.
China
Joint-venture OEMs in Shanghai and Guangzhou are localizing multi-stage pyrotechnic module assembly for export to Southeast Asian markets. MIIT's GB standard convergence with UN R94/R95 protocols is accelerating homologation timelines for domestic suppliers. The Yangtze River Delta cluster around Shanghai anchors inflator production capacity expansion.
Germany
Sensor-restraint integration development for EU General Safety Regulation compliance is concentrating in Stuttgart and Munich engineering centers. KBA oversight of UN R94/R95 certification is creating first-mover advantages for domestic tier-one suppliers. The Baden-Württemberg corridor hosts specialized ISO 26262 ASIL-D certification expertise for pyrotechnic control units.
United States
NHTSA's proposed FMVSS 214 side-impact updates are forcing pre-certification investments for 2027 platform awards. Detroit-based OEM procurement offices are consolidating blanket orders with tier-one suppliers across North American supply chains. The Midwest manufacturing belt around Michigan and Ohio retains concentration in seatbelt anchorages and steering column assemblies.
South Korea
Hyundai and Kia captive demand is driving specification escalation toward active buckle presenters and integrated load sensors. MFDS alignment with international restraint certification standards is smoothing export pathways to European markets. The Seoul Capital Area anchors R&D investment in algorithm-controlled deployment timing systems.
India
Maruti Suzuki and Hyundai Motor India are expanding airbag fitment mandates across entry-level vehicle lines under SIAM safety roadmaps. The PLI scheme for auto components is attracting contract manufacturers to Tamil Nadu and Gujarat assembly zones. The Chennai-Bengaluru industrial corridor is emerging as a regional hub for seatbelt retractor module production.
Automotive Passive Safety System Market Vendor Landscape
On the supply side, the industry is consolidating around three inflator chemistry specialists who control propellant capacity, while tier-two assemblers challenge through asset-light contract manufacturing. Strategic archetypes include vertically integrated module producers, sensor-restraint integrators, and captive OEM safety divisions. Competitive moves concentrate on backward integration into inflator production and algorithm licensing for predictive deployment systems.
Among European-based tier-one suppliers, ZF Friedrichshafen AG and Continental AG exemplify the sensor-restraint integration archetype, while Autoliv Inc. represents the vertically integrated module producer model with captive inflator capacity. Hyundai Mobis Co. Ltd. occupies a position within the captive OEM safety division category, leveraging Korean joint-venture demand and Chinese manufacturing partnerships.
| Leading Market Players |
|---|
| Faurecia SE |
| DENSO Corporation |
| Autoliv Inc. |
| Hyundai Mobis Co. Ltd. |
| Toyoda Gosei Co. Ltd. |
| ZF Friedrichshafen AG |
| Continental AG |
| Magna International Inc. |
| Joyson Safety Systems Aschaffenburg GmbH |
| Others |
Supply Flow & Price Mechanics
Sodium azide and guanidine nitrate propellant production concentrates among three suppliers, anchoring margin capture upstream while OEM price-down pressure compresses module assembler returns downstream. This concentration dynamic forces tier-one suppliers to seek backward integration or long-term offtake contracts to defend position.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled pricing tiers. Price differentiation rests on certification grade—UN R94/R95 versus NHTSA FMVSS 208 compliance—and vertical integration depth in inflator production. Cost compression in commodity airbag modules is intensifying because NCAP protocol escalation accelerates redesign cycles. Entry-level vehicle assemblers in India exhibit highest price sensitivity; premium European OEMs prioritize algorithm performance over unit cost.
Supply Chain Analysis
Sodium azide feedstock draws from Chinese and German chemical processors, with module assembly clustering in the Yangtze River Delta, Baden-Württemberg, and Seoul Capital Area. High-strength boron steel for seatbelt anchorages and press-hardened grades for steering columns feed from Japanese and South Korean mills. Single-source vulnerability in propellant chemistry creates systemic exposure. Distribution runs through tier-one direct supply agreements with blanket order structures, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Over-the-air calibration and cloud-based restraint parameter updates represent a service-attach layer expanding faster than hardware replacement cycles, enabling recurring revenue streams from installed base optimization.
For Market Incumbents: Harden algorithm licensing portfolios against sensor-restraint integrators encroaching on predictive deployment value pools. Deepen captive inflator capacity to offset propellant supply concentration risk. Secure ISO 26262 ASIL-D certification lock-in at German and Japanese engineering centers to raise rival compliance barriers. For New Entrants and Emerging Players: Contract manufacturing white-space in India's Tamil Nadu and Gujarat assembly zones offers the most penetrable entry point for tier-two assemblers seeking OEM captive demand. Algorithm-development boutiques serving 48V electrical architecture migration represent a second avenue. Pursue PLI scheme qualification to unlock Maruti Suzuki and Hyundai Motor India procurement access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor-technology specialists holding EU General Safety Regulation compliance moats. Five-to-ten year viability hinges on software-defined deployment timing capabilities displacing fixed-threshold pyrotechnic systems. Monitor NHTSA FMVSS 214 final rule publication as inflection signal for US market pre-certification investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inflator Chemistry | Captive sodium azide capacity insulates Autoliv and ZF from propellant supply shocks. |
| Sensor-Restraint Algorithm Licensing | Continental AG monetizes predictive deployment IP across multiple OEM platform architectures. |
| Composite Material Hybridization | Carbon fiber-reinforced knee bolsters enable 30-40% mass reduction for Hyundai Mobis contracts. |
| Cloud-Based OTA Calibration Infrastructure | Post-sale algorithm refinement eliminates physical recall campaigns for fleet operator accounts. |
| ISO 26262 ASIL-D Certification Acquisition | Specialist German engineering firms command premium valuations for functional safety expertise. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations managers and refined through secondary validation. Regulatory filings from NHTSA, KBA, and MIIT anchored compliance pathway mapping. Trade data from customs authorities, SEC 10-K disclosures, and vehicle production databases supplied volume triangulation. Bottom-up content-per-vehicle estimates and top-down OEM procurement spend analysis converged on segment sizing.
Demand-supply balance modeling across the analysis window integrated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from regression against historical fitment rate trajectories and regulatory mandate timelines. NCAP protocol escalation schedules and electrical architecture migration curves served as automotive-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in steel price volatility, semiconductor availability for sensor modules, or joint-venture OEM localization timelines would shift the trajectory. Cross-checking against IHS Markit vehicle registration data and OEM earnings call commentary on safety content spend is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market