
 Airbag Market | 2026-2036
Airbag Market Size, Share, and Industry Trends Forecast 2026-2036
Airbag Market Intelligence
Electric vehicle architectures is realigning airbag deployment strategies as battery-electric platforms demand redesigned occupant protection geometries. Autoliv Inc. leverages its pyrotechnic expertise to anchor supply relationships with premium EV manufacturers. ZF Friedrichshafen AG sustains factory-installed integration capabilities across European and North American assembly plants. Joyson Safety Systems competes through specialized curtain airbag configurations for crossover utility vehicles.
An airbag is a rapidly inflatable safety restraint comprising a folded textile cushion, gas generator, and crash sensor array designed to deploy within milliseconds of collision detection. The system utilizes sodium azide or guanidine nitrate propellants to generate nitrogen gas, filling woven nylon or polyester bags to pressures between 5 and 25 psi depending on seating position and crash severity. Frontal airbags dominate installed volume but face margin compression as standard equipment across all vehicle classes. Curtain airbags represent the fastest-expanding product category due to rollover protection mandates and structural pillar integration requirements. MEMS sensors command premium positioning within the technology stack as multi-axis accelerometers enable predictive deployment algorithms.
NHTSA Federal Motor Vehicle Safety Standards, Euro NCAP assessment protocols, and China's GB/T automotive safety standards collectively mandate multi-chamber airbag configurations and pedestrian protection compatibility. These frameworks compel manufacturers to validate systems across expanded crash scenarios, elevating R&D expenditure and certification timelines. Stakeholders must monitor sensor fusion developments and software-defined deployment logic as regulatory bodies integrate autonomous vehicle crashworthiness into existing safety architectures.
Market Dynamics
Electric vehicle platform proliferation is forcing airbag system redesigns as battery-pack positioning alters occupant compartment geometries and crash pulse signatures. Tier-1 suppliers must revalidate sensor fusion algorithms and pyrotechnic deployment sequences against these modified structural load paths.
Growth Catalysts
- Euro NCAP Protocols:The assessment body's five-star rating thresholds mandate side-curtain and center airbag coverage, compelling automakers to expand multi-chamber installations across vehicle classes.
- Sodium Azide Substitution:Guanidine nitrate propellant chemistry eliminates toxic byproduct concerns while maintaining deployment velocity, satisfying environmental compliance in European and North American markets.
- China:Domestic EV manufacturers are specifying ten-plus airbag configurations for premium battery-electric platforms, creating concentrated demand for advanced curtain and knee-protection modules.
Market Restraints
- Weaving Equipment Concentration:Specialized loom capacity for high-tenacity nylon 6,6 fabrics clusters in Germany and Japan, creating single-source vulnerability for bag textile supply.
- MEMS Sensor Cost Structure:Multi-axis accelerometer packages represent 35-40% of module bill-of-materials, compressing margins as automakers resist pass-through pricing.
- Pyrotechnic Shipment Restrictions:IATA dangerous goods classifications limit air freight options for inflator components, extending lead times for just-in-sequence assembly plant delivery.
Strategic Opportunities
- India:The country's PLI scheme for automotive components creates manufacturing incentives for domestic airbag assembly, targeting export markets in Southeast Asia and Africa.
- Pedestrian Protection Airbags:External hood-lifting and fender-deploying systems address Euro NCAP vulnerable road user protocols, opening new product categories beyond occupant restraints.
- Software-Defined Deployment:Over-the-air algorithm updates enable post-sale crash-signature optimization, converting hardware sales into recurring calibration revenue streams.
Industry Challenges
- Propellant Chemist Talent Pool:Guanidine nitrate formulation expertise concentrates among retiring specialists, constraining R&D velocity for next-generation inflator development.
- Homologation Timeline Compression:NHTSA's updated FMVSS 208 validation requirements extend certification cycles by 8-12 months, delaying platform launches and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airbag Market |
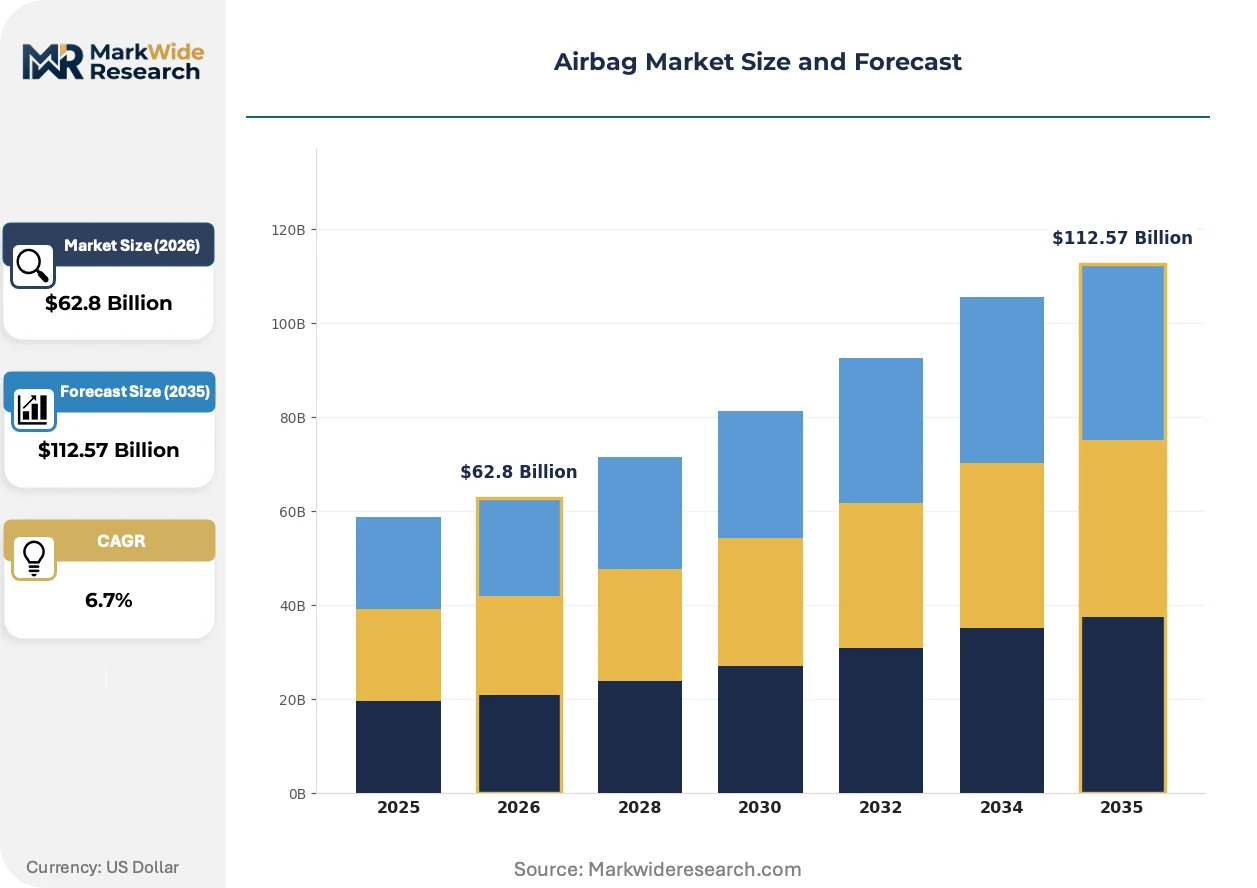
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $112.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Hybrid Airbags, MEMS Sensors, Pyrotechnic Systems, Inflatable Tubes End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Installation: Factory-installed, Retrofit Solutions, Mobile Installations, Integrated Systems |
| Companies Covered | Hyundai Mobis Co., Ltd., Denso Corporation, Autoliv Inc., Robert Bosch GmbH, Toyoda Gosei Co., Ltd., ZF Friedrichshafen AG, Continental AG, Yanfeng Automotive Safety, Joyson Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airbag Market Strategic Shifts & Innovations
Sensor fusion architectures are displacing discrete crash detection modules, consolidating accelerometer, pressure, and radar inputs into unified deployment decision engines. This integration demands new competencies in signal processing and functional safety validation.
Far-side airbag modules is electrifying competitive positioning as center-console-mounted cushions address lateral impact scenarios previously unprotected by conventional side-curtain systems. European luxury EV platforms are adopting these units as standard equipment. The technology is electrifying supplier differentiation as first-movers capture platform-specific design wins before standardization commoditizes the segment.
REACH chemical restrictions are forcing propellant reformulation across European supply chains. The regulation's sunset dates for legacy azide compounds compress transition timelines for inflator manufacturers. Module suppliers are responding with accelerated guanidine nitrate qualification programs and dual-chemistry production lines to maintain cross-border shipment flexibility.
Fleet procurement of standardized safety packages is consolidating specification authority away from individual OEM engineering teams. Rental and mobility-service buyers now dictate airbag count and sensor configuration as condition of volume fleet orders. This concentration is most visible in Germany's corporate leasing market, where pooled procurement agreements favor suppliers offering modular, scalable restraint platforms.
Airbag Market Segmentation
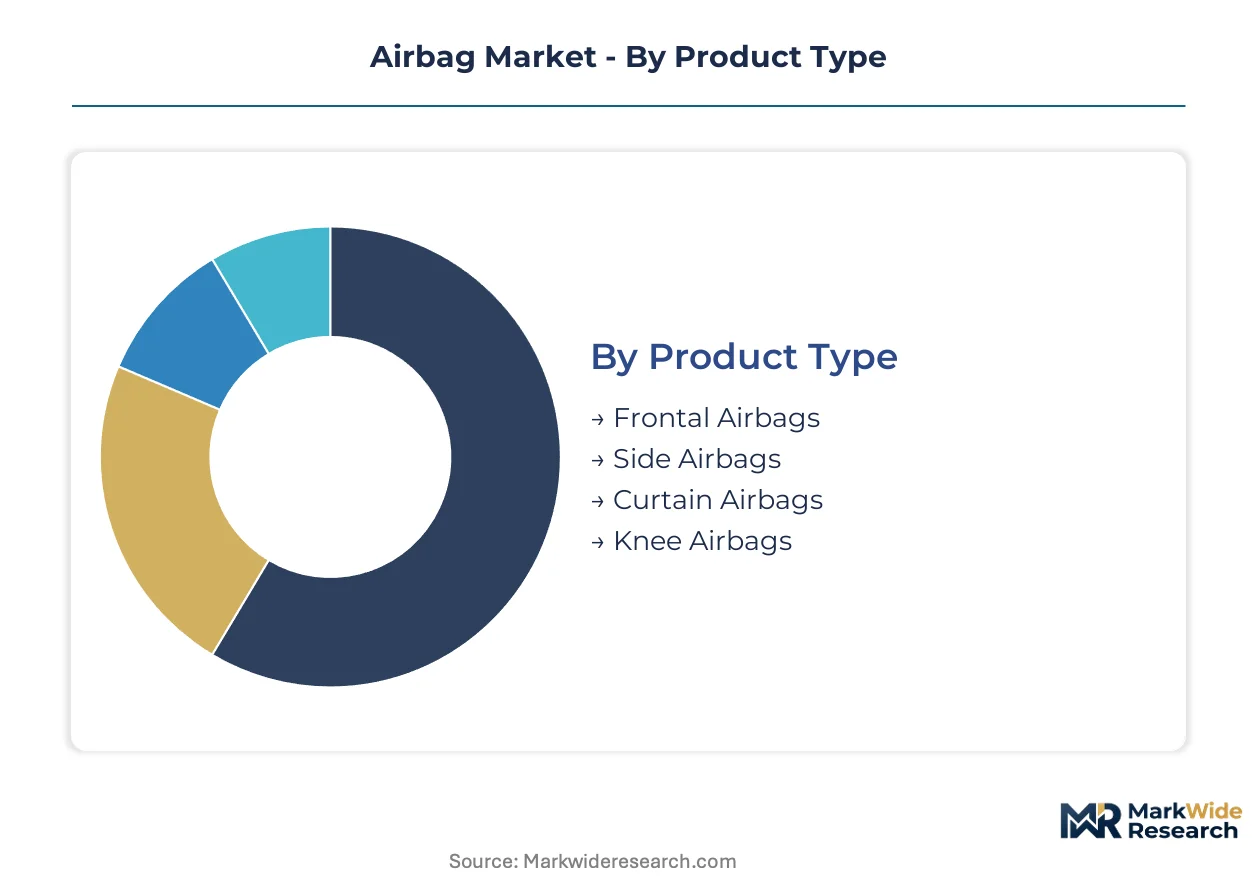
Airbag procurement patterns diverge sharply across product architectures and installation channels, with regulatory mandates and platform electrification reshaping specification authority. Segment boundaries are blurring as sensor fusion and software-defined deployment create cross-category technology dependencies.
Product Type:
Supply concentration for woven nylon 6,6 fabrics clusters among German and Japanese loom operators, dictating which cushion geometries achieve volume scale.
- Frontal Airbags:Dual-stage deployment modules utilizing sodium azide or guanidine nitrate propellants generate nitrogen gas at 5-25 psi depending on crash severity. China, Germany, and the United States concentrate factory-installed demand as NHTSA and Euro NCAP protocols mandate standard fitment across all vehicle classes, compressing margins through universal adoption.
- Curtain Airbags:Woven polyester cushions spanning A-pillar to C-pillar integrate with roof rail structural members for rollover protection. European luxury EV platforms and Chinese battery-electric crossovers are driving specification expansion as Euro NCAP five-star thresholds mandate side-curtain coverage, making this the fastest-climbing product category.
- Side Airbags:Seat-mounted or door-panel modules address lateral impact scenarios through compact pyrotechnic inflators.
- Knee Airbags:Lower-dash deployment units protect femur and patella load paths in frontal collisions.
Frontal airbags absorb the bulk of installed capacity; curtain airbags are expanding most quickly.
Technology:
Cost tier differentiation separates premium sensor-fusion architectures from commodity pyrotechnic systems, with MEMS packages commanding 35-40% of module bill-of-materials.
- MEMS Sensors:Multi-axis accelerometer arrays enable predictive deployment algorithms through signal processing integration. Fleet procurement consolidation in Germany's corporate leasing market favors suppliers offering modular, scalable sensor platforms with over-the-air calibration capability.
- Pyrotechnic Systems:Guanidine nitrate chemistry eliminates toxic byproduct concerns while maintaining deployment velocity under REACH chemical restrictions. European and North American environmental compliance deadlines are accelerating substitution timelines for legacy azide compounds.
- Hybrid Airbags:Combined gas-generator and stored-gas architectures optimize fill rates for far-side protection scenarios.
- Inflatable Tubes:Cylindrical restraint structures deploy along roof rails or seat frames for specialized occupant positioning.
MEMS sensors capture premium positioning; pyrotechnic systems maintain volume dominance through cost efficiency.
End User:
Customer type concentration is shifting as pooled procurement agreements transfer specification authority from individual OEM engineering teams to fleet buyers.
- OEMs:Original equipment manufacturers validate systems across expanded crash scenarios under NHTSA FMVSS 208 and Euro NCAP protocols, extending certification cycles. Platform-specific design wins for far-side airbag modules are concentrating among first-movers in European luxury EV segments.
- Fleet Operators:Rental and mobility-service buyers now dictate airbag count and sensor configuration as conditions of volume orders. India's PLI scheme for automotive components is creating manufacturing incentives targeting export markets in Southeast Asia and Africa.
- Vehicle Assemblers:Contract manufacturers integrate pre-validated restraint modules into final assembly sequences.
- Aftermarket Providers:Independent installers address replacement demand and retrofit opportunities outside factory channels.
OEMs retain design validation authority; fleet operators are gaining procurement leverage fastest.
Installation:
Volume distribution favors captive supply relationships, with factory-installed integration commanding margin premiums over post-sale channels.
- Factory-installed:Module integration occurs during vehicle assembly with just-in-sequence delivery from Tier-1 suppliers. IATA dangerous goods classifications for pyrotechnic components limit air freight options, extending lead times for assembly plant synchronization.
- Integrated Systems:Unified sensor-fusion and deployment architectures consolidate accelerometer, pressure, and radar inputs into single decision engines. Software-defined deployment logic enables post-sale crash-signature optimization, converting hardware sales into recurring calibration revenue.
- Retrofit Solutions:Post-manufacture installations address regulatory upgrades or fleet standardization requirements.
- Mobile Installations:Service-provider deployment at customer locations for replacement or upgrade scenarios.
Factory-installed systems dominate revenue concentration; integrated systems are climbing fastest through software monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hefei Economic and Technological Development Zone and Germany's Saxony-Anhalt automotive corridor are concentrating new airbag module assembly capacity as battery-electric platform proliferation reshapes supplier geography.
China
Domestic EV manufacturers specify ten-plus airbag configurations for premium battery-electric platforms, creating concentrated demand for advanced curtain modules. MIIT's GB/T automotive safety standards mandate multi-chamber protection systems, accelerating validation cycles for local suppliers. Hefei and Shanghai clusters host expanding inflator assembly lines serving BYD and NIO vehicle programs.
Germany
European luxury EV platforms adopt far-side airbag modules as standard equipment, driving specification expansion among premium OEMs. KBA homologation protocols under Euro NCAP five-star thresholds compel side-curtain and center airbag coverage across vehicle classes. Saxony-Anhalt and Bavaria production corridors concentrate weaving capacity for high-tenacity nylon 6,6 fabrics.
United States
Detroit Three automakers revalidate sensor fusion algorithms against modified crash pulse signatures from battery-pack positioning in electric platforms. NHTSA's updated FMVSS 208 validation requirements extend certification cycles, freezing engineering resources at Tier-1 suppliers. Michigan and Ohio assembly corridors sustain factory-installed integration relationships with captive pyrotechnic suppliers.
India
Domestic passenger vehicle safety penetration climbs as Maruti Suzuki and Tata Motors expand airbag fitment beyond regulatory minimums. The PLI scheme for automotive components creates manufacturing incentives for domestic module assembly targeting Southeast Asian export markets. Tamil Nadu and Gujarat industrial corridors attract inflator component investments from Korean and Japanese suppliers.
Japan
Keiretsu-affiliated suppliers maintain pyrotechnic expertise concentration as guanidine nitrate formulation transitions accelerate. METI industrial standards coordinate with global REACH chemical restrictions to sunset legacy azide compounds. Aichi and Kanagawa prefectures host specialized loom operators supplying woven bag textiles to regional assembly plants.
Airbag Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated Tier-1 suppliers commanding factory-installed relationships while component specialists capture textile and sensor sub-tier positions. The structure consolidates around pyrotechnic expertise holders and MEMS sensor fabricators, creating asymmetric dependency patterns. Three archetypes dominate: full-system integrators with captive inflator production, modular component specialists supplying across OEM programs, and regional assemblers serving emerging market vehicle manufacturers. Competitive moves concentrate on backward integration into propellant chemistry and upstream control over high-tenacity fabric weaving capacity.
Within the full-system integrator tier, Autoliv Inc., ZF Friedrichshafen AG, and Joyson Safety Systems occupy positions representing distinct geographic and capability anchors. Autoliv exemplifies the pyrotechnic-first archetype with European and North American production footprints. ZF Friedrichshafen AG represents the diversified automotive supplier model integrating restraint systems within broader chassis and safety portfolios. Joyson Safety Systems sits within the acquisition-driven expansion pattern, illustrating how Chinese capital has consolidated former North American and European safety assets into a regionally focused competitor.
| Leading Market Players |
|---|
| Hyundai Mobis Co., Ltd. |
| Denso Corporation |
| Autoliv Inc. |
| Robert Bosch GmbH |
| Toyoda Gosei Co., Ltd. |
| ZF Friedrichshafen AG |
| Continental AG |
| Yanfeng Automotive Safety |
| Joyson Safety Systems |
| Others |
Cost & Logistics Intelligence
Guanidine nitrate propellant chemistry transitions are compressing module economics while concentrating supply relationships among chemistry-qualified suppliers. This dual restructuring elevates backward integration premiums for pyrotechnic expertise holders and tightens procurement leverage for OEMs resisting pass-through pricing.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard contract pricing as IATA dangerous goods restrictions limit air freight options for inflator components. Three-tier pricing structure across premium, standard, and economy levels separates MEMS sensor-fusion architectures from commodity pyrotechnic systems, with certification grade under Euro NCAP protocols driving tier placement. Pricing pressure stems from automaker resistance to MEMS cost pass-through, which represents 35-40% of module bill-of-materials. Fleet operators exhibit highest price sensitivity through pooled procurement agreements, while luxury EV platforms maintain lowest sensitivity for far-side airbag specifications.
Supply Chain Analysis
Reverse logistics for pyrotechnic components face IATA dangerous goods classification barriers that block refurbishment flows and mandate specialized disposal chains. Supply concentration clusters in Germany, Japan, and China for high-tenacity nylon 6,6 weaving capacity, inflator assembly, and MEMS sensor fabrication respectively. Raw material dependencies draw from guanidine nitrate chemical feedstocks, woven polyester and nylon textiles, and semiconductor-grade silicon for accelerometer substrates. Single-source vulnerability in German and Japanese loom capacity creates structural risk for bag textile supply. Distribution runs through just-in-sequence delivery to assembly plants, with rail and sea freight dominating pyrotechnic component movement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into propellant chemistry and upstream fabric weaving capacity is accelerating as suppliers defend margin position against OEM procurement consolidation. Players are racing to capture captive supply of guanidine nitrate formulation expertise and high-tenacity nylon 6,6 production before homologation timelines freeze platform access.
For Market Incumbents: Anticipate sensor fusion commoditization by deepening captive pyrotechnic production and securing dual-chemistry qualification programs under REACH sunset deadlines. Lock in long-term weaving capacity contracts in Saxony-Anhalt and Aichi prefectures before loom operators impose allocation restrictions. Counter fleet procurement leverage through modular platform architectures that enable over-the-air deployment calibration revenue streams. For New Entrants and Emerging Players: The premium-economy price-point gap in India's domestic passenger vehicle segment offers white-space entry through PLI scheme manufacturing incentives targeting Southeast Asian export markets. Target aftermarket retrofit solutions for regulatory upgrade cycles in African and Latin American markets where factory-installed penetration remains incomplete. Pursue specialized curtain airbag configurations for crossover utility vehicles as the most penetrable product category with lower certification barriers than frontal systems. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-system integrators seeking propellant chemistry expertise or MEMS sensor fabrication capabilities. Long-term viability hinges on software-defined deployment monetization converting hardware sales into recurring calibration revenue. Monitor NHTSA FMVSS 208 validation requirement updates as the critical inflection signal for engineering resource allocation and platform launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propellant Chemistry | Captures guanidine nitrate formulation expertise as retiring specialists constrain R&D velocity. |
| Weaving Capacity Lock-in | Secures high-tenacity nylon 6,6 supply from German and Japanese loom operators against allocation risk. |
| Software-Defined Deployment Investment | Enables over-the-air algorithm updates converting hardware sales into recurring calibration revenue. |
| Dual-Chemistry Production Lines | Maintains cross-border shipment flexibility under REACH chemical restrictions and NHTSA validation protocols. |
| Far-Side Airbag Platform Standardization | Captures design wins in European luxury EV segments before standardization commoditizes the category. |
Research Approach
Multi-period observation of airbag unit counts per vehicle, propellant chemistry transitions, and regulatory protocol evolution anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from NHTSA FMVSS 208 filings, Euro NCAP assessment protocols, MIIT GB/T standards, vehicle production databases, and IHS Markit registration data. Bottom-up module shipment triangulation against top-down OEM platform volume estimates calibrated market sizing.
Input-output matrix modeling connected propulsion architecture shifts, content-per-vehicle trajectories, and regional production cluster expansion to generate segment-level projections across the analysis window. Segmentation dimensions incorporated product type, technology tier, end-user category, and installation channel. CAGRs were derived from slope-intercept fitting of validated data points against platform rollout schedules. Industry-specific forecast inputs included battery-electric vehicle penetration curves and Euro NCAP five-star threshold adoption rates.
Inputs from regulatory filing databases and supplier disclosure documents were available through the study window; gaps in proprietary OEM platform engineering specifications introduce uncertainty bands around far-side airbag adoption timelines. Forecasts reflect assumptions regarding REACH chemical restriction enforcement consistency and NHTSA validation cycle durations. Practitioners should monitor NHTSA FMVSS 208 update announcements and Euro NCAP protocol revision schedules for early signals of certification burden shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market