
 Forklift Camera Systems Market | 2026-2036
Forklift Camera Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Camera Systems Market Insights
Modular camera kits with wireless transmitters and magnetic mounts is expanding buyer flexibility, allowing warehouses to reconfigure visibility zones without hardwiring infrastructure. Orlaco leverages its marine-grade sealing heritage to dominate outdoor and cold-storage forklift applications. STONKAM anchors its position through integrated monitor-and-camera bundles priced for mid-size logistics fleets. Bosch competes on automotive-grade image processing algorithms adapted for low-light warehouse environments.
Forklift camera systems comprise ruggedized video capture devices, display monitors, and signal transmission hardware engineered to eliminate operator blind spots during material handling operations. These systems typically withstand vibration levels exceeding five grms, operate across temperature ranges from minus twenty to sixty degrees Celsius, and deliver real-time video feeds with latency below one hundred milliseconds to prevent pedestrian strikes and rack collisions. Rearview cameras sustain the largest installed base due to straightforward retrofit compatibility with legacy forklift fleets, while digital systems are displacing analog installations as warehouses upgrade to high-definition feeds and digital video recording for incident documentation. Wireless systems represent the fastest-growing technology category, eliminating cable fatigue failures in high-cycle reach truck applications where mast flexing degrades wired connections.
FDA facility sanitation requirements indirectly shape camera housing material specifications in pharmaceutical and food-grade warehouses, while OSHA powered industrial truck standards mandate operator visibility safeguards that directly drive camera adoption in United States facilities. EMA good manufacturing practice guidelines and Japan's METI industrial safety frameworks create parallel compliance pull across European and Japanese pharmaceutical distribution networks. Stakeholders must monitor convergence between camera systems and fleet telematics platforms, as integration with warehouse management software becomes the decisive procurement criterion beyond standalone video functionality.
Market Dynamics
Wireless transmission hardware is compressing installation timelines from weeks to days, eliminating cable fatigue failures in high-cycle reach truck operations where mast flexing degrades wired connections. This infrastructure shift is redrawing competitive boundaries between retrofit specialists and integrated system providers.
Growth Catalysts
- OSHA powered industrial truck standards:United States facilities face direct visibility mandates that accelerate camera adoption in legacy forklift fleets. Warehouses retrofit rearview systems to achieve compliance without equipment replacement.
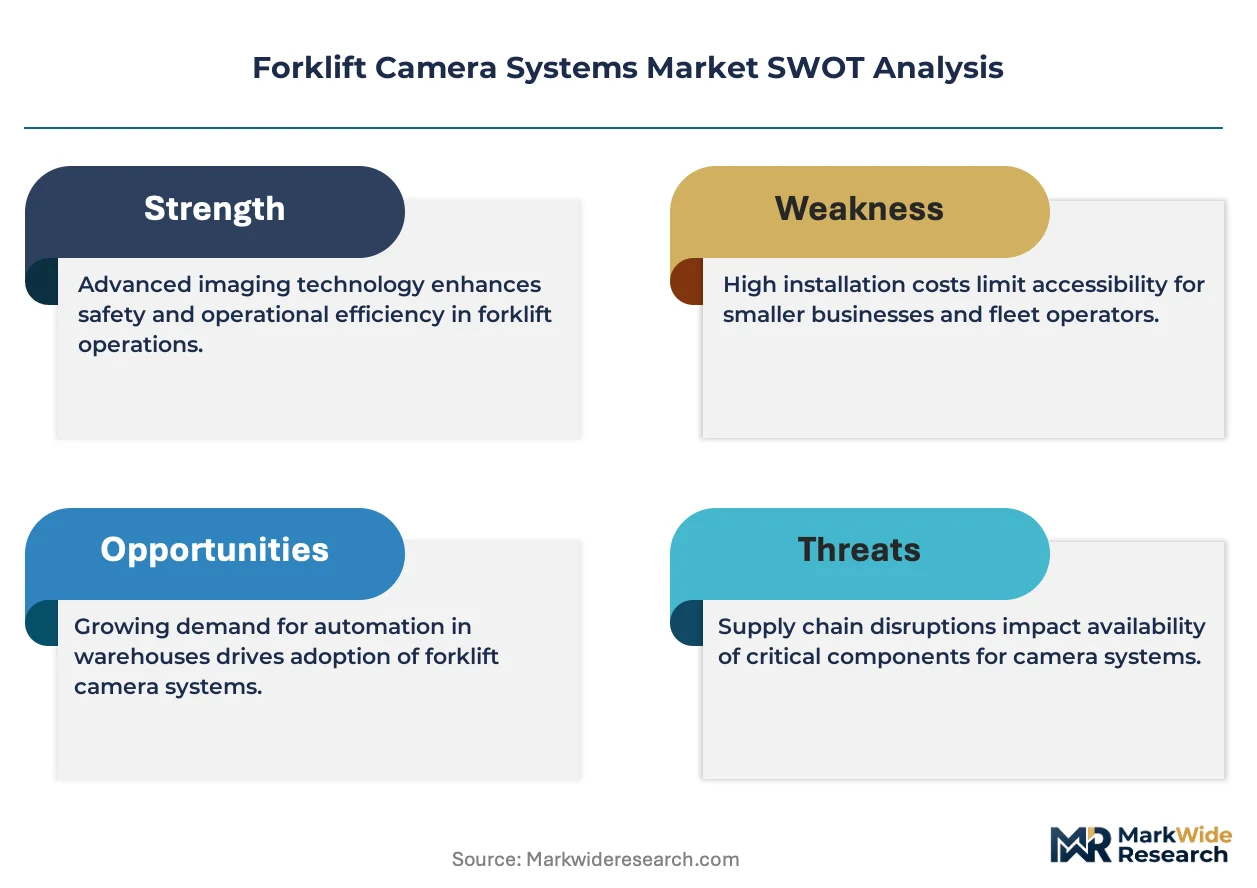
- Automated warehousing corridors:E-commerce fulfillment centers in Germany and China deploy camera networks to enable narrow-aisle automation. These facilities require real-time visual verification for autonomous navigation systems.
- Digital video recording capability:High-definition feed documentation resolves liability disputes and insurance claims. Incident footage provides objective evidence in pedestrian strike investigations.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication concentrates in East Asian foundries, exposing camera manufacturers to input volatility and extended lead times for specialized automotive-grade components.
- Legacy analog infrastructure:Thousands of warehouses operate coaxial cable networks that resist digital upgrade paths without complete rewiring, trapping buyers in lower-resolution systems.
- Cold-storage operational limits:Condensation and thermal cycling in minus-twenty-degree environments degrade standard camera housings, requiring costly marine-grade sealing specifications.
Strategic Opportunities
- India's logistics modernization:The country's PLI scheme for warehousing infrastructure creates subsidy pathways for safety equipment procurement in emerging distribution hubs near Mumbai and Delhi.
- Fleet telematics convergence:Camera systems that feed directly into warehouse management software platforms capture premium positioning. Integration becomes the decisive procurement criterion beyond standalone video functionality.
- Pharmaceutical cold chain expansion:FDA facility sanitation requirements indirectly shape camera housing material specifications, opening specialized demand for stainless-steel enclosures in temperature-controlled pharmaceutical distribution.
Industry Challenges
- ISO 26262 functional safety certification:Automotive-grade reliability standards for image processing algorithms demand eighteen-month validation timelines that delay product launches and compress R&D budgets.
- Legacy forklift electrical architecture:Pre-2010 lift trucks lack CAN bus connectivity, forcing camera suppliers to engineer standalone power and signal solutions for the installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Camera Systems Market |
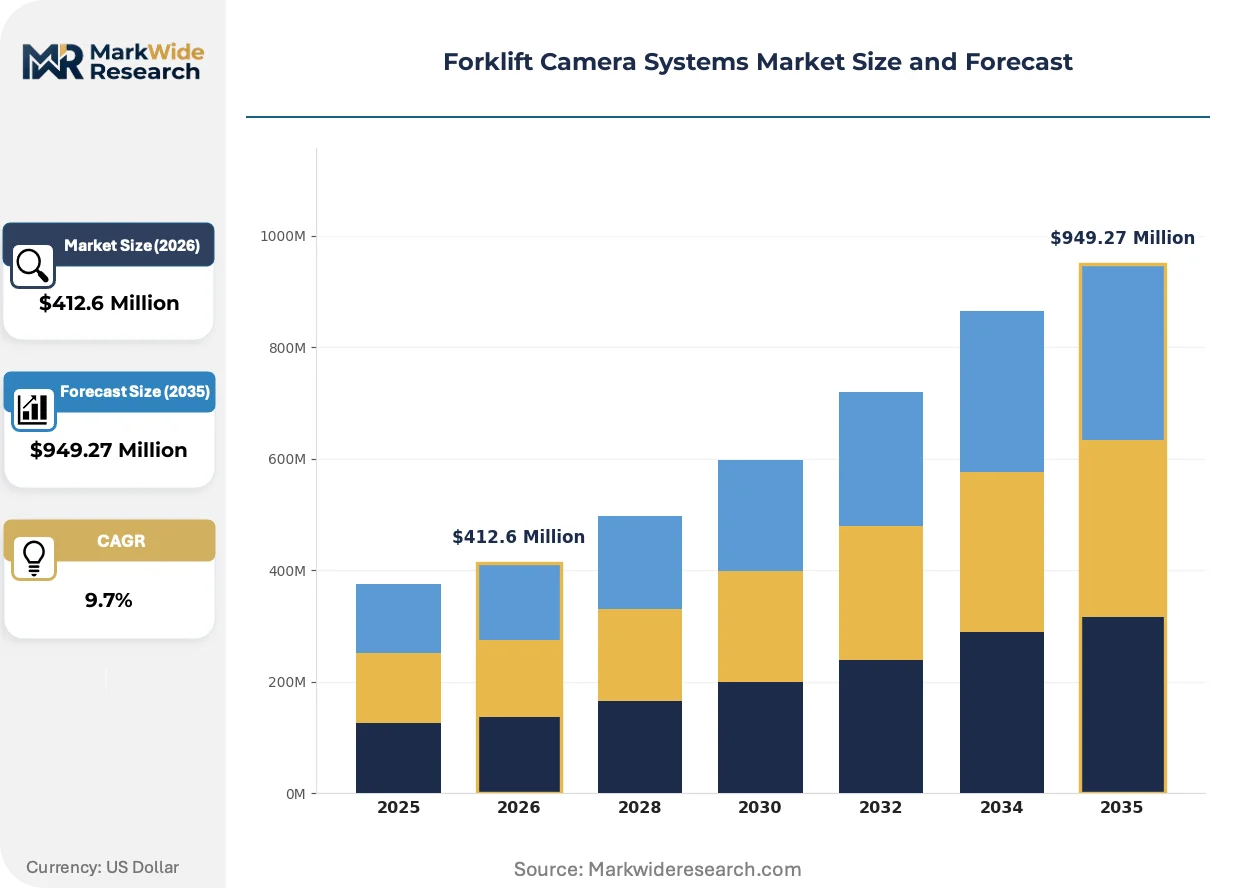
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Cameras, 360-Degree Cameras, Dual-Lens Cameras, Front Cameras Technology: Analog Systems, Digital Systems, Wireless Systems, IP Cameras End User: Manufacturing Plants, Warehouses, Distribution Centers, Construction Sites Installation Type: Fixed Installation, Portable Installation, Permanent Installation, Temporary Installation |
| Companies Covered | Orlaco, STONKAM, TVH, Bosch, Brigade Electronics, Spillard Safety Systems, Rosco, SharpEagle Technology, Rear View Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Camera Systems Market Trends and Innovations
Artificial intelligence inference at the edge is transforming camera systems from passive recording devices into active collision avoidance systems. This capability expansion is redefining buyer value propositions and supplier technical requirements.
Machine vision processors with onboard object detection algorithms are integrating pedestrian recognition and proximity alerting directly into camera housings. Third-party logistics operators in high-density United States distribution centers deploy these systems to reduce near-miss incidents without centralized server infrastructure. The technology is integrating safety and productivity metrics into unified fleet management dashboards.
Japan's METI industrial safety frameworks now mandate documented visibility assessments for powered industrial trucks in pharmaceutical distribution networks. Compliance officers require timestamped video archives spanning ninety days. Japanese facilities respond by specifying cameras with embedded solid-state storage and automated upload protocols to satisfy audit requirements.
Buyer preference for bundled hardware-software subscriptions is displacing traditional capital expenditure procurement in mid-size logistics fleets. Leasing arrangements that include installation, maintenance, and cloud storage spread costs across operating budgets. This shift is most visible among European third-party logistics providers managing seasonal volume fluctuations.
Forklift Camera Systems Market Segmentation
Forklift camera systems fragment across four dimensions that shape procurement decisions and supplier positioning. Each category reflects distinct technical requirements, compliance pressures, and total cost of ownership profiles that buyers must navigate.
Product Type:
Capital intensity varies sharply across camera configurations, with multi-lens arrays demanding substantially higher upfront investment than single-point solutions.
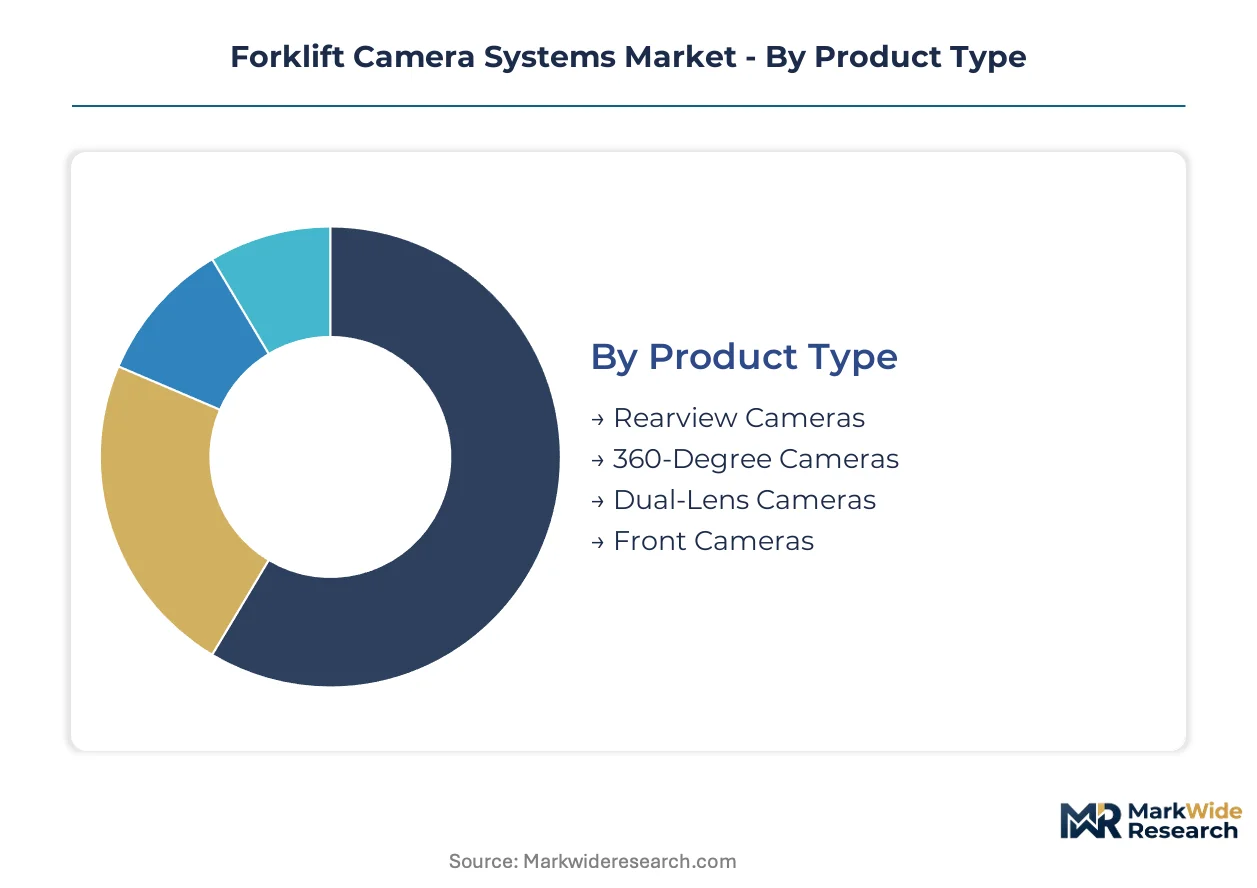
- Rearview Cameras:Single-lens units mounted to overhead guards or rear frames deliver basic blind-spot elimination for legacy fleet retrofits. Demand concentrates in United States distribution centers where OSHA visibility mandates drive rapid deployment without mast modification. These systems dominate current installed capacity due to straightforward compatibility with existing electrical architectures.
- 360-Degree Cameras:Multi-sensor arrays with stitched-image processing create bird's-eye visibility for narrow-aisle navigation. German e-commerce fulfillment centers specify these for automated warehousing corridors where autonomous navigation systems require comprehensive spatial awareness. The complexity of calibration and installation elevates total project cost significantly above single-lens alternatives.
- Dual-Lens Cameras:Paired forward-and-rear configurations balance coverage depth with moderate hardware investment.
- Front Cameras:Forward-facing units address load engagement visibility for high-reach applications in dense rack environments.
Most installed capacity flows through Rearview Cameras. Expansion is steepest in 360-Degree Cameras.
Technology:
Migration patterns across technology tiers reflect infrastructure lifecycle status and digital maturity in target facilities.
- Digital Systems:High-definition feeds with digital video recording capability resolve liability disputes through timestamped incident documentation. Chinese automated warehousing corridors specify these for integration with warehouse management platforms. The shift from analog infrastructure requires complete cable replacement, compressing upgrade timelines where coaxial networks resist retrofit.
- Wireless Systems:Radio-frequency transmission eliminates cable fatigue failures in high-cycle reach truck operations where mast flexing degrades wired connections. Japanese pharmaceutical distribution networks deploy these to satisfy METI visibility assessment mandates without invasive electrical rework. Battery-powered transmitters and magnetic mounts accelerate installation to hours rather than days.
- Analog Systems:Coaxial-based video persists in budget-constrained facilities with legacy monitor infrastructure.
- IP Cameras:Network-addressable units enable direct integration with fleet telematics and cloud storage architectures.
Digital Systems carry the largest revenue base. Wireless Systems are climbing the fastest as mast-flexing failures drive infrastructure replacement.
End User:
Application environment dictates sealing specifications, temperature tolerance, and vibration resistance requirements.
- Warehouses:Indoor facilities with climate-controlled environments standardize on mid-grade housings for high-volume forklift operations. United States third-party logistics providers specify these for seasonal volume flexibility with bundled maintenance subscriptions. The density of pedestrian traffic elevates collision avoidance priority over extreme environmental protection.
- Distribution Centers:High-throughput facilities with automated sortation systems require camera integration with warehouse management software for real-time visual verification. German and Chinese e-commerce fulfillment networks concentrate demand here as narrow-aisle automation scales. FDA sanitation requirements in pharmaceutical cold chain operations shape stainless-steel housing specifications.
- Manufacturing Plants:Assembly-line adjacent operations demand ruggedized units resistant to chemical exposure and particulate contamination.
- Construction Sites:Outdoor and rough-terrain applications specify marine-grade sealing and extended temperature ranges.
Warehouse deployments account for the greatest unit volume. Distribution Centers show the steepest technology upgrade trajectory.
Installation Type:
Flexibility premiums separate temporary configurations from permanent infrastructure commitments.
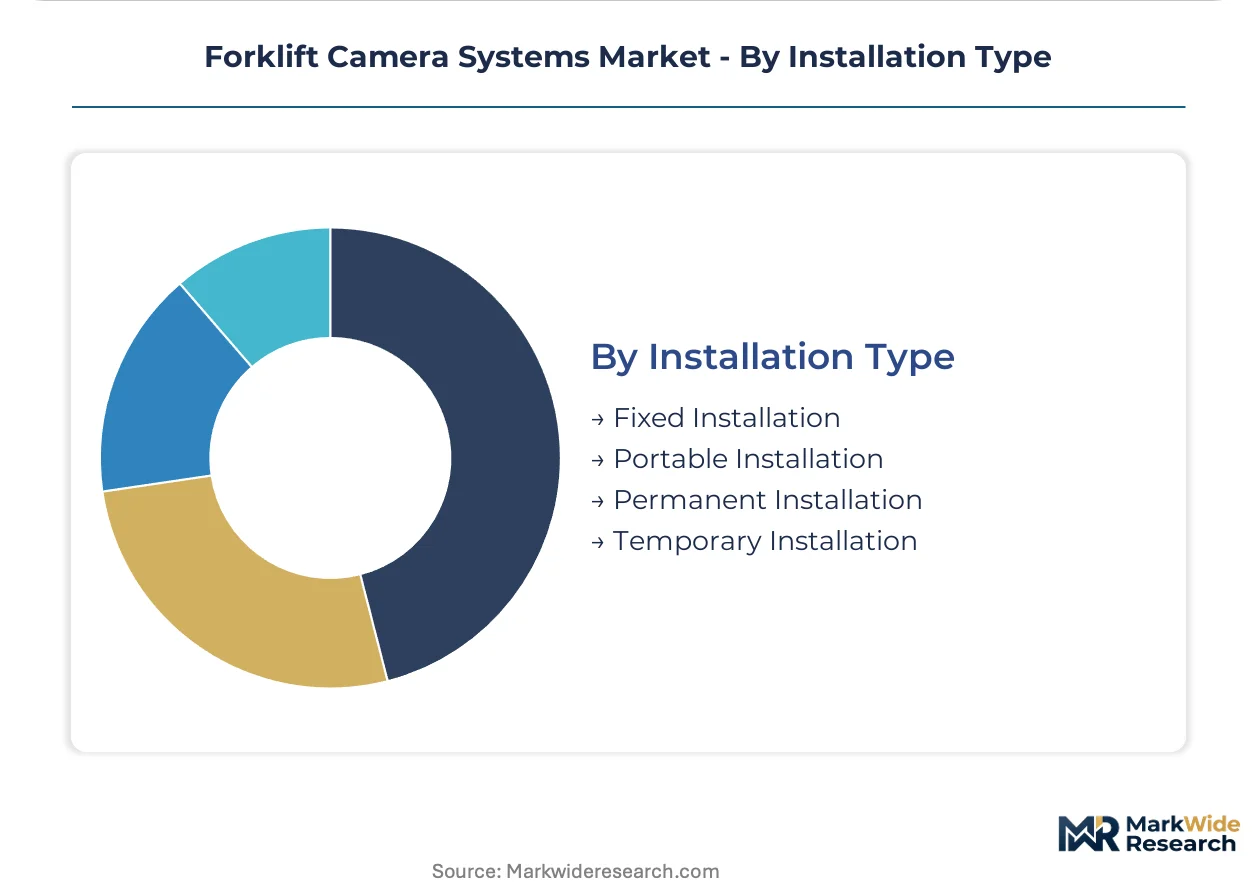
- Fixed Installation:Hardwired mounting with integrated power delivery suits dedicated fleet assignments in stable operational layouts. United States manufacturing plants favor these for predictable maintenance scheduling and minimal downtime exposure. The capital expenditure treatment aligns with depreciation schedules for long-asset holding periods.
- Portable Installation:Magnetic mounts and battery-powered transmitters enable rapid reconfiguration across shifting visibility zones. European third-party logistics providers lease these under hardware-software subscription models to spread costs across operating budgets. Seasonal volume fluctuations drive preference for reconfigurable infrastructure without permanent modification.
- Permanent Installation:Factory-integrated camera architectures specified for new forklift procurement.
- Temporary Installation:Short-term rental arrangements for project-based material handling needs.
Fixed Installation retains the largest cumulative deployment base. Portable Installation is gaining share fastest as subscription procurement displaces traditional capital expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forklift camera systems originated in European maritime and industrial safety engineering, with Dutch and German manufacturers pioneering ruggedized vision systems for harsh environments before warehouse adoption accelerated in the 2010s.
United States
OSHA powered industrial truck standards mandate operator visibility safeguards that drive retrofit demand across legacy forklift fleets. Distribution centers near Chicago and Atlanta deploy rearview systems to achieve compliance without equipment replacement. Third-party logistics providers in these corridors specify bundled hardware-software subscriptions to spread costs across operating budgets.
Germany
Automated warehousing corridors in e-commerce fulfillment networks require real-time visual verification for autonomous navigation systems. EMA good manufacturing practice guidelines create compliance pull across pharmaceutical distribution networks. Facilities near Düsseldorf and Hamburg specify 360-degree camera arrays with stitched-image processing for narrow-aisle automation at scale.
China
High-definition digital systems integrate with warehouse management platforms in automated logistics hubs. GB standards for industrial equipment safety shape procurement specifications for domestic and export-bound manufacturers. Yangtze River Delta distribution clusters near Shanghai deploy camera networks to enable dense rack automation with minimal pedestrian exposure.
Japan
METI industrial safety frameworks mandate documented visibility assessments for powered industrial trucks in pharmaceutical distribution. Compliance officers require timestamped video archives spanning ninety days. Kanto region facilities around Tokyo specify cameras with embedded solid-state storage and automated upload protocols to satisfy audit requirements.
India
The PLI scheme for warehousing infrastructure creates subsidy pathways for safety equipment procurement in emerging distribution hubs. CDSCO facility requirements for pharmaceutical cold chain operations shape stainless-steel housing specifications. Logistics modernization near Mumbai and Delhi drives demand for modular camera kits with wireless transmitters and magnetic mounts.
Forklift Camera Systems Market Competitive Landscape
The competitive structure tilts toward specialized vision technology providers with heritage in adjacent ruggedized applications. Three archetypes occupy distinct positions: marine-grade sealing specialists leveraging outdoor durability credentials, integrated monitor-and-camera bundlers serving mid-size fleet operators, and automotive-grade image processing vendors adapting low-light algorithms for warehouse environments. Dominant competitive moves include portfolio diversification into fleet telematics integration and geographic expansion through distribution partnerships in Asian logistics corridors.
Among European heritage specialists, Orlaco occupies a position exemplifying marine-grade engineering translation into cold-storage applications. STONKAM anchors the integrated bundle tier for mid-size logistics operators. Bosch represents automotive-grade image processing adaptation for industrial vision requirements. These three entities collectively illustrate how technical lineage from adjacent sectors shapes competitive positioning in warehouse safety systems.
| Leading Market Players |
|---|
| Orlaco |
| STONKAM |
| TVH |
| Bosch |
| Brigade Electronics |
| Spillard Safety Systems |
| Rosco |
| SharpEagle Technology |
| Rear View Safety |
| Others |
Pricing and Supply Chain Analysis
Image sensor wafer pricing indices cascade through forklift camera system supply chains, compressing margins at the economy tier while marine-grade sealing specifications sustain premium positioning in cold-storage applications. Buyers in United States distribution centers face escalating procurement complexity as semiconductor input volatility intersects with OSHA compliance deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns, with ISO 26262 functional safety certification and marine-grade IP69K sealing ratings as the primary price differentiation drivers. Cost compression in economy-tier analog retrofit kits is intensifying because legacy fleet operators prioritize rapid OSHA compliance over feature depth. Third-party logistics providers managing seasonal volume fluctuations exhibit the highest price sensitivity, while pharmaceutical cold chain operators demonstrate minimal elasticity due to FDA sanitation mandates.
Supply Chain Analysis
Automotive-grade image sensor qualification gates access to tier-one OEM supply relationships, with fabrication concentrated in Taiwan, South Korea, and Japan. Supply chains draw from CMOS wafer foundries, marine-grade aluminum housing suppliers, and CAN bus integration module manufacturers. Single-source vulnerability in automotive-grade sensor fabrication exposes camera assemblers to extended allocation periods. Distribution runs through industrial safety equipment distributors and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with OSHA powered industrial truck standards creating recurring retrofit demand cycles that extend equipment replacement timelines across United States warehousing infrastructure.
For Market Incumbents: Cement market position through backward integration into image sensor procurement agreements with Taiwanese foundries, insulating against allocation volatility that threatens mid-tier competitors. Deepen fleet telematics integration capabilities to capture premium positioning as warehouse management software convergence becomes the decisive procurement criterion. Defensive patenting around AI-enabled edge inference algorithms blocks emerging entrants from collision avoidance feature parity. For New Entrants and Emerging Players: Enter via India's PLI-subsidized warehousing modernization corridor, where Mumbai and Delhi distribution hub construction creates greenfield installation demand without legacy analog infrastructure displacement costs. Target portable wireless camera kits with magnetic mounts for European third-party logistics providers adopting subscription procurement models. Lead with hardware-software bundling that spreads capital expenditure across operating budgets. For Investors and Strategic Acquirers: Asymmetric upside sits with marine-grade sealing specialists possessing transferable IP from adjacent offshore and cold-chain applications, as pharmaceutical distribution networks expand temperature-controlled infrastructure. Five-to-ten year viability hinges on telematics platform integration depth rather than standalone camera hardware margins. Monitor METI audit requirement expansions across Japanese pharmaceutical distribution as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Telematics Platform Integration | Captures premium positioning as warehouse management software convergence reshapes procurement criteria beyond standalone video functionality. |
| Automotive-Grade Image Sensor Supply Agreement | Secures allocation priority from Taiwanese and South Korean foundries amid semiconductor input volatility. |
| AI Edge Inference Capability Development | Transforms passive recording systems into active collision avoidance platforms with pedestrian recognition algorithms. |
| Wireless Transmission Hardware Miniaturization | Eliminates cable fatigue failures in high-cycle reach truck operations where mast flexing degrades wired connections. |
| Pharmaceutical Cold Chain Certification Investment | Opens specialized demand for stainless-steel enclosures meeting FDA facility sanitation requirements in temperature-controlled distribution. |
Research Methodology
Direct dialogue with fleet safety managers, warehouse operations directors, OEM procurement teams, and aftermarket service heads grounded qualitative findings in operational reality across United States, German, and Chinese logistics corridors. Secondary validation drew from OSHA enforcement data, EMA good manufacturing practice guidance documents, METI industrial safety framework publications, and customs trade records for industrial vision equipment. Bottom-up unit deployment estimates triangulated against top-down addressable fleet calculations.
Bottom-up modeling aggregated installed base estimates by forklift class and retrofit penetration rates across product type, technology, and installation type segments. Top-down validation cross-referenced regulatory compliance timelines against fleet age distributions. CAGRs derived from regression analysis of historical deployment velocity correlated with OSHA citation frequency and e-commerce fulfillment center construction permits. Forecast inputs incorporated semiconductor supply lead time volatility and warehouse automation capital expenditure cycles.
Inputs from regulatory filing databases and fleet operator interviews were available through the study window; gaps in real-time OEM procurement pipeline visibility introduce uncertainty bands around near-term deployment velocity. Forecasts reflect documented assumptions regarding OSHA enforcement intensity and e-commerce fulfillment network expansion trajectories. A model refresh is warranted upon material change in automotive-grade image sensor allocation protocols or METI audit requirement scope expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market