
 Thailand Metal Packaging Market | 2026-2036
Thailand Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Metal Packaging Market Analytics
Lightweighting in aluminum can body stock is tilting Thai converter investments toward thinner-gauge, higher-strength alloys. Bangkok Can Manufacturing Co., Ltd. leverages its proximity to ThaiBev and Singha bottling networks to dominate regional two-piece can supply. Toyo Seikan Group Holdings, Ltd. sustains technology leadership through advanced DWI (drawn-and-wall-ironed) line installations at its Thai facilities. Crown Holdings, Inc. anchors beverage can demand through long-term supply agreements with carbonated soft drink multinationals operating in Greater Bangkok.
Thailand metal packaging comprises rigid containers fabricated from aluminum, steel, tinplate, or copper alloys through processes including deep drawing, three-piece welding, and DWI forming, engineered to provide barrier protection against oxygen, light, and mechanical damage for shelf-stable goods. Cans command the largest product volume pool, driven by ASEAN beverage export demand and domestic consumption growth, while aluminum as a material category captures premium margin pools due to its infinite recyclability and lower transport cost per unit. Food & Beverage end users absorb the majority of sheet and container output, with pharmaceutical blister and tube applications representing a higher-specification, slower-growing niche.
Thailand's FDA enforces food-contact material safety standards that mandate migration testing for epoxy and polyester can coatings, while the Ministry of Industry's Thailand Industrial Standards Institute certifies tinplate and TFS sheet specifications under TIS standards. Board of Investment privileges for packaging sector investments in the Eastern Economic Corridor reduce import dependence for cansheet and cap stock. Stakeholders must monitor evolving extended producer responsibility frameworks and aluminum scrap purity requirements that will reshape sourcing economics and converter capex priorities.
Market Dynamics
Thailand's metal packaging sector is restructuring around aluminum cansheet localization as Board of Investment incentives draw capital toward Eastern Economic Corridor smelter and rolling mill investments, compressing import dependence while tightening supply chain control.
Growth Catalysts
- BOI Zone Privileges:Tax holidays and machinery import duty exemptions for packaging investments in the Eastern Economic Corridor accelerate domestic cansheet production capacity.
- Thai FDA Recycling Mandates:Tighter post-consumer aluminum recovery requirements push beverage brands toward infinitely recyclable formats over glass and PET alternatives.
- DWI Line Modernization:Drawn-and-wall-ironed forming technology upgrades at Thai facilities reduce material throughput per can while strengthening sidewall integrity.
Market Restraints
- Primary Aluminum Price Volatility:London Metal Exchange ingot pricing swings transmit directly into can body stock input costs, squeezing converter margin stability.
- Coating Chemical Import Dependence:Epoxy and polyester can lining formulations rely on specialty chemical suppliers concentrated in Northeast Asian production hubs.
- Tinplate Substitution Ceiling:Steel-based three-piece can formats retain cost advantage in low-acid food segments, capping aluminum penetration in traditional preserves packaging.
Strategic Opportunities
- ASEAN Export Corridor Expansion:Thai-produced two-piece beverage cans serve under-supplied neighboring markets in Cambodia, Laos, Myanmar, and Vietnam with shorter lead times than Chinese or Korean sources.
- Pharmaceutical Blister Specification Upgrades:Cold-form aluminum foil demand accelerates as Thai generic drug manufacturers pursue EU-GMP and US FDA facility certifications.
- Extended Producer Responsibility Pre-Positioning:Early compliance infrastructure for anticipated national packaging waste frameworks secures preferred supplier status with multinational FMCG procurement teams.
Industry Challenges
- High-Strength Alloy Metallurgy Talent Scarcity:Thin-gauge can body stock production requires specialized rolling mill engineers and quality control chemists in short supply across Thai technical institutes.
- Legacy Three-Piece Welding Line Stranding:Food can converters face capital allocation dilemmas between maintaining tinplate soldering capacity and accelerating DWI conversion timelines.
- Coating Migration Testing Bottlenecks:Thai FDA food-contact certification queues create 4-6 month delays for new internal lining formulations, slowing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Metal Packaging Market |
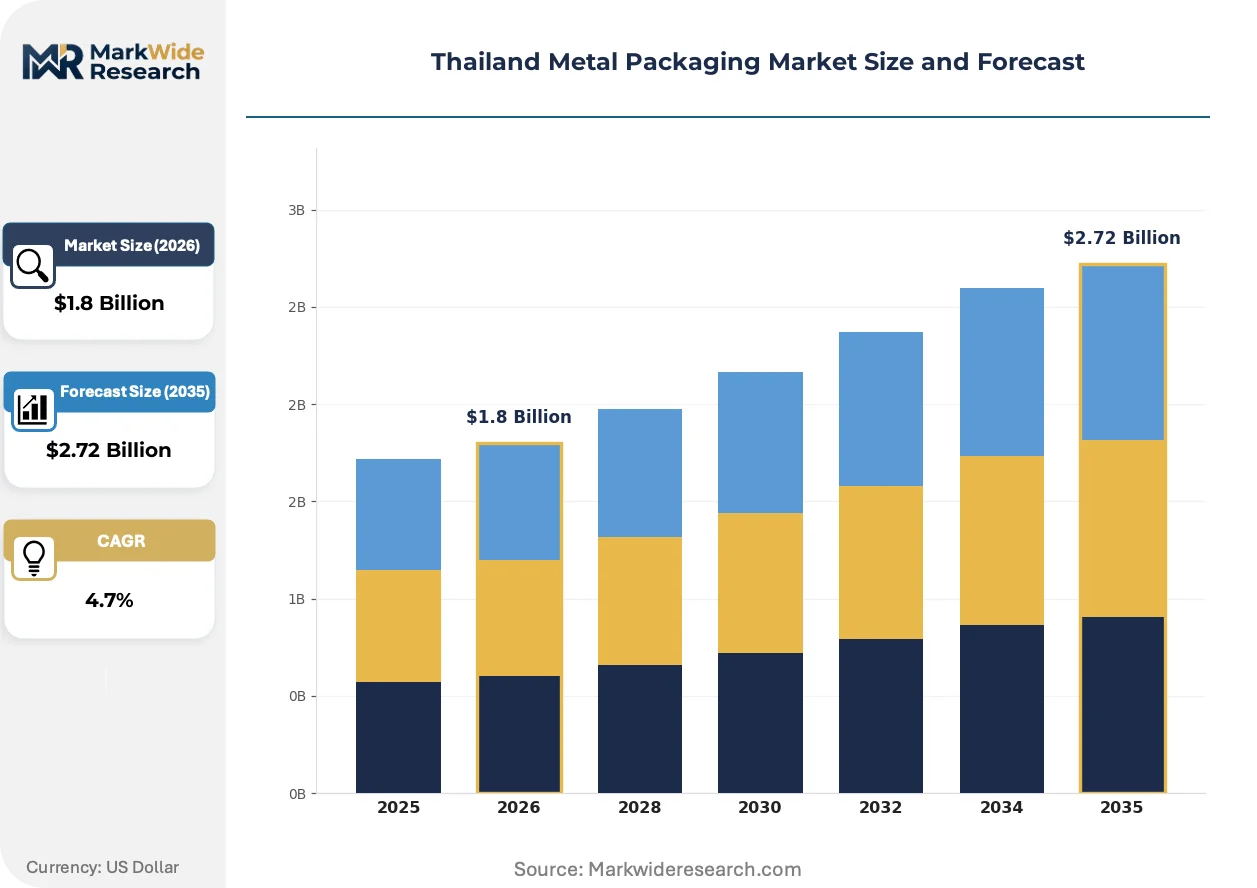
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Sheets, Caps, Containers End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Material: Aluminum, Steel, Tin, Copper Application: Packaging Solutions, Storage, Transportation, Disposal |
| Companies Covered | Toyo Seikan Group Holdings, Ltd., Bangkok Can Manufacturing Co., Ltd., ALUCON Public Company Limited, Lohakij Rung Charoen Sub Co., Ltd., Swan Industries (Thailand) Co., Ltd., Crown Holdings, Inc., Thai Beverage Can Co., Ltd., Next Can Innovation Co., Ltd., Ball Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Metal Packaging Market Evolving Landscape
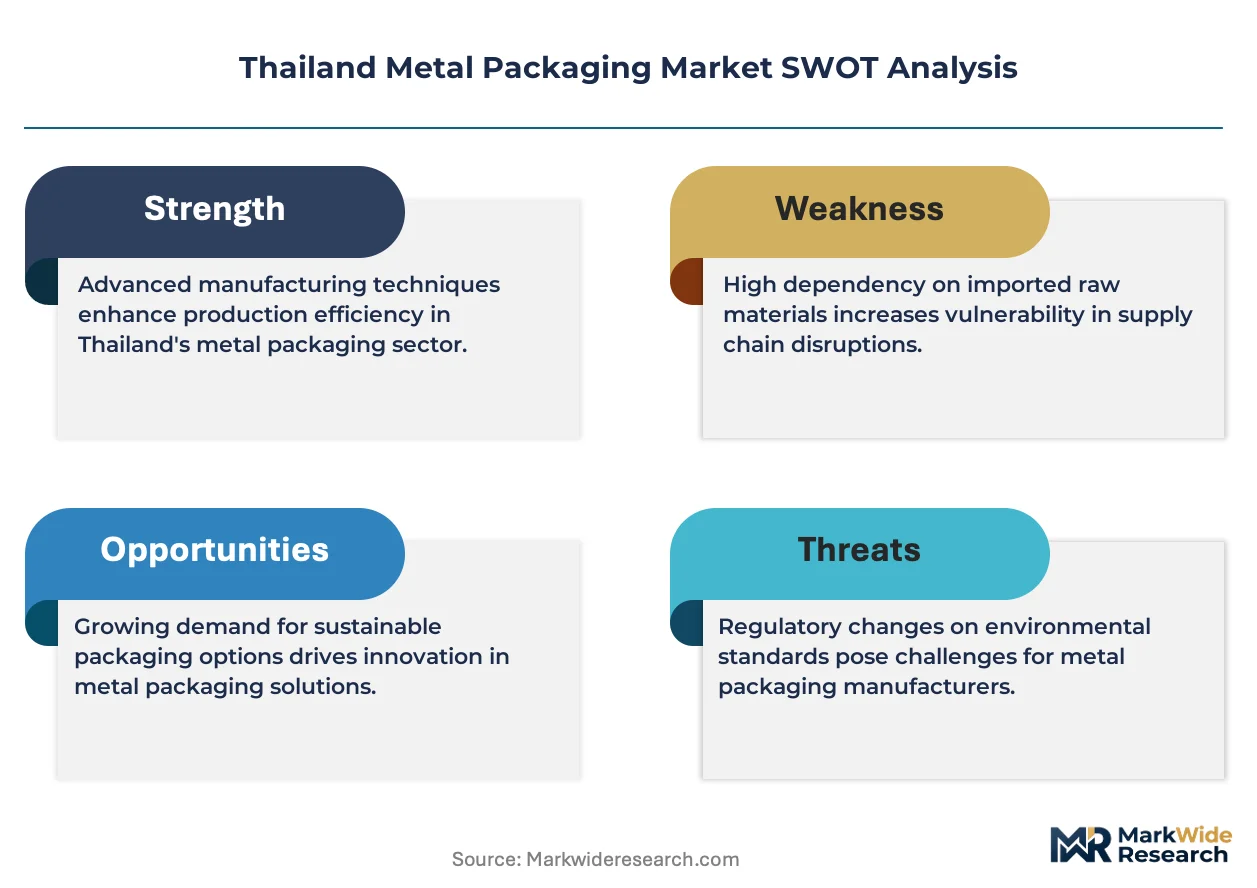
Material science advances and regulatory pressure are converging to transform Thai metal packaging from commodity container supply toward engineered barrier solutions with embedded sustainability credentials.
Sub-250 micron aluminum can body stock is collapsing the traditional gauge floor that governed Thai converter economics for two decades. Energy drink and beer bottlers in Greater Bangkok are specifying these thinner substrates at scale for 2024-2025 line retrofits. The technology is collapsing transport cost per thousand units and enabling lightweighting claims that resonate with multinational brand sustainability scorecards.
Thailand's FDA has tightened food-contact material safety standards mandating comprehensive migration testing for BPA-non-intent epoxy alternatives and polyester-based can coatings. Industrial consequence includes reformulation timelines extending 8-12 months for established suppliers while opening qualification windows for Japanese and European coating technology licensors. Beverage can segments with acidic contents face the steepest compliance ramps, driving accelerated partnership discussions between Thai fillers and certified coating compounders.
Direct procurement relationships between ThaiBev, Singha, and regional can converters are displacing traditional distributor-mediated sheet and container purchasing. This disintermediation concentrates volume commitments with Bangkok Can Manufacturing and Toyo Seikan Thai facilities while marginalizing smaller trading houses. The pattern is most visible in carbonated soft drink and energy drink verticals where annual volume guarantees now anchor multi-year supply agreements with indexed aluminum pricing mechanisms.
Thailand Metal Packaging Market Segmentation
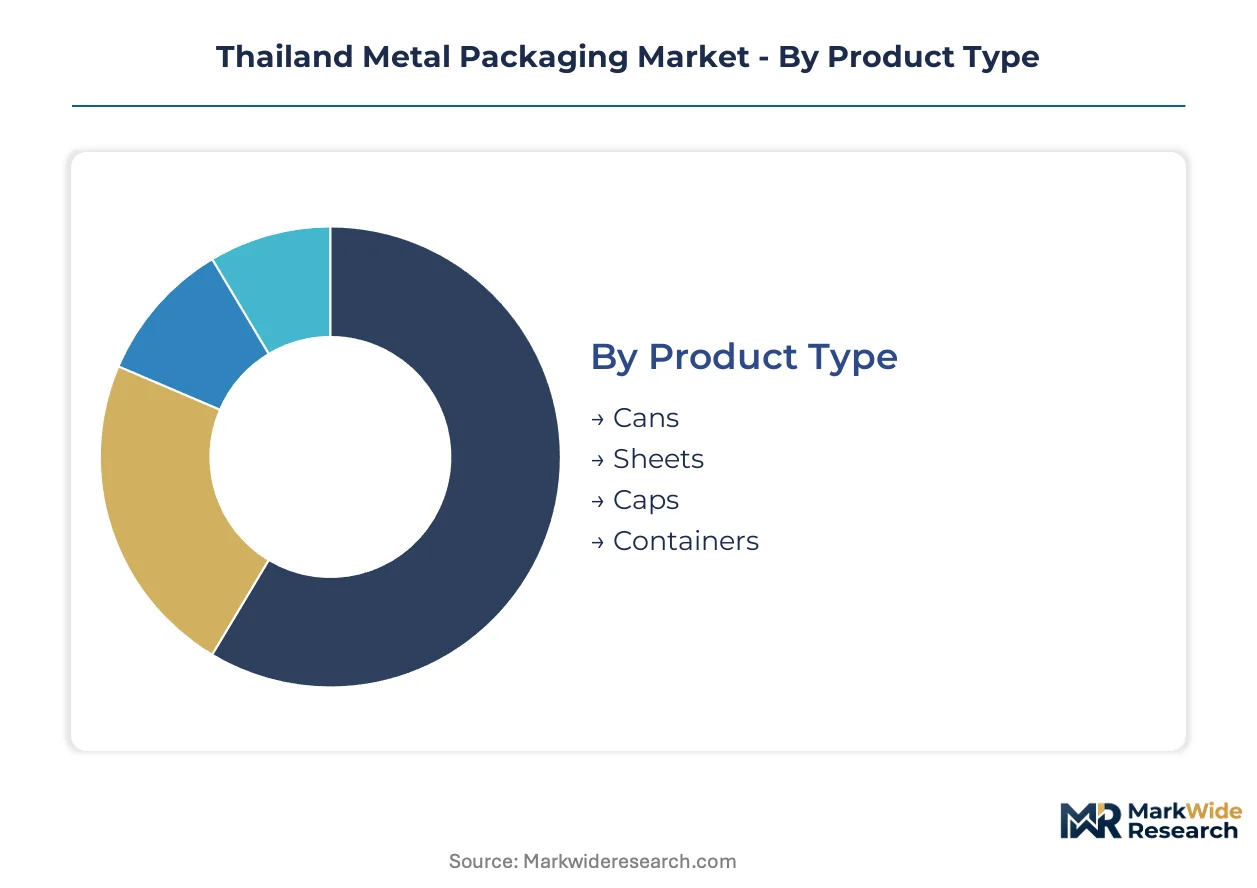
Thai metal packaging demand fragments across material specifications and end-use requirements that dictate barrier performance, recyclability credentials, and regulatory compliance intensity. Each segmentation dimension reveals distinct margin structures and investment priorities for converters operating within Board of Investment incentive zones.
Product Type:
Volume concentration and value capture diverge sharply across container formats, with beverage-facing formats pulling premium pricing through DWI technology investments.
- Cans:Two-piece aluminum beverage cans dominate Thai converter output through DWI forming lines concentrated in Eastern Economic Corridor facilities. ThaiBev and Singha bottling networks in Greater Bangkok anchor demand for slim and standard formats, with energy drink specifications driving sub-250 micron gauge adoption.
- Sheets:Cansheet and cap stock in H19 and H39 alloys constitute the upstream material flow feeding downstream forming operations. Local rolling mill investments are compressing import dependence from Korean and Japanese primary metal sources.
- Caps:Crown cork and screw cap formats serve carbonated soft drink and beer closures with lower capital intensity than body stock production. Specifications cluster around standard 26mm and 29mm diameters with epoxy-phenolic lining compliance.
- Containers:Three-piece welded food cans retain cost advantage in low-acid preserves segments, though aluminum substitution is eroding share in premium seafood and ready-meal applications.
Cans command the established base. The steepest expansion runs through sheet localization as domestic rolling capacity scales.
End User:
Application-specific barrier requirements and regulatory exposure create tiered margin pools across consumer-facing industries.
- Food & Beverage:Absorbs the majority of Thai metal packaging volume through carbonated drinks, beer, energy drinks, processed seafood, and ready-meal formats. Thai FDA food-contact certification mandates and extended producer responsibility frameworks are reshaping supplier qualification protocols.
- Pharmaceuticals:Cold-form aluminum foil for blister packs and tube laminates commands specification premiums as Thai generic manufacturers pursue EU-GMP and US FDA facility certifications. Migration testing requirements for direct drug contact materials extend qualification timelines.
- Personal Care:Aerosol cans and collapsible tubes for cosmetics and toiletries represent stable demand with lower growth velocity than beverage segments. Aluminum monobloc formats dominate premium positioning.
- Household Products:Insecticide and cleaning product aerosols utilize tinplate and aluminum combinations with corrosion-resistant internal coatings. Volume scales with rural distribution network expansion.
Food & Beverage absorbs the volume base. Pharmaceuticals is climbing the fastest through certification-driven specification upgrades.
Material:
Recyclability economics and strength-to-weight ratios are rebalancing material selection across Thai converter investments.
- Aluminum:Infinite recyclability and lower transport cost per unit have positioned aluminum as the priority material for Board of Investment incentive targeting. Cansheet demand from Greater Bangkok bottlers is accelerating domestic smelter and rolling mill partnerships.
- Steel:Tinplate and TFS (tin-free steel) retain cost advantage in three-piece food can segments where acid resistance and solderability remain critical. Thailand Industrial Standards Institute certification under TIS standards governs sheet specifications.
- Tin:Electrolytic tin coating applications concentrate in traditional preserves packaging with declining share as aluminum substitution advances. Legacy soldering line maintenance costs are stranding capital for converters.
- Copper:Limited to specialized pharmaceutical tube and high-barrier laminate applications where antimicrobial properties justify material premiums. Volume remains constrained by raw material cost volatility.
Steel retains the installed base. Aluminum is gaining share fastest through beverage format conversion and sustainability credentialing.
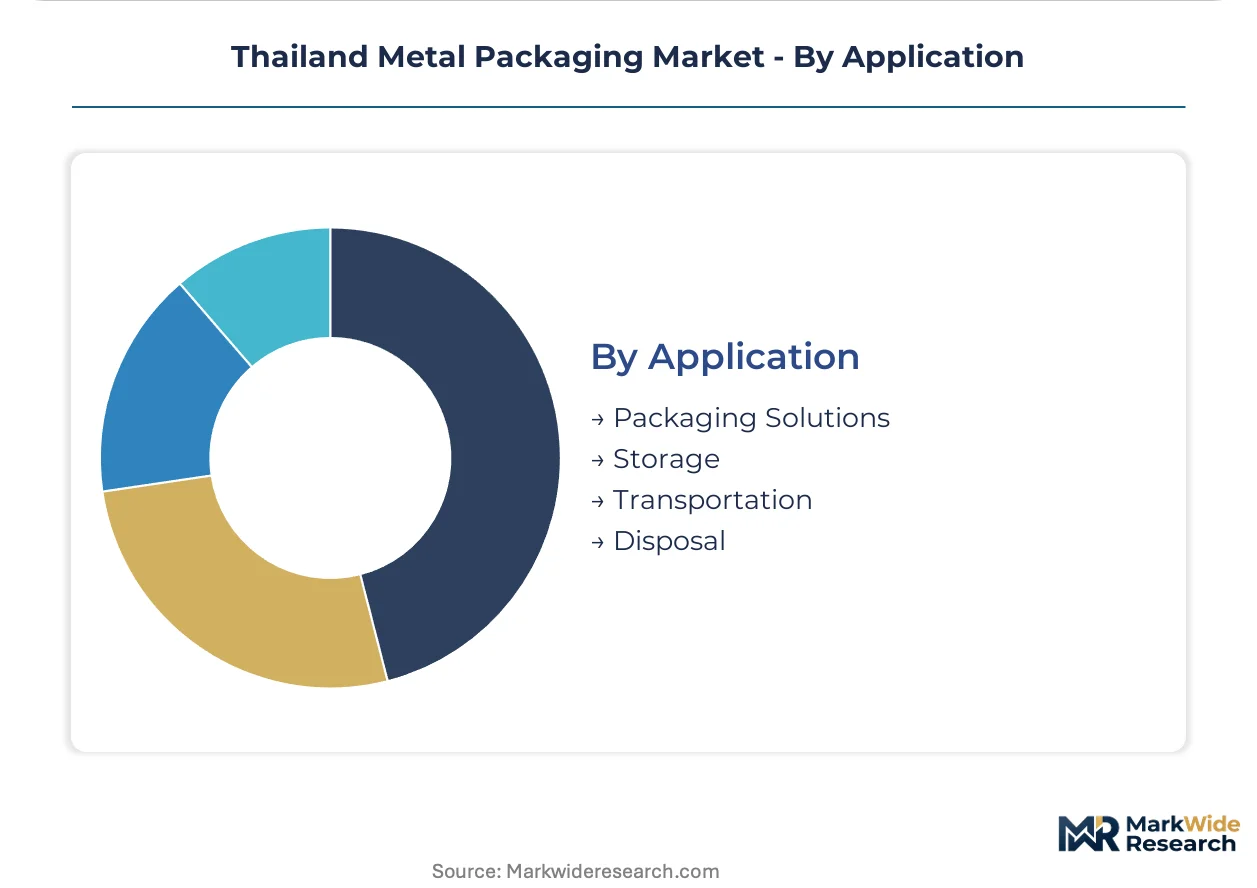
Application:
Functional role in the value chain determines specification intensity and customer relationship durability for Thai suppliers.
- Packaging Solutions:Primary containment function with direct food or beverage contact drives the most stringent Thai FDA migration testing and coating compliance requirements. Direct procurement relationships between fillers and converters are displacing distributor channels.
- Storage:Industrial and institutional bulk containers for ingredients and intermediates prioritize cost efficiency over consumer-facing aesthetics. Specification flexibility allows steel retention where aluminum would be cost-prohibitive.
- Transportation:Intermediate bulk containers and drum formats for chemical and food ingredient logistics leverage steel durability for multi-trip reuse cycles. Eastern Economic Corridor port access concentrates demand.
- Disposal:Single-use formats with minimal recovery infrastructure face tightening extended producer responsibility mandates. Aluminum formats benefit from established scrap collection networks relative to mixed-material alternatives.
Packaging Solutions anchors revenue concentration. Disposal is expanding most quickly through regulatory pressure on post-consumer recovery rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai beverage bottlers and food processors concentrate procurement authority within Greater Bangkok and the Eastern Economic Corridor, where direct converter relationships displace traditional distributor channels. This buyer archetype clustering shapes capacity location decisions across ASEAN supply networks.
Greater Bangkok
ThaiBev and Singha bottling networks anchor aluminum can demand through multi-year supply agreements with indexed pricing mechanisms. Thai FDA food-contact certification mandates for migration testing concentrate compliance expertise in metropolitan laboratories. Samut Prakan and Pathum Thani provinces host DWI forming lines serving carbonated soft drink and energy drink verticals.
Eastern Economic Corridor
Board of Investment tax holidays and machinery import duty exemptions draw rolling mill investments toward Rayong and Chonburi provinces. Domestic cansheet production capacity compresses import dependence from Korean and Japanese metal sources. Port access at Laem Chabang enables two-piece beverage can exports to Cambodia, Laos, Myanmar, and Vietnam.
Central Plains
Three-piece welded food can converters retain tinplate soldering capacity for low-acid preserves segments where steel cost advantage persists. Thailand Industrial Standards Institute certification queues for TIS-compliant sheet specifications create regional specialization in traditional seafood and ready-meal packaging. Ayutthaya and Saraburi host legacy can manufacturing serving rural distribution networks.
Northern Region
Pharmaceutical blister foil demand from generic drug manufacturers accelerates cold-form aluminum specification upgrades. EU-GMP and US FDA facility certifications drive migration testing requirements for direct drug contact materials. Chiang Mai and Lampang concentrate higher-specification, slower-growing niche applications.
Southern Peninsula
Seafood processing clusters in Songkhla and Surat Thani generate demand for corrosion-resistant internal coatings in premium packaging applications. Extended producer responsibility frameworks for post-consumer aluminum recovery reshape sourcing economics. Regional converters face capital allocation dilemmas between tinplate maintenance and DWI conversion timelines.
Thailand Metal Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships in Thai metal packaging. Bangkok Can Manufacturing and Toyo Seikan Thai facilities anchor volume concentration through direct procurement ties to major beverage bottlers. Three strategic archetypes dominate: integrated converters with captive sheet supply, technology licensors with advanced DWI line installations, and regional specialists serving ASEAN export corridors. Competitive moves center on capacity expansion in Eastern Economic Corridor zones and strategic partnerships for coating compound qualification.
Among Thailand-based fabricators, Bangkok Can Manufacturing Co., Ltd. and Thai Beverage Can Co., Ltd. represent integrated converter archetypes with proximity advantages to domestic bottling networks. Toyo Seikan Group Holdings, Ltd. occupies a technology-licensor position exemplifying advanced forming capabilities. Crown Holdings, Inc. anchors multinational supply relationships serving carbonated soft drink brands operating across Greater Bangkok. These three named entities illustrate the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Toyo Seikan Group Holdings, Ltd. |
| Bangkok Can Manufacturing Co., Ltd. |
| ALUCON Public Company Limited |
| Lohakij Rung Charoen Sub Co., Ltd. |
| Swan Industries (Thailand) Co., Ltd. |
| Crown Holdings, Inc. |
| Thai Beverage Can Co., Ltd. |
| Next Can Innovation Co., Ltd. |
| Ball Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Korean and Japanese cansheet rolling mills exerts downward pressure on Thai converter input costs while simultaneously compressing margin recovery for domestic suppliers investing in Eastern Economic Corridor localization. This utilization asymmetry between regional metal sources and emerging Thai capacity shapes converter procurement strategies and pricing postures across beverage and food packaging segments.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum ingot indexation dominate Thai cansheet procurement between Greater Bangkok bottlers and Eastern Economic Corridor rolling mills. Price differentiation rests on volume scale and Thai FDA food-contact certification tier, with migration-tested coating compliance commanding premiums over standard formulations. Pricing pressure stems from primary aluminum volatility transmitting directly into body stock input costs. Small-scale food can converters exhibit highest price sensitivity due to tinplate substitution ceilings, while energy drink bottlers anchored to multi-year supply agreements show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from ThaiBev and Singha bottling networks strain converter working capital, prompting supply-chain finance facilities backed by Eastern Economic Corridor Board of Investment privileges. Geographic concentration draws from South Korean, Japanese, and emerging Thai primary metal sources. Raw material dependencies center on LME-grade aluminum ingot, epoxy-phenolic coating compounds, and H19/H39 alloy specifications. Single-source vulnerability concentrates in specialty chemical imports for BPA-non-intent lining formulations. Distribution runs through direct procurement relationships displacing traditional distributor channels across Greater Bangkok bottling networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thai metal packaging is transitioning toward a service-attach model where coating compound qualification support and migration testing advisory layers expand faster than commodity can body stock supply. Technical service contracts tied to Thai FDA compliance timelines now generate recurring revenue streams exceeding per-unit container margins for integrated converters.
For Market Incumbents: Harden supply chain control through backward integration into Eastern Economic Corridor cansheet production while accelerating DWI line conversion timelines before tinplate soldering capacity strands legacy food can assets. Threat substitution from PET and aseptic carton formats in beverage segments demands defensive certification investment in extended producer responsibility infrastructure. Vertical integration into coating compound formulation reduces Thai FDA queue exposure. For New Entrants and Emerging Players: Mid-tier pharmaceutical blister foil specifications for Thai generic manufacturers pursuing EU-GMP certification represent the most penetrable entry point given incumbent concentration in beverage can volume. ASEAN export corridors into Cambodia, Laos, Myanmar, and Vietnam offer secondary white-space with shorter lead time advantages over Northeast Asian sources. Go-to-market positioning should emphasize cold-form aluminum foil migration testing expertise as a qualification accelerator. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with captive coating compound partnerships and Thai FDA certification advisory services. Five-to-ten year viability favors integrated players with Eastern Economic Corridor capacity and direct procurement ties to multinational FMCG procurement teams. Signal to watch: Board of Investment incentive renewal timelines and aluminum scrap purity mandate implementation schedules as inflection indicators for localization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cansheet Production | Captive H19 alloy supply from Rayong rolling mills reduces Korean import dependence for Bangkok Can Manufacturing. |
| DWI Line Modernization | Sub-250 micron gauge capability at Toyo Seikan Thai facilities collapses transport cost per thousand units for energy drink bottlers. |
| Coating Compound Qualification Partnership | Japanese epoxy technology licensing accelerates Thai FDA migration testing timelines for acidic beverage applications. |
| Extended Producer Responsibility Infrastructure | Post-consumer aluminum recovery compliance secures preferred supplier status with Singha and ThaiBev procurement teams. |
| ASEAN Export Corridor Expansion | Laem Chabang port access enables two-piece beverage can shipments to under-supplied Myanmar and Cambodia markets. |
Research Methodology
A standing panel of rolling mill operations directors, Thai FDA compliance officers, beverage procurement managers at Singha and ThaiBev, coating compound technical directors, and Eastern Economic Corridor investment promotion specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from Thailand Industrial Standards Institute TIS certification databases, Board of Investment incentive disclosure filings, London Metal Exchange aluminum price series, and Thai FDA food-contact material safety standards. Bottom-up volume modeling across converter capacity installations triangulated with top-down macroeconomic consumption projections.
Scenario-bracketing around primary aluminum price volatility bands and Thai FDA regulatory implementation timelines bounded forecast outputs across the analysis window. Segmentation dimensions modeled include material specification tier, end-use industry vertical, container format technology, and geographic production cluster within Thailand. CAGRs were derived from installed capacity utilization trajectories and demand elasticity estimates specific to beverage can substitution patterns. Industry-specific inputs incorporated DWI line conversion schedules and extended producer responsibility framework adoption curves.
Macroeconomic conditions sit as an overlay; deviation in Thai baht exchange rates against the US dollar and London Metal Exchange aluminum ingot pricing would shift the trajectory of import-dependent converter economics. Forecasts reflect assumptions regarding Board of Investment incentive continuity and Thai FDA migration testing queue durations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Metal Drums Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Tin Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
Metal Pails Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
India Metal Packaging Market