
 Global Metal Print Packaging Market | 2026-2036
Global Metal Print Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Print Packaging Market Foresight
Modular beverage packaging is pivoting toward mixed-format SKUs that pair standard cans with slim and sleek variants within single product lines. Crown Holdings, Inc. leverages its integrated beverage can operations across multiple continents to supply these configurable formats. Ball Corporation anchors North American aluminum can supply through extensive domestic manufacturing infrastructure. Ardagh Group S.A. specializes in decorated metal packaging for premium beverage and food accounts, competing on design complexity and color fidelity.
Metal print packaging encompasses decorated aluminum and steel substrates formed into rigid containers, with wall gauges typically ranging from 0.007 to 0.012 inches and surface treatments including epoxy-phenolic or polyester coatings for ink adhesion and corrosion resistance. Its primary commercial purpose is to combine product protection with high-resolution brand communication on shelf-stable and refrigerated consumer goods. Beverage cans dominate volume within product type segments, while digital printing represents the fastest-expanding printing technology category as brands seek shorter run lengths and regional customization. Flexographic and offset lithography processes still occupy the majority of high-speed production lines for multinational accounts where margin pools concentrate at scale.
EPA guidelines in the United States govern volatile organic compound emissions from metal decorating operations, while REACH in Europe restricts hazardous substances in coating formulations and mandates recyclability documentation. China's SAMR enforces GB standards for food-contact metal packaging safety and labeling accuracy. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling targets as these regulations reshape material specifications and regional manufacturing investment decisions.
Market Dynamics
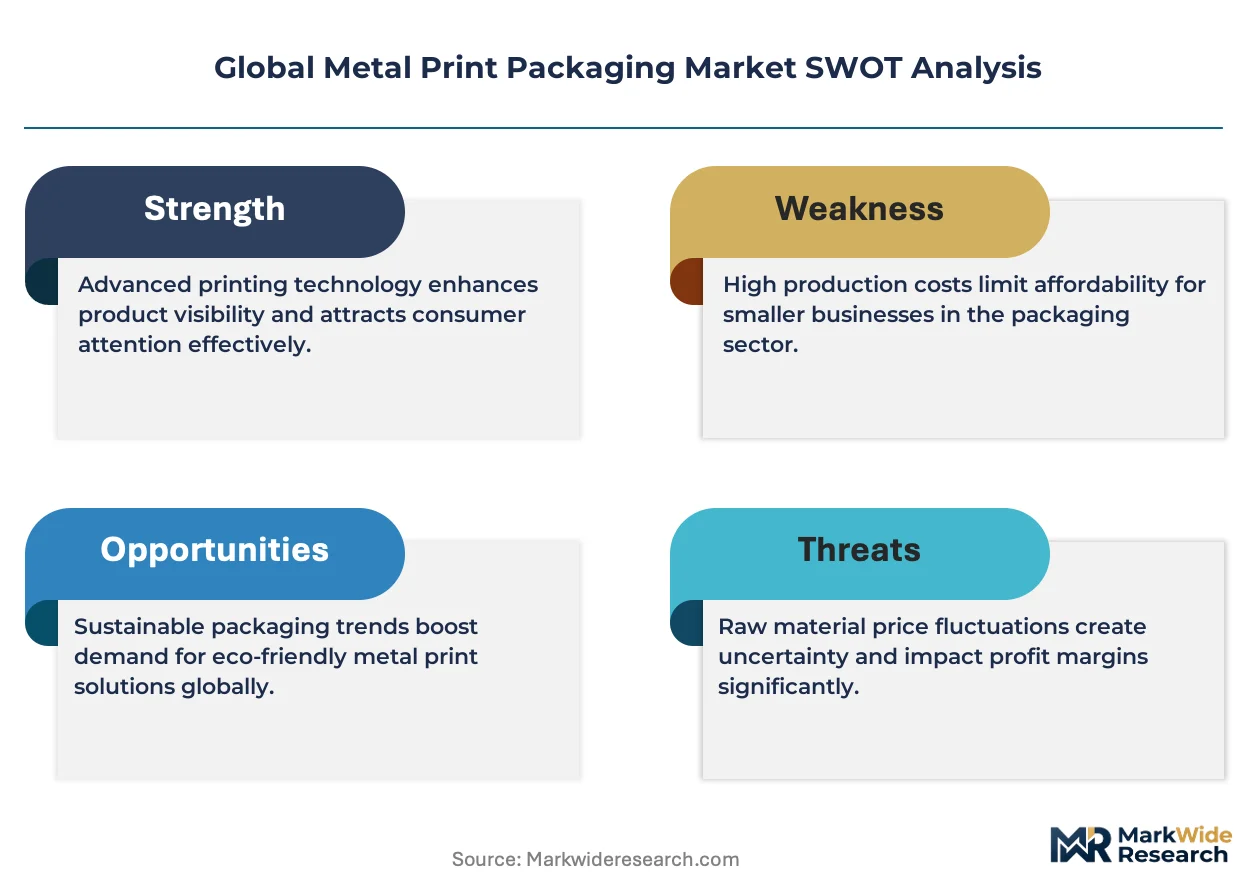
Aluminum substrate cost volatility and EU Green Deal carbon disclosure mandates are forcing simultaneous investment in lightweighting technology and renewable energy sourcing across metal decorating operations. Manufacturers must reconcile shorter run-length demand from beverage brands with the capital intensity of high-speed coating lines.
Growth Catalysts
- REACH recyclability documentation:European mandates for material circularity documentation accelerate closed-loop aluminum collection infrastructure investment. Metal packaging suppliers capture premium positioning through verified recycled content claims.
- Digital inkjet decoration:Variable-data printing enables regional SKU proliferation without plate-change downtime. Beverage marketers deploy hyper-localized campaigns on aluminum surfaces.
- China urban beverage consumption:Tier-1 and Tier-2 city demand for carbonated and alcoholic beverages drives domestic two-piece can manufacturing expansion. Local production capacity scales alongside consumption clusters.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings compress margin predictability for substrate-dependent converters. Hedging costs add operational overhead.
- Epoxy-phenolic coating supply concentration:Specialty resin production concentrates among limited chemical suppliers in Germany and Japan. Formulation availability constrains output during supply disruptions.
- Steel can substitution in food:Cost-sensitive processed food segments retain tinplate three-piece construction. Aluminum penetration faces incumbent equipment and supply chain lock-in.
Strategic Opportunities
- India beverage can underpenetration:Per-capita aluminum can consumption remains a fraction of developed-market levels. Domestic can manufacturing investments align with FSSAI food-contact safety modernization.
- UV-LED curing convergence:Energy-efficient curing technology reduces volatile organic compound emissions while enabling heat-sensitive substrate decoration. Regulatory compliance costs drop alongside energy consumption.
- Direct-to-brand digital platforms:E-commerce channels for short-run promotional cans bypass traditional distributor networks. Craft breweries and seasonal beverage launches access flexible decoration without minimum order thresholds.
Industry Challenges
- Decorating chemist talent scarcity:Specialized expertise in coating adhesion science and corrosion inhibition faces generational retirement. Technical training pipelines lag automation deployment.
- GB standard certification timelines:China's SAMR food-contact safety approvals require extended laboratory testing cycles. Product launch schedules stretch across quarters.
- Legacy press integration complexity:Retrofitting existing offset lithography lines with digital print heads demands mechanical and software synchronization. Downtime costs compound during hybrid system commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Print Packaging Market |
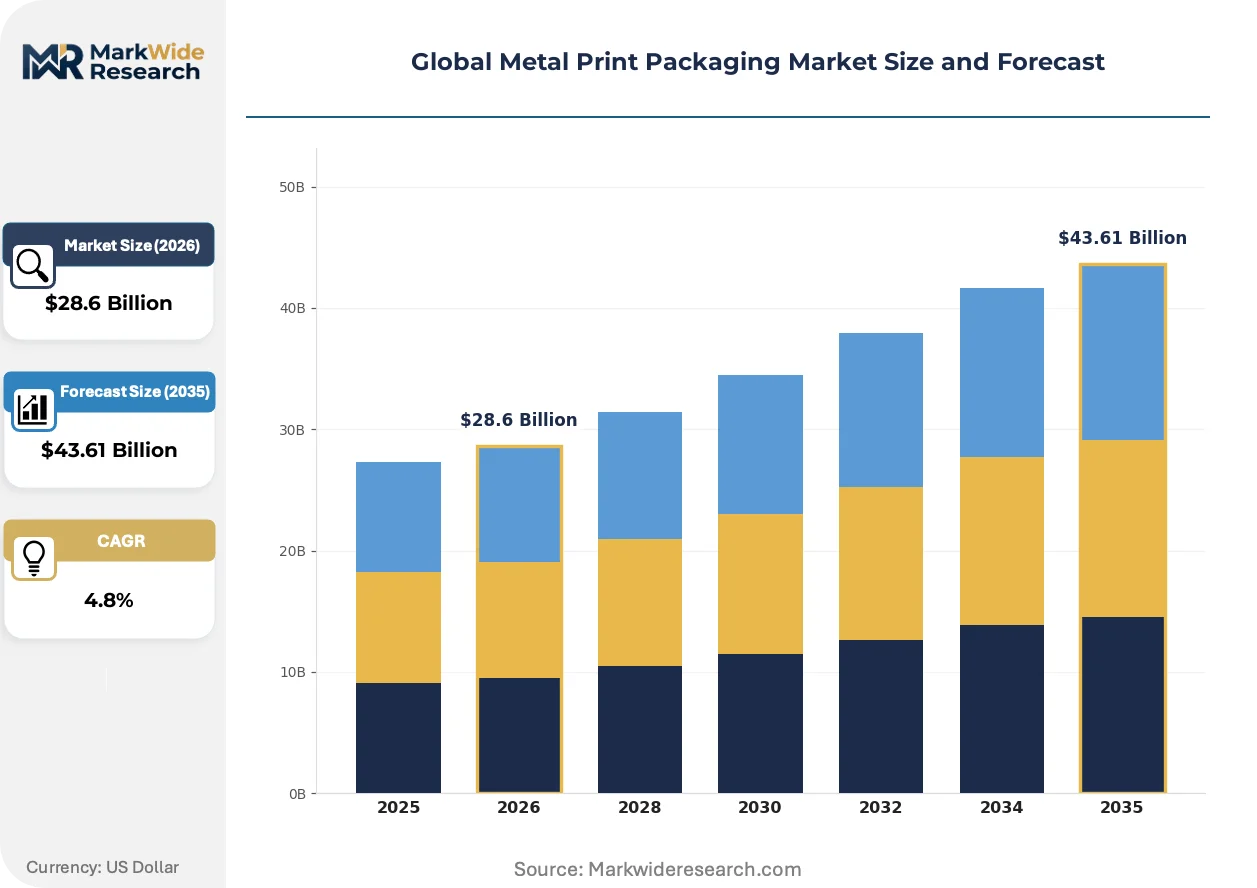
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Aerosol Containers, Food Containers, Beverage Cans Printing Technology: Flexographic, Offset Lithography, Digital Printing, Gravure, Screen Printing Application: Food & Beverages, Personal Care, Pharmaceutical, Household Chemicals, Industrial Goods End User: Manufacturers, Retail Brands, Contract Packers, Distributors, Advertising Agencies |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Ardagh Group S.A., Silgan Holdings Inc., CCL Industries Inc., Amcor plc, Sonoco Products Company, Toyo Seikan Group Holdings, Ltd., Can-Pack S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Print Packaging Market Shifts & Advancements
Active transformation across metal print packaging centers on three vectors: decoration technology enabling mass customization, regulatory pressure accelerating material circularity verification, and procurement behavior fragmenting order patterns toward micro-lots.
High-resolution digital inkjet systems are rewriting the economics of short-run aluminum decoration. Craft beverage portfolios and limited-edition consumer goods brands adopt these systems for sub-10,000-unit campaigns. The technology compresses minimum viable order thresholds while expanding SKU proliferation without plate inventory carrying costs.
EU Green Deal carbon footprint disclosure requirements and extended producer responsibility frameworks reshape substrate specification processes. Metal packaging converters invest in lifecycle assessment documentation and renewable energy certificates to meet retailer procurement criteria. Premium beverage segments in Germany and France now mandate supplier climate data as a condition of contract renewal.
Beverage brand procurement teams fragment volume across multiple decorating suppliers to secure capacity flexibility and risk distribution. Long-term sole-source relationships give way to dual-qualified vendor structures with volume allocation shifting quarterly. This pattern concentrates among North American and Western European multinational accounts managing seasonal demand spikes.
Global Metal Print Packaging Market Segmentation
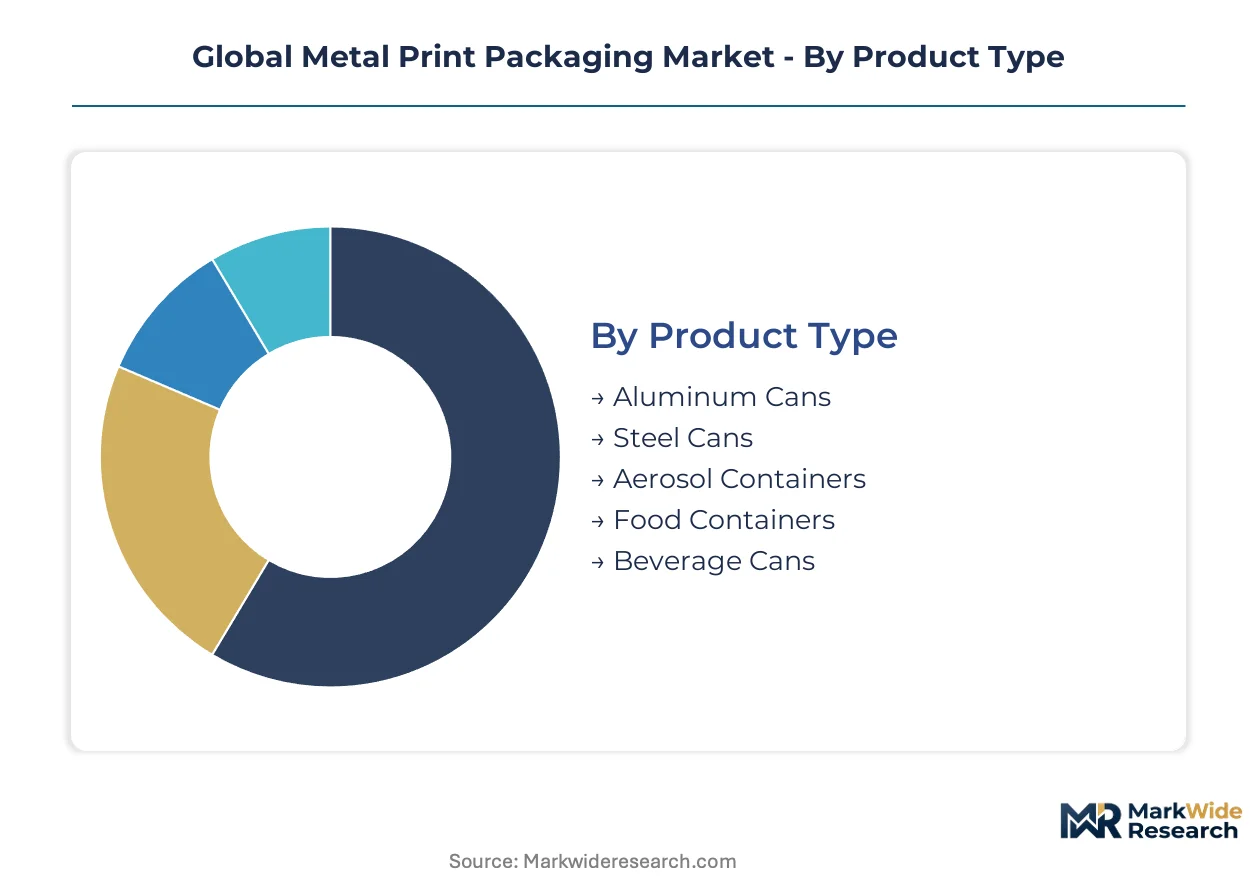
Metal print packaging segmentation reveals how substrate choices, decoration methods, and customer procurement patterns split value creation across fundamentally different operational models. Understanding these divisions exposes where capital intensity concentrates versus where flexibility premiums command pricing power.
Product Type:
Integration depth varies sharply across substrate formats, with some categories functioning as standalone consumer-facing units while others embed into multi-component systems.
- Beverage Cans:Two-piece aluminum construction with wall gauges of 0.007-0.009 inches and internal epoxy-phenolic liners dominates high-speed filling lines. Demand clusters in China's Tier-1 cities where carbonated and craft beer consumption drives domestic manufacturing expansion alongside urban beverage consumption growth.
- Aluminum Cans:Lightweight substrates with polyester or epoxy-phenolic surface treatments enable high-resolution brand communication on shelf-stable goods. European beverage brands under REACH and EU Green Deal mandates prioritize verified recycled content claims and carbon footprint disclosures in supplier selection.
- Steel Cans:Tinplate three-piece construction retains cost-sensitive processed food segments where incumbent equipment and supply chain lock-in slows aluminum substitution.
- Aerosol Containers:Pressurized aluminum or steel cylinders with specialized internal coatings withstand propellant chemical exposure.
- Food Containers:Rigid metal packaging for shelf-stable and refrigerated consumer goods combines corrosion resistance with decoration surface area.
Volume placements concentrate in Beverage Cans; the faster expansion belongs to Aluminum Cans as lightweighting mandates and recyclability documentation reshape procurement criteria.
Printing Technology:
Capital deployment patterns separate high-volume continuous processes from emerging systems enabling mass customization without plate inventory.
- Flexographic:Rotary relief printing with photopolymer plates operates at speeds exceeding 1,000 feet per minute on metal coil lines. Multinational beverage accounts in North America and Western Europe rely on this process for seasonal volume surges where margin pools concentrate at scale.
- Digital Printing:Piezoelectric inkjet heads deposit UV-curable or solvent-based inks without plate changes, compressing minimum order thresholds below 10,000 units. Craft breweries and limited-edition consumer goods brands deploy this technology for hyper-localized campaigns and regional SKU proliferation.
- Offset Lithography:Planographic printing with aluminum plates dominates long-run production for multinational accounts.
- Gravure:Intaglio cylinder engraving delivers premium image quality for high-end cosmetic and gift packaging applications.
- Screen Printing:Mesh stencil methods apply thick ink deposits for tactile effects and specialty coatings.
Production gravity sits with Flexographic systems; Digital Printing climbs the fastest as procurement teams fragment volume across multiple suppliers to secure capacity flexibility.
Application:
Regulatory exposure and shelf-life requirements create distinct specification ladders across end-use environments.
- Food & Beverages:Metal packaging for shelf-stable and refrigerated goods demands FDA, EFSA, or SAMR food-contact compliance depending on destination market. China's GB standards and FSSAI modernization in India reshape certification timelines and laboratory testing cycles for exporters.
- Personal Care:Aerosol and rigid container decoration for cosmetics and grooming products emphasizes color fidelity and tactile surface effects.
- Pharmaceutical:Child-resistant closures and tamper-evident features combine with serialization requirements for compliance.
- Household Chemicals:Corrosion-resistant internal coatings protect against aggressive cleaning formulations.
- Industrial Goods:Heavy-gauge metal packaging for lubricants and coatings prioritizes structural durability over decoration complexity.
Revenue concentration pools in Food & Beverages; Personal Care gains share fastest as premium cosmetic segments mandate supplier climate data under EU Green Deal procurement criteria.
End User:
Procurement sophistication and order pattern fragmentation distinguish direct manufacturing accounts from intermediary-dependent channels.
- Retail Brands:Multinational beverage and food companies manage seasonal demand spikes through dual-qualified vendor structures with quarterly volume allocation shifts. Long-term sole-source relationships give way to risk-distributed supplier portfolios across North American and Western European accounts.
- Contract Packers:Third-party filling and packaging operations aggregate demand across multiple brand owners, consolidating decoration procurement at regional scale.
- Manufacturers:Integrated producers of metal packaging substrates operate captive decoration lines for high-volume internal consumption.
- Distributors:Inventory-carrying intermediaries serve smaller brands without direct converter relationships.
- Advertising Agencies:Promotional and limited-edition campaign managers access short-run digital decoration through direct-to-brand e-commerce platforms.
Order volume concentrates with Retail Brands; Contract Packers expand most quickly as brand owners outsource filling operations to capture capital flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of aluminum beverage cans consumed domestically, while European converters face the steepest compliance costs from carbon disclosure rules. The United States maintains extensive coating and printing infrastructure for multinational beverage accounts.
China
Tier-1 cities Shanghai and Beijing drive per-capita consumption of carbonated beverages and craft beer. SAMR enforces GB standards for food-contact metal packaging safety and labeling accuracy. Domestic two-piece can manufacturing clusters in Guangdong and Zhejiang provinces scale capacity alongside urban consumption growth.
Germany
Premium beverage segments in Bavaria and North Rhine-Westphalia mandate supplier climate data as a condition of contract renewal. REACH restricts hazardous substances in coating formulations and mandates recyclability documentation. Metal decorating operations in the Ruhr industrial region invest in renewable energy certificates to meet retailer procurement criteria.
United States
Multinational beverage brands manage seasonal demand spikes through dual-qualified vendor structures with quarterly volume allocation shifts. EPA guidelines govern volatile organic compound emissions from metal decorating operations. Extensive domestic manufacturing infrastructure in the Midwest and Southeast anchors North American aluminum can supply.
India
Per-capita aluminum can consumption remains a fraction of developed-market levels in Maharashtra and Gujarat. FSSAI food-contact safety modernization reshapes certification timelines for exporters and domestic producers. Domestic can manufacturing investments align with urban beverage consumption growth in Delhi-NCR and Bangalore.
Japan
Specialty resin production for epoxy-phenolic coatings concentrates among limited chemical suppliers serving metal packaging converters. METI industrial standards govern material specifications for food-contact applications. Precision manufacturing clusters in the Kanto region supply high-resolution decoration systems for premium cosmetic and gift packaging applications.
Global Metal Print Packaging Market Competitive Landscape
The competitive structure tilts toward integrated multinational converters with captive substrate supply and regional decoration networks. Tier-1 players operate across multiple continents with high-speed coating lines serving multinational beverage accounts. Mid-tier specialists compete on design complexity and color fidelity for premium segments. Dominant competitive moves include capacity expansion in high-growth consumption clusters and strategic partnerships with digital printing equipment vendors.
Among North American-based fabricators, Ball Corporation and Crown Holdings, Inc. exemplify the integrated multinational archetype with extensive domestic manufacturing infrastructure. Ardagh Group S.A. occupies a position within the European premium-tier specialist segment, competing on decoration complexity. These three anchors represent contrasting strategic positions: scale-driven continental supply, integrated global operations, and design-focused premium positioning.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Ardagh Group S.A. |
| Silgan Holdings Inc. |
| CCL Industries Inc. |
| Amcor plc |
| Sonoco Products Company |
| Toyo Seikan Group Holdings, Ltd. |
| Can-Pack S.A. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up metal decorating specialists anchor supply consolidation in North America and Western Europe, concentrating pricing power among integrated converters while fragmenting procurement options for mid-tier beverage brands seeking flexible capacity allocation.
Pricing Analysis
Margin tightening in standard-grade beverage can decoration reflects primary aluminum price volatility on the London Metal Exchange and hedging cost burdens passed through contract structures. Three-tier pricing structure across premium, standard, and economy levels separates verified recycled-content suppliers under EU Green Deal mandates from commodity-grade converters and cost-optimized tinplate food can specialists. Price differentiation hinges on carbon disclosure documentation and ISO 14001 environmental management certification tiers. Cost-down pressure on economy-tier steel food containers accelerates because incumbent equipment lock-in slows aluminum substitution despite raw material savings.
Supply Chain Analysis
Epoxy-phenolic coating supply rests on specialty resin producers concentrated in Germany and Japan, creating single-source vulnerability for metal packaging converters dependent on corrosion-resistant internal liners. Raw material feeds draw from primary aluminum smelters in China and Russia, tinplate rolling mills in South Korea and Japan, and UV-curable ink formulators in the United States and Netherlands. Tariff exposure on Chinese aluminum imports into North America and Europe compounds margin pressure for substrate-dependent decorators. Distribution runs through multinational beverage company procurement hubs, contract packer consolidation points, and direct-to-brand digital platforms for short-run craft beverage campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH recyclability documentation and EU Green Deal carbon disclosure mandates erect compliance moats that favor incumbent converters with capitalized lifecycle assessment infrastructure and renewable energy certificates.
For Market Incumbents: Cement market position by acquiring distressed digital printing equipment vendors in Germany and Japan to secure variable-data decoration capabilities ahead of SKU proliferation demand. Prioritize backward integration into specialty resin formulation to mitigate epoxy-phenolic supply concentration risk from limited German and Japanese chemical suppliers. Defend against craft beverage direct-to-brand platform disintermediation by offering sub-10,000-unit minimum order thresholds through hybrid offset-digital press configurations. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian beverage can decoration opens white-space opportunity for domestic two-piece aluminum manufacturing investments aligned with FSSAI food-contact safety modernization. Target Maharashtra and Gujarat industrial corridors where per-capita aluminum can consumption remains a fraction of developed-market levels. Pursue contract packer aggregation partnerships to secure volume commitments without direct multinational brand procurement qualification hurdles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European decorators with verified recycled-content certification infrastructure and established retailer climate data reporting relationships. Long-term viability centers on converters capable of documenting circularity claims under tightening extended producer responsibility frameworks. Monitor UV-LED curing technology adoption rates as inflection indicator for regulatory compliance cost reduction and energy efficiency positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Printing Platform Acquisition | Variable-data capability from Fujifilm or Heidelberg systems enables hyper-localized beverage campaigns without plate inventory costs. |
| Renewable Energy Certificate Procurement | Verified clean power sourcing satisfies EU Green Deal retailer procurement criteria for German and French premium beverage contracts. |
| Specialty Resin Backward Integration | In-house epoxy-phenolic formulation reduces dependency on limited German and Japanese chemical supplier concentration. |
| India Manufacturing Footprint Establishment | Domestic two-piece can capacity in Gujarat captures FSSAI-aligned demand from Delhi-NCR and Bangalore urban consumption clusters. |
| Direct-to-Brand E-Commerce Platform Launch | Short-run digital decoration access bypasses traditional distributor networks for craft brewery and seasonal promotional launches. |
Research Methodology
Independent corroboration across plant managers at North American coating lines, procurement leads at multinational beverage companies, and distribution channel partners in European metal decorating networks underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at specialty resin suppliers and regulatory affairs specialists navigating REACH documentation requirements combined with secondary validation from SEC 10-K filings, customs and trade data, and Cefic chemical industry reports. Bottom-up capacity assessments at individual converter facilities triangulate against top-down demand modeling from beverage consumption clusters.
Rate-of-change decomposition across substrate type, decoration technology, and end-use application segments drives the analytical framework over the projection horizon. Segmentation dimensions modeled include aluminum versus steel substrate grades, flexographic versus digital versus offset lithography processes, and food and beverage versus personal care versus pharmaceutical end-use environments. CAGRs derive from volume trajectory analysis incorporating urban consumption growth patterns, regulatory compliance cost pass-through assumptions, and technology substitution elasticities for digital inkjet systems displacing conventional plate-based decoration.
Inputs from primary stakeholder interviews and published regulatory filings were available through the study window; gaps in real-time London Metal Exchange hedging cost disclosures and proprietary coating formulation specifications introduce uncertainty bands around margin compression forecasts. A small set of triggers including EU carbon border adjustment implementation timelines and China GB standard certification cycle lengths warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Cans Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
North America 3 Piece Metal Cans Market