
 Food and Beverages Metal Can Market | 2026-2036
Food and Beverages Metal Can Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverages Metal Can Market Intelligence
A transition from single-supplier contracts toward multi-sourcing for high-volume can requirements is shifting procurement strategies among major beverage manufacturers. This move aims to mitigate supply chain disruptions and increase pricing leverage. Ball Corporation leverages its global manufacturing footprint to serve multinational clients across regions. Crown Holdings, Inc. differentiates through specialized can shaping and printing technologies for premium beverage brands.
Food and beverages metal cans are hermetically sealed containers, typically manufactured from aluminum or tinplated steel. These containers are defined by their ability to preserve contents from light and oxygen, often utilizing a double-seam construction for integrity. Aluminum dominates the beverage application due to its light weight and recyclability, particularly for two-piece cans. While the processed food segment remains a stable volume driver, ready-to-eat meals show significant expansion.
Regulations from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate material composition and coating safety. These standards, particularly regarding substances like BPA, directly influence material selection and manufacturing processes for can producers. Navigating the divergent recycling infrastructure and collection rates across key national markets will determine long-term material choices.
Market Dynamics
The market's central dynamic is the interplay between material selection and circular economy pressures. The superior recyclability of aluminum competes with the established infrastructure and cost structure of tinplated steel, forcing producers to navigate divergent regional recycling systems.
Growth Catalysts
- Ready-to-Eat Meals:Demand for convenient, shelf-stable food, particularly in urbanized areas of Southeast Asia, drives significant volume growth for both steel and aluminum cans.
- Advanced Coatings:The development of BPA-free polymer coatings allows manufacturers to meet stringent food contact safety standards from regulators like the FDA and EFSA.
- Urbanization in Asia:Rapid urbanization and changing dietary patterns in countries such as Vietnam and Indonesia are expanding the consumer base for canned foods and beverages.
Market Restraints
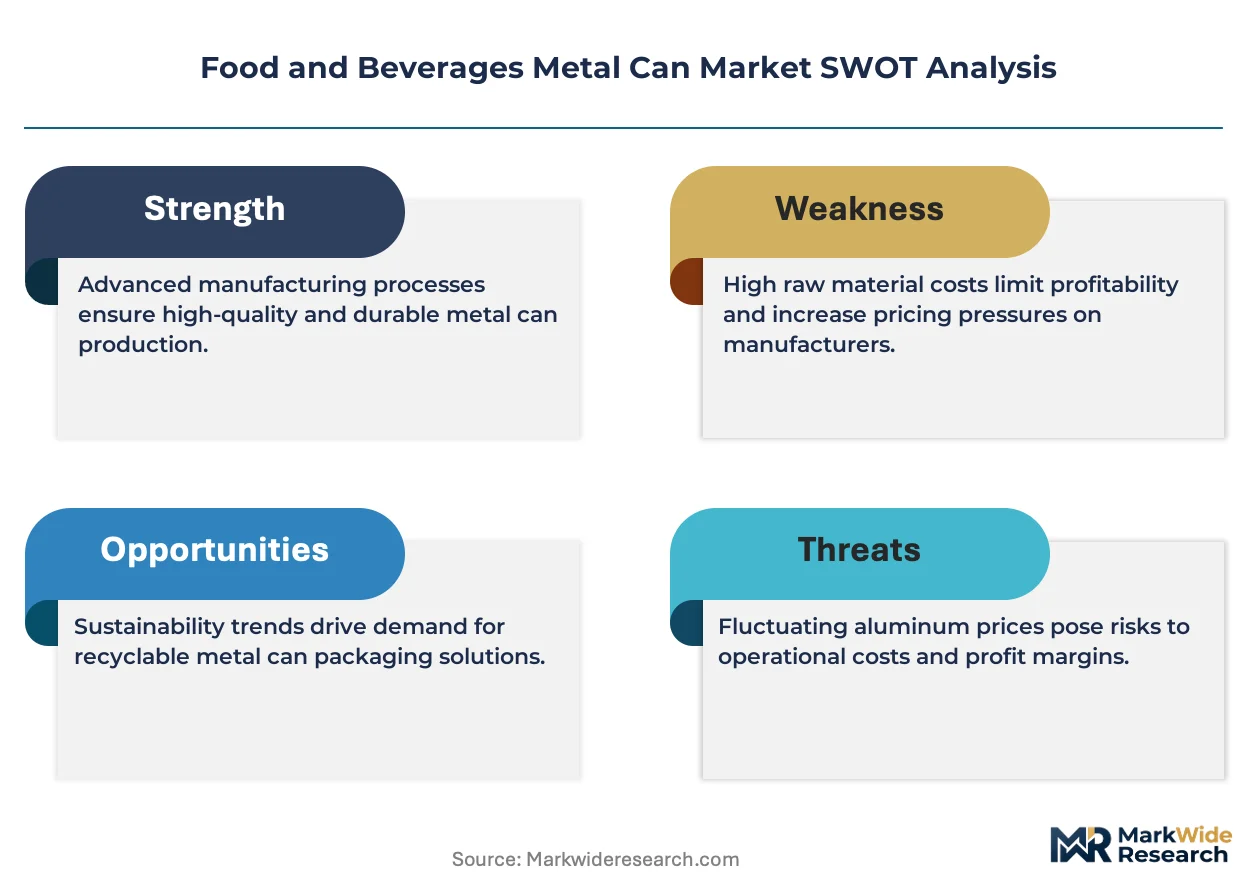
- Input Cost Volatility:Fluctuations in the global prices of primary aluminum and tinplate steel create significant margin pressure and forecasting challenges for can manufacturers.
- Substitution Threat:Flexible pouches and PET bottles present a persistent competitive threat, especially in single-serve beverage and liquid food categories due to lower weight.
- Regulatory Fragmentation:Navigating disparate national regulations for food contact materials and recycling mandates increases compliance costs and complicates market entry strategies for producers.
Strategic Opportunities
- Functional Beverages:The growing market for energy drinks, hard seltzers, and ready-to-drink coffees provides a high-margin opportunity for specialized can sizes and finishes.
- Aerosol Can Innovation:Development of shaped aluminum aerosol cans for personal care and household products opens a new avenue for differentiation beyond traditional food and beverage uses.
- Closed-Loop Recycling:Establishing dedicated collection and recycling systems for aluminum cans offers a path to secure a stable supply of post-consumer scrap and meet sustainability goals.
Industry Challenges
- Supply Chain Reconfiguration:The transition to multi-sourcing models requires sophisticated logistics and inventory management to balance risk mitigation with the cost efficiencies of single-supplier relationships.
- Capital Investment for Lightweighting:Upgrading production lines to handle thinner gauge metals for lightweighting requires significant capital expenditure and extensive requalification with customers.
- Recycling Infrastructure Gaps:A lack of standardized and efficient recycling collection and sorting infrastructure in many key markets limits the availability of high-quality recycled content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverages Metal Can Market |
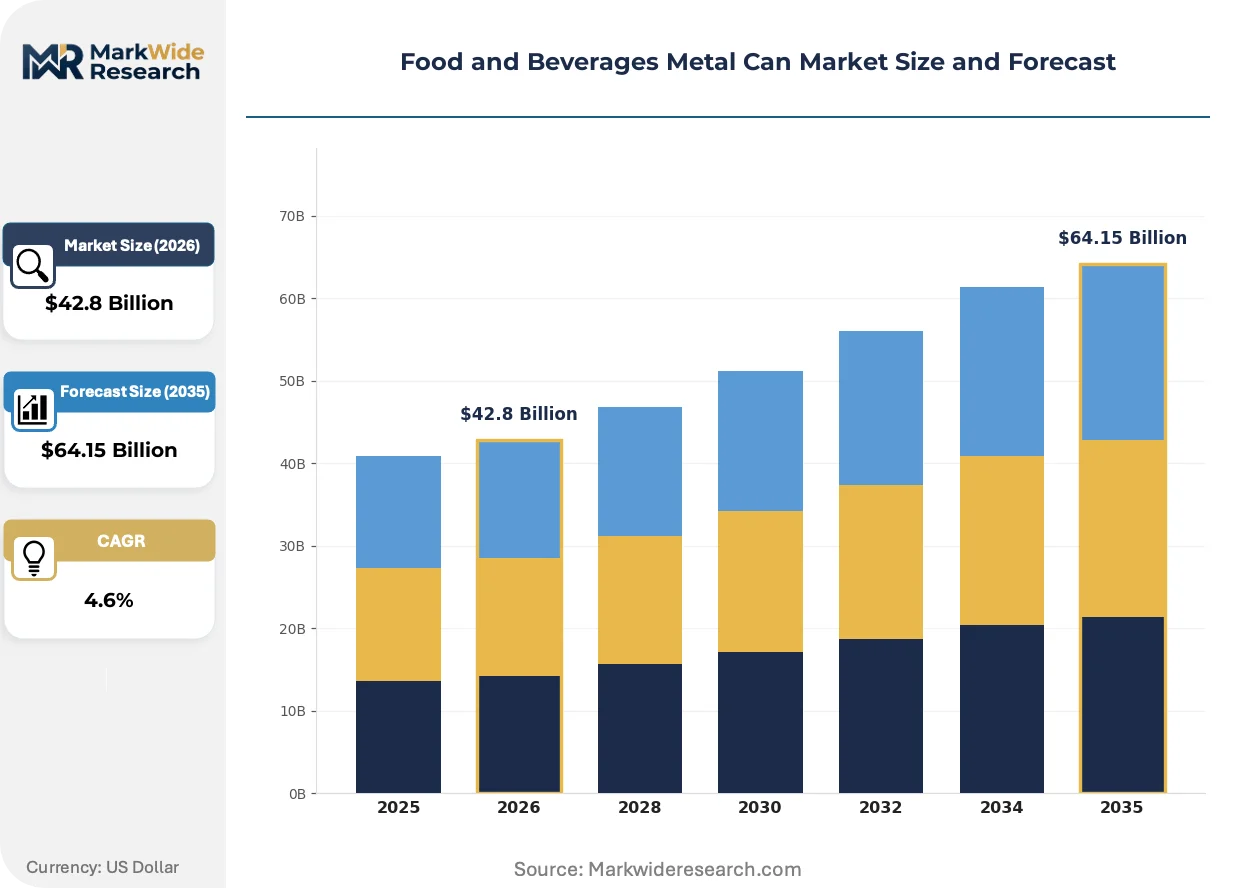
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Piece Can, Three-Piece Can, Drawn & Ironed Can, Impact Extruded Can, Aerosol Can Material: Tinplated Steel, Aluminum, Aluminum Alloy, Stainless Steel, Steel with Polymer Coating Application: Carbonated Beverages, Alcoholic Drinks, Processed Food, Ready-to-Eat Meals, Pet Food End User: Beverage Manufacturers, Food Processors, Packaging Companies, Contract Packers, Specialty Food Producers |
| Companies Covered | Crown Holdings, Inc, Ball Corporation, Silgan Holdings Inc., Ardagh Group, CAN-PACK Group, Toyo Seikan Group Holdings, Ltd., CPMC Holdings Limited, Kian Joo Group, Envases Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverages Metal Can Market Strategic Shifts & Innovations
A dual focus on manufacturing efficiency and sustainability is driving material and process innovation. Can makers are adopting new technologies to offer greater customization while simultaneously addressing regulatory pressures for increased recyclability and reduced material usage across their product lines.
Advanced digital printing technology enables high-resolution, full-color graphics to be applied directly onto the can surface. Premium and craft beverage brands are rapidly adopting this for limited editions and targeted marketing campaigns. This technology is automating the process of creating customized packaging, reducing the reliance on paper or plastic labels and shortening production lead times.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes stringent targets for material recyclability and the inclusion of post-consumer recycled content. This directive forces can manufacturers to invest in new aluminum alloys and can designs that facilitate easier sorting and reprocessing. The beverage segment is most impacted, prompting producers to explore direct-to-consumer take-back schemes to secure a consistent supply of used beverage cans.
Large consumer packaged goods companies are diversifying their can supply away from single-source agreements toward a multi-vendor procurement model. This strategy mitigates risks from supply chain disruptions and strengthens their negotiating position on pricing and service levels. The shift is most pronounced in the North American and European beverage markets, where brand owners can leverage their immense volumes across several major can producers.
Food and Beverages Metal Can Market Segmentation
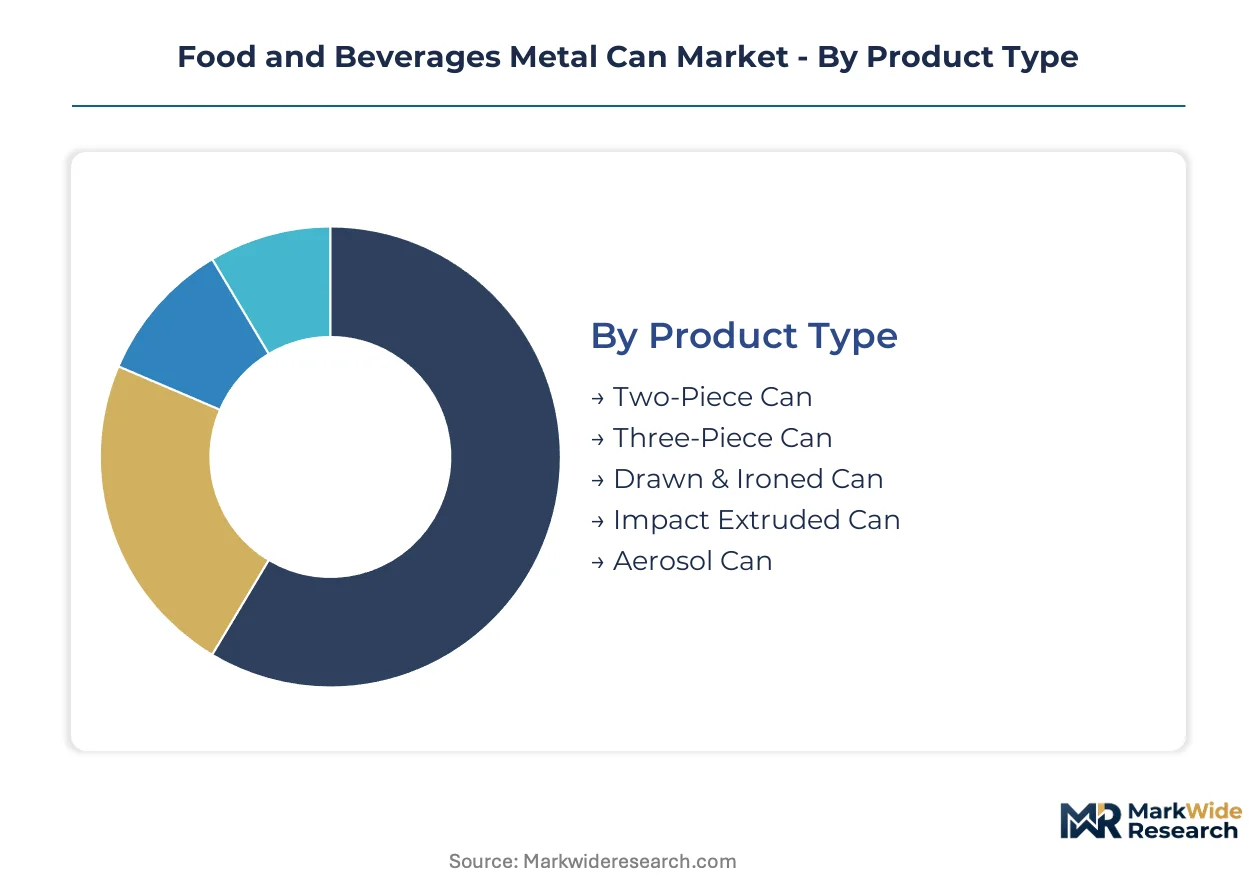
Understanding the varied segments within the food and beverages metal can market is crucial for strategic planning. Each category reflects distinct manufacturing processes, material dependencies, and end-user requirements, directly impacting investment decisions and competitive dynamics. This segmentation provides clarity on where capital is deployed and where demand is most active.
Product Type:
Segments in this market often reflect the capital intensity of their production lines. Producing certain can types requires substantial upfront investment in specialized machinery and tooling for high-speed, high-volume output.
- Two-Piece Can:These cans are formed from a single piece of metal for the body and a separate end, primarily used for beverages due to their lightweight design and ability to withstand internal pressure. Demand concentrates in carbonated beverage and alcoholic drink applications, driven by high-speed filling lines and consumer preference for convenience.
- Drawn & Ironed Can:A specific type of two-piece can, produced by drawing a shallow cup and then ironing the sidewalls to achieve desired height and thinness, widely adopted for high-volume beverage packaging. This method is prevalent in the beverage sector, especially for aluminum cans, due to its material efficiency and structural integrity.
- Three-Piece Can:Comprising a cylindrical body and two separate ends, these cans are versatile for various food products and are often made from tinplated steel.
- Impact Extruded Can:These cans are typically produced for aerosol products or small, high-pressure containers, characterized by a seamless body and precise dimensions.
- Aerosol Can:Designed to dispense contents under pressure, these cans are common in personal care, household, and some food applications, increasingly utilizing aluminum for lightweighting.
Most installed capacity flows through Two-Piece Can production. Expansion is steepest in Aerosol Can innovation.
Material:
The choice of material often dictates the cost tier of the final product and influences its recyclability profile. Material selection is also heavily influenced by regulatory compliance and consumer sustainability preferences.
- Tinplated Steel:This material consists of steel sheets coated with a thin layer of tin, offering excellent strength and corrosion resistance for processed foods and industrial applications. Demand remains stable in the processed food segment, supported by its established infrastructure and cost-effectiveness.
- Aluminum:Valued for its lightweight properties, high recyclability, and corrosion resistance, aluminum dominates the beverage can market, particularly for two-piece can constructions. Its use is prevalent across carbonated beverages and alcoholic drinks due to superior barrier properties and consumer appeal.
- Aluminum Alloy:These materials blend aluminum with other elements to enhance specific properties like strength, formability, or corrosion resistance, tailored for specialized packaging needs.
- Stainless Steel:Offering superior corrosion resistance and durability, stainless steel cans are used in niche applications requiring high-purity or extreme conditions, though less common for mass-market food and beverage.
- Steel with Polymer Coating:This material combines the strength of steel with an internal polymer layer, providing an additional barrier against product interaction and enhancing food safety, especially for acidic contents.
The established material base rests with Tinplated Steel. Demand for Aluminum is gaining share fastest.
Application:
Volume dynamics in the market are heavily influenced by the specific application, with certain segments driving consistent, large-scale demand and others exhibiting rapid expansion due to changing consumer habits.
- Carbonated Beverages:This segment represents a significant volume driver, primarily utilizing aluminum two-piece cans due to their ability to withstand internal pressure and offer effective light and oxygen barriers. Consumption is concentrated in mature markets and expanding rapidly in urbanizing regions.
- Ready-to-Eat Meals:This application shows significant expansion, particularly in urbanized areas of Southeast Asia, driving demand for shelf-stable food packaging. Convenience and longer shelf life are key drivers for this segment.
- Alcoholic Drinks:Including beer, hard seltzers, and ready-to-drink cocktails, this segment increasingly adopts metal cans for portability, recyclability, and branding opportunities.
- Processed Food:A foundational segment for metal cans, covering a wide array of products from vegetables and fruits to soups and sauces, relying on cans for preservation and extended shelf life.
- Pet Food:Metal cans offer durability and preservation for wet pet food products, a stable and consistent demand segment within the broader food packaging market.
Large-scale consumption patterns are anchored by Processed Food. The most dynamic growth originates from Ready-to-Eat Meals.
End User:
Different end-user types exhibit distinct procurement patterns and leverage varying scales of demand. Their strategic choices significantly influence can manufacturers' production schedules and innovation priorities.
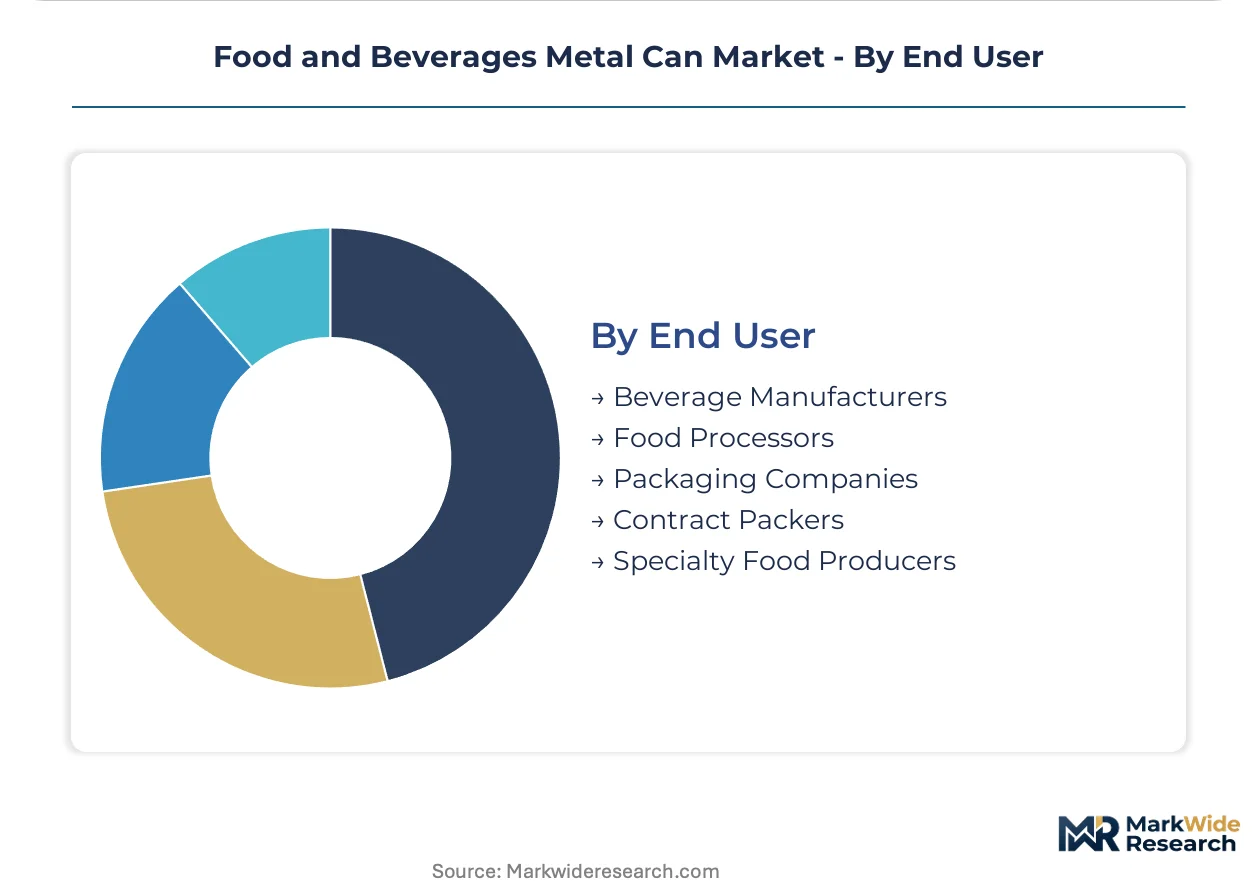
- Beverage Manufacturers:These entities represent major buyers, often engaging in multi-sourcing strategies for high-volume can requirements to mitigate supply chain risks. Their demand spans carbonated soft drinks, alcoholic beverages, and functional drinks.
- Food Processors:Companies that prepare and package a wide range of processed food items, from vegetables to ready meals, form a stable and consistent demand base for metal cans. They prioritize preservation qualities and cost-effectiveness.
- Packaging Companies:These firms act as intermediaries, supplying packaging solutions to various brand owners, often requiring a diverse portfolio of can types and sizes.
- Contract Packers:Specializing in packaging services for other companies, contract packers require flexible can supply to meet diverse client specifications and production schedules.
- Specialty Food Producers:This segment includes smaller producers of gourmet or niche food items, often seeking customized can designs and lower volume orders for unique product differentiation.
The largest purchasing power resides with Beverage Manufacturers. Niche requirements are increasingly met by Specialty Food Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asia's urban centers, particularly in Vietnam and Indonesia, drive significant metal can demand for convenience foods. North America and Europe maintain established markets, while China's vast consumer base expands its requirements. These regions collectively showcase diverse regulatory landscapes and evolving consumer preferences for metal packaging.
Vietnam
Demand for ready-to-eat meals and functional beverages propels metal can consumption in Vietnam. The Ministry of Health establishes stringent food contact material standards for packaging. Ho Chi Minh City's burgeoning food processing sector requires high volumes of two-piece and three-piece cans.
Indonesia
Rapid urbanization and changing dietary patterns fuel demand for canned foods and beverages across Indonesia. The National Agency of Drug and Food Control (BPOM) enforces food packaging safety regulations. Jakarta's expanding beverage industry concentrates significant can manufacturing and filling operations.
United States
Carbonated beverages and an expanding functional drinks segment anchor metal can demand in the United States. The U.S. Food and Drug Administration (FDA) mandates material composition and coating safety for food contact surfaces. Packaging hubs in the Midwest support beverage and processed food manufacturers with extensive can production.
Germany
Germany's robust processed food and alcoholic beverage sectors maintain stable demand for metal cans. European Food Safety Authority (EFSA) guidelines heavily influence material selection and manufacturing processes. The Rhine-Ruhr region's industrial base hosts significant metal packaging production capabilities.
China
Urbanization and a growing middle class drive substantial demand for various canned goods across China. The State Administration for Market Regulation (SAMR) oversees food packaging standards and compliance. The Pearl River Delta region features a dense concentration of can manufacturing facilities and consumer packaged goods companies.
Food and Beverages Metal Can Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized can shaping and advanced coating technologies. The market features global integrators, regional specialists, and niche innovators. Strategic partnerships and multi-sourcing models are reshaping procurement strategies among major beverage manufacturers.
Among global manufacturers, Crown Holdings, Inc. and Ball Corporation exemplify large-scale operational efficiency and extensive geographic reach. Silgan Holdings Inc. represents a diversified packaging solution provider, often catering to specialized food and beverage segments. These entities anchor the market's supply base, providing extensive production capabilities across multiple geographies.
| Leading Market Players |
|---|
| Crown Holdings, Inc |
| Ball Corporation |
| Silgan Holdings Inc. |
| Ardagh Group |
| CAN-PACK Group |
| Toyo Seikan Group Holdings, Ltd. |
| CPMC Holdings Limited |
| Kian Joo Group |
| Envases Group |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and large multinational corporations influence both supply behavior and pricing discipline within the food and beverages metal can market. These entities manage extensive production capacities and often engage in long-term contracts with major brand owners.
Pricing Analysis
Input cost pass-through mechanisms significantly influence pricing across the metal can market. Manufacturers often negotiate contract-based long-term offtake agreements with beverage and food companies. Price differentiation stems from the level of customization required and the volume scale of the order. Margin pressure intensifies due to the volatility in primary aluminum and tinplate steel prices. Beverage manufacturers represent the least price-sensitive segment given their brand reliance, while smaller food processors exhibit higher price sensitivity.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks characterize the metal can supply chain, ensuring timely delivery to filling operations. Geographic supply concentration for can manufacturing centers in China, the United States, and Germany. The industry relies heavily on primary aluminum, tinplate steel, and specialized polymer coatings as key raw materials. Commodity price volatility presents a significant structural risk for can manufacturers. Distribution primarily runs through direct sales to large beverage and food manufacturers, supplemented by packaging companies serving smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards higher-value specialized can finishes and advanced BPA-free polymer coatings.
For Market Incumbents: Anchor existing market share by investing in advanced lightweighting technologies for aluminum cans. Diversify raw material sourcing to mitigate input cost volatility, a persistent threat to profitability. Expand regional manufacturing footprints in high-growth areas like Southeast Asia to counter rising logistics costs. Leverage global manufacturing scale to offer competitive multi-sourcing solutions to large beverage manufacturers.
For New Entrants and Emerging Players: Capture niche segments by offering specialized can shaping and high-resolution digital printing services. The functional beverages segment, particularly in urbanizing Asian markets, represents a penetrable application. Develop proprietary BPA-free coating technologies to meet stringent regulatory standards. A go-to-market angle focused on customization and faster turnaround times can attract craft beverage brands and specialty food producers.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized can shapers and advanced coating developers with strong intellectual property. The long-term viability of metal packaging remains strong, driven by sustainability trends and recyclability advantages over plastics. Target companies with established closed-loop recycling capabilities or those developing innovative material solutions. A signal to watch is the adoption rate of post-consumer recycled content mandates by major regulatory bodies like the European Union.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Printing Technology | Enables high-resolution customization and reduces lead times for premium beverage brands. |
| Develop Advanced BPA-Free Coatings | Ensures compliance with stringent FDA and EFSA food contact material safety standards. |
| Expand Lightweighting Production Lines | Reduces material costs and improves environmental performance for aluminum cans. |
| Establish Dedicated Recycling Systems | Secures stable supply of post-consumer scrap and meets sustainability objectives. |
| Diversify Raw Material Procurement | Mitigates margin pressure from fluctuations in primary aluminum and tinplate steel prices. |
Research Approach
Direct dialogue with beverage manufacturers, food processors, can producers, and packaging companies forms the qualitative grounding of this analysis. This primary research is validated against extensive secondary data from regulatory bodies like the FDA and EFSA, trade association reports, and company annual reports. A comprehensive bottom-up and top-down triangulation approach ensures robust data integrity.
This analytical framework models market dynamics across the analysis window, segmenting by product type, material, application, end-user, and regional regulatory cluster. Compound annual growth rates are derived from historical data trends, macroeconomic indicators, and projected consumer behavior shifts. Urbanization rates in Southeast Asia and raw material pricing trends are critical forecast inputs for volume and value projections.
Input cost volatility, regulatory changes, and alternative packaging innovation are the dominant revision risks for market forecasts. Forecasts reflect assumptions documented within the study's scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
India Metal Cans Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Household Aluminum Foils Market