
 APAC Food Cans Market | 2026-2036
APAC Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Food Cans Market Insights
Aluminum is realigning food can economics across Asia-Pacific as brands seek lighter, infinitely recyclable alternatives to traditional tinplate. Toyo Seikan Group Holdings, Ltd. dominates Japan's precision-coated can segment through advanced surface engineering. CPMC Holdings Limited anchors mainland China's supply chain via integrated tinplate rolling and lithography operations. Crown Holdings, Inc. extends its regional footprint through high-speed two-piece aluminum can lines serving ASEAN beverage bottlers.
APAC food cans are cylindrical metal containers, typically fabricated from tin-coated steel or aluminum alloy, engineered to hermetically seal processed food against oxygen, light, and microbial contamination through double-seamed ends. The manufacturing process involves either three-piece welding of body blanks or deep-drawing of aluminum into seamless two-piece vessels, with internal epoxy phenolic coatings preventing metal-food interaction. Aluminum cans command expanding share in beverages and ready-to-eat meals where weight reduction drives logistics savings, while tinplate sustains dominance in vegetable and sauce applications requiring aggressive retort processing. Specialty cans with easy-open ends and shaped profiles capture premium margin pools across retail channels, whereas standard cylindrical formats remain volume leaders in institutional food manufacturing procurement.
China's SAMR enforces GB 4806 food contact material standards that restrict heavy metal migration into canned contents, compelling coating reformulation and substrate purification investments. Japan's METI promotes circular packaging targets that incentivize aluminum can-to-can recycling loops, while Australia's TGA-aligned state food regulators mandate detailed allergen labeling on imported canned goods. Stakeholders must monitor evolving extended producer responsibility frameworks across Southeast Asian markets where informal collection networks currently handle post-consumer can recovery.
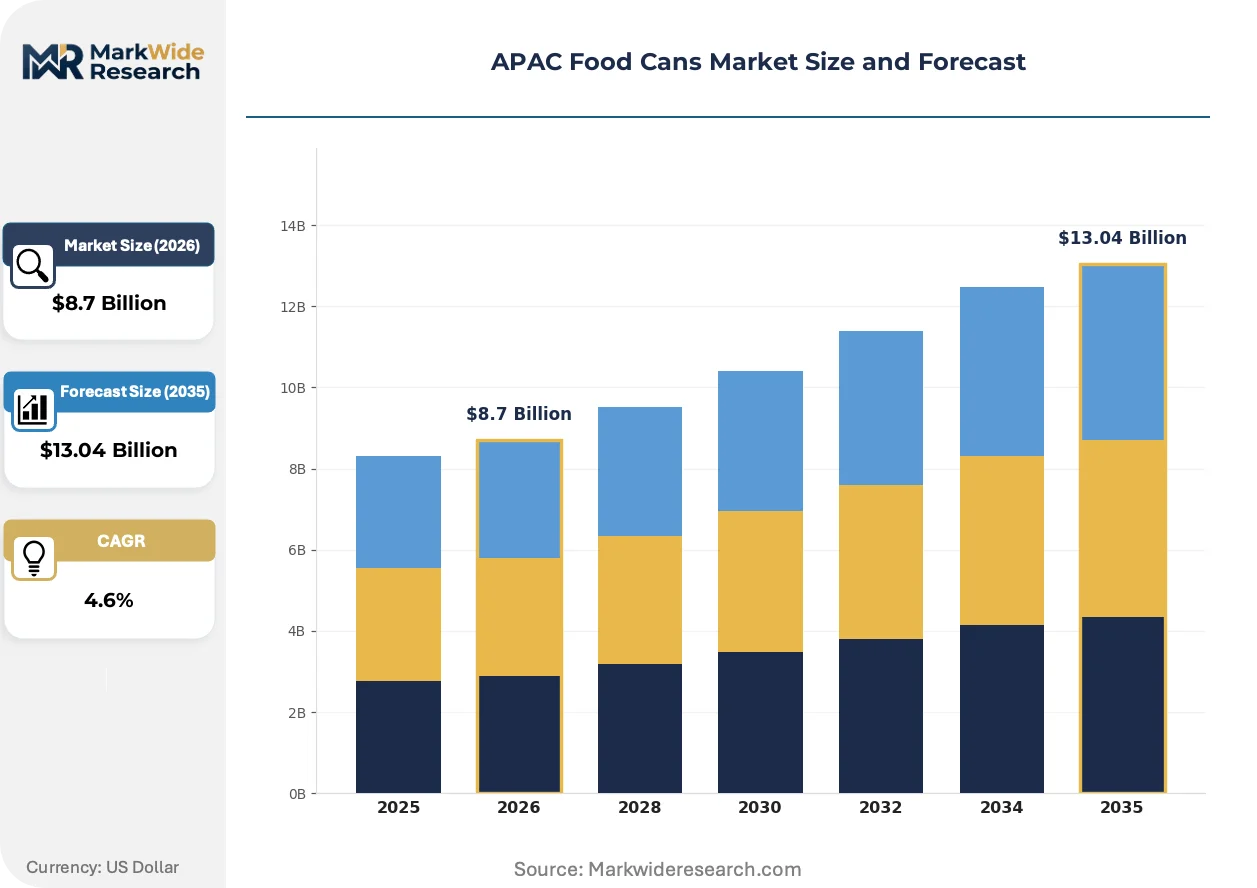
Market Dynamics
China's SAMR is tightening GB 4806 metal migration limits, forcing coating reformulation investments across Asia-Pacific food can supply chains while aluminum substrate adoption accelerates logistics savings for regional beverage and ready-meal brands.
Growth Catalysts
- Indonesia's processed food sector:Expanding domestic canning capacity for seafood and tropical fruits is pulling regional tinplate and aluminum supply toward Southeast Asian manufacturing clusters.
- Japan's METI circular packaging targets:Aluminum can-to-can recycling mandates are creating closed-loop material demand that favors infinitely recyclable substrate investments over single-use alternatives.
- Easy-open end technology:Precision-scored aluminum lid systems are capturing premium retail margins across Japan and South Korea's convenience store channels.
Market Restraints
- Tinplate cost volatility:Iron ore and tin price swings concentrate input cost risk among integrated steel-rolling suppliers in China and Japan.
- Epoxy phenolic coating dependency:Bisphenol-A migration concerns under China's GB standards are compressing approved coating chemistries and extending reformulation timelines.
- Retort processing limitations:Aluminum's lower thermal tolerance versus tinplate blocks penetration into high-temperature vegetable and sauce applications.
Strategic Opportunities
- Vietnam's underpenetrated seafood canning:Mekong Delta aquaculture expansion offers white-space demand for two-piece aluminum formats in export-oriented processing.
- Australia's TGA-aligned allergen labeling:Mandatory disclosure requirements on imported canned goods create compliance-service revenue streams for regional labeling specialists.
- Digital printing convergence:UV-cured inkjet systems on can lithography lines are enabling short-run customization for seasonal and promotional SKUs.
Industry Challenges
- Surface engineering talent scarcity:Precision coating application and corrosion testing expertise concentrates among aging technical workforces in Japan and South Korea.
- Extended producer responsibility integration:Informal collection networks across Southeast Asia complicate post-consumer can recovery traceability for brand sustainability reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Food Cans Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Tinplate Cans, Flexible Pouches, Glass Jars End User: Restaurants, Retailers, Food Manufacturers, Home Consumers Application: Ready-To-Eat Meals, Vegetables, Sauces, Beverages Packaging Type: Standard Cans, Specialty Cans, Eco-Friendly Cans, Bulk Packaging |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Ardagh Group, Can-Pack Group, Toyo Seikan Group Holdings, Ltd., CPMC Holdings Limited, Silgan Holdings Inc., Visy Industries, Kian Joo Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Food Cans Market Trends and Innovations
Material substitution and regulatory compression are restructuring Asia-Pacific food can manufacturing, with aluminum formats penetrating new application boundaries while coating chemistry faces stringent migration testing protocols.
High-speed two-piece aluminum deep-drawing lines are expanding into ready-to-eat meal segments previously dominated by three-piece tinplate welding. Japanese and South Korean convenience retailers are adopting these lighter formats to reduce shelf stocking labor and transportation fuel surcharges. The shift is expanding into retort-compatible aluminum alloys that challenge tinplate's thermal performance monopoly in sauce applications.
China's GB 4806 food contact material standards are mandating stricter heavy metal migration thresholds for lead, cadmium, and arsenic in canned contents. SAMR enforcement is compelling substrate purification investments at tinplate rolling mills and accelerated epoxy phenolic coating validation cycles. Vegetable and infant food can segments face the steepest compliance timelines, with some manufacturers shifting toward aluminum to bypass tin-coating migration risks entirely.
Buyer concentration among ASEAN beverage bottlers is compressing supplier negotiation cycles and unbundling after-sales technical service from equipment procurement contracts. Large-scale Thai and Indonesian bottlers are demanding dedicated field engineering support as standard contract terms, displacing traditional third-party maintenance arrangements. This pattern is most visible in Vietnam's emerging canning corridor, where foreign direct investment is scaling two-piece aluminum capacity ahead of domestic service infrastructure maturity.
APAC Food Cans Market Segmentation
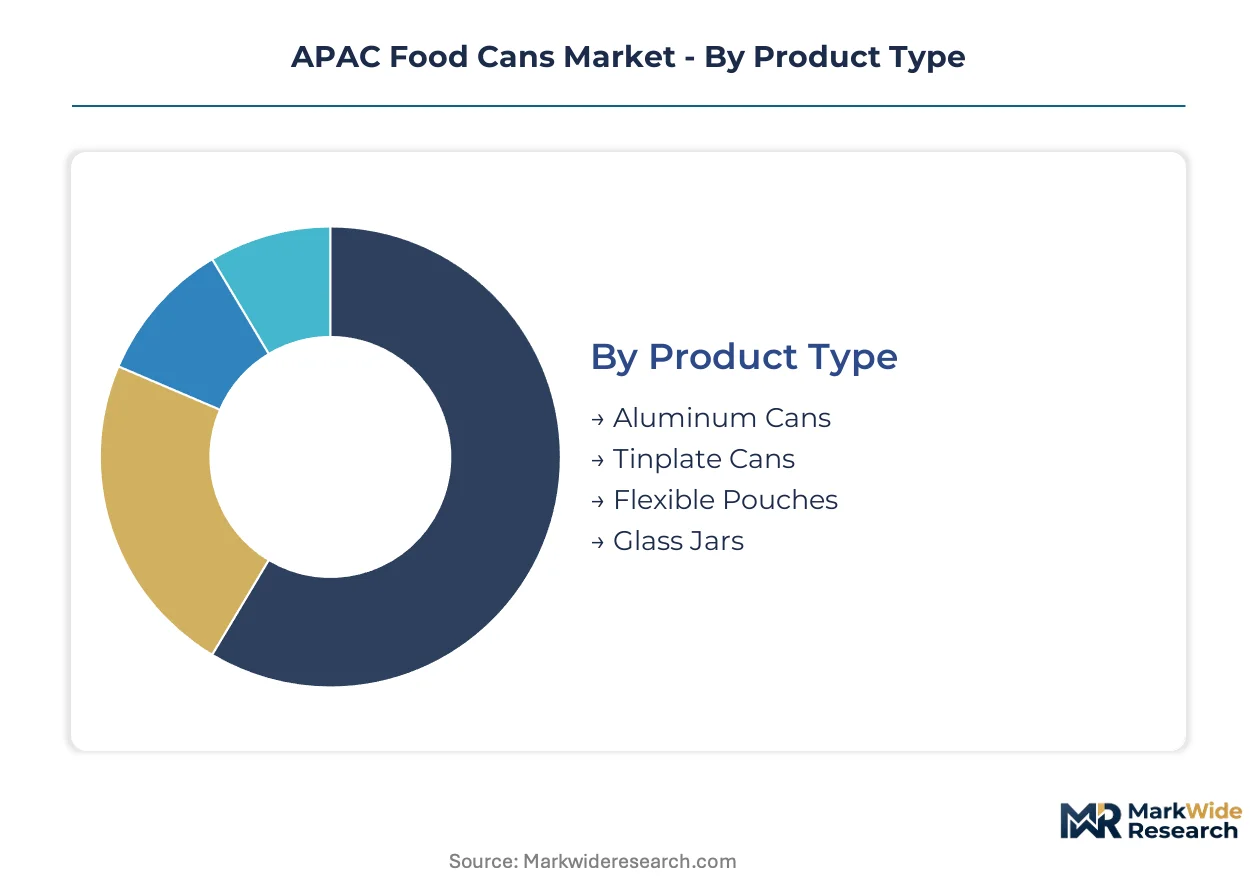
APAC food can segmentation reveals diverging substrate economics between aluminum and tinplate formats, with coating compliance costs and logistics weight driving procurement decisions across Indonesia's seafood processors and Japan's convenience retail channels.
Product Type:
Upgrade cycles favor lighter substrates where logistics savings compound across archipelago geographies and high-frequency distribution networks.
- Aluminum Cans:Deep-drawn two-piece vessels with internal epoxy phenolic linings deliver 30-40% weight reduction versus steel equivalents. Indonesia's processed seafood sector is pulling regional aluminum supply toward Batam and Surabaya manufacturing clusters to cut inter-island shipping fuel surcharges.
- Tinplate Cans:Three-piece welded construction with tin-coated steel bodies withstands aggressive retort processing above 121°C. China's vegetable canning belt around Shandong province sustains dominance here, though GB 4806 metal migration limits are extending coating validation timelines.
- Flexible Pouches:Multi-layer polymer laminates with aluminum foil barriers compete in single-serve ready-meal segments.
- Glass Jars:Premium sauce and specialty food applications in Japan and South Korea where shelf visibility commands retail margin.
Volume placements concentrate in Tinplate Cans; the faster expansion belongs to Aluminum Cans.
End User:
Procurement authority splits between institutional scale and fragmented retail, with technical service bundling becoming a contract differentiator.
- Restaurants:Foodservice operators source #10 institutional cans through wholesale distributors, prioritizing stackability and manual opening reliability in high-throughput kitchens.
- Retailers:Convenience store chains across Japan and South Korea are specifying easy-open aluminum ends to reduce shelf-stocking labor costs and enable single-serve pricing.
- Food Manufacturers:Integrated canning operations in Thailand and Vietnam control substrate selection to lock in export certification compliance.
- Home Consumers:E-commerce penetration in China's tier-2 cities is reshaping multipack formats toward lighter shippable configurations.
Contract value concentrates with Food Manufacturers; Retailers are gaining procurement leverage fastest through volume consolidation.
Application:
Retort compatibility requirements create substrate lock-in effects that aluminum alloy innovation is gradually eroding.
- Ready-To-Eat Meals:Aluminum two-piece formats with modified atmosphere sealing are displacing retort pouches in Japanese convenience channels where shelf stability and microwave compatibility intersect.
- Vegetables:High-temperature sterilization above 125°C preserves tinplate's structural necessity, particularly in China's export-oriented asparagus and mushroom processing.
- Sauces:Tomato and curry applications face Bisphenol-A scrutiny under China's GB standards, pushing some reformulation toward aluminum or glass alternatives.
- Beverages:ASEAN bottler consolidation is standardizing 330ml and 500ml aluminum formats for carbonated and still drinks.
Shipment tonnage concentrates in Vegetables; Beverages are climbing the fastest as two-piece capacity scales ahead of food applications.
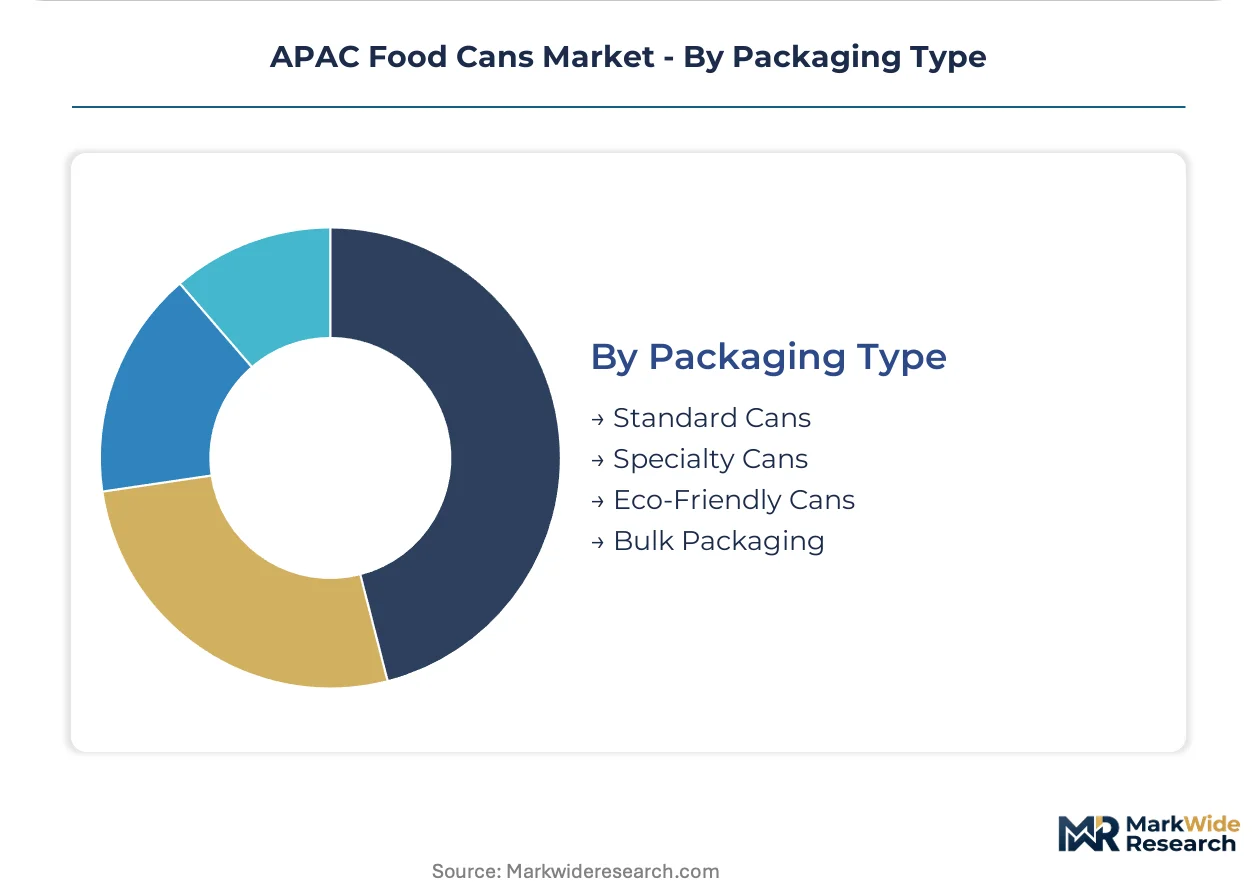
Packaging Type:
Margin capture separates commodity cylinders from value-added formats where differentiation justifies equipment investment.
- Standard Cans:Cylindrical three-piece welding dominates institutional procurement with minimal specification variance.
- Specialty Cans:Shaped profiles and easy-open aluminum ends command premium placement in Japanese and South Korean retail, with precision-scored lid technology concentrating among Japanese equipment suppliers.
- Eco-Friendly Cans:Higher recycled content aluminum and bio-based interior coatings respond to Australia's extended producer responsibility frameworks and METI circular packaging targets.
- Bulk Packaging:#10 and institutional sizes serve food manufacturing inputs and foodservice distribution across Southeast Asia's growing processing sector.
Unit volume concentrates in Standard Cans; Specialty Cans are gaining share fastest through convenience channel premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's processed food sector concentrates regional demand, pulling tinplate and aluminum supply toward Southeast Asian manufacturing clusters as logistics weight reduction becomes a decisive procurement factor.
China
Shandong province's vegetable canning belt sustains tinplate dominance for high-temperature retort applications. SAMR's GB 4806 standards are compressing coating validation timelines and forcing substrate purification investments at rolling mills. Yangtze River Delta processors are shifting portions of sauce production toward aluminum formats to bypass tin-coating migration risks.
Japan
METI circular packaging targets are accelerating aluminum can-to-can recycling loops that favor infinitely recyclable substrate investments. Kanto region convenience retailers specify precision-scored easy-open aluminum ends to reduce shelf-stocking labor costs. Toyo Seikan Group Holdings, Ltd. anchors precision-coated can production through advanced surface engineering capabilities concentrated in eastern manufacturing corridors.
Indonesia
Domestic canning capacity for seafood and tropical fruits is expanding across Batam and Surabaya manufacturing clusters. Inter-island shipping fuel surcharges are driving aluminum adoption for weight-sensitive distribution networks. The country's growing processed food sector is pulling regional substrate supply toward Southeast Asian procurement hubs.
Vietnam
Mekong Delta aquaculture expansion is creating white-space demand for two-piece aluminum formats in export-oriented seafood processing. Foreign direct investment is scaling canning capacity ahead of domestic service infrastructure maturity. Ho Chi Minh City corridor bottlers are demanding dedicated field engineering support as standard contract terms.
Australia
TGA-aligned state food regulators mandate detailed allergen labeling on imported canned goods, creating compliance-service revenue streams for regional specialists. Extended producer responsibility frameworks are reshaping post-consumer can recovery requirements. Premium sauce and specialty food applications in urban retail channels sustain glass jar competition for shelf visibility.
APAC Food Cans Market Competitive Landscape
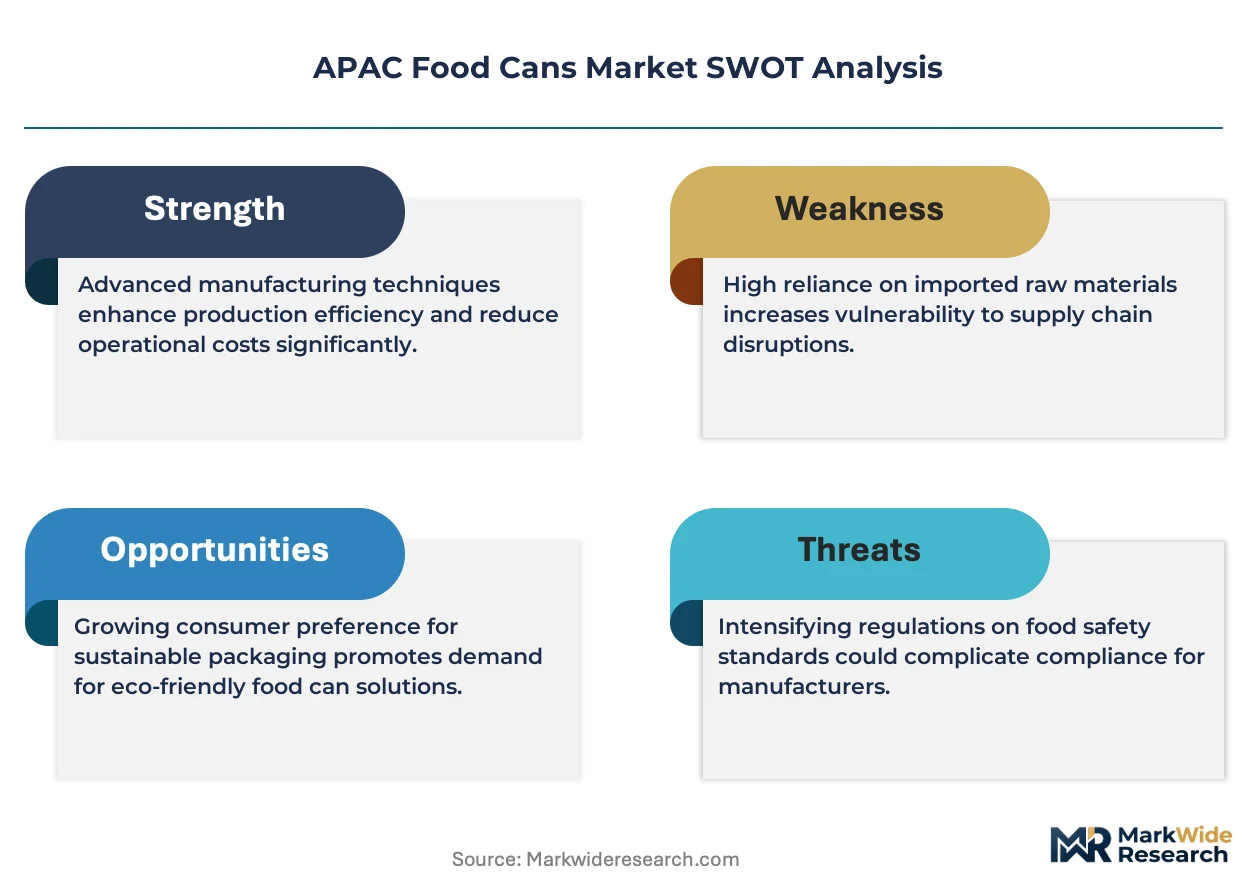
Branded specialists and contract manufacturers split share differently across segments, with integrated substrate producers commanding procurement leverage in China's vegetable processing belt while regional fabricators serve ASEAN beverage bottlers through equipment-plus-service bundling. The vendor base organizes around three archetypes: steel-rolling conglomerates with captive tinplate supply, aluminum specialists leveraging logistics weight advantages, and diversified packaging groups spanning multiple substrate formats. Capacity expansion and coating chemistry reformulation represent the dominant competitive moves as GB 4806 compliance timelines compress.
Within the integrated substrate tier, Toyo Seikan Group Holdings, Ltd. and CPMC Holdings Limited exemplify divergent geographic anchoring strategies—Japanese precision engineering versus mainland Chinese supply chain integration—while Crown Holdings, Inc. occupies a position among aluminum format specialists serving ASEAN bottler consolidation. These three entities represent distinct archetype endpoints: technology-driven surface engineering, backward-controlled raw material access, and high-speed two-piece capacity scaling.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Ardagh Group |
| Can-Pack Group |
| Toyo Seikan Group Holdings, Ltd. |
| CPMC Holdings Limited |
| Silgan Holdings Inc. |
| Visy Industries |
| Kian Joo Group |
| Others |
Pricing and Supply Chain Analysis
Japan's convenience retailers specifying easy-open aluminum ends are compressing procurement cycles and unbundling technical service from equipment contracts, forcing suppliers to absorb field engineering costs and compressing margins across ASEAN fabricator tiers.
Pricing Analysis
Volume placements in standard three-piece tinplate cans run on thin commodity margins, while specialty formats with precision-scored aluminum lids capture premium positioning through reduced shelf-stocking labor and single-serve pricing power. Price differentiation separates easy-open end specifications from conventional welded constructions, with certification tiers under China's GB 4806 standards adding compliance cost layers. Pricing pressure stems from buyer consolidation among Thai and Indonesian bottlers demanding dedicated field support as standard terms. Food manufacturers with integrated canning operations exhibit lowest price sensitivity due to export certification lock-in requirements, whereas institutional foodservice distributors prioritize stackability and manual opening reliability at lowest unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Crown Holdings and Ball Corporation serving consolidated ASEAN beverage bottlers, while regional fabricators feed Indonesia's seafood processors through distributor-mediated procurement. Raw material flows draw from China's tinplate rolling mills around Shandong province, Japanese aluminum smelting corridors, and Australian bauxite refining. Supply chain risk centers on iron ore and tin price volatility concentrating input cost exposure among integrated steel-rolling suppliers. Distribution runs through Batam and Surabaya manufacturing clusters serving Indonesia's inter-island shipping networks, with Ho Chi Minh City corridor emerging as Vietnam's canning capacity scales ahead of domestic service infrastructure maturity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC food cans market has become a vertical-integration race where substrate purification investments and captive coating formulation capabilities determine who captures GB 4806 compliance rents versus who bleeds margin on external validation cycles.
For Market Incumbents: Anticipate aluminum alloy innovation eroding tinplate's thermal performance monopoly in retort applications by accelerating R&D into high-temperature-compatible two-piece formats. Defensive consolidation should prioritize backward integration into tinplate rolling or aluminum smelting to lock in substrate supply during commodity volatility, while securing precision coating application talent from Japan's aging technical workforce before capability scarcity intensifies. For New Entrants and Emerging Players: E-commerce direct procurement channels targeting China's tier-2 city home consumers offer white-space entry with lighter shippable multipack configurations bypassing established distributor relationships. Vietnam's Mekong Delta seafood processing corridor presents the most penetrable geography, with foreign direct investment scaling capacity ahead of local service infrastructure and creating demand for technical service bundling as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive epoxy phenolic coating validation capabilities and established SAMR regulatory relationships. Long-term viability hinges on aluminum can-to-can recycling loop economics under METI circular packaging targets and extended producer responsibility frameworks across Southeast Asia. Watch for inflection in China's vegetable canning belt migration decisions—shifts from Shandong tinplate dominance toward Yangtze River Delta aluminum adoption would signal structural substrate displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | GB 4806 metal migration compliance creates competitive moat for validated substrate-coating combinations. |
| Backward Integration into Aluminum Smelting | Captive supply secures logistics weight advantages for Indonesia's inter-island distribution networks. |
| Precision Surface Engineering Acquisition | Japan's aging technical workforce makes coating application expertise a scarce defensible asset. |
| Easy-Open End Technology Licensing | Convenience channel premiumization in Japan and South Korea commands retail margin capture. |
| Vietnam Manufacturing Footprint Expansion | Mekong Delta aquaculture growth pulls regional supply toward export-oriented seafood processing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with canning plant managers, coating R&D directors, retail category buyers, and SAMR regulatory affairs specialists. Analysis triangulated bottom-up production capacity surveys against top-down consumption estimates across the projection horizon, validating substrate flow assumptions through rolling mill output disclosures and ASEAN beverage bottler procurement patterns.
Granularity-level modeling captured aluminum versus tinplate substrate splits, three-piece versus two-piece fabrication formats, and retort-compatible versus ambient-stable application boundaries throughout the forecast period. CAGRs derived from shipment volume trajectories weighted by regional logistics cost structures and GB 4806 compliance timeline impacts on coating reformulation cycles. Forecast inputs included inter-island shipping fuel surcharge sensitivity for Indonesia's archipelago distribution and METI recycling loop economics under circular packaging mandates.
The model holds under stable iron ore and tin price regimes; deviation in commodity volatility or accelerated aluminum alloy thermal performance breakthroughs would shift substrate adoption curves. Forecasts reflect base-case assumptions regarding SAMR enforcement intensity and ASEAN extended producer responsibility implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Metal Pails Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
PTP Aluminum Foil Market