
 Automotive Smart Antenna Market | 2026-2036
Automotive Smart Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Antenna Market Analysis
Germany is tilting its automotive electronics supply chain toward high-frequency antenna manufacturing for next-generation vehicle platforms. Continental AG leverages in-house RF module production to sustain design-to-delivery cycles for European OEM programs. Robert Bosch GmbH anchors its smart antenna portfolio through integrated sensor fusion with ADAS controllers. HELLA GmbH competes on compact multi-protocol antenna designs that occupy premium mounting positions on electric vehicle rooflines.
An automotive smart antenna integrates multiple RF transceivers, signal processing units, and vehicle-network interfaces into a single housing to enable cellular, satellite, navigation, and dedicated short-range communications for connected mobility. These assemblies typically operate across 700 MHz to 6 GHz bands with embedded low-noise amplifiers and digital beamforming chipsets to maintain link integrity at highway speeds. Cellular antenna segments lead current revenue contribution as 5G automotive modules penetrate OEM build specifications, while MIMO technology segments capture the fastest expansion due to spatial multiplexing demands for autonomous sensor backhaul. Active technology segments retain margin concentration because of their proprietary firmware and calibration IP requirements.
The European Telecommunications Standards Institute and the Federal Communications Commission shape product certification timelines for cross-border vehicle platforms, with ETSI EN 302 571 and FCC Part 90 rules governing DSRC and C-V2X emission masks. China's Ministry of Industry and Information Technology enforces GB/T protocol compliance for domestic smart antenna deployments, creating parallel testing requirements for suppliers serving multiple geographies. Stakeholders must monitor spectrum reallocation proceedings in major automotive markets and pre-position dual-protocol architectures before mandate deadlines crystallize.
Market Dynamics
The Automotive Smart Antenna Market is restructuring around embedded MIMO architectures as electric vehicle platforms demand consolidated RF modules for V2X, 5G, and satellite positioning. Tier-1 suppliers face compressed design cycles driven by OEM software-defined vehicle roadmaps.
Growth Catalysts
- EU Green Deal digital-mobility mandates:Brussels has embedded V2X communication requirements into vehicle-type approval frameworks, forcing antenna integration into connected-car platforms.
- Electric vehicle architectures:South Korean and German OEMs specify multi-band smart antenna arrays as standard equipment for battery-electric vehicle roofline mounting positions.
- 5G automotive modules:Cellular antenna penetration into OEM build specifications accelerates as embedded low-noise amplifiers enable highway-speed link integrity.
Market Restraints
- RF semiconductor supply concentration:Foundry capacity for gallium arsenide and silicon germanium LNAs clusters in Taiwan and South Korea, exposing antenna manufacturers to allocation risk.
- Dual-protocol testing burden:ETSI EN 302 571 and FCC Part 90 emission mask requirements force parallel certification tracks for DSRC and C-V2X variants.
- Calibration IP intensity:Active antenna firmware requires proprietary beamforming algorithms that lock suppliers into recurring engineering service contracts.
Strategic Opportunities
- India's automotive electronics localization:PLI scheme incentives for advanced driver-assistance systems create entry points for smart antenna suppliers establishing domestic RF module production.
- Software-defined vehicle convergence:Antenna-as-a-service models bundling over-the-air calibration updates with hardware sales capture recurring revenue streams.
- China's MIIT dual carbon goals:Domestic V2X infrastructure rollout mandates GB/T protocol compliance, opening captive demand for localized antenna suppliers.
Industry Challenges
- Electromagnetic compatibility certification:Multi-band arrays must satisfy simultaneous FCC, ETSI, and GB/T testing timelines that stretch 18-24 months for new vehicle programs.
- Legacy vehicle network integration:Smart antenna controllers must bridge CAN-FD and Ethernet backbones while maintaining signal integrity across heterogeneous OEM electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Antenna Market |
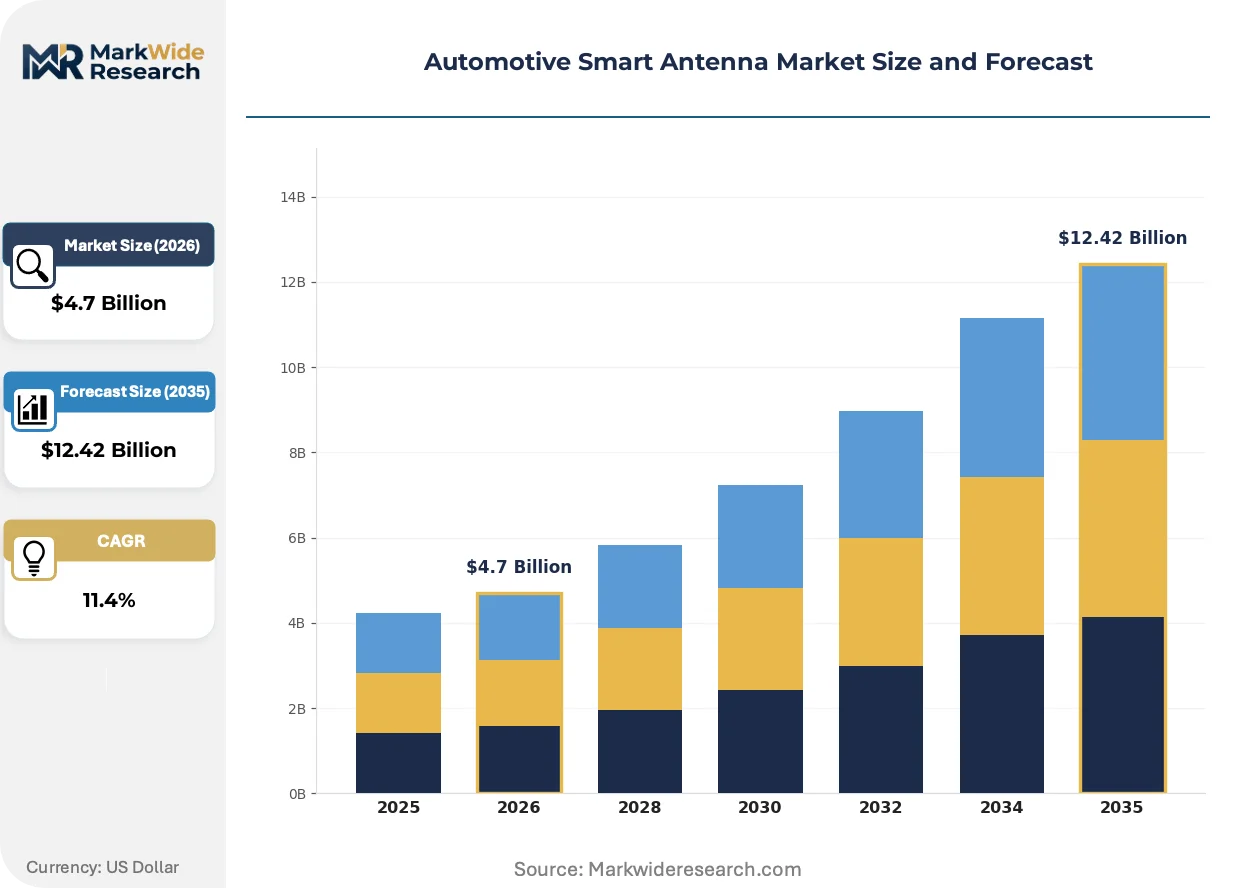
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Antennas, Cellular Antennas, Bluetooth Antennas, Satellite Antennas Technology: Active Technology, Passive Technology, MIMO Technology, Beamforming Technology End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Integrated Installation, External Mounting, Embedded Systems, Standalone Units |
| Companies Covered | Robert Bosch GmbH, HELLA GmbH, Continental AG, Harada Industry, Harman International, DENSO Corporation, Ficosa International, NXP Semiconductors, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Antenna Market Emerging Trajectories
Digital beamforming chipsets are compressing antenna form factors while expanding frequency coverage, enabling roofline consolidation that was physically impossible with passive element designs three years ago.
Integrated antenna-RF modules are digitizing vehicle connectivity stacks by embedding baseband processing directly at the aperture. German premium OEMs now specify these modules for 2027 platform launches. The technology is digitizing supplier value capture from discrete component sales toward firmware-licensing models.
China's MIIT enforcement of GB/T protocol compliance for domestic V2X deployments is fragmenting certification pathways. Suppliers serving multiple geographies must maintain parallel test labs in Shanghai, Munich, and Detroit. The regulation most impacts active antenna segments where firmware modifications trigger re-certification.
Fleet operators are unbundling antenna hardware from telematics service contracts, purchasing modules directly from Tier-1 suppliers rather than through OEM captive channels. This disintermediation is most visible in North American commercial vehicle segments where logistics companies specify open-architecture connectivity stacks. The shift compresses OEM margin capture while expanding aftermarket antenna replacement cycles.
Automotive Smart Antenna Market Segmentation
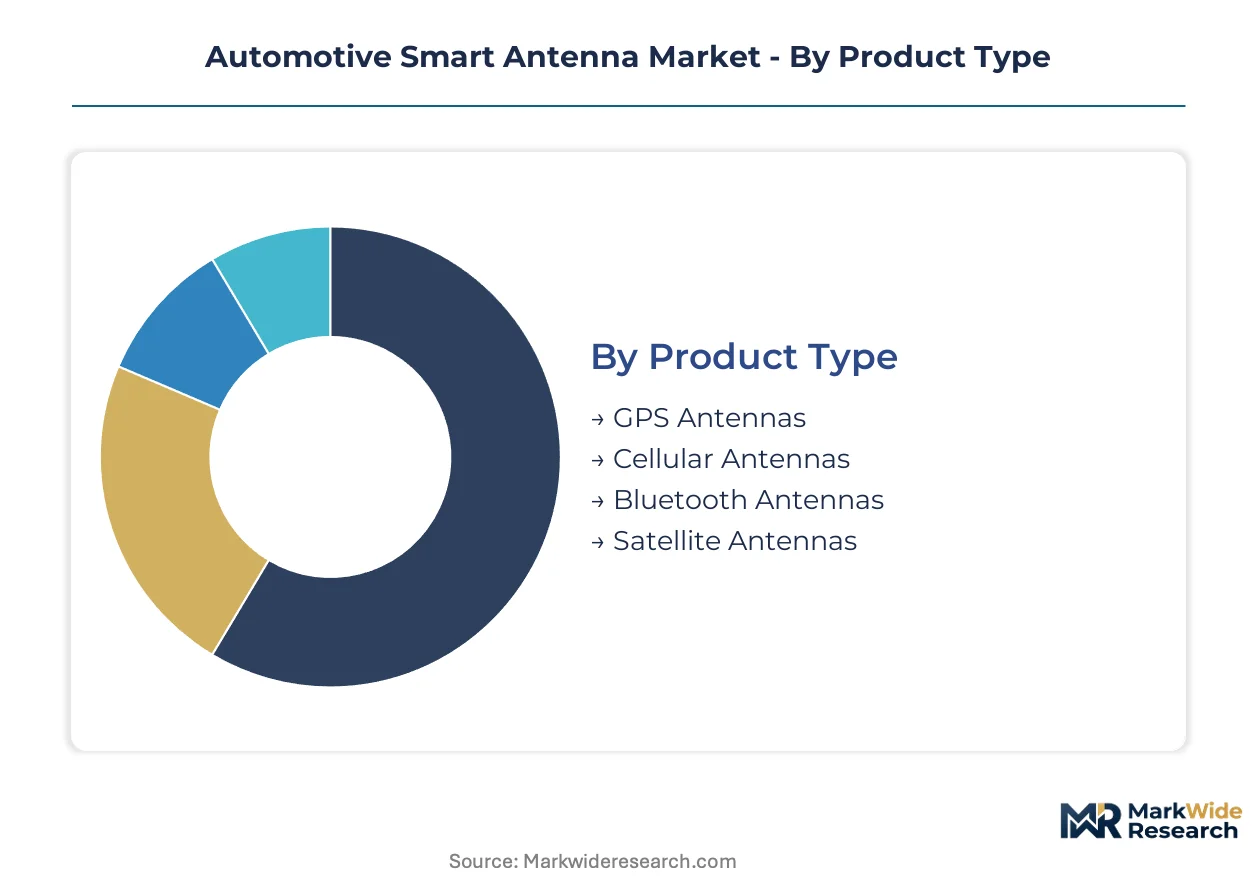
Automotive smart antenna segmentation reflects divergent replacement cycles across product categories. Cellular modules refresh every 3-4 years with protocol upgrades, while satellite positioning hardware maintains 7-10 year lifecycles in vehicle programs.
Product Type:
Replacement velocity separates this category sharply—cellular antennas turn over fastest as 5G modules displace 4G hardware, while satellite systems persist across multiple platform generations.
- Cellular Antennas:Multi-band 5G modules with embedded low-noise amplifiers dominate current OEM build specifications. South Korean and German electric vehicle platforms specify these as standard roofline equipment to maintain highway-speed link integrity for connected-car services.
- GPS Antennas:Dual-frequency L1/L5 receivers with ceramic patch elements provide centimeter-level positioning for autonomous navigation stacks. Demand concentrates in German premium OEM programs where sensor fusion requirements mandate high-availability satellite fixes.
- Bluetooth Antennas:Compact 2.4 GHz PCB trace designs enable smartphone pairing and keyless entry systems. Japanese OEMs embed these in mirror housings for reduced cable routing complexity.
- Satellite Antennas:S-band and L-band apertures support emergency calling and over-the-air update backhaul. Long procurement cycles characterize this segment due to extended vehicle platform lifespans.
Cellular antennas anchor the volume base while satellite systems gain share at the steepest rate through emergency-services mandates.
Technology:
Cost tier stratification defines competitive positioning—passive designs compete on unit economics while active variants capture margin through firmware IP.
- Active Technology:Digitally controlled impedance matching and embedded amplification compensate for vehicle body shadowing. Proprietary beamforming algorithms lock suppliers into recurring calibration service contracts.
- MIMO Technology:Spatial multiplexing arrays with 4×4 and 8×8 configurations enable autonomous sensor backhaul. South Korean battery-electric architectures specify these for V2X communication redundancy.
- Passive Technology:Simple radiating elements without active electronics serve cost-sensitive vehicle programs. Chinese domestic OEMs specify these for entry-level electric vehicle variants.
- Beamforming Technology:Phased-array chipsets dynamically steer radiation patterns toward cellular base stations. German premium OEMs specify these for 2027 platform launches.
Passive technology anchors the volume base while MIMO configurations gain share at the steepest rate through autonomous vehicle sensor fusion requirements.
End User:
Customer type determines contract structure—OEMs demand multi-year supply agreements while aftermarket channels favor spot purchasing.
- OEMs:Vehicle manufacturers specify smart antenna arrays at the platform design stage with 5-7 year supply commitments. German and Japanese premium brands mandate multi-protocol V2X compliance in build specifications.
- Tier-1 Suppliers:Integrated module producers consolidate RF, baseband, and antenna functions for delivery to vehicle assemblers. Continental AG and Robert Bosch GmbH dominate European sourcing channels.
- Aftermarket Providers:Independent distributors serve fleet operators and collision repair networks. North American logistics companies increasingly specify open-architecture connectivity stacks directly.
- Vehicle Assemblers:Contract manufacturers integrate antenna modules during final assembly sequences. South Korean production facilities maintain captive antenna calibration capabilities.
OEMs anchor the volume base while aftermarket providers gain share at the steepest rate through fleet operator disintermediation.
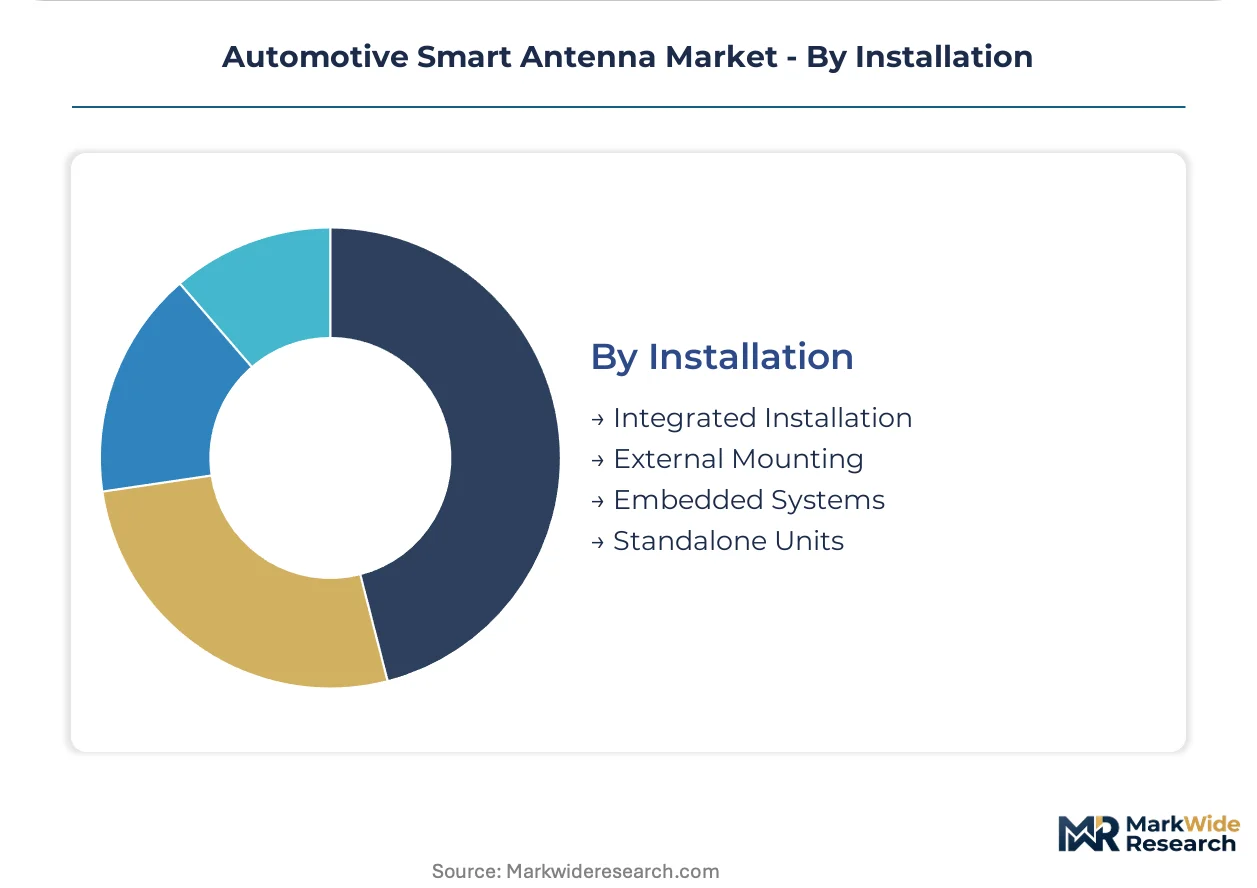
Installation:
Application geometry drives form factor selection—roofline consolidation favors embedded systems while service accessibility preserves standalone variants.
- Embedded Systems:Multi-function modules integrate cellular, satellite, and V2X apertures within single housings. Electric vehicle architectures specify these for aerodynamic roofline packaging.
- Integrated Installation:Antenna functions merge with existing vehicle components such as windscreens and rear spoilers. German OEMs embed cellular elements in heated windscreen laminates.
- External Mounting:Shark-fin and blade-style housings mount on vehicle roof panels. Traditional designs persist in commercial vehicle segments for service accessibility.
- Standalone Units:Discrete antenna modules connect via coaxial cabling to central processing units. Aftermarket retrofits and legacy vehicle upgrades favor this approach.
External mounting anchors the volume base while embedded systems gain share at the steepest rate through electric vehicle platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for gallium arsenide and silicon germanium LNAs clusters in Taiwan and South Korea, exposing antenna manufacturers to allocation risk while German and Japanese OEMs accelerate multi-band array adoption.
United States
FCC Part 90 emission mask requirements govern DSRC and C-V2X certification timelines for cross-border vehicle platforms. Fleet operators in North American commercial vehicle segments increasingly specify open-architecture connectivity stacks directly from Tier-1 suppliers. Detroit maintains captive antenna calibration capabilities for domestic OEM production facilities.
Germany
Premium passenger vehicle OEMs specify multi-band smart antenna arrays as standard equipment for battery-electric vehicle roofline mounting positions. KBA vehicle-type approval frameworks embed V2X communication requirements into connected-car platforms. Bavaria anchors Continental AG's in-house RF module production for European OEM programs.
China
MIIT dual carbon goals accelerate domestic V2X infrastructure rollout mandates requiring GB/T protocol compliance. Parallel testing requirements force suppliers serving multiple geographies to maintain test labs in Shanghai alongside Munich and Detroit facilities. Yangtze River Delta clusters host localized antenna suppliers capturing captive demand from domestic OEMs.
South Korea
Battery-electric architectures specify MIMO configurations with 4×4 and 8×8 arrays for V2X communication redundancy. MFDS-equivalent automotive electronics standards shape certification pathways for embedded RF modules. Seoul Capital Area production facilities integrate antenna modules during final assembly sequences with captive calibration capabilities.
Japan
METI standards influence multi-protocol antenna designs competing for premium mounting positions on electric vehicle rooflines. Compact 2.4 GHz PCB trace designs enable smartphone pairing systems embedded in mirror housings for reduced cable routing complexity. Kansai and Nagoya industrial corridors concentrate supplier engineering centers serving domestic OEM build specifications.
Automotive Smart Antenna Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between consolidated Tier-1 module producers and fragmented RF semiconductor foundries. Three archetypes dominate: integrated module producers consolidating RF, baseband, and antenna functions; active technology specialists capturing margin through proprietary firmware IP; and passive component suppliers competing on unit economics for cost-sensitive programs. Competitive moves center on backward integration into RF semiconductor sourcing and geographic expansion into India's PLI scheme incentives.
Among Germany-based fabricators, Robert Bosch GmbH, Continental AG, and HELLA GmbH exemplify the integrated module producer archetype. Bosch occupies a position anchoring smart antenna portfolios through sensor fusion integration. Continental represents the design-to-delivery cycle specialist with in-house RF module production capabilities. HELLA exemplifies compact multi-protocol design specialists competing for premium electric vehicle roofline mounting positions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| HELLA GmbH |
| Continental AG |
| Harada Industry |
| Harman International |
| DENSO Corporation |
| Ficosa International |
| NXP Semiconductors |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Undercapacity at Taiwan and South Korea gallium arsenide foundries is compressing lead times for low-noise amplifiers and forcing antenna manufacturers into premium pricing postures for active technology segments. This utilization squeeze cascades through Tier-1 supplier negotiations with German and Japanese OEMs, embedding cost-plus escalation clauses into multi-year platform supply agreements.
Pricing Analysis
ETSI EN 302 571 and FCC Part 90 emission mask requirements dictate the pricing tier structure across active, MIMO, and passive technology segments. Certification-grade differentiation separates premium active antenna modules with embedded beamforming firmware from standard passive designs serving Chinese entry-level electric vehicle programs. Cost compression in passive tiers is intensifying because domestic OEMs in China are consolidating procurement volumes around standardized multi-band arrays. Fleet operators in North American commercial vehicle segments exhibit the highest price sensitivity as they disintermediate OEM captive channels for direct Tier-1 sourcing.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs are squeezing working capital at RF semiconductor foundries in Taiwan and South Korea. The supply chain draws from gallium arsenide substrates, silicon germanium wafers, and ceramic patch elements for GPS receivers. Single-source vulnerability clusters around TSMC-equivalent capacity for automotive-grade LNAs. Distribution runs through Tier-1 module producers consolidating RF, baseband, and antenna functions for delivery to vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
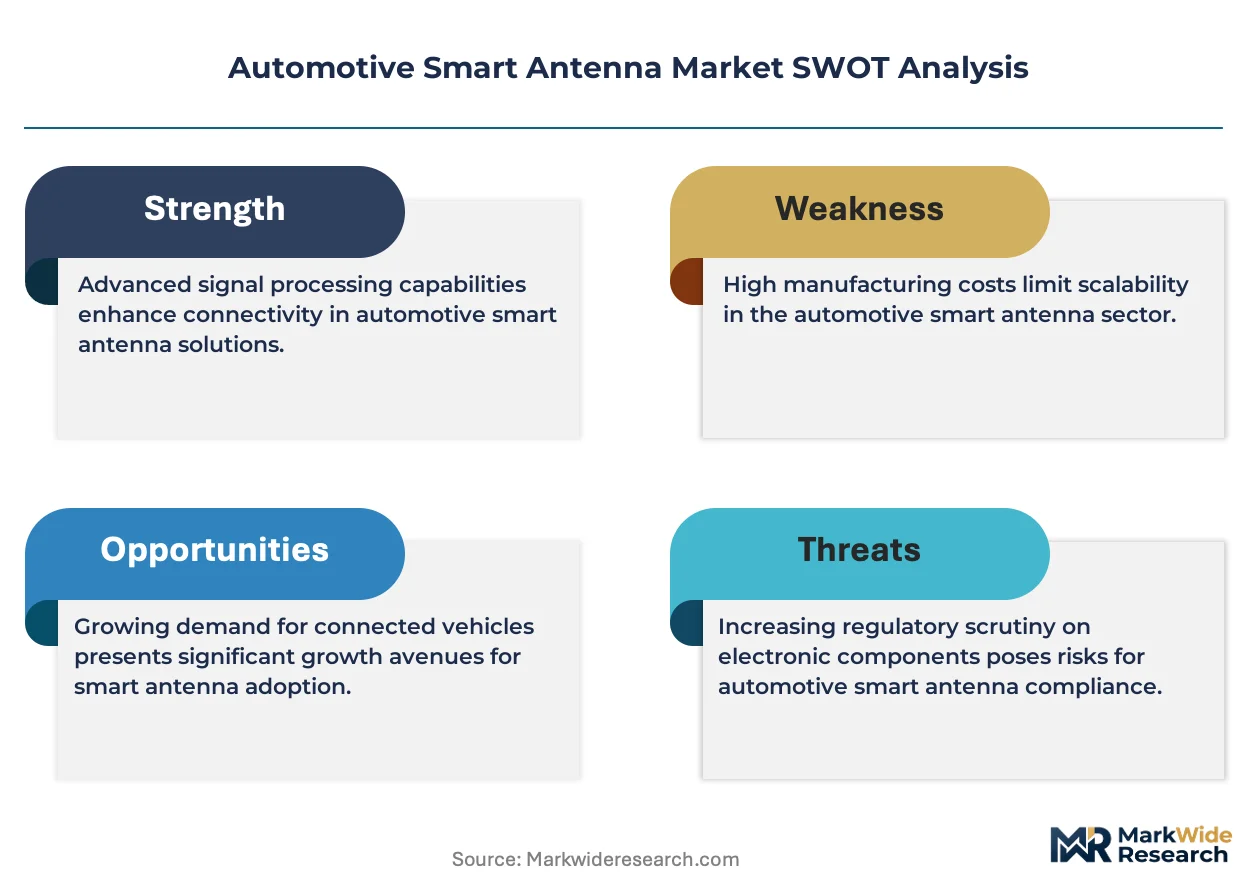
The automotive smart antenna market is accelerating through the EU Green Deal's digital-mobility mandates and China's MIIT V2X infrastructure rollout, creating a regulatory-inflected growth window for embedded MIMO architectures.
For Market Incumbents: Entrench firmware IP advantages by deepening calibration service contracts with German premium OEMs and securing captive gallium arsenide foundry allocation in Taiwan. Threat substitution from open-architecture connectivity stacks demands accelerated backward integration into RF semiconductor sourcing to defend margin position against fleet operator disintermediation. For New Entrants and Emerging Players: Build out localized production footprints in India's PLI scheme corridors to capture advanced driver-assistance system incentives and serve domestic OEM electrification programs. The most penetrable white space sits in aftermarket open-architecture modules for North American logistics fleets, accessed through direct telematics service bundling rather than OEM channel dependence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among active technology specialists with proprietary beamforming algorithms and multi-protocol certification capabilities. Long-term viability over the coming decade hinges on software-defined vehicle convergence and antenna-as-a-service model adoption. Watch for inflection signals in GB/T protocol compliance mandates accelerating captive demand for China-localized suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Antenna-as-a-service models bundling OTA calibration updates capture recurring revenue from German OEM 2027 platform launches. |
| Backward Integration into RF Semiconductors | In-house gallium arsenide LNA production insulates Tier-1 suppliers from Taiwan foundry allocation risk. |
| Geographic Manufacturing Footprint | India PLI scheme incentives for ADAS create entry points for domestic RF module production serving localized OEM demand. |
| Platform Standardization | Multi-protocol V2X compliance across DSRC and C-V2X variants reduces parallel certification burden for cross-border vehicle programs. |
| Battery Supply Agreement | South Korean electric vehicle architectures specify MIMO antenna arrays as standard roofline equipment, anchoring volume commitments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, regulatory filings with ETSI and FCC, and customs trade records for RF semiconductor flows. Primary interviews engaged Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers across Germany, Japan, South Korea, China, and the United States. Bottom-up unit economics modeling triangulates against top-down market sizing from vehicle build specification analysis.
Forecast inputs include vehicle class stratification, propulsion architecture differentiation between battery-electric and internal combustion platforms, content per vehicle trajectories for antenna module consolidation, and regional production cluster capacity expansion plans. CAGRs across the analysis window derive from segment-level volume projections calibrated to OEM platform launch timelines and regulatory mandate crystallization dates. Industry-specific inputs incorporate V2X infrastructure deployment schedules and spectrum reallocation proceedings in major automotive markets.
Stress conditions across gallium arsenide foundry utilization, dual-protocol certification timeline compression, and fleet operator disintermediation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate adherence and OEM software-defined vehicle roadmap execution. Macroeconomic contraction, accelerated spectrum reallocation, or breakthrough in satellite-to-vehicle direct communication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market