
 PET Radiotracer Market | 2026-2036
PET Radiotracer Market Size, Share, and Industry Trends Forecast 2026-2036
PET Radiotracer Market Outlook
Good Manufacturing Practice (GMP) certification for cyclotron-produced isotopes is unwinding legacy supply constraints across the PET radiotracer value chain. GE Healthcare leverages its integrated cyclotron and distribution network to sustain same-day delivery capabilities for short-lived Fluorine-18 compounds. Cardinal Health anchors hospital-centric procurement through centralized radiopharmacy operations spanning major metropolitan corridors. Lantheus Holdings differentiates via specialized manufacturing scale for Gallium-68 based theranostic pairs.
PET radiotracers are positron-emitting chemical compounds labeled with radioisotopes such as Fluorine-18, Carbon-11, or Gallium-68, synthesized in cyclotron or generator systems for in vivo molecular imaging with half-lives ranging from 68 minutes to 110 minutes. Their primary purpose is enabling non-invasive visualization of metabolic processes, receptor expression, and pathological biomarkers at the cellular level for diagnostic and treatment-monitoring decisions. Fluorine-18 products occupy the dominant revenue position due to established reimbursement for FDG-PET across oncology staging protocols, while Gallium-68 segments are recording the fastest expansion as theranostic applications in prostate cancer imaging gain clinical traction. Application concentration in oncology reflects mature reimbursement infrastructure, though neurology represents an emerging margin pool amid amyloid and tau tracer development for Alzheimer's disease characterization.
The FDA governs radiopharmaceutical manufacturing under 21 CFR Part 212 current good manufacturing practice standards, while the Nuclear Regulatory Commission enforces dose calibration and handling protocols that shape facility licensing requirements and operational costs. The European Medicines Agency's centralized marketing authorization process for radiopharmaceuticals creates divergent market access timelines compared with the US pathway, affecting multinational deployment strategies. Stakeholders must monitor evolving theranostic reimbursement frameworks and cyclotron capacity buildouts to align manufacturing investments with shifting clinical demand patterns.
Market Dynamics
Short half-life isotopes concentrate production within 300-mile delivery radii, binding facility location to patient density and cyclotron capital deployment decisions. This geographic coupling shapes competitive entry barriers and margin structures across the value chain.
Growth Catalysts
- 21 CFR Part 212 GMP harmonization:FDA alignment with ICH Q7 standards reduces multi-site compliance overhead for cross-border tracer distribution.
- Theranostic protocol expansion:Gallium-68 PSMA-11 pairing with Lutetium-177 therapy creates diagnostic-treatment revenue stacking in prostate cancer care pathways.
- Academic medical center oncology investment:Precision tumor characterization programs drive PET-CT scanner procurement and tracer volume commitments.
Market Restraints
- Cyclotron supply concentration:North American and Western European facility density leaves Latin America, Africa, and Southeast Asia dependent on air-freight imports with decay-compromised yields.
- Molybdenum-99 generator dependency:Technetium-99m availability disruptions cascade into Gallium-68 generator production scheduling constraints.
- Reimbursement lag for novel tracers:Medicare National Coverage Determination timelines extend 18-24 months beyond FDA approval, compressing commercialization windows.
Strategic Opportunities
- India cyclotron buildout:BIS radiopharmaceutical licensing streamlines and PLI scheme capital subsidies attract manufacturing investment for regional tracer supply.
- Alzheimer's disease imaging protocols:Amyloid and tau tracer development opens neurology reimbursement categories beyond oncology concentration.
- Centralized radiopharmacy networks:Hub-and-spoke distribution models with satellite pharmacy satellites extend same-day Fluorine-18 coverage into secondary markets.
Industry Challenges
- Qualified personnel scarcity:Radiochemist and nuclear pharmacist training pipelines lag cyclotron facility expansion schedules.
- Multi-agency compliance synchronization:FDA 21 CFR Part 212, NRC dose calibration, and DOT radioactive materials transport permitting create timeline coordination friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Radiotracer Market |
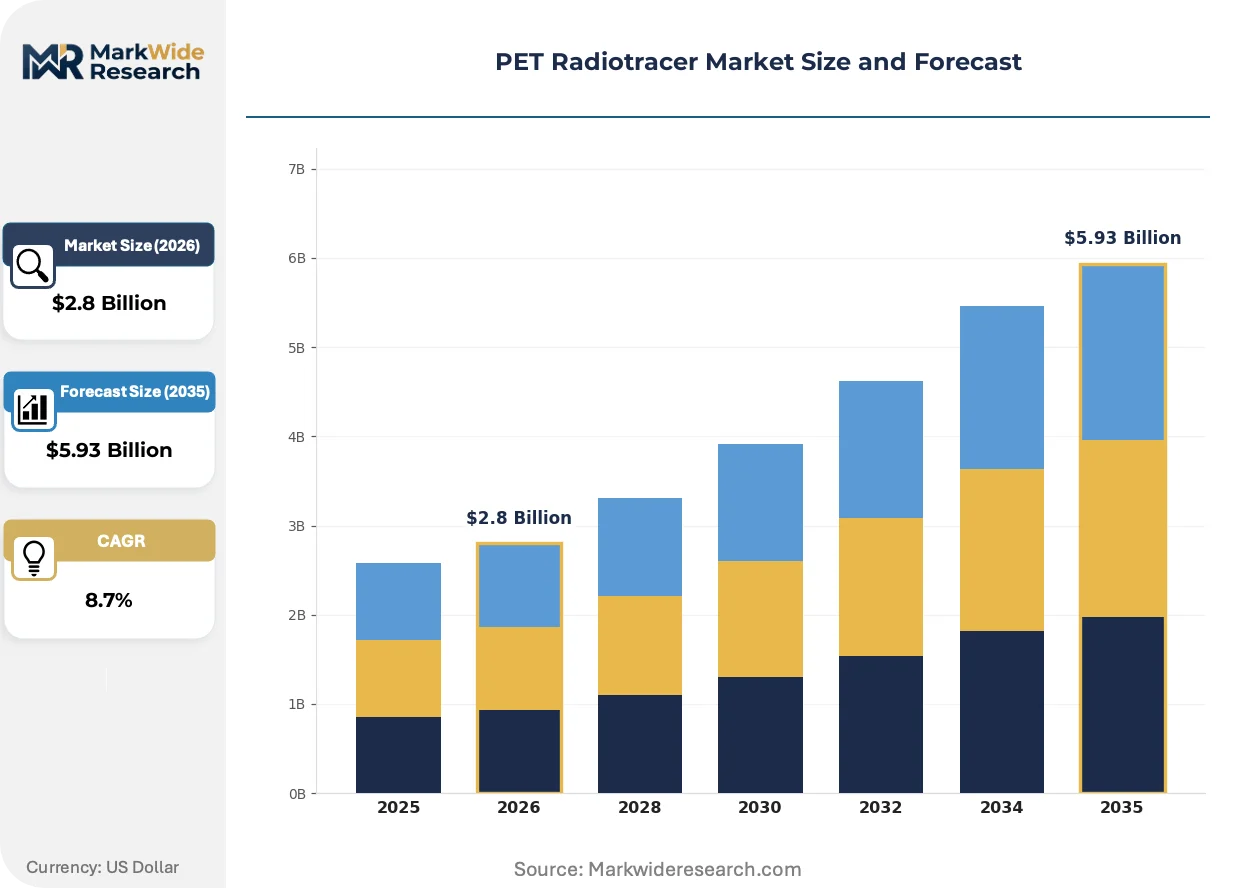
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
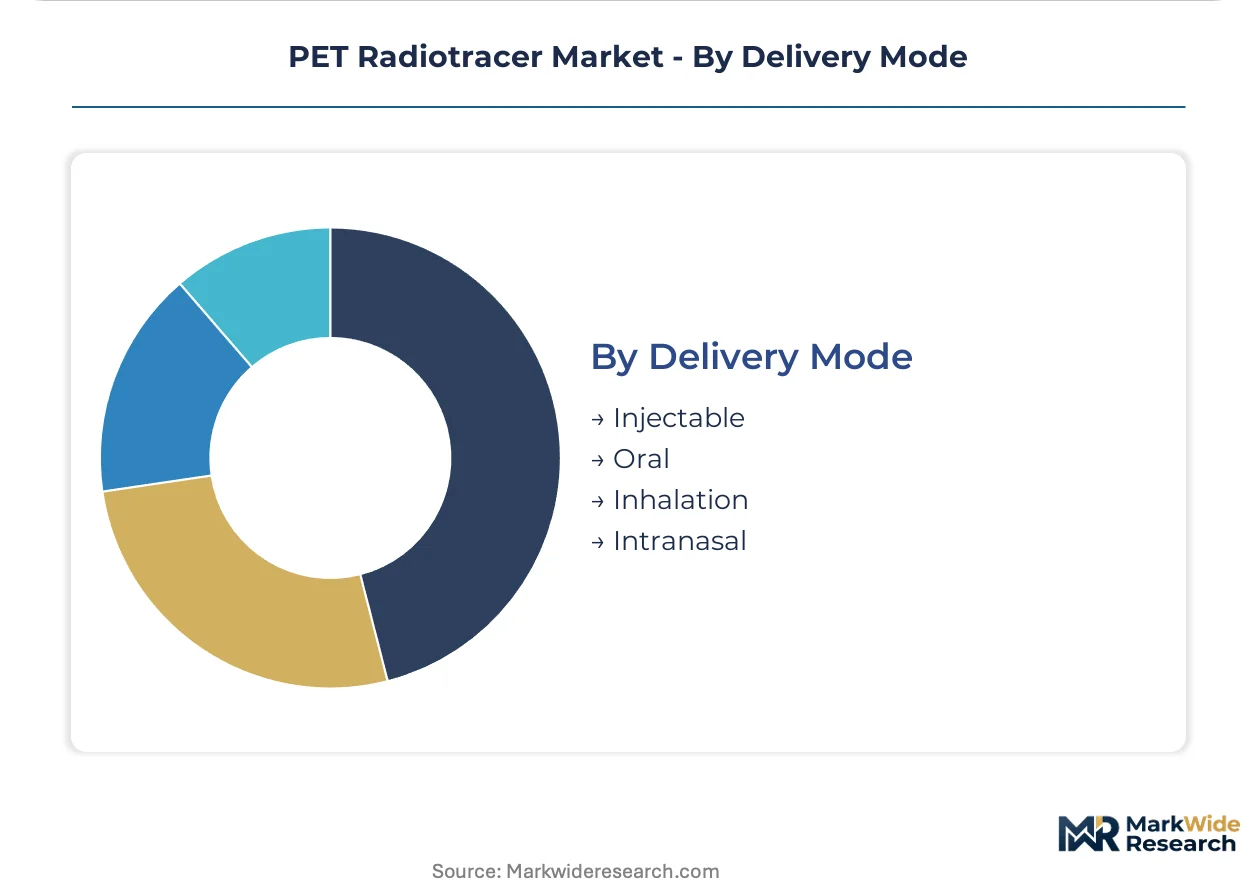
| Segmentation | Product Type: Fluorine-18, Carbon-11, Gallium-68, Iodine-124 Application: Oncology, Cardiology, Neurology, Infection Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Centers Delivery Mode: Injectable, Oral, Inhalation, Intranasal |
| Companies Covered | Blue Earth Diagnostics, ABX advanced biochemical compounds GmbH, Cardinal Health, GE Healthcare, Lantheus Holdings, IBA Radiopharma Solutions, Jubilant Pharma Limited, Siemens Healthineers AG, Yantai Dongcheng Pharmaceutical Group Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Radiotracer Market Strategic Shifts
Automation and isotope production diversification are compressing traditional supply constraints while regulatory frameworks adapt to theranostic convergence. These forces reshape facility economics and competitive positioning simultaneously.
Automated synthesis modules for Gallium-68 radiolabeling are displacing manual hot-cell operations in hospital-based radiopharmacies. Community oncology centers and mid-sized hospitals deploy these systems to bypass centralized supplier dependencies. This diffusion is fragmenting procurement relationships and compressing margins for traditional radiopharmacy operators.
EMA centralized marketing authorization for radiopharmaceuticals diverges from FDA's decentralized review pathway, creating asynchronous market entry timelines. European manufacturers face extended centralized assessment periods while US competitors secure earlier commercial traction. This regulatory asynchrony forces multinational firms to sequence geographic launches strategically rather than simultaneously.
Hospital procurement committees now bundle PET-CT scanner acquisitions with multi-year tracer supply agreements, locking in volume commitments and pricing floors. Equipment vendors and radiopharmacy operators form captive partnerships to secure these bundled contracts. This consolidation concentrates purchasing power in United States academic medical centers and integrated delivery networks.
PET Radiotracer Market Segmentation

Segmentation in PET radiotracers reveals how isotope half-lives, reimbursement pathways, and facility infrastructure create divergent competitive dynamics across product categories. Understanding these fault lines illuminates where substitution pressures and margin compression concentrate most intensely.
Product Type:
Substitution pressure runs highest against Carbon-11 and Iodine-124 products, where ultra-short half-lives limit distribution economics and drive customers toward more logistically tractable alternatives.
- Fluorine-18:This isotope delivers 109.8-minute half-life stability that enables same-day regional distribution without decay-compromised yields. Oncology departments at US academic medical centers anchor demand through FDG-PET staging protocols with established Medicare reimbursement. Cyclotron network density in the United States sustains per-capita consumption rates unmatched elsewhere.
- Gallium-68:Generator-produced Gallium-68 eliminates cyclotron dependency for end-users, enabling hospital-based radiopharmacies to synthesize PSMA-11 and DOTATATE tracers on-site. Theranostic pairing with Lutetium-177 therapy in prostate cancer care pathways concentrates demand at US integrated delivery networks building diagnostic-treatment revenue stacks.
- Carbon-11:Twenty-minute half-life restricts this isotope to on-site cyclotron production, binding usage to major research institutions with captive synthesis capabilities.
- Iodine-124:Four-day half-life suits longitudinal immuno-PET studies but requires specialized dosimetry infrastructure that limits adoption to select research hospitals.
Fluorine-18 retains volume leadership; Gallium-68 holds the steepest expansion curve.
Application:
Cost tier stratification separates mature reimbursement categories from emerging indications still negotiating coverage determinations.
- Oncology:Tumor characterization, staging, and treatment monitoring consume the majority of PET tracer volumes through FDG-PET for lung, lymphoma, and colorectal malignancies. US Medicare National Coverage Determinations create predictable reimbursement that academic medical centers leverage for scanner procurement and tracer volume commitments.
- Neurology:Amyloid and tau tracer development for Alzheimer's disease characterization opens margin pools beyond oncology concentration as FDA approves novel diagnostics for cognitive impairment workups. US memory disorder clinics and academic neurology departments drive early adoption amid evolving CMS coverage policies.
- Cardiology:Myocardial perfusion imaging with Rubidium-82 and ammonia N-13 tracers serves coronary artery disease assessment, though SPECT competition limits PET penetration.
- Infection Imaging:FDG-PET applications in fever of unknown origin and prosthetic joint infection remain niche indications with variable payer coverage.
Oncology commands the revenue base; neurology is climbing the fastest toward commercial scale.
End User:
Customer type determines procurement sophistication, with integrated delivery networks extracting volume pricing that fragments margin structures.
- Hospitals:Academic medical centers and community hospitals with PET-CT capabilities represent the core consumption base, particularly those with captive cyclotron or generator infrastructure. US hospital procurement committees now bundle scanner acquisitions with multi-year tracer supply agreements.
- Diagnostic Centers:Independent imaging facilities concentrate in US metropolitan corridors with dense Medicare beneficiary populations, relying on centralized radiopharmacy networks for Fluorine-18 delivery.
- Research Institutions:National laboratories and university medical centers drive Carbon-11 and novel tracer development under NIH grant funding cycles.
- Imaging Centers:Outpatient facilities with PET-CT capabilities serve oncology practices without hospital-based imaging, particularly in US suburban markets.
Hospitals retain volume leadership; diagnostic centers hold the steepest expansion curve.
Delivery Mode:
Supply concentration in parenteral administration creates barriers to alternative route development despite patient convenience advantages.
- Injectable:Intravenous administration dominates PET imaging through rapid systemic distribution and precise dose calibration. US nuclear pharmacy operations under NRC licensing standardize injectable preparation protocols.
- Oral:Limited applications include FDG for brain metabolism studies where blood-brain barrier penetration timing matters.
- Inhalation:Oxygen-15 labeled gases for pulmonary perfusion and ventilation studies remain confined to research settings with specialized delivery apparatus.
- Intranasal:Experimental routes for brain-targeted tracers face pharmacokinetic validation hurdles before clinical translation.
Injectable administration retains volume leadership; alternative routes face the steepest technical barriers to expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss radiopharmaceutical manufacturers export Gallium-68 generators and Fluorine-18 compounds to Middle Eastern and Latin American markets where cyclotron infrastructure remains sparse. Air-freight logistics with decay-managed cold chains determine viable delivery radii for these short-half-life products.
United States
Medicare reimbursement policies for FDG-PET oncology staging sustain per-capita consumption rates unmatched elsewhere. FDA 21 CFR Part 212 GMP standards govern manufacturing compliance across cyclotron-equipped academic medical centers. The Boston-Cambridge corridor anchors tracer innovation through NIH-funded research institutions developing novel amyloid and tau diagnostics.
Germany
EMA centralized marketing authorization procedures create extended assessment timelines for novel radiopharmaceuticals compared with US pathways. The country's national pharmaceutical regulator enforces batch release protocols that shape multi-site manufacturing economics. Baden-Württemberg hosts concentrated cyclotron networks serving precision oncology programs at university hospitals.
India
BIS radiopharmaceutical licensing streamlines and PLI scheme capital subsidies attract manufacturing investment for regional tracer supply. CDSCO approval pathways for diagnostic radiopharmaceuticals are converging with international standards under revised medical device rules. Maharashtra and Gujarat are building cyclotron capacity to reduce import dependency for Fluorine-18 compounds.
Japan
PMDA review timelines for novel PET tracers have compressed through priority review voucher programs for neurological diagnostics. METI industrial policy supports domestic isotope production to secure supply chain resilience. The Kanto region around Tokyo maintains the highest cyclotron density per capita for Carbon-11 research applications.
Switzerland
Swissmedic marketing authorization procedures for theranostic pairs enable synchronous diagnostic-therapy product launches. The country's pharmaceutical manufacturing heritage attracts Gallium-68 specialist operations serving European hospital networks. Basel and Zurich anchor radiochemistry expertise clusters supporting multinational tracer development programs.
PET Radiotracer Market Competitive Environment
Listed leaders compete with private specialists across cyclotron infrastructure and radiopharmacy network coverage. The market structure concentrates around integrated healthcare conglomerates with captive isotope production, mid-sized radiopharmacy operators with regional hub-and-spoke distribution, and specialized theranostic developers with generator-based manufacturing. Competitive moves center on strategic partnerships for scanner-tracer bundled procurement and backward integration into cyclotron manufacturing.
Within the integrated healthcare tier, GE Healthcare and Siemens Healthineers exemplify equipment-tracer convergence strategies. Cardinal Health occupies a position as a radiopharmacy network anchor with centralized distribution capabilities. Lantheus Holdings represents the theranostic specialization archetype with Gallium-68 manufacturing scale.
| Leading Market Players |
|---|
| Blue Earth Diagnostics |
| ABX advanced biochemical compounds GmbH |
| Cardinal Health |
| GE Healthcare |
| Lantheus Holdings |
| IBA Radiopharma Solutions |
| Jubilant Pharma Limited |
| Siemens Healthineers AG |
| Yantai Dongcheng Pharmaceutical Group Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Ninety-minute half-life constraints compress order-to-delivery windows to same-day fulfillment cycles, binding pricing power to cyclotron proximity and forcing premium markups on air-freight imports outside 300-mile production radii. This geographic coupling concentrates margin capture among US academic medical centers with captive isotope production while exposing import-dependent markets to decay-driven yield losses and elevated procurement costs.
Pricing Analysis
Hospital procurement committees anchor contract pricing through multi-year scanner-tracer bundled agreements that lock volume commitments and pricing floors. Three-tier pricing structure across premium theranostic pairs, standard FDG oncology protocols, and economy research-grade tracers differentiates based on GMP certification tier and cold-chain reliability. Pricing pressure stems from automated Gallium-68 synthesis modules displacing centralized supplier relationships at mid-sized hospitals. Community oncology centers exhibit highest price sensitivity due to Medicare reimbursement lag, while integrated delivery networks with captive cyclotrons demonstrate lowest sensitivity through backward integration into isotope production.
Supply Chain Analysis
Just-in-time production protocols dominate Fluorine-18 distribution, with hospital-based radiopharmacies maintaining minimal inventory due to 109.8-minute half-life decay curves. Supply concentrates in the United States, Germany, and Switzerland through cyclotron-equipped academic medical centers and specialized radiopharmacy networks. Raw material dependencies include enriched water for Fluorine-18 targets, Molybdenum-99 generators for Gallium-68 extraction, and specialized synthesis cassettes for automated radiolabeling. Single-source vulnerability in Molybdenum-99 reactor supply creates cascading scheduling constraints for generator-dependent facilities. Distribution runs through hub-and-spoke radiopharmacy networks with satellite pharmacy satellites extending same-day coverage into secondary metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Theranostic protocol convergence is transforming PET radiotracers from diagnostic commodities into platform-anchored care pathways, with diagnostic-treatment revenue stacking creating ecosystem lock-in comparable to pharmaceutical companion diagnostic models.
For Market Incumbents: Shield installed base relationships by deepening backward integration into cyclotron manufacturing and securing exclusive multi-year supply agreements with academic medical centers expanding precision oncology programs. Automated synthesis module proliferation at community hospitals threatens centralized radiopharmacy margins; incumbents should deploy satellite pharmacy networks to extend geographic coverage and retain volume commitments. FDA 21 CFR Part 212 GMP certification investments create regulatory moats against non-compliant regional competitors. For New Entrants and Emerging Players: CDSCO fast-track pathways for diagnostic radiopharmaceuticals under India's revised medical device rules offer accelerated market entry for regional tracer supply. Target Maharashtra and Gujarat cyclotron buildouts where PLI scheme capital subsidies reduce facility deployment costs and BIS licensing streamlines manufacturing authorization. White-space concentration in neurology amyloid and tau tracers for Alzheimer's disease characterization offers penetration opportunity ahead of CMS coverage determination finalization. Go-to-market positioning should emphasize hospital-based automated synthesis partnerships bypassing centralized distributor dependencies. For Investors and Strategic Acquirers: Long-term, this sits as a theranostic platform play because diagnostic-treatment pairing in prostate cancer care pathways creates recurring revenue stacks with higher switching costs than standalone diagnostics. Acquisition target archetype: Gallium-68 specialist manufacturers with established Lutetium-177 therapy partnerships and generator-based production scale. Signal to watch is Medicare National Coverage Determination timeline compression for novel neurology tracers, which would validate amyloid and tau diagnostic categories beyond oncology concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Capacity Buildout | Same-day Fluorine-18 delivery capabilities in secondary US markets reduce import dependency. |
| Theranostic Partnership Formation | Gallium-68 PSMA-11 pairing with Lutetium-177 therapy creates diagnostic-treatment revenue stacking. |
| Automated Synthesis Deployment | Hospital-based Gallium-68 modules displace centralized radiopharmacy dependencies in community oncology. |
| Regulatory Fast-Track Utilization | CDSCO and PMDA priority review pathways compress novel tracer commercialization timelines. |
| Reimbursement Strategy Investment | Medicare National Coverage Determination preparation accelerates FDA-approved tracer adoption. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiochemistry directors at academic medical centers, nuclear pharmacy operations managers, cyclotron facility engineers, hospital procurement committee members, and regulatory affairs specialists at radiopharmaceutical manufacturers. Secondary validation drew from FDA 21 CFR Part 212 filings, EMA centralized marketing authorization submissions, CMS Medicare National Coverage Determination records, and NIH clinical trial registries. Bottom-up tracer volume estimates triangulated against top-down healthcare expenditure allocations across oncology, neurology, and cardiology service lines.
Across the analysis window, forecasts modeled isotope-specific demand trajectories segmented by product type, application concentration, end-user procurement sophistication, and delivery mode infrastructure. CAGRs were derived from facility capacity buildout schedules, reimbursement policy evolution, and theranostic protocol adoption curves. Industry-specific inputs included cyclotron deployment pipelines, generator production forecasts, and radiopharmacy network expansion plans.
Underlying assumptions cover stable Medicare reimbursement for FDG-PET oncology staging, with deviation risk concentrated in Molybdenum-99 generator supply disruptions and qualified radiochemist training pipeline constraints. Revision becomes warranted when automated synthesis module penetration at community hospitals crosses thresholds that structurally fragment centralized supplier relationships.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
North America Nuclear Imaging Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Enterprise Medical Image Viewers Market