
 Central Nervous System (CNS) Therapeutics Market | 2026-2036
Central Nervous System (CNS) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Central Nervous System (CNS) Therapeutics Market Outlook
North American biopharma manufacturing capacity is consolidating around high-complexity biologics for neurological targets. Biogen leverages its established multiple sclerosis franchise to sustain manufacturing scale in the region. Roche Holding AG anchors its CNS portfolio through differentiated antibody engineering capabilities. AbbVie Inc. competes on immunology-neurology crossover pipelines, while Eli Lilly and Company specializes in amyloid-targeting modalities for Alzheimer's disease.
Central Nervous System therapeutics comprise pharmacological agents engineered to modulate neurotransmission, neuroinflammation, or protein aggregation pathways within the brain and spinal cord, typically requiring molecular weights below 500 Da for passive blood-brain barrier penetration or active transport mechanisms for larger biologics. These compounds serve to arrest disease progression, manage symptom burden, or modify underlying pathology in conditions where neuronal function degrades through ischemic, autoimmune, or degenerative mechanisms. Antidepressants and antipsychotics occupy mature margin pools with established generic erosion, while stimulants for attention deficit indications lead volume growth due to expanding diagnostic criteria and pediatric-to-adult patient transitions. Intravenous delivery modes for monoclonal antibodies concentrate value capture among infusion-center networks, whereas oral formulations dominate prescription volume through pharmacy distribution channels.
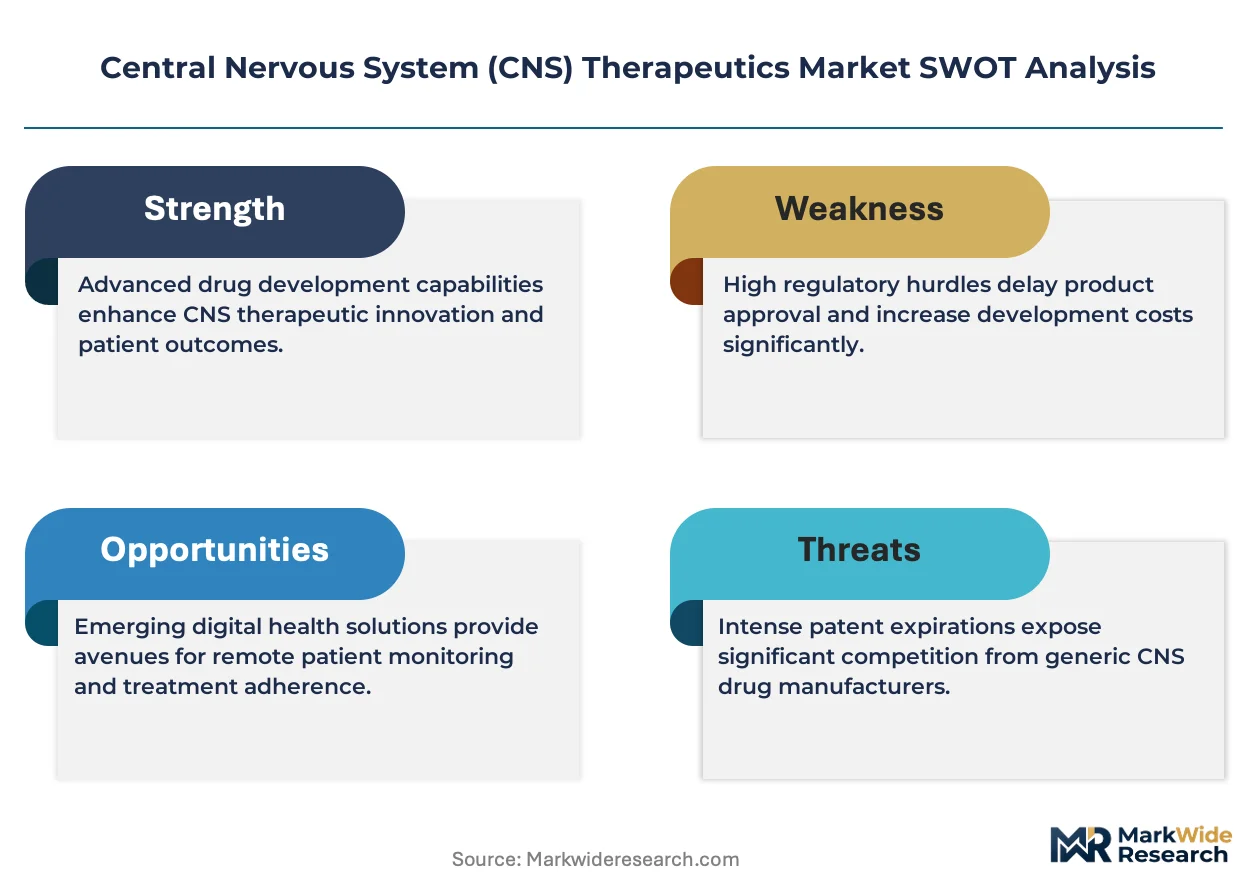
FDA's Breakthrough Therapy designation and EMA's PRIME scheme compress development timelines for novel CNS mechanisms, though both agencies demand rigorous cognitive endpoint validation that extends Phase III durations. The EU AI Act and FDA's emerging guidance on algorithmic diagnostic tools shape how digital biomarkers integrate into trial protocols and reimbursement submissions. Stakeholders must monitor evolving payer evidence requirements for surrogate endpoints versus functional clinical outcomes as regulatory scrutiny intensifies for accelerated approval pathways in neurodegeneration.
Market Dynamics
Gene therapy platforms and blood-brain barrier delivery technologies are compressing traditional small-molecule development cycles while forcing biopharma capital toward high-complexity manufacturing infrastructure. This structural shift rewards firms with integrated antibody engineering and viral vector production capabilities.
Growth Catalysts
- FDA Breakthrough Therapy designation:The pathway accelerates Phase III initiation for novel CNS mechanisms targeting neurodegeneration, compressing time-to-market for amyloid-clearing antibodies.
- Specialty neurology clinic expansion:United States-based infusion networks are scaling capacity to capture intravenous biologic administration, anchoring patient capture for monoclonal antibody franchises.
- Japan's aging demographic concentration:PMDA reimbursement frameworks for dementia therapeutics sustain prescription volume growth as diagnostic criteria expand to capture mild cognitive impairment transitions.
Market Restraints
- Blood-brain barrier penetration physics:Passive diffusion limits molecular weight thresholds to approximately 500 Da, constraining large-molecule biologics to active transport engineering or invasive delivery.
- EU AI Act algorithmic validation requirements:Digital biomarker integration into trial protocols faces extended compliance timelines as cognitive endpoint algorithms require documented training-data transparency.
- Specialized viral vector manufacturing scarcity:AAV and lentiviral production concentrates among contract manufacturers in Massachusetts and North Carolina, creating single-source dependency for gene therapy supply.
Strategic Opportunities
- Germany's EMA PRIME scheme utilization:Early access pathways for neurodegenerative indications offer priority regulatory engagement, enabling smaller biotechs to compress development timelines against established players.
- Convergence of antisense oligonucleotides with CNS-targeted lipid nanoparticles:Hybrid delivery platforms expand addressable genetic targets beyond current viral vector cargo limits.
- Direct-to-patient pharmacy distribution for oral neuropsychiatric formulations:Mail-order channels bypass traditional infusion-center gatekeepers, capturing margin from maintenance therapy prescriptions.
Industry Challenges
- Neuroimaging biomarker standardization gaps:Tau PET and amyloid quantification protocols lack cross-site harmonization, complicating multi-center trial enrollment and data pooling.
- Gene therapy manufacturing capex intensity:GMP-compliant viral vector suites require $200-400 million facility investments with 3-4 year construction timelines, straining mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Nervous System (CNS) Therapeutics Market |
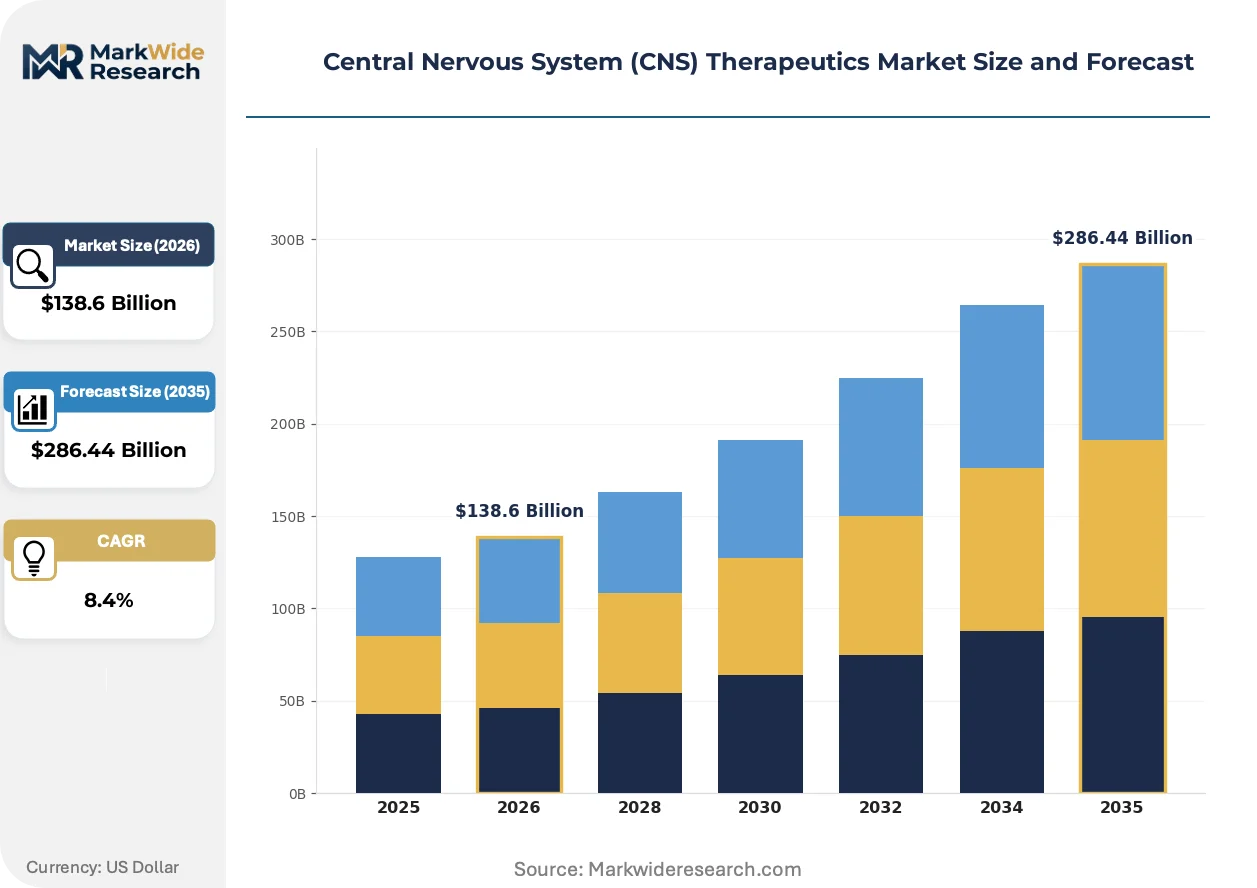
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $286.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Antipsychotics, Stimulants, Anxiolytics Delivery Mode: Oral, Intravenous, Transdermal, Inhalation Indication: Major Depressive Disorder, Schizophrenia, Attention Deficit Hyperactivity Disorder, Generalized Anxiety Disorder End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Biogen, Novartis AG, Pfizer Inc., Johnson & Johnson, Eli Lilly and Company, Roche Holding AG, AbbVie Inc., Takeda Pharmaceutical Company Limited, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Nervous System (CNS) Therapeutics Market Strategic Shifts
Antibody engineering and nucleic acid delivery modalities are fragmenting the traditional small-molecule dominance in neurological targets, while regulatory frameworks race to adapt evidence standards for accelerated approval.
Antisense oligonucleotides targeting superoxide dismutase 1 and huntingtin protein are overtaking small-molecule approaches in inherited neurodegeneration. Academic medical centers in Boston and San Diego are prioritizing these programs for their precision-targeting advantages. The technology is overtaking kinase inhibitor pipelines that previously dominated rare CNS genetic disease portfolios.
EMA's PRIME scheme and FDA's Breakthrough Therapy designation are compressing Phase II-to-III transitions for novel mechanisms. Both agencies now mandate rigorous cognitive endpoint validation that extends trial durations despite accelerated approval eligibility. Neurodegenerative indications in the European Union face heightened scrutiny for surrogate endpoint acceptability versus functional clinical outcomes.
Specialty pharmacy channels are disintermediating traditional hospital outpatient departments for oral CNS maintenance therapies. United States-based payers are steering stable patients toward mail-order fulfillment with 90-day supply incentives. Psychiatric and pain management verticals exhibit the most pronounced channel migration, compressing infusion-center revenue pools to acute biologic administration only.
Central Nervous System (CNS) Therapeutics Market Segmentation
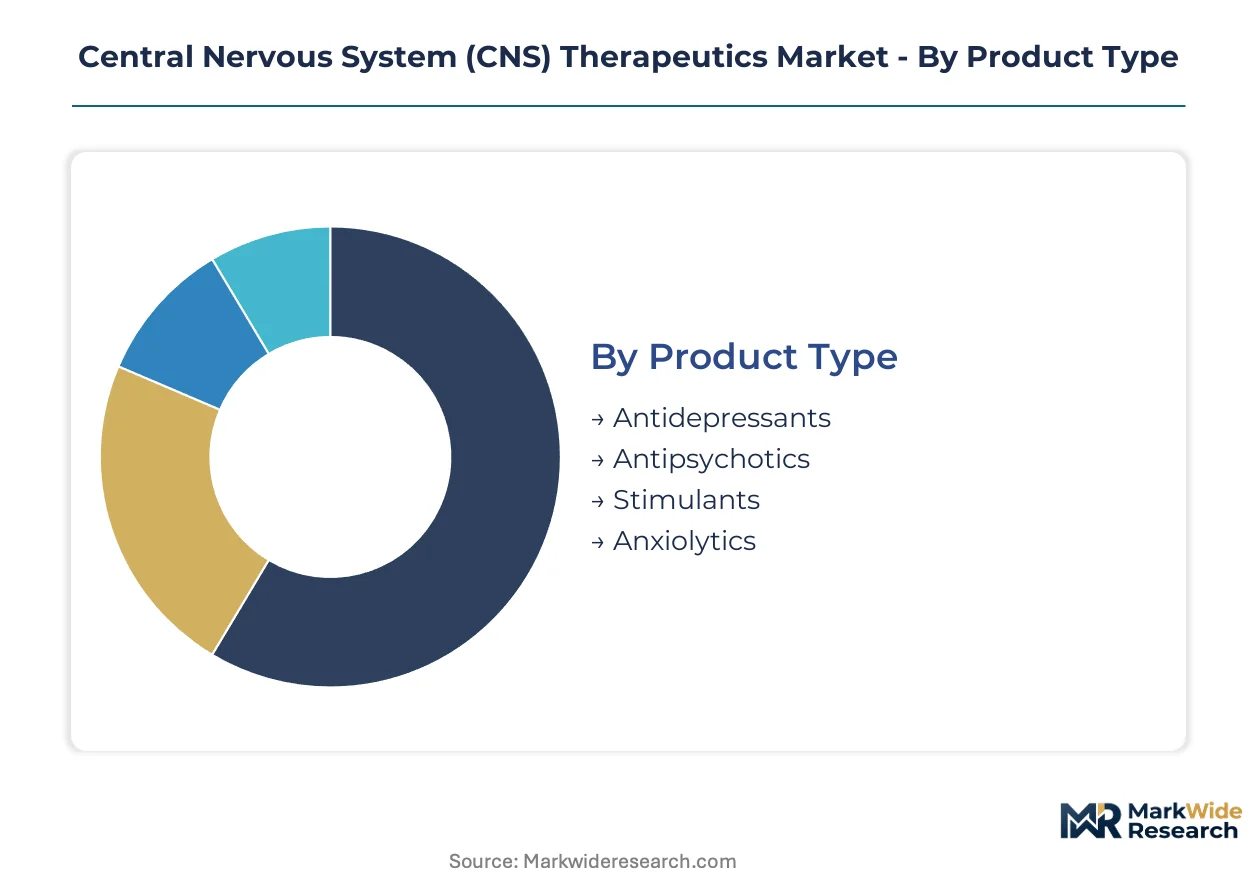
CNS therapeutics fragment across pharmacological classes, delivery technologies, and care settings. Each dimension carries distinct margin profiles, regulatory pathways, and patient access constraints that reshape competitive positioning.
Product Type:
Volume concentrates in mature oral categories with established generic erosion, while premium capture shifts toward novel mechanisms with orphan-disease pricing power.
- Antidepressants:Selective serotonin reuptake inhibitors and serotonin-norepinephrine reuptake inhibitors dominate prescription volumes through primary care channels. United States pharmacy benefit managers steer coverage toward preferred formulary tiers, compressing branded margin pools as therapeutic equivalents multiply.
- Antipsychotics:Second-generation dopamine antagonists command higher reimbursement for schizophrenia and bipolar maintenance through specialty psychiatry networks. Long-acting injectable formulations concentrate value capture among hospital outpatient departments in Germany and Japan where adherence monitoring justifies premium pricing.
- Stimulants:Amphetamine and methylphenidate derivatives lead pediatric-to-adult diagnostic expansion for attention deficit indications.
- Anxiolytics:Benzodiazepine and buspirone formulations serve acute anxiety management with shorter prescription durations.
Today's leader: Antidepressants. Tomorrow's challenger: Stimulants.
Delivery Mode:
Route selection determines manufacturing complexity, distribution channel requirements, and patient compliance economics across neurological indications.
- Oral:Immediate-release and extended-release tablets dominate maintenance therapy for chronic psychiatric conditions. Pharmacy distribution networks in the United States and Germany capture 90-day supply fulfillment, anchoring patient adherence programs.
- Intravenous:Monoclonal antibodies for multiple sclerosis and Alzheimer's disease require infusion-center infrastructure with cold-chain logistics. Massachusetts and North Carolina manufacturing clusters supply these high-complexity biologics.
- Transdermal:Patch delivery bypasses first-pass metabolism for motion sickness and Parkinson's disease adjunct therapy.
- Inhalation:Aerosolized formulations address acute migraine rescue with rapid onset requirements.
Oral formulations anchor volume economics. Intravenous delivery commands the steepest expansion trajectory through biologic penetration.
Indication:
Disease prevalence, diagnostic criteria breadth, and unmet medical need intensity segment addressable patient pools across neurological and psychiatric domains.
- Major Depressive Disorder:Expanded screening protocols in primary care settings widen the diagnosed population. United States payers increasingly require documented failure on two prior agents before approving novel rapid-acting antidepressants.
- Schizophrenia:Chronic disease management demands long-acting injectable options to address adherence gaps. Japan's PMDA reimbursement frameworks sustain higher per-patient spending for treatment-resistant cases.
- Attention Deficit Hyperactivity Disorder:Adult diagnostic criteria expansion drives prescription growth beyond pediatric populations.
- Generalized Anxiety Disorder:Overlap with depressive comorbidities complicates standalone therapeutic targeting.
Major Depressive Disorder leads commercial scale. Attention Deficit Hyperactivity Disorder expands most quickly through diagnostic criteria broadening.
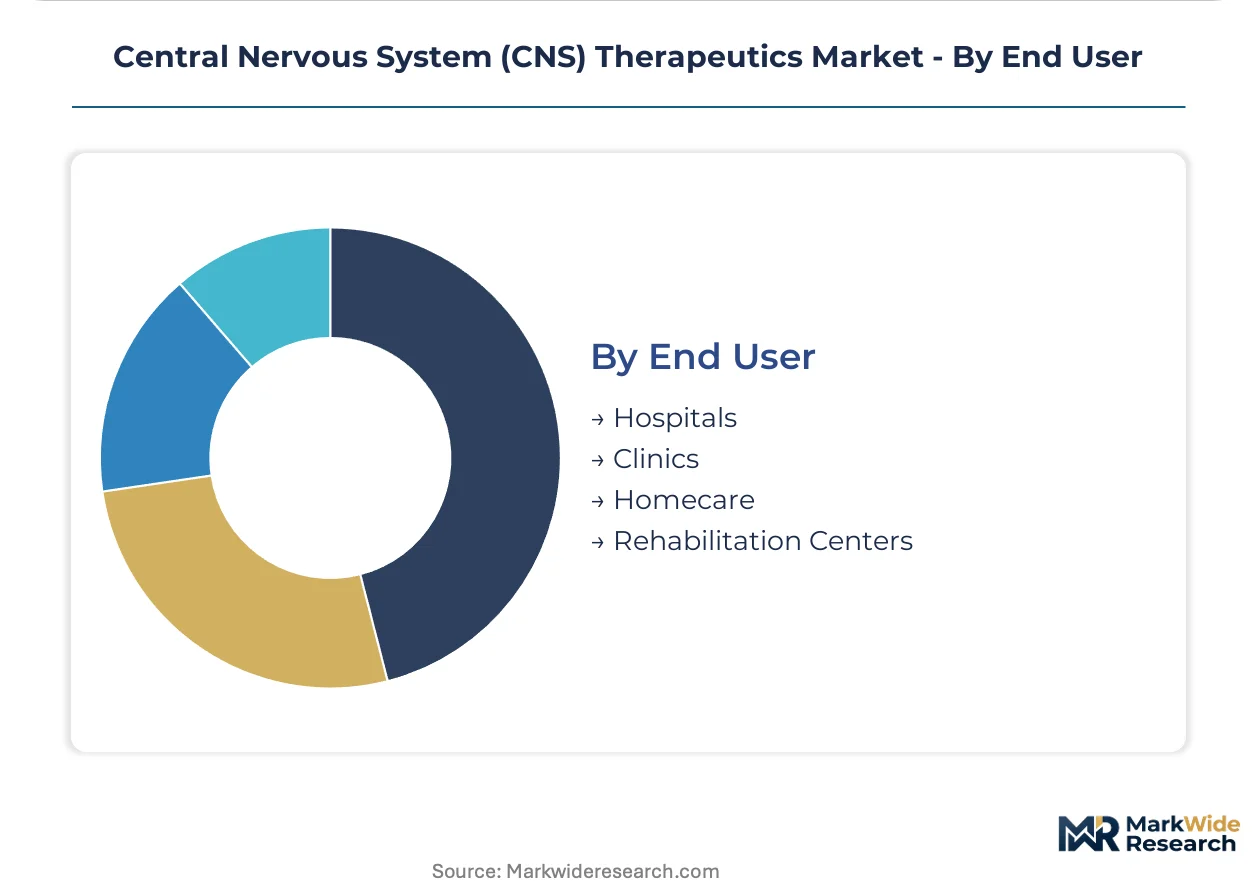
End User:
Site of care determines reimbursement rates, formulary control points, and patient monitoring intensity for CNS therapeutic administration.
- Hospitals:Acute inpatient units manage neuropsychiatric emergencies and first-episode psychosis with parenteral formulations. Germany's DRG-based reimbursement concentrates high-cost biologic initiation in university hospital settings.
- Clinics:Specialty neurology and psychiatry practices capture chronic disease management with infusion-center capabilities for monoclonal antibodies. United States-based independent practice associations negotiate directly with manufacturers for value-based contracts.
- Homecare:Nurse-administered injectables and patient self-management of oral regimens shift care outside institutional settings.
- Rehabilitation Centers:Post-acute facilities address stroke recovery and traumatic brain injury with multimodal therapeutic protocols.
Hospitals anchor high-acuity initiation. Clinics capture the fastest-growing share through specialty consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping CNS therapeutic manufacturing footprints as firms migrate toward jurisdictions with streamlined clinical-trial frameworks and favorable reimbursement negotiation climates. Cost-of-compliance gaps between the FDA's Breakthrough Therapy pathway and EMA's PRIME scheme are accelerating site-selection decisions for Phase III neurodegeneration programs.
United States
FDA's accelerated approval mechanisms and Medicare's willingness to cover amyloid-clearing antibodies sustain prescription volume leadership. Massachusetts and North Carolina manufacturing clusters anchor monoclonal antibody production for multiple sclerosis and Alzheimer's indications. Specialty neurology clinic networks in Boston and Raleigh-Durham are expanding infusion-center capacity to capture biologic administration revenue.
Germany
EMA's PRIME scheme offers priority regulatory engagement that compresses development timelines for novel mechanisms. DRG-based reimbursement concentrates high-cost biologic initiation in university hospital settings across Bavaria and North Rhine-Westphalia. Heidelberg and Munich academic medical centers are prioritizing antisense oligonucleotide programs for inherited neurodegeneration.
Japan
PMDA reimbursement frameworks for dementia therapeutics sustain prescription growth as diagnostic criteria expand to mild cognitive impairment. Tokyo and Osaka metropolitan areas concentrate specialty neurology practice consolidation. Aging demographic concentration in Kansai and Chubu regions drives demand for Parkinson's disease maintenance therapies.
Switzerland
Swissmedic's alignment with EMA standards enables parallel submission strategies for CNS gene therapies. Basel and Zurich anchor antibody engineering and viral vector production capabilities. The country's concentration of contract manufacturing organizations supports mid-cap biotechs lacking in-house GMP suites.
United Kingdom
MHRA's post-Brexit regulatory autonomy is attracting CNS trial sponsorship through streamlined ethics review processes. London and Cambridge biotech clusters are specializing in blood-brain barrier delivery platform development. The National Institute for Health and Care Excellence's value-based assessment frameworks are shaping payer evidence requirements for novel psychiatric mechanisms.
Central Nervous System (CNS) Therapeutics Market Competitive Environment
Established producers occupy the standard tier with mature oral franchises; emerging entrants pursue gene therapy and antisense oligonucleotide platforms. The market structures around three tiers: large-cap diversified pharmas with neurology divisions, mid-cap biotechs with single-asset CNS programs, and emerging gene therapy specialists. Consolidation pressures favor firms with integrated antibody engineering and viral vector manufacturing capabilities. Dominant competitive moves include strategic partnerships for blood-brain barrier delivery technologies and capacity expansion in Massachusetts and North Carolina manufacturing clusters.
Among large-cap diversified pharmas, Biogen and Roche Holding AG exemplify the established neurology franchise archetype, leveraging manufacturing scale and regulatory expertise to sustain market presence. Eli Lilly and Company occupies a position within the amyloid-targeting specialization tier, reflecting strategic concentration on Alzheimer's disease mechanisms. These three entities anchor competitive dynamics through their respective antibody engineering capabilities and established relationships with specialty infusion networks.
| Leading Market Players |
|---|
| Biogen |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| Roche Holding AG |
| AbbVie Inc. |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
United States pharmacy benefit managers now mandate documented failure on two prior antidepressant agents before approving novel rapid-acting therapies, forcing manufacturers to absorb higher patient-access program costs and compress net realized prices for premium mechanisms.
Pricing Analysis
Distributor margin capture concentrates in specialty pharmacy channels for oral neuropsychiatric maintenance therapies, with mail-order fulfillment commanding 90-day supply economics. Pricing stratifies across premium amyloid-clearing antibodies, standard long-acting injectable antipsychotics, and economy-tier generic selective serotonin reuptake inhibitors. Cost compression in the antidepressant category is intensifying because therapeutic equivalents multiply under formulary tier steering. Hospital outpatient departments exhibit lowest price sensitivity for intravenous biologic initiation, while primary care channels face highest sensitivity due to step-therapy protocols.
Supply Chain Analysis
Regional distribution centers in Massachusetts and North Carolina anchor hub-and-spoke patterns for monoclonal antibody cold-chain logistics. Active pharmaceutical ingredient manufacturing draws from India, China, and Switzerland for small-molecule neuropsychiatric compounds. Viral vector production rests on single-source contract manufacturers in the United States, creating vulnerability to capacity constraints. Distribution runs through specialty infusion-center networks for intravenous biologics and pharmacy channels for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where United States payers increasingly steer stable patients toward 90-day mail-order fulfillment, elevating specifications for adherence-monitoring infrastructure and direct-to-patient logistics.
For Market Incumbents: To counter antisense oligonucleotide displacement of kinase inhibitor pipelines in inherited neurodegeneration, Biogen and Roche Holding AG should deepen backward integration into viral vector manufacturing in North Carolina and Massachusetts. Captive supply of AAV production capacity secures gene therapy launch timelines against contract manufacturer queue delays. For New Entrants and Emerging Players: The price-point gap between premium intravenous biologics and economy oral generics creates entry space for hybrid delivery platforms combining antisense oligonucleotides with CNS-targeted lipid nanoparticles. Germany's EMA PRIME scheme offers the most penetrable regulatory pathway for novel mechanisms. A direct-to-patient pharmacy distribution angle bypasses infusion-center gatekeepers for maintenance therapy capture. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotechs possessing integrated antibody engineering and blood-brain barrier delivery platform capabilities. The five-to-ten year viability window favors acquisition targets with GMP-compliant viral vector suites or validated cognitive endpoint algorithms. Watch FDA Breakthrough Therapy designation velocity for Alzheimer's disease mechanisms as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Massachusetts and North Carolina viral vector capacity expansions secure gene therapy supply timelines against single-source dependency. |
| Regulatory Approval Pathway | EMA PRIME scheme utilization compresses Phase II-to-III transitions for neurodegenerative mechanisms in Germany. |
| Licensing Agreement | Blood-brain barrier delivery technology partnerships enable large-molecule biologic penetration beyond passive diffusion limits. |
| Pipeline Diversification | Antisense oligonucleotide programs targeting superoxide dismutase 1 displace kinase inhibitors in rare CNS genetic disease portfolios. |
| Clinical Trial Advancement | Tau PET and amyloid quantification protocol harmonization accelerates multi-center enrollment for neuroimaging biomarker trials. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market's stakeholder ecosystem. The research combines primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down therapeutic class spend analysis undergo triangulation to reconcile market size estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derive from patient population growth, diagnostic criteria expansion, and reimbursement access assumptions. Forecast inputs incorporate PMDA dementia framework evolution and Medicare amyloid-clearing antibody coverage policy.
The model assumes a particular technology adoption path; alternative pathways for blood-brain barrier delivery platforms would alter the outlook if passive diffusion limits yield to active transport engineering breakthroughs. Forecasts reflect documented assumptions regarding regulatory scrutiny intensity for accelerated approval pathways and viral vector manufacturing capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Multiple Sclerosis Treatment Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
3D Neuroscience Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
North America Neurology Monitoring Market
Neurology
North America Neurology Devices Market
Neurology
Hepatic Encephalopathy Market
Neurology
South America Neurology Monitoring Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Interventional Neurology Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Diabetic Neuropathy Market