
 Dermal Fillers and Botulinum Toxin Market | 2026-2036
Dermal Fillers and Botulinum Toxin Market Size, Share, and Industry Trends Forecast 2026-2036
Dermal Fillers and Botulinum Toxin Market Analysis
Buyer concentration among medical spas and dermatology centers is realigning as independent aesthetic clinics consolidate into multi-site chains. AbbVie leverages its therapeutic aesthetics portfolio to sustain brand loyalty across physician-administered channels. Galderma anchors its position through specialized hyaluronic acid formulations that dominate facial contouring applications. Merz Pharma differentiates via R&D intensity in neurotoxin purification, competing directly with established toxin platforms.
Dermal fillers and botulinum toxin comprise injectable biologic and synthetic substances formulated to restore facial volume, reduce dynamic wrinkles, and modify soft-tissue contours through intradermal or subcutaneous delivery mechanisms. Hyaluronic acid-based fillers dominate current volume due to reversible action profiles and established safety databases, while botulinum toxin type A commands premium positioning in wrinkle reduction through precise neuromuscular blockade. Calcium hydroxylapatite and poly-L-lactic acid segments occupy specialized niches in deeper volume restoration where collagen biostimulation delivers extended duration. Application demand fragments across facial contouring and lip enhancement as younger demographics enter preventive treatment protocols.
The FDA regulates these products as either drugs, biologics, or medical devices depending on primary mode of action, creating divergent approval pathways that shape manufacturer investment timelines. EMA's Medical Device Regulation and REACH compliance for synthetic filler substrates impose additional formulation and labeling requirements across European markets. Stakeholders must monitor evolving regulatory distinctions between cosmetic and therapeutic indications, as reimbursement access and promotional restrictions hinge on these classifications.
Market Dynamics
The aesthetic medicine sector is experiencing a structural pivot as preventive treatment protocols among patients under 35 compress traditional age-based market segmentation and expand total addressable volume beyond corrective applications.
Growth Catalysts
- Biologics pathway streamlining:FDA guidance harmonization for combination products accelerates manufacturer investment timelines and reduces regulatory uncertainty for novel filler-toxin formulations.
- Medical spa channel maturation:Multi-site aesthetic clinic chains consolidate purchasing power and standardize treatment protocols, creating predictable demand pipelines for premium injectable portfolios.
- Hyaluronic acid reversibility:Immediate dissolution capability with hyaluronidase reduces patient hesitation and expands first-time trial rates among risk-averse demographics.
Market Restraints
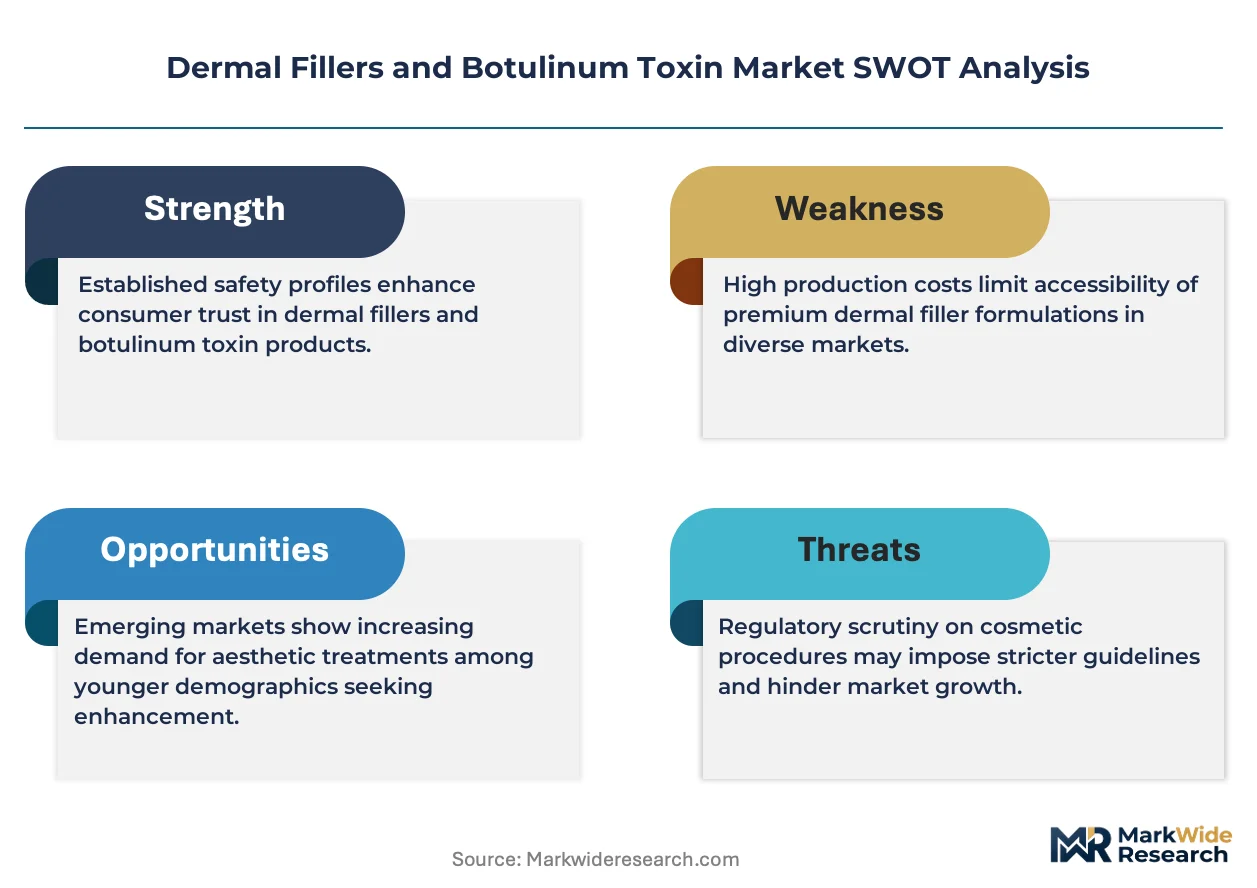
- Neurotoxin supply concentration:Purification complexity and biosafety containment requirements limit viable manufacturing sites, creating geographic supply vulnerability concentrated in North American and European production clusters.
- Poly-L-lactic acid technical limitations:Delayed onset of visible correction and requirement for multiple treatment sessions restrict adoption in time-sensitive patient segments seeking immediate results.
- REACH substrate compliance:ECHA registration requirements for synthetic filler carriers impose formulation reformulation costs and extended European market entry timelines.
Strategic Opportunities
- Men's aesthetic underpenetration:Jawline contouring and masseter reduction applications among male patients remain underserved relative to female market saturation, with Brazil and South Korea showing early adoption velocity.
- Regenerative convergence:Integration of platelet-rich plasma with hyaluronic acid delivery creates differentiated positioning in collagen biostimulation segments beyond volume replacement.
- Subscription channel innovation:Direct-to-provider membership models for maintenance dosing secure patient retention and smooth revenue cyclicality for independent dermatology practices.
Industry Challenges
- Injector skill stratification:Advanced facial anatomy training and complication management certification create talent bottlenecks as demand outpaces qualified provider pipeline expansion.
- Batch variability control:Biological source material inconsistency in toxin production requires intensive quality assurance protocols that extend release timelines and compress manufacturing margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermal Fillers and Botulinum Toxin Market |
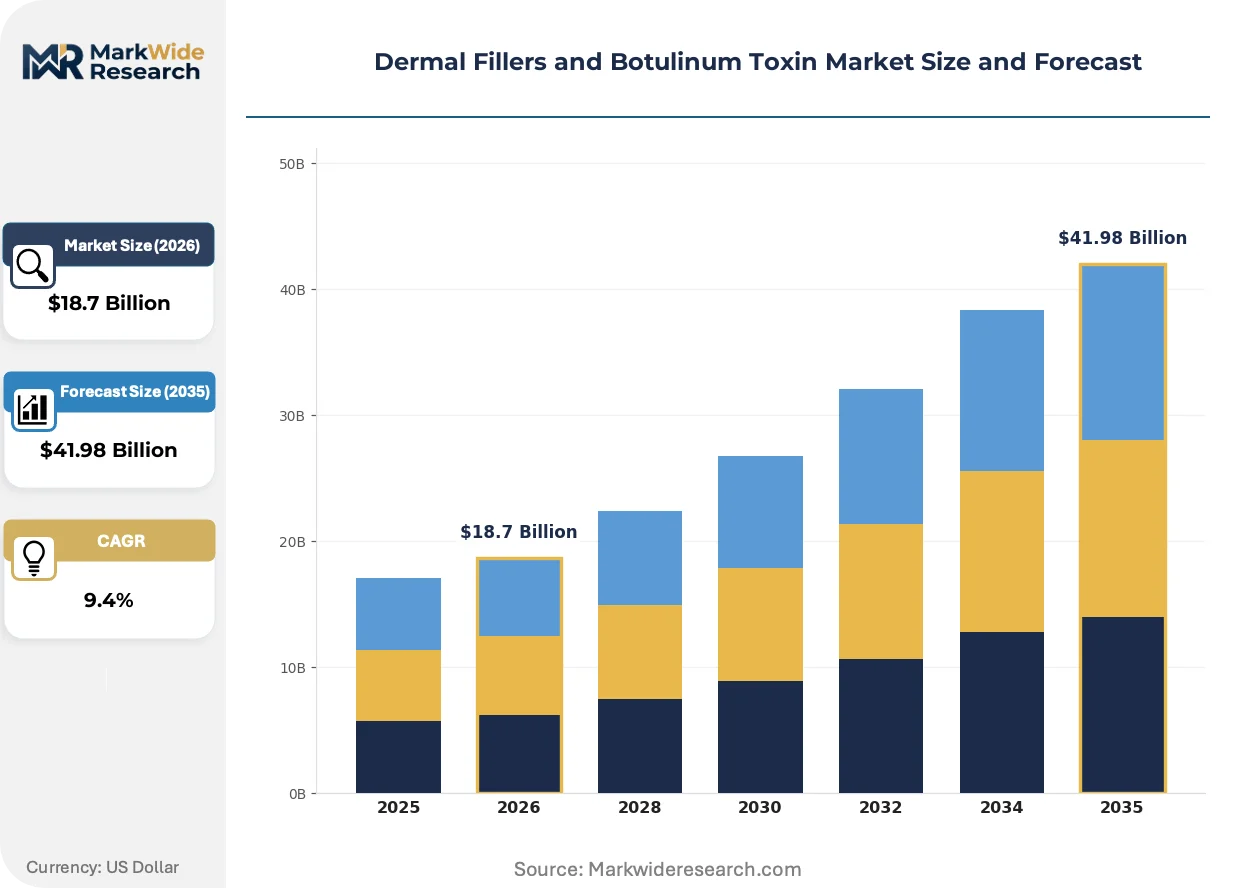
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid, Botulinum Toxin Type A Application: Facial Contouring, Wrinkle Reduction, Lip Enhancement, Volume Restoration End User: Aesthetic Clinics, Dermatology Centers, Hospitals, Medical Spas Delivery Mode: Injectables, Intradermal, Subcutaneous, Topical |
| Companies Covered | Ipsen, Evolus, AbbVie, Medytox, Sinclair Pharma, Galderma, Revance Therapeutics, Hugel, Merz Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermal Fillers and Botulinum Toxin Market Emerging Trajectories
Injectable aesthetics is undergoing material science evolution alongside channel restructuring, with reversible formulations and preventive protocols displacing traditional corrective-only treatment paradigms.
Calcium hydroxylapatite microsphere suspensions are expanding into subdermal hand rejuvenation and décolletage applications beyond their established cheek and jawline positioning. Dermatology centers in Germany and Australia report accelerated adoption for off-face indications where collagen induction delivers durable structural improvement. The technology is expanding into anatomical territories previously dominated by laser resurfacing, compressing equipment capital requirements for multi-modality practices.
EMA's Medical Device Regulation recast imposes Unique Device Identification mandates and post-market surveillance obligations on hyaluronic acid filler manufacturers. European notified body capacity constraints extend conformity assessment timelines, forcing portfolio prioritization decisions among mid-sized competitors. Swissmedic and TGA alignment with MDR technical documentation standards creates transatlantic regulatory coherence that simplifies multi-territory submission strategies.
Patients are compressing treatment intervals through preventive micro-dosing protocols that initiate toxin administration before static wrinkle formation. Medical spas in South Korea and the United Arab Emirates promote "baby toxin" memberships targeting consumers in their late twenties, displacing traditional age-40 entry thresholds. This behavioral shift concentrates volume in maintenance rather than correction segments, altering manufacturer sales force training toward retention metrics over new patient acquisition.
Dermal Fillers and Botulinum Toxin Market Segmentation
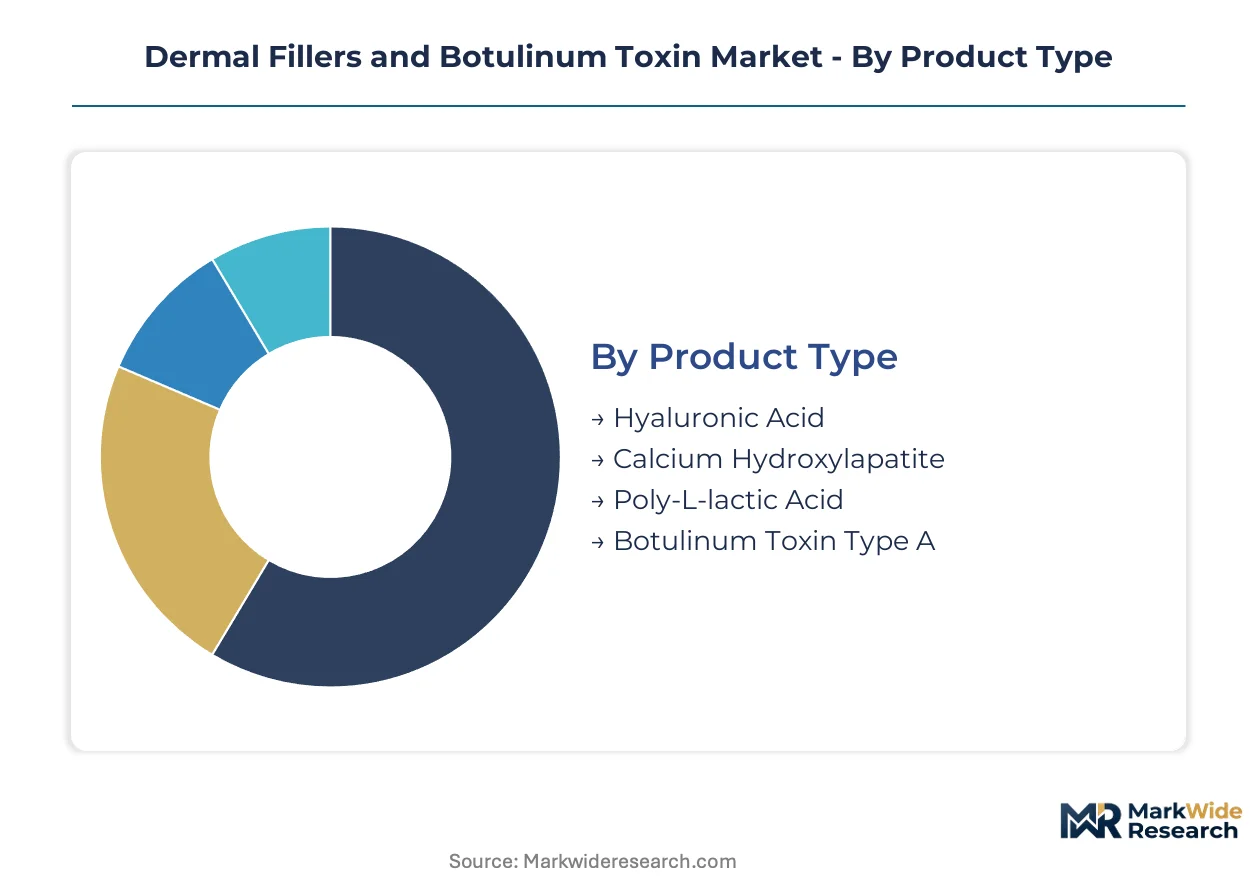
Segmentation in the Dermal Fillers and Botulinum Toxin Market reveals distinct procurement patterns across product chemistry, anatomical application, and clinical setting. Understanding these divides enables manufacturers to align formulation investments with specific channel requirements and reimbursement access.
Product Type:
Cost tier differentiation separates reversible premium formulations from biostimulatory alternatives requiring longer patient commitment cycles.
- Hyaluronic Acid:Cross-linked polysaccharide gels with tunable viscosity grades enable precise volumetric control across superficial to deep dermal planes. Demand concentrates in United States medical spas where immediate correction and hyaluronidase reversibility reduce first-treatment hesitation. FDA 510(k) clearance pathways for established crosslinking technologies compress development timelines relative to novel substrates.
- Botulinum Toxin Type A:Purified neuroprotein complexes delivered via intramuscular injection achieve temporary chemodenervation through SNAP-25 cleavage. Volume clusters in German dermatology centers where preventive micro-dosing protocols among patients under 35 displace traditional age-based entry thresholds. Complex biosafety containment requirements and batch potency variability limit viable manufacturing sites to North American and European production clusters.
- Calcium Hydroxylapatite:Biosynthetic microsphere suspensions suspended in aqueous gel carriers stimulate neocollagenesis through subdermal implantation.
- Poly-L-lactic Acid:Biodegradable polymer microparticles requiring reconstitution and serial injection sessions deliver gradual volumetric restoration through fibroblast activation.
Volume sits with Hyaluronic Acid; growth tilts toward Botulinum Toxin Type A.
Application:
Anatomical treatment zones fragment demand across corrective and preventive protocols with divergent product performance requirements.
- Facial Contouring:Midface volumization and jawline definition procedures employ high G-prime fillers for structural support in deep supraperiosteal planes. Adoption accelerates in South Korean aesthetic clinics where male jawline enhancement addresses underpenetrated demographic segments. Calcium hydroxylapatite's collagen biostimulation properties extend correction duration beyond hyaluronic acid alternatives in this indication.
- Wrinkle Reduction:Dynamic rhytid treatment via neuromuscular blockade targets glabellar lines, crow's feet, and forehead furrows through precise toxin dosing. Demand concentrates in United Arab Emirates medical spas where "baby toxin" memberships for patients in their late twenties compress traditional age-40 entry thresholds. Preventive protocols alter manufacturer sales training toward retention metrics over new patient acquisition.
- Lip Enhancement:Vermilion border definition and philtral column support utilize low-viscosity hyaluronic acid formulations with lidocaine integration.
- Volume Restoration:Pan-facial rejuvenation addressing age-related lipoatrophy combines multiple product classes across treatment sessions.
Revenue concentrates in Wrinkle Reduction; Facial Contouring gains share fastest.
End User:
Channel consolidation patterns create divergent purchasing power and protocol standardization requirements across delivery settings.
- Medical Spas:Multi-site aesthetic clinic chains consolidate injectable procurement through centralized formularies and standardized training protocols. United States-based chains leverage membership models for maintenance dosing that smooth revenue cyclicality and secure patient retention. FDA biologics licensing and state medical board supervision requirements shape staffing and oversight investments.
- Dermatology Centers:Physician-directed practices emphasize advanced facial anatomy training and complication management certification as competitive differentiators. German and Australian centers report accelerated calcium hydroxylapatite adoption for off-face hand rejuvenation applications. EMA Medical Device Regulation post-market surveillance obligations impose documentation and adverse event reporting burdens.
- Aesthetic Clinics:Independent single-site practices compete through specialized injector expertise and personalized treatment planning.
- Hospitals:Academic medical centers and integrated health systems address reconstructive applications including facial lipoatrophy and post-surgical contour defects.
Procurement volume clusters with Medical Spas; Dermatology Centers climb the fastest.
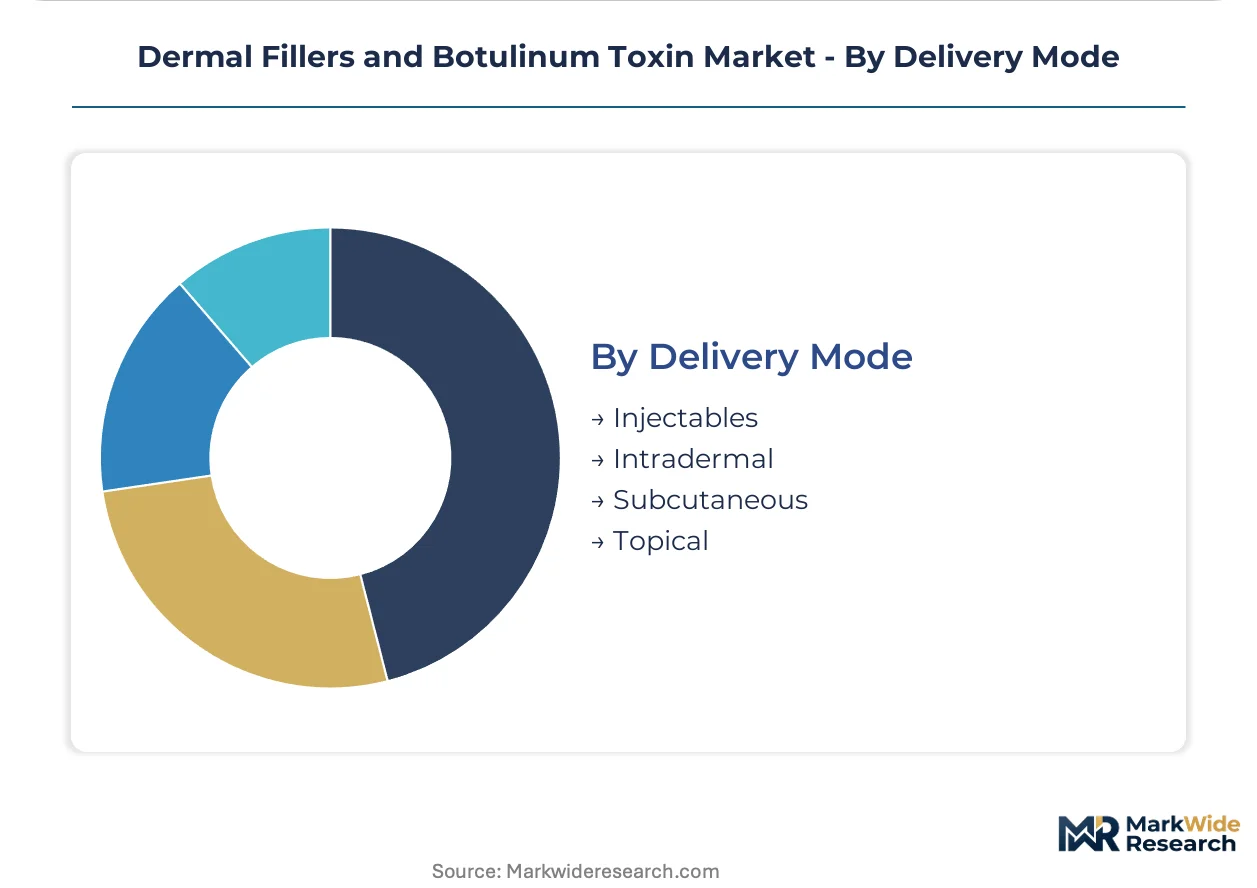
Delivery Mode:
Route of administration determines device compatibility, practitioner training requirements, and regulatory classification pathways.
- Injectables:Needle-based delivery via standard syringe systems dominates current volume through established reimbursement coding and training infrastructure.
- Intradermal:Superficial papule placement techniques for fine line correction require specialized micro-cannula or sharp needle expertise.
- Subcutaneous:Deep plane volumization in preperiosteal or supraperiosteal locations employs longer cannulas for reduced vascular compromise risk.
- Topical:Transdermal formulations remain investigational with limited commercial availability pending permeation enhancement validation.
Utilization concentrates in Injectables; Intradermal techniques expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for dermal fillers and botulinum toxin concentrates in affluent metropolitan clusters where disposable income supports premium aesthetic procedures and regulatory infrastructure enables rapid product registration.
United States
Medical spa chains in Los Angeles and Miami drive volume through membership-based maintenance protocols. FDA biologics licensing requirements shape staffing investments and oversight structures. The Dallas-Fort Worth corridor anchors multi-site aesthetic clinic consolidation, compressing procurement timelines for premium hyaluronic acid portfolios.
Germany
Dermatology centers in Munich and Hamburg accelerate calcium hydroxylapatite adoption for hand rejuvenation applications. EMA Medical Device Regulation post-market surveillance obligations impose documentation burdens on filler manufacturers. The Rhine-Ruhr metropolitan region concentrates physician-administered toxin demand through preventive micro-dosing protocols among younger demographics.
South Korea
Seoul aesthetic clinics pioneer "baby toxin" memberships targeting consumers in their late twenties, displacing traditional age-based entry thresholds. MFDS regulatory alignment with international standards accelerates novel product registration. The Gangnam district anchors facial contouring specialization, particularly male jawline enhancement addressing underpenetrated segments.
Brazil
São Paulo and Rio de Janeiro medical spas expand men's aesthetic applications including masseter reduction and jawline definition. ANVISA pharmaceutical regulation governs import licensing and distribution authorization for neurotoxin products. The southeastern industrial corridor concentrates hyaluronic acid demand through high-volume aesthetic clinic chains.
United Arab Emirates
Dubai medical tourism infrastructure attracts regional patients seeking premium injectable treatments. MOHAP pharmaceutical registration requirements align with Gulf Cooperation Council harmonization initiatives. The Dubai Healthcare City cluster standardizes training protocols across multi-site aesthetic clinic operations, smoothing demand cyclicality.
Dermal Fillers and Botulinum Toxin Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue regenerative convergence and combination product development. The vendor base stratifies across multinational pharmaceutical portfolios, specialized aesthetics pure-plays, and regional biosimilar manufacturers. Three archetypes dominate: therapeutic-diversified conglomerates, hyaluronic acid formulation specialists, and neurotoxin purification experts. Competitive moves concentrate on medical spa channel partnerships and regulatory pathway acceleration for novel filler-toxin combinations.
Within the therapeutic-diversified tier, AbbVie and Galderma represent contrasting geographic anchoring strategies, with AbbVie leveraging North American physician networks and Galderma emphasizing European formulation specialization. Merz Pharma occupies a position in the neurotoxin purification archetype, competing through R&D intensity against established toxin platforms. These three exemplify how regulatory sophistication and channel depth separate sustainable market presence from commodity positioning.
| Leading Market Players |
|---|
| Ipsen |
| Evolus |
| AbbVie |
| Medytox |
| Sinclair Pharma |
| Galderma |
| Revance Therapeutics |
| Hugel |
| Merz Pharma |
| Others |
Supply Flow & Price Mechanics
Hyaluronidase-enabled reversibility in hyaluronic acid formulations simultaneously compresses patient acquisition costs for first-time buyers and concentrates margin capture among manufacturers with proprietary crosslinking intellectual property. This technological inflection reshapes procurement economics as medical spa chains negotiate volume-based contracts against the backdrop of limited qualified manufacturing sites for neurotoxin purification.
Pricing Analysis
Volume concentrates in mid-tier hyaluronic acid segments while margins cluster in premium botulinum toxin portfolios. Three-tier pricing structure across premium, standard, and economy levels separates reversible HA formulations from biostimulatory alternatives and commodity-grade synthetics. Pricing pressure stems from REACH compliance costs forcing European market entry delays and reformulation expenses. Price-sensitive independent aesthetic clinics in Brazil and Southeast Asia defer to economy-tier synthetics, while United States medical spa chains absorb premium toxin pricing through membership retention models.
Supply Chain Analysis
Dual-sourcing requirements for neurotoxin raw materials compel manufacturers to qualify secondary suppliers against biosafety containment standards. Supply concentrates in North American and European production clusters for toxin purification, with South Korean and German sites anchoring hyaluronic acid fermentation capacity. Raw material dependencies include pharmaceutical-grade hyaluronic acid, Clostridium botulinum seed cultures, and crosslinking agent chemistries. Single-source vulnerability in toxin batch release timelines creates supply risk during regulatory inspections. Distribution runs through medical spa chain central procurement offices and dermatology center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive micro-dosing protocols are displacing corrective-only treatment paradigms, compressing traditional age-based segmentation and demanding recalibrated sales force training toward retention metrics.
For Market Incumbents: Anchor market position through captive supply of pharmaceutical-grade hyaluronic acid fermentation capacity and exclusive medical spa chain partnership structures. Consolidate procurement relationships with multi-site aesthetic clinic networks before emerging biosimilar manufacturers achieve EMA MDR conformity assessment. Invest in injector training certification programs to create talent bottlenecks that protect premium toxin pricing. For New Entrants and Emerging Players: The price-point gap between premium AbbVie toxin portfolios and economy-tier Korean biosimilars creates white-space opportunity for mid-market positioning. Target men's aesthetic applications in Brazil and South Korea where jawline contouring demand outpaces qualified provider supply. Pursue direct-to-provider subscription models for maintenance dosing that smooth revenue cyclicality for independent dermatology practices. For Investors and Strategic Acquirers: Exit pathways concentrate in therapeutic-diversified conglomerates seeking aesthetic medicine diversification and specialized neurotoxin purification platforms with EMA/FDA dual regulatory approval. Long-term viability hinges on regenerative convergence capabilities integrating platelet-rich plasma with filler delivery systems. Watch FDA guidance harmonization for combination products as inflection indicator for novel filler-toxin formulation investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Spa Chain Partnership | AbbVie and Galderma secure predictable demand pipelines through centralized formulary placement. |
| EMA MDR Conformity Assessment | European notified body capacity constraints force portfolio prioritization among mid-sized competitors. |
| Neurotoxin Purification Scale-Up | Merz Pharma's R&D intensity competes against established toxin platforms through batch potency consistency. |
| Regenerative Convergence Development | Platelet-rich plasma integration creates differentiated positioning in collagen biostimulation segments. |
| Men's Aesthetic Protocol Expansion | Jawline contouring and masseter reduction applications address underpenetrated demographic segments in Brazil. |
Methodological Framework
Independent corroboration across aesthetic clinic operators, pharmaceutical regulatory affairs specialists, and medical spa procurement directors underwrites the qualitative findings. Primary interviews with dermatology center medical directors, hyaluronic acid formulation scientists, and group purchasing organization contract managers combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, and MFDS product registration databases. Bottom-up demand modeling across product chemistry tiers and top-down market sizing through manufacturer revenue analysis enabled triangulation.
Comparable-period anchoring to historical neurotoxin and filler volume data established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product chemistry class, anatomical application zone, clinical delivery setting, and regional regulatory cluster. CAGRs were derived through exponential smoothing of annual volume and value outputs. Industry-specific forecast inputs incorporated medical spa chain expansion rates and preventive micro-dosing protocol adoption curves.
Inputs from clinical injector training programs and medical spa membership databases were available through the study window; gaps in off-label usage reporting and adverse event frequency introduce uncertainty bands around volume projections. Deviation in FDA biologics pathway streamlining timelines or EMA notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Europe Dermal Fillers Market