
 China Food Flavor and Enhancer Market | 2026-2036
China Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Flavor and Enhancer Market Analysis
Buyer concentration among food manufacturers is restructuring procurement dynamics across the China food flavor and enhancer landscape. Meihua Holdings Group leverages its vertically integrated fermentation capacity to secure raw material cost advantages. Ajinomoto Group anchors its position through advanced umami research facilities in Jiangsu province. Fufeng Group competes on monosodium glutamate scale, operating one of Asia's largest amino acid production bases.
Food flavor and enhancer products comprise chemically synthesized or naturally derived compounds that intensify or modify taste perception, typically formulated to achieve specific threshold concentrations measured in parts per million for optimal sensory impact. These ingredients serve primarily to standardize flavor profiles across large-batch processed food production while reducing sodium or sugar content. Monosodium Glutamate maintains mature volume leadership though margin pools increasingly shift toward Natural Extracts as clean-label requirements intensify. Flavor Powders dominate snack and instant noodle applications where heat stability during processing determines technical suitability.
SAMR oversees food additive registration and safety assessments while GB standards mandate compositional limits and labeling disclosures for flavor compounds sold in China. The dual carbon goals pressure manufacturers toward biotechnology-based production methods that reduce energy intensity in fermentation processes. Stakeholders must monitor evolving GB standard revisions and carbon accounting rules to align capacity investments with compliance trajectories.
Market Dynamics
Dual carbon goals are compressing energy-intensive fermentation capacity while GB standards tighten additive purity thresholds, forcing manufacturers to reconfigure production footprints or exit.
Growth Catalysts
- Clean-label mandates:SAMR labeling rules are pulling natural extract demand upward as reformulated sauces and snacks require non-synthetic alternatives.
- Shandong cluster expansion:Food processing density in this province generates captive demand for flavor standardization at scale.
- Biotechnology adoption:Enzymatic synthesis methods are cutting carbon intensity in glutamate production lines.
Market Restraints
- Corn price volatility:Fermentation feedstock costs swing with agricultural commodity cycles, squeezing margin predictability for amino acid producers.
- Guangdong supply concentration:Overreliance on Pearl River Delta manufacturing clusters creates single-point vulnerability for national distribution.
- Clean-label substitution ceiling:Natural extracts face sensory performance gaps in high-heat applications, limiting full synthetic replacement.
Strategic Opportunities
- Western province penetration:Sichuan and Chongqing food processing bases remain undersupplied relative to coastal saturation.
- Plant-based meat alignment:Alternative protein formulations require novel umami systems beyond traditional MSG applications.
- Carbon credit monetization:MEE emissions trading schemes reward biotech fermentation retrofits with tradable allowances.
Industry Challenges
- Fermentation engineering scarcity:Talent pipelines for industrial microbiology lag capacity expansion timelines.
- GB standard revision cycles:Pending additive safety reassessments freeze formulation investments until compliance clarity emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Flavor and Enhancer Market |
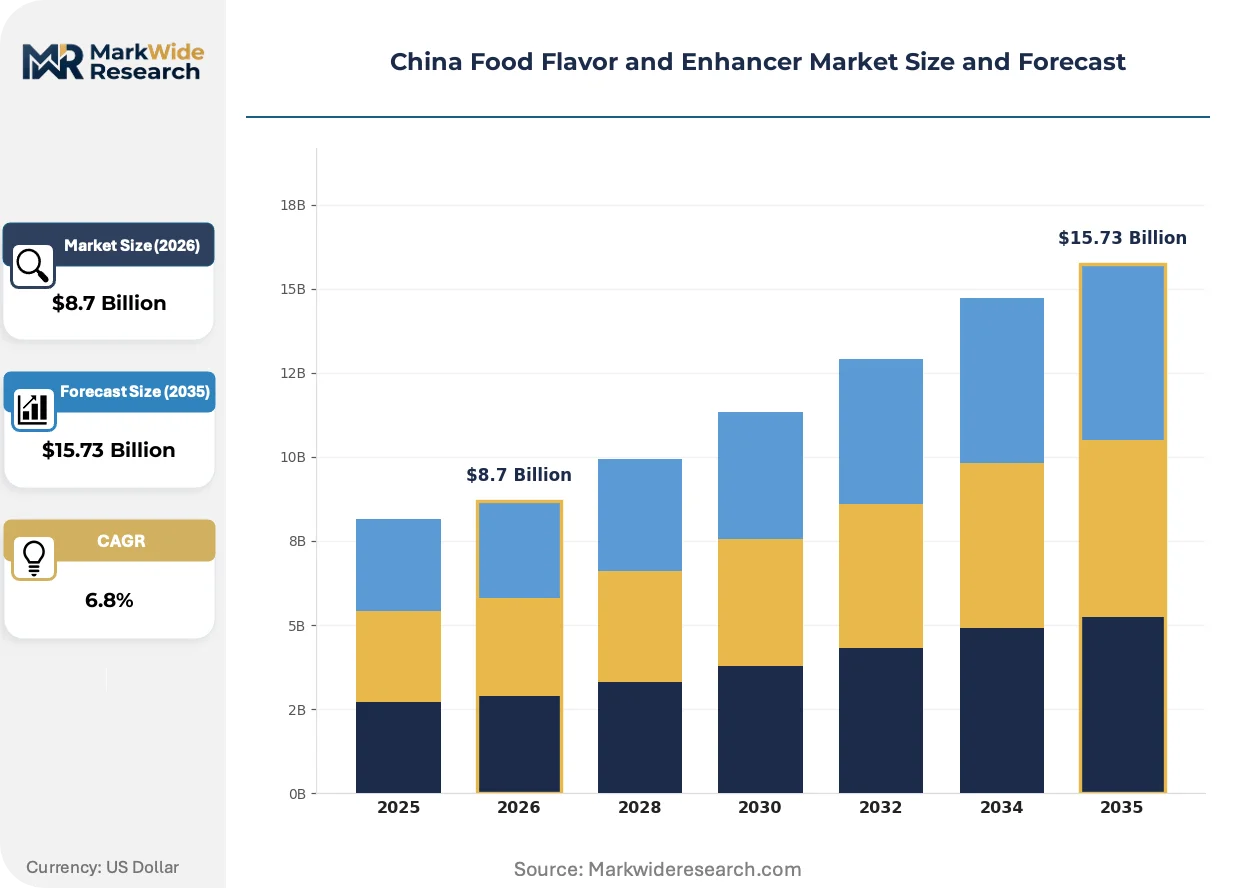
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monosodium Glutamate, Natural Extracts, Flavor Powders, Seasoning Blends Application: Processed Foods, Snacks, Marinades, Sauces End User: Food Manufacturers, Restaurants, Retailers, Food Service Providers Packaging Type: Bags, Bottles, Tubs, Sachets |
| Companies Covered | International Flavors & Fragrances Inc., Meihua Holdings Group, Ajinomoto Group, Symrise, Angel Yeast, Givaudan, Fufeng Group, Sensient Technologies Corporation, Firmenich, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Flavor and Enhancer Market Emerging Trajectories
Biotechnology convergence with carbon accounting is redefining production economics, while procurement patterns shift toward vertically assured supply chains.
Precision fermentation platforms are unifying carbon reduction targets with cost optimization in amino acid manufacturing. Instant noodle and savory sauce producers are piloting these systems at commercial scale. The technology is unifying formerly separate sustainability and procurement functions into unified supplier scorecards.
GB standards for food additive labeling are tightening disclosure requirements for synthetic versus natural origin. SAMR safety reassessments are forcing reformulation cycles across seasoning and snack categories. Powder flavor applications face the steepest compliance recalibration as heat-processed products dominate revision scope.
Buyer consolidation among processed food manufacturers is compressing supplier qualification timelines. Direct sourcing agreements are displacing layered distribution networks for volume flavor contracts. Guangdong-based snack conglomerates are most aggressive in this channel restructuring.
China Food Flavor and Enhancer Market Segmentation
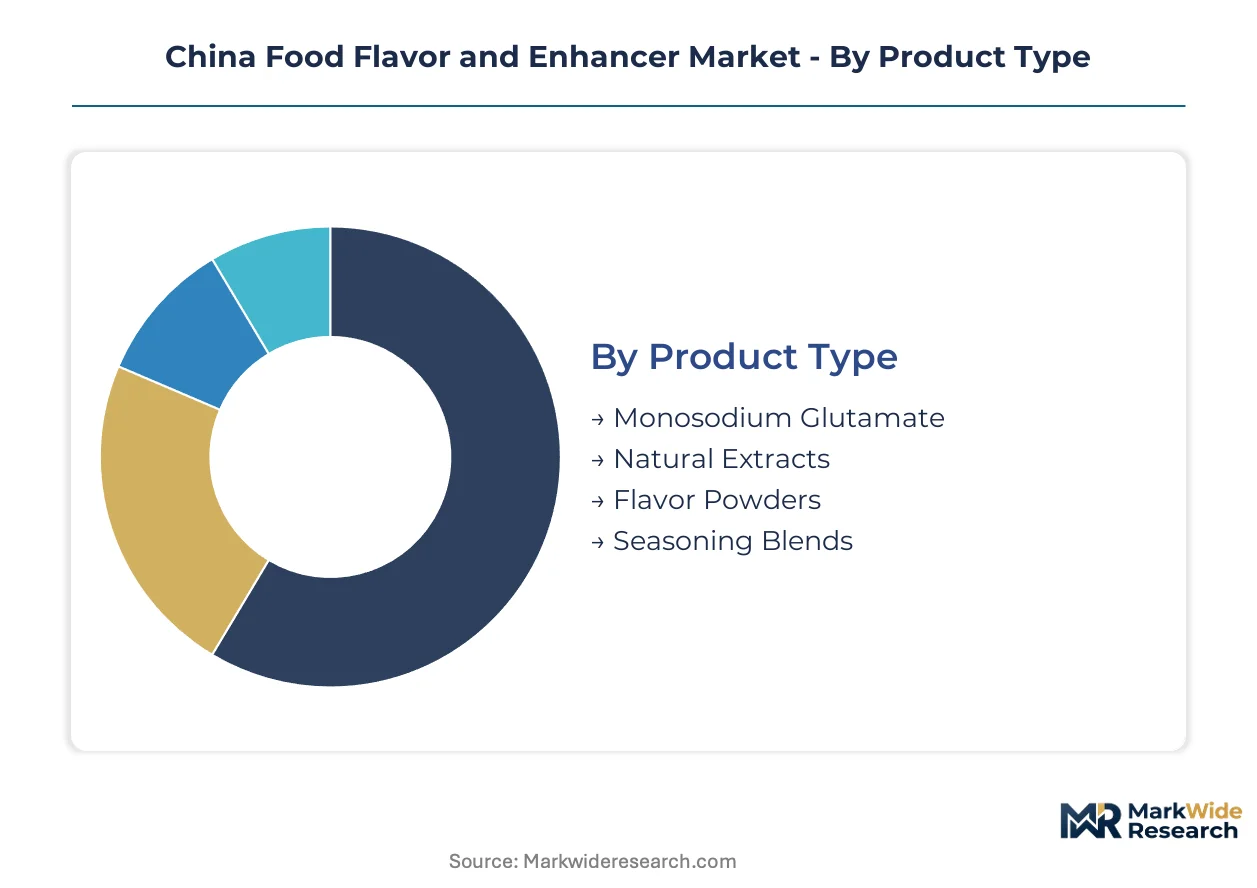
Supply concentration in Guangdong and Shandong provinces shapes how flavor and enhancer segments compete for procurement contracts. Distinct technical requirements across product types and applications create divergent margin structures that manufacturers must navigate.
Product Type:
Fermentation capacity allocation determines which product categories secure priority investment from major producers.
- Monosodium Glutamate:Chemically synthesized sodium salt of glutamic acid produced through bacterial fermentation of starch or molasses. Shandong province's amino acid production clusters consume the majority of national MSG output for instant noodle and savory sauce manufacturing. Corn feedstock price volatility directly compresses margin predictability for this mature category.
- Natural Extracts:Compounds derived from yeast, mushrooms, seaweed, or vegetable sources through enzymatic or solvent extraction. Guangdong-based clean-label snack producers are pulling demand upward as SAMR labeling disclosure rules tighten. Sensory performance gaps in high-heat applications constrain full synthetic substitution.
- Flavor Powders:Spray-dried or agglomerated formulations engineered for heat stability during extrusion and frying processes.
- Seasoning Blends:Pre-mixed combinations of flavor enhancers, salts, and aromatic compounds tailored to specific food processing applications.
Monosodium Glutamate absorbs the bulk of installed fermentation capacity; Natural Extracts is expanding most quickly as clean-label procurement criteria harden.
Application:
End-use thermal processing requirements segment the market by technical performance thresholds rather than price alone.
- Processed Foods:Canned, frozen, and retort-pouched products requiring flavor stability across sterilization temperatures. Shandong's meat processing corridor generates concentrated demand for standardized taste profiles in ready-to-eat meals.
- Snacks:Extruded, fried, and baked products where Maillard reaction compatibility determines enhancer selection. Guangdong snack conglomerates are consolidating supplier qualification timelines for direct sourcing agreements.
- Marinades:Liquid and paste formulations for meat and seafood preparation in food service channels.
- Sauces:Soy, oyster, and chili-based condiments requiring umami depth with reduced sodium targets.
Processed Foods commands the largest volume commitments; Snacks shows the steepest expansion trajectory as regional brands scale production.
End User:
Procurement scale and technical specification authority vary sharply across buyer categories.
- Food Manufacturers:Large-scale processors with in-house formulation teams and direct supplier negotiations. Shandong and Guangdong clusters dominate national purchasing volume for standardized enhancer contracts.
- Restaurants:Independent and chain operators sourcing through wholesale distributors with limited technical specification input.
- Retailers:Supermarket and e-commerce platforms controlling private-label seasoning specifications.
- Food Service Providers:Institutional caterers and centralized kitchens with cost-optimized procurement protocols.
Food Manufacturers concentrate the highest-volume contracts; Food Service Providers are gaining specification influence as institutional catering scales.
Packaging Type:
Distribution channel requirements and shelf-life demands shape packaging technology investment.
- Bags:Multi-layer polymer or paper laminates for bulk industrial shipments and food service quantities.
- Bottles:PET or glass containers for liquid extracts and tabletop seasoning retail distribution.
- Tubs:Injection-molded plastic containers for paste and concentrated base formulations.
- Sachets:Single-serve foil or film packets for instant noodle inclusions and airline catering portions.
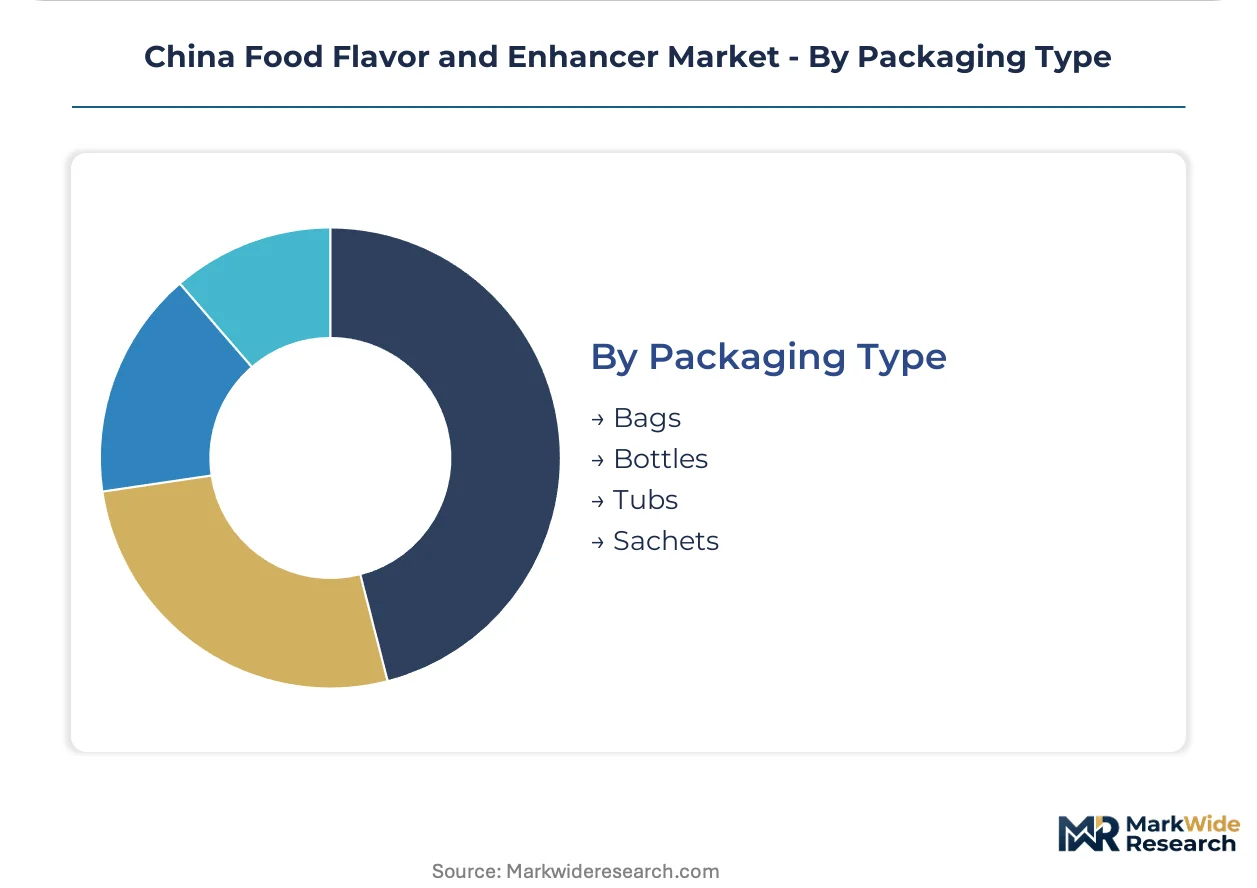
Bags handle the majority of industrial volume; Sachets are climbing fastest alongside instant noodle and airline catering expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal manufacturing corridors where food processing clusters generate captive consumption of flavor standardization ingredients. Provincial industrial policies and carbon reduction mandates are reshaping capacity allocation across eastern and western production bases.
Guangdong Province
Snack conglomerates and instant noodle manufacturers in the Pearl River Delta drive volume procurement of heat-stable flavor powders. SAMR labeling disclosure rules are accelerating clean-label reformulation cycles among Guangdong-based processors. Shenzhen and Dongguan host dense networks of seasoning blend suppliers serving export-oriented food factories.
Shandong Province
Meat processing corridors and amino acid fermentation bases generate concentrated demand for monosodium glutamate and savory enhancers. Dual carbon goals are pressuring Shandong's corn-based fermentation facilities to adopt biotechnology retrofits. Qingdao and Weifang anchor the province's integrated supply chains linking starch processing to flavor manufacturing.
Jiangsu Province
Advanced umami research facilities and enzymatic synthesis pilot plants are clustering in the Yangtze River Delta corridor. GB standards for food additive purity are tightening faster here than in northern provinces. Nanjing and Suzhou are attracting fermentation engineering talent pools for carbon-efficient production platforms.
Sichuan-Chongqing Region
Spicy sauce and hotpot base manufacturers in Chengdu and Chongqing are expanding flavor procurement as regional brands scale nationally. Western province penetration strategies target this undersupplied corridor with direct sourcing agreements. Local governments are subsidizing biotechnology adoption to close the carbon intensity gap with coastal competitors.
China Food Flavor and Enhancer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-based carbon reduction and clean-label extract portfolios. The supplier base organizes around fermentation scale, natural extraction capabilities, and vertical integration into agricultural feedstocks. Three archetypes dominate: amino acid specialists with captive corn supply, multinational flavor houses with research platforms, and yeast-based extract innovators. Competitive moves center on enzymatic synthesis licensing and direct procurement contracts with snack conglomerates.
Within the fermentation-scale tier, Meihua Holdings Group and Fufeng Group exemplify capacity-driven positioning anchored in Shandong's amino acid production clusters. Ajinomoto Group occupies a distinct research-intensive position through its Jiangsu-based umami science facilities. These three entities represent divergent strategic vectors: backward integration into agricultural inputs, multinational R&D platform deployment, and regional scale concentration serving domestic processed food manufacturers.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Meihua Holdings Group |
| Ajinomoto Group |
| Symrise |
| Angel Yeast |
| Givaudan |
| Fufeng Group |
| Sensient Technologies Corporation |
| Firmenich |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap producers in Shandong's amino acid corridors anchor supply discipline through backward integration into corn processing, while their pricing power tightens as GB standard compliance costs filter out marginal competitors. This ownership structure concentrates procurement leverage among vertically assured players who can absorb feedstock volatility without passing full cost swings to processed food manufacturers.
Pricing Analysis
Volume-mature Monosodium Glutamate trades on thin commodity margins while Natural Extracts commands premium-mid-economy pricing differentiation based on SAMR disclosure tier and enzymatic certification. Price differentiation hinges on fermentation scale and clean-label sourcing transparency. Cost compression in standard-grade MSG is intensifying because corn feedstock swings squeeze unintegrated producers. Food Manufacturers with direct sourcing agreements show lowest price sensitivity; independent Restaurants face highest cost pass-through exposure.
Supply Chain Analysis
Dual-sourcing mandates from Guangdong snack conglomerates force qualification of secondary fermentation bases in Jiangsu and Sichuan despite Shandong's production dominance. Geographic supply concentration centers on China for amino acid fermentation, with yeast extract feedstock drawing from regional corn and molasses belts. Raw material dependencies rest on corn starch, bacterial culture strains, and enzymatic processing agents. Single-source vulnerability concentrates in Pearl River Delta distribution nodes. Distribution runs through direct procurement contracts displacing layered wholesale networks for volume flavor agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
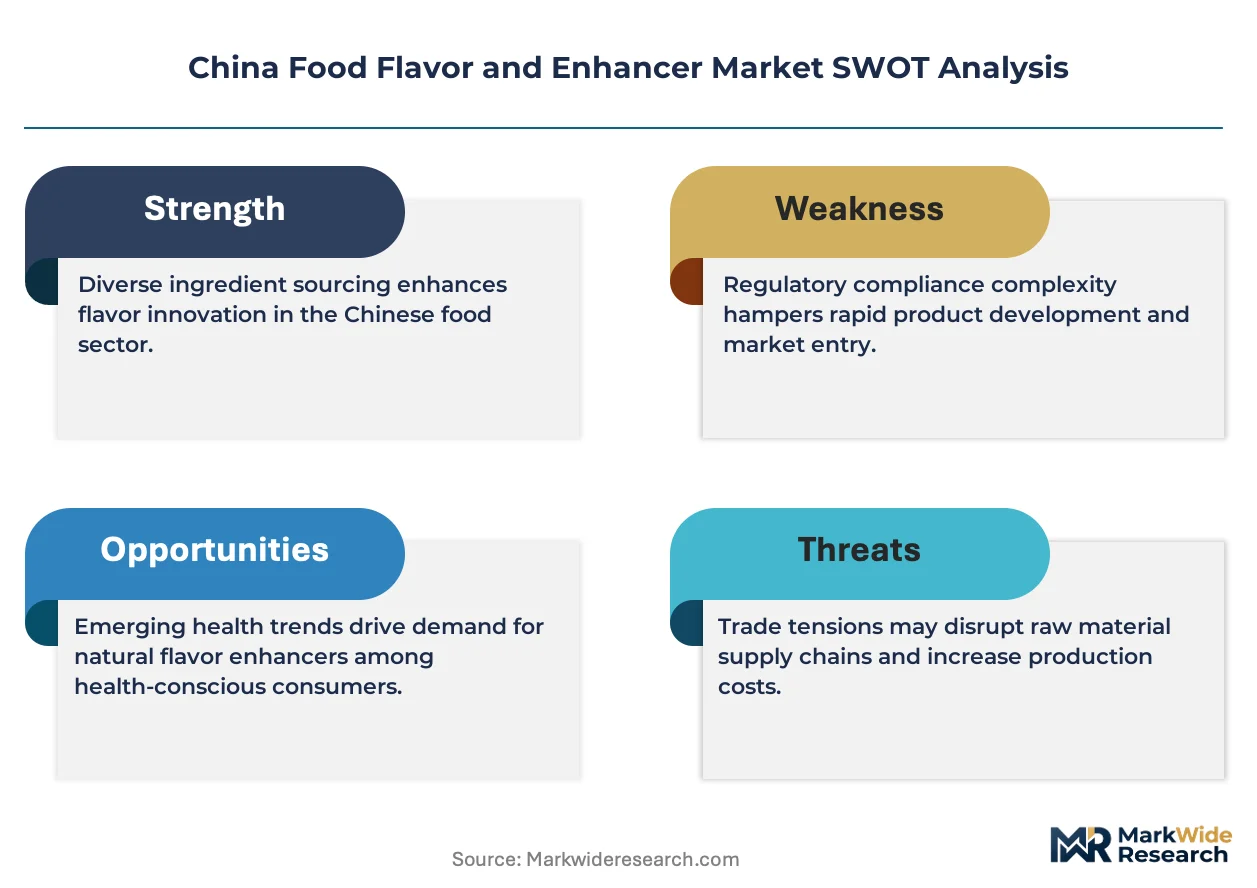
This market reads as a cost-of-compliance story where GB standards for food additive purity and SAMR registration requirements erect barrier-to-entry moats favoring producers with captive fermentation engineering and carbon-accounting infrastructure.
For Market Incumbents: Hedge margin exposure by locking multi-year corn supply contracts before agricultural commodity cycles tighten further. Accelerate biotechnology retrofit investments to capture MEE emissions trading allowances before carbon credit monetization windows narrow. Defensive consolidation around enzymatic synthesis licensing will neutralize emerging yeast-extract innovators threatening clean-label positioning.
For New Entrants and Emerging Players: Food service distributors represent the most accessible channel partner type for penetrating undersupplied Sichuan-Chongqing hotpot base manufacturers without confronting Guangdong's consolidated supplier qualification timelines. Target plant-based meat formulators seeking novel umami systems beyond traditional MSG applications. A carbon-efficient fermentation narrative unlocks procurement conversations with institutional catering chains facing dual carbon procurement mandates.
For Investors and Strategic Acquirers: SAMR safety reassessment announcement delays are the leading indicator that formulation investment freezes will concentrate market share among pre-qualified incumbents with compliant inventory buffers. Long-term viability favors biotechnology-integrated mid-caps with Jiangsu or Shandong production footprints over legacy chemically synthesized capacity. Watch for GB standard revision publication timing as the inflection signal for accelerated M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Licensing | Unlocks carbon credit revenue streams under MEE emissions trading schemes for retrofitted Shandong facilities. |
| Direct Sourcing Agreement Expansion | Guangdong snack conglomerates compress supplier qualification timelines by eliminating layered distribution markups. |
| Natural Extract Portfolio Buildout | Aligns with SAMR labeling disclosure tightening that disadvantages synthetic origin formulations. |
| Western Province Distribution Investment | Chengdu and Chongqing food processing bases remain capacity-constrained relative to coastal saturation. |
| Fermentation Engineering Talent Acquisition | Jiangsu's Yangtze River Delta corridor attracts scarce industrial microbiology capability for carbon-efficient platforms. |
Methodological Framework
Independent corroboration across SAMR regulatory filing databases, GB standards revision dockets, and processed food manufacturer procurement disclosures underwrites the qualitative findings in this study. Primary interviews with fermentation plant managers, seasoning blend procurement leads at snack conglomerates, distribution channel partners, and technical R&D directors at enzymatic synthesis platforms combined with secondary validation from customs trade records, MEE emissions data, and corporate sustainability reports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across product type, application thermal processing requirement, end-user procurement scale, and provincial regulatory cluster shapes the analytical framework over the projection horizon. CAGRs derive from segment-level growth differentials weighted by base-year value shares. Forecast inputs incorporate biotechnology adoption curves in glutamate production and clean-label substitution elasticity in snack and sauce categories.
Caveats apply where SAMR safety reassessment timing, corn commodity price spikes, or dual carbon enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about GB standard implementation pace and carbon accounting rule finalization. A model refresh is warranted upon material change in biotechnology retrofit subsidy programs or instant noodle demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market