
 Middle East and Africa Botanical Extract Market | 2026-2036
Middle East and Africa Botanical Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Botanical Extract Market Foresight
Supercritical CO2 extraction is reshaping how botanical actives are recovered across the Middle East and Africa, replacing solvent-based methods with cleaner, higher-yield processes that preserve thermolabile compounds. Martin Bauer Group leverages its European technical base to supply standardized herbal extracts into North African pharmaceutical channels. Döhler Group SE anchors beverage formulation partnerships in the Gulf, while African Botanicals Ltd. specializes in indigenous species sourcing from southern African biomes.
Botanical extracts comprise concentrated bioactive compounds derived from plant material through mechanical pressing, solvent extraction, distillation, or supercritical fluid methods, typically standardized to marker compound percentages for batch consistency. These extracts serve as functional ingredients in pharmaceuticals, flavor systems, cosmetic actives, and nutritional supplements where synthetic alternatives face consumer rejection. Essential oils command premium positioning in Gulf cosmetics manufacturing due to halal-certification alignment and aromatherapy positioning. Herbal extracts dominate pharmaceutical procurement volumes across Egypt and Nigeria, while nutraceutical applications in South Africa show accelerated uptake among aging demographics seeking immune support.
SFDA in Saudi Arabia enforces stringent heavy-metal and pesticide residue limits on imported botanical materials, reshaping supplier qualification protocols for entrants. South Africa's SAHPRA and Egypt's drug authority maintain parallel registration tracks for traditional herbal medicines, creating compliance complexity for multi-market operators. The EU Green Deal's due diligence requirements on deforestation-linked imports are cascading into Moroccan and Kenyan export supply chains through buyer mandates. Stakeholders must monitor evolving national pharmacopeia harmonization efforts and build traceability infrastructure before regulatory deadlines harden.
Market Dynamics
Supercritical CO2 extraction is rendering obsolete solvent-based recovery methods across North African pharmaceutical corridors, compressing processing costs while preserving thermolabile bioactives for standardized API production.
Growth Catalysts
- SFDA Heavy-Metal Protocols:Saudi Arabia's stringent residue limits on imported botanical materials are forcing supplier qualification upgrades that favor certified extract processors capable of batch-level traceability documentation.
- Pharmaceutical API Sourcing:Generic drug manufacturers across Egypt and Nigeria are expanding botanical active procurement volumes as cost-containment pressures intensify for off-patent formulations.
- Morocco Argan Corridor:Concentrated processing infrastructure around Agadir and Essaouira is achieving economies of scale in cold-press and supercritical oil extraction for export-grade cosmetic actives.
Market Restraints
- Frankincense Supply Concentration:Ethiopia's Somali Region and Puntland supply 80% of global Boswellia resin, exposing processors to harvest volatility from regional security disruptions and over-tapping degradation.
- Dual Registration Tracks:South Africa's SAHPRA and Egypt's drug authority maintain non-harmonized herbal medicine pathways, forcing multi-market operators to duplicate toxicology and stability studies.
- Synthetic Substitution Pressure:Fermentation-derived phytochemicals from European biotech suppliers are capturing mid-tier cosmetic applications where botanical provenance carries no price premium.
Strategic Opportunities
- Kenya Underpenetration:Mount Kenya highland cultivation zones for pyrethrum and Artemisia remain underdeveloped for GACP-certified extract supply, offering first-mover positioning before EU deforestation due diligence hardens.
- Halal-Certified Aromatherapy:Gulf cosmetics manufacturers are mandating alcohol-free extraction methods and halal supply chain documentation, creating premium positioning for compliant Moroccan and Egyptian processors.
- Blockchain Traceability Convergence:Integration of distributed ledger systems with supercritical extraction batch records is enabling real-time provenance verification for EU buyer compliance under Green Deal requirements.
Industry Challenges
- GACP Auditor Scarcity:Qualified personnel for Good Agricultural and Collection Practice certification are concentrated in South Africa and Morocco, creating 12-18 month qualification backlogs for East African suppliers.
- Cold-Chain Capex Burden:Thermolabile compound preservation requires -20°C storage infrastructure that extract processors in Nigeria and Ethiopia must finance without established offtake guarantees.
- Traditional Knowledge Licensing:Bioprospecting agreements under the Nagoya Protocol are generating protracted negotiation timelines between southern African communities and commercial extract developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Botanical Extract Market |
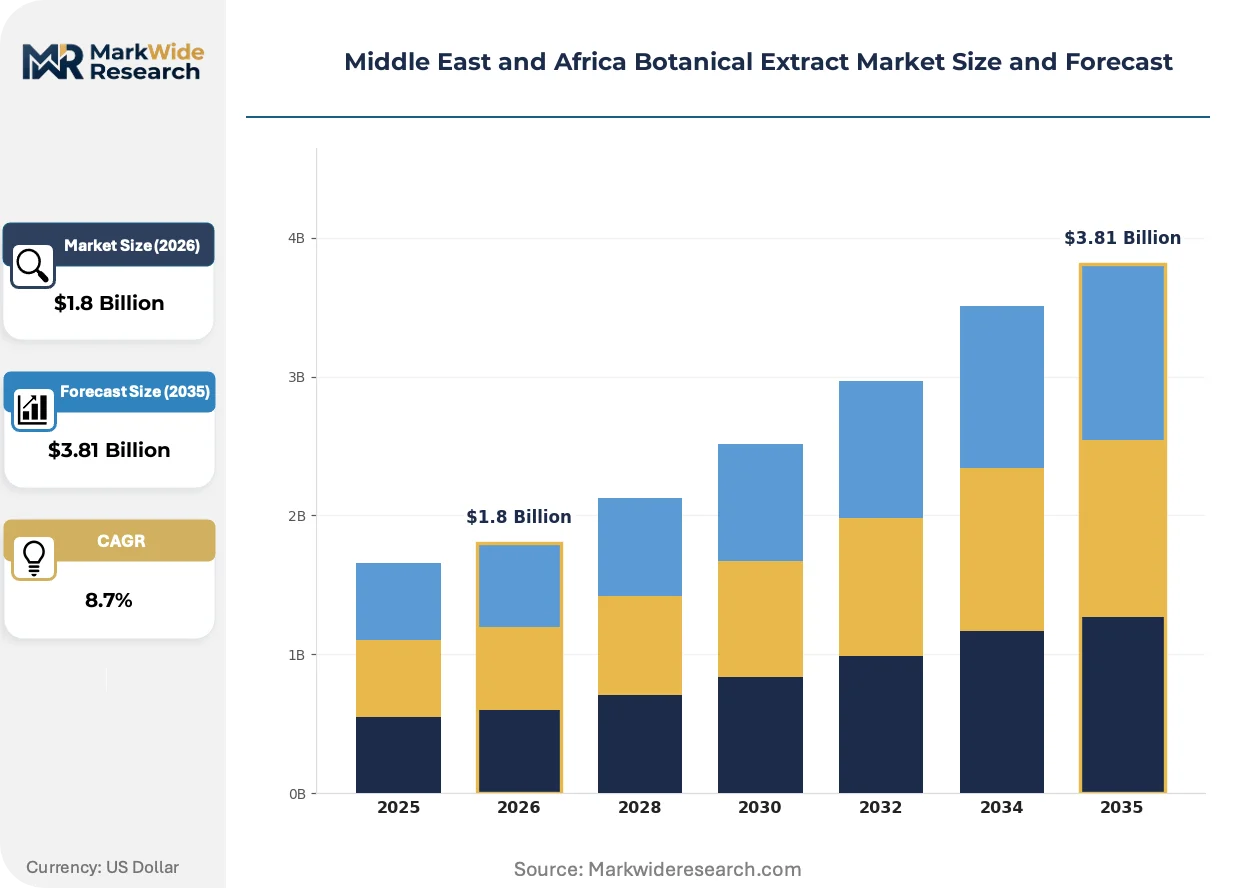
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Powders, Tinctures Application: Cosmetics, Food & Beverage, Pharmaceuticals, Nutraceuticals Form: Liquid, Solid, Gel, Cream End User: Food Manufacturers, Cosmetic Companies, Herbal Retailers, Pharmaceutical Firms |
| Companies Covered | Martin Bauer Group, Döhler Group SE, International Flavors & Fragrances Inc., Givaudan, Al Khair Natural Herbs Factory, Indena S.p.A., Kalsec Inc., African Botanicals Ltd., Synthite Industries Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Botanical Extract Market Shifts & Advancements
Extraction technology convergence with digital traceability systems is compressing quality assurance timelines while regulatory fragmentation across the region forces adaptive compliance architectures.
Supercritical CO2 systems configured for selective fractionation of cannabinoids and terpenoids are rendering obsolete ethanol-soak methods in South African hemp processing facilities. Pharmaceutical contract manufacturers in Cape Town are adopting these units to meet SAHPRA stability requirements for standardized extracts. The technology shift is compressing solvent recovery costs and eliminating residual ethanol concerns for halal certification pathways.
EU Green Deal due diligence requirements on deforestation-linked imports are cascading into Moroccan and Kenyan export supply chains through buyer mandates rather than direct jurisdiction. Processors in the Maghreb are deploying satellite-verified geolocation tagging for argan and prickly pear sourcing to pre-empt documentation requests. The regulatory externality is favoring vertically integrated operators with captive cultivation over aggregator-dependent traders.
Halal-certification alignment has become a non-negotiable filter for Gulf cosmetics procurement decisions, displacing European suppliers unable to demonstrate alcohol-free extraction and segregated logistics. Moroccan essential oil exporters are restructuring processing lines to capture this premium positioning in Dubai and Riyadh formulation houses. The preference shift is most visible in frankincense and myrrh derivatives where religious compliance commands 15-20% price premiums over conventional grades.
Middle East and Africa Botanical Extract Market Segmentation
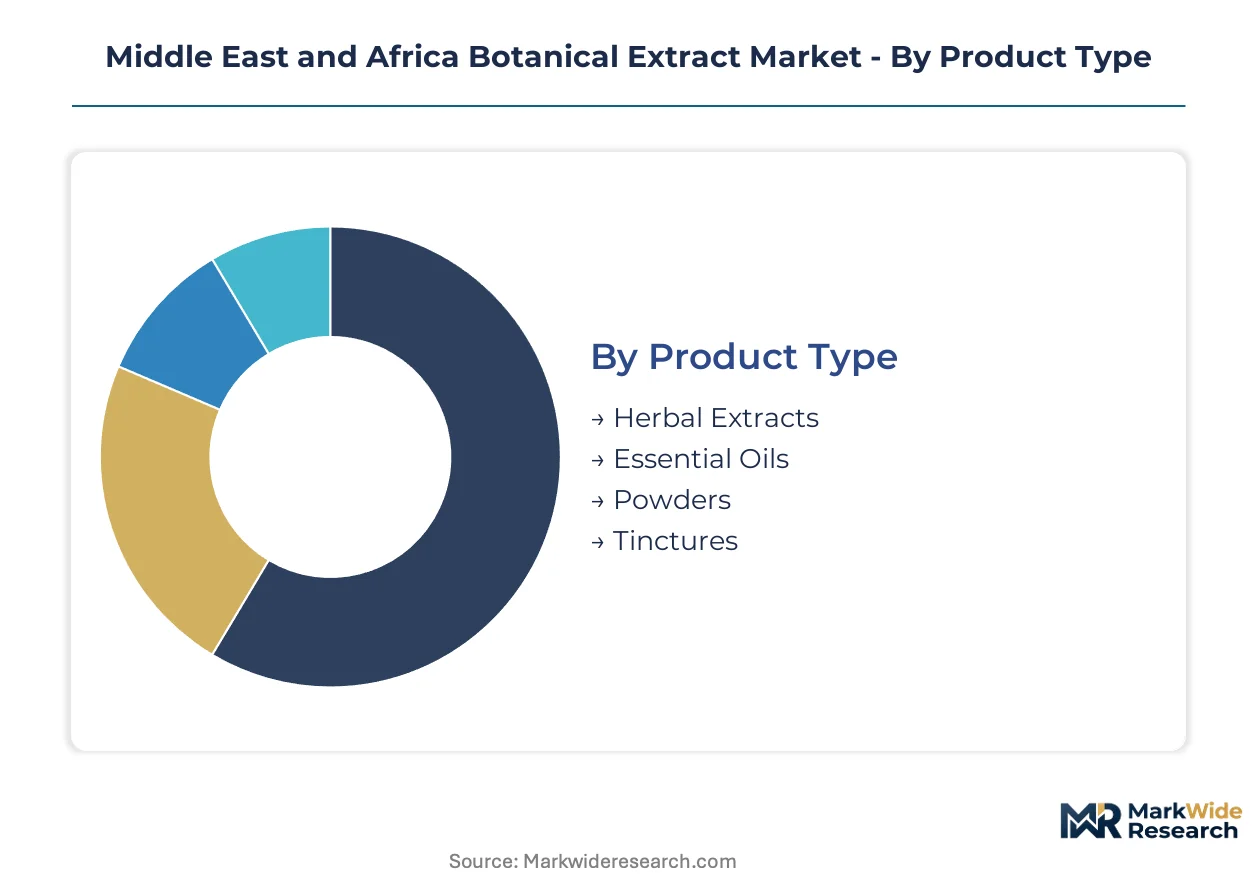
Botanical extract procurement cycles vary dramatically across the Middle East and Africa, from quarterly reformulation orders in Gulf cosmetics to multi-year pharmaceutical API contracts in Egypt and Nigeria. Understanding these velocity differences enables suppliers to align working capital and certification investments with segment-specific cash conversion profiles.
Product Type:
Essential oils turn inventory fastest in Moroccan argan corridors, while tinctures linger in Ethiopian frankincense supply chains due to extended resin curing protocols.
- Herbal Extracts:Standardized phytochemical concentrates derived from solvent or supercritical processing, typically specified to marker compound percentages. Egyptian and Nigerian generic drug manufacturers are expanding procurement volumes as cost-containment pressures intensify for off-patent formulations. Herbal extracts anchor the volume base while essential oils gains share at the steepest rate.
- Essential Oils:Volatile aromatic compounds recovered through steam distillation or cold-press methods, commanding premium positioning in Gulf cosmetics manufacturing. SFDA heavy-metal protocols are forcing supplier qualification upgrades that favor certified processors capable of batch-level traceability documentation. Essential oils anchor the volume base while herbal extracts gains share at the steepest rate.
- Powders:Spray-dried or freeze-dried botanical concentrates for nutraceutical encapsulation and instant beverage applications.
- Tinctures:Alcohol-based or glycerin-based liquid preparations, predominantly serving traditional medicine channels in South Africa under SAHPRA registration tracks.
Herbal extracts anchor the volume base while essential oils gains share at the steepest rate.
Application:
Margin structures diverge sharply across end-use categories, with pharmaceutical procurement demanding stability documentation that cosmetics buyers rarely require.
- Pharmaceuticals:Botanical active pharmaceutical ingredients for generic drug manufacturing, subject to stringent stability and toxicology requirements. South Africa's SAHPRA and Egypt's drug authority maintain parallel registration tracks for traditional herbal medicines, creating compliance complexity for multi-market operators. Pharmaceuticals anchor the volume base while nutraceuticals gains share at the steepest rate.
- Cosmetics:Functional actives and fragrance materials for skincare and personal care formulations, with halal-certification alignment becoming a non-negotiable filter for Gulf procurement decisions. Moroccan processors are restructuring extraction lines to capture premium positioning in Dubai and Riyadh formulation houses. Cosmetics anchor the volume base while nutraceuticals gains share at the steepest rate.
- Food & Beverage:Natural flavor systems and colorants for beverage formulation partnerships concentrated in the Gulf.
- Nutraceuticals:Immune support and wellness positioning targeting South Africa's aging demographics, showing accelerated uptake in capsule and tablet formats.
Pharmaceuticals anchor the volume base while nutraceuticals gains share at the steepest rate.
Form:
Cold-chain requirements segment processing economics, with liquid extracts demanding continuous refrigeration that solid forms avoid.
- Liquid:Aqueous or oil-based extracts requiring controlled temperature storage, predominant in essential oil and tincture supply chains. Thermolabile compound preservation demands -20°C storage infrastructure that extract processors in Nigeria and Ethiopia must finance without established offtake guarantees. Liquid anchors the volume base while gel gains share at the steepest rate.
- Solid:Powdered and granulated formats for nutraceutical encapsulation and food ingredient applications, offering superior shelf stability and reduced logistics costs across East African distribution networks. Solid anchors the volume base while gel gains share at the steepest rate.
- Gel:Semi-solid preparations for topical cosmetic applications, expanding in Moroccan argan oil processing corridors.
- Cream:Emulsion-based delivery systems for dermal cosmetic actives, concentrated in South African formulation houses serving regional skincare brands.
Liquid anchors the volume base while gel gains share at the steepest rate.
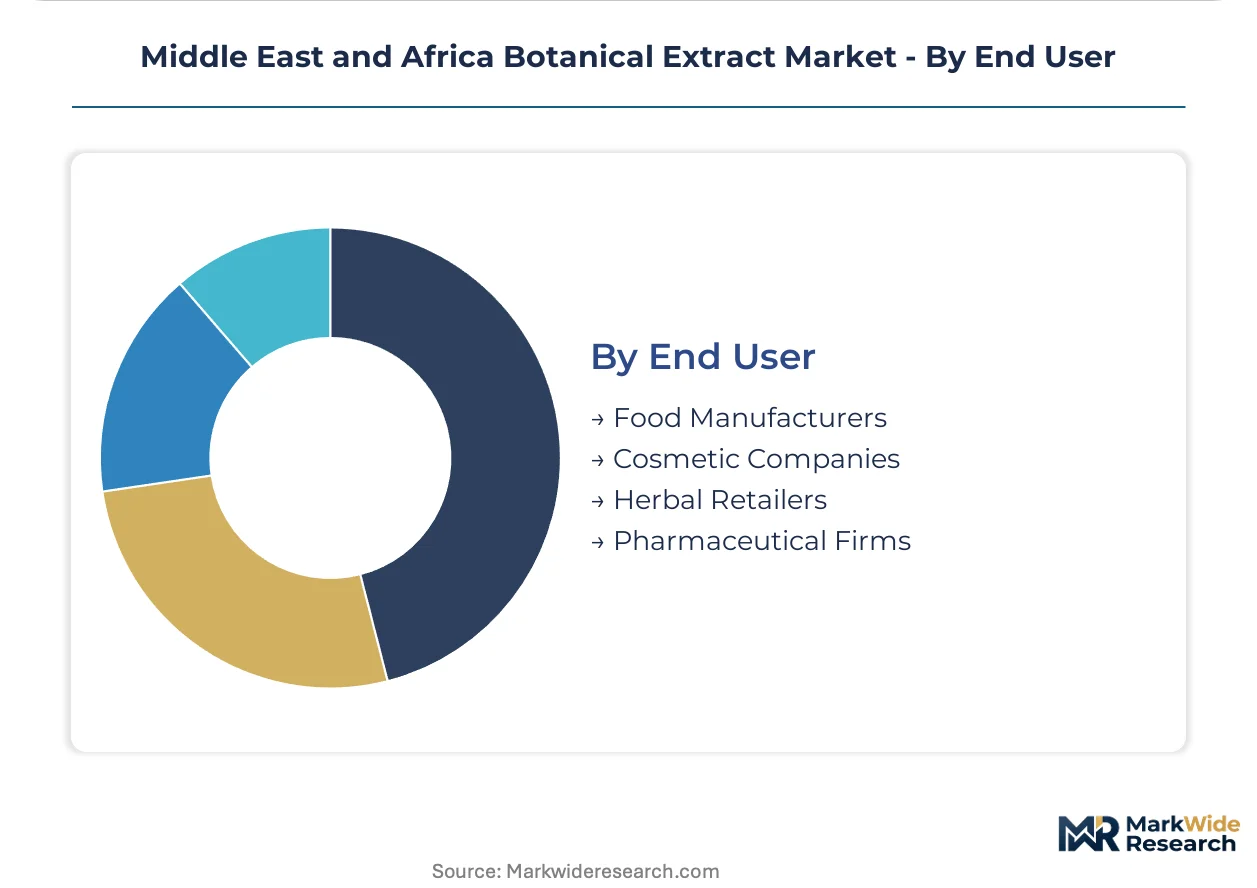
End User:
Buyer concentration patterns shape supplier negotiation leverage, with pharmaceutical firms consolidating procurement while herbal retailers fragment orders.
- Pharmaceutical Firms:Generic drug manufacturers and contract development organizations sourcing standardized botanical APIs for tablet and capsule production. Procurement is shifting toward certified extract processors capable of meeting SFDA heavy-metal and pesticide residue limits on imported materials. Pharmaceutical firms anchor the volume base while cosmetic companies gains share at the steepest rate.
- Cosmetic Companies:Gulf-based formulation houses and North African personal care manufacturers mandating halal-certification alignment and alcohol-free extraction methods. EU Green Deal due diligence requirements on deforestation-linked imports are cascading into Moroccan and Kenyan export supply chains through buyer mandates. Cosmetic companies anchor the volume base while food manufacturers gains share at the steepest rate.
- Food Manufacturers:Beverage and confectionery processors in the Gulf and South Africa incorporating natural flavor systems.
- Herbal Retailers:Traditional medicine dispensaries and direct-to-consumer channels across South Africa, Nigeria, and Ethiopia, operating outside formal pharmaceutical registration frameworks.
Pharmaceutical firms anchor the volume base while cosmetic companies gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical firms and Gulf cosmetics manufacturers concentrate procurement across distinct national corridors, with regulatory fragmentation forcing multi-country compliance architectures for extract suppliers seeking scale.
Saudi Arabia
SFDA heavy-metal protocols on imported botanical materials are upgrading supplier qualification standards for generic drug manufacturers in Riyadh and Jeddah. The regulator's pesticide residue limits now require batch-level traceability documentation that favors certified extract processors over traditional traders. Supercritical CO2 extraction infrastructure is concentrating in Jeddah's pharmaceutical corridor to meet these documentation demands for API production.
South Africa
SAHPRA's parallel registration tracks for traditional herbal medicines are creating compliance complexity for multi-market operators serving aging demographics seeking immune support. The Traditional Health Practitioners Act has tightened herbal medicine registration requirements, extending toxicology study timelines for entrants. Cape Town contract manufacturers are adopting selective fractionation systems to meet stability requirements for standardized extracts.
Morocco
Argan oil processing infrastructure around Agadir and Essaouira is achieving economies of scale in cold-press and supercritical extraction for export-grade cosmetic actives. EU Green Deal due diligence requirements are cascading into export supply chains through buyer mandates, driving satellite-verified geolocation tagging for argan and prickly pear sourcing. Halal-certification alignment has become a non-negotiable filter for Gulf cosmetics procurement, restructuring processing lines to capture premium positioning.
Egypt
Generic drug manufacturers are expanding botanical active procurement volumes as cost-containment pressures intensify for off-patent formulations. The country's drug authority maintains non-harmonized herbal medicine pathways with SAHPRA, forcing duplicate stability studies for multi-market operators. Processing clusters in Cairo and Alexandria are consolidating around standardized herbal extract supply for pharmaceutical API production.
Ethiopia
Frankincense harvesting regions in the Somali Region and Puntland supply the majority of global Boswellia resin, exposing processors to harvest volatility from regional security disruptions. Extended resin curing protocols are compressing inventory velocity for tincture supply chains compared to Moroccan argan corridors. Cold-chain infrastructure investment requirements for thermolabile compound preservation are straining processor balance sheets without established offtake guarantees.
Middle East and Africa Botanical Extract Market Competitive Landscape
Channel-controlling players compete with product-specialist players across extraction technology tiers, with consolidated European technical bases supplying standardized extracts into North African pharmaceutical channels while regional specialists anchor indigenous species sourcing. The market structure fragments across three strategic archetypes: European extract houses with Gulf beverage formulation partnerships, African indigenous species specialists with captive biome access, and Gulf-based halal-certified processors serving cosmetics demand. Dominant competitive moves include backward integration into captive cultivation to preempt EU deforestation due diligence requirements, and technology licensing for supercritical CO2 systems to displace solvent-based methods.
Within the European technical base tier, Martin Bauer Group and Döhler Group SE exemplify channel-controlling positions, with the former anchoring pharmaceutical extract supply and the latter anchoring beverage formulation partnerships in the Gulf. African Botanicals Ltd. occupies the indigenous specialist archetype, sourcing from southern African biomes under Nagoya Protocol frameworks. These three entities represent the core competitive vectors: European technical standardization, regional biome access, and Gulf halal-compliance infrastructure.
| Leading Market Players |
|---|
| Martin Bauer Group |
| Döhler Group SE |
| International Flavors & Fragrances Inc. |
| Givaudan |
| Al Khair Natural Herbs Factory |
| Indena S.p.A. |
| Kalsec Inc. |
| African Botanicals Ltd. |
| Synthite Industries Ltd. |
| Others |
Supply & Pricing Matrix
Ethiopia's Somali Region and Puntland supply 80% of global Boswellia resin, concentrating upstream margin capture with harvesters while Gulf cosmetics manufacturers and North African pharmaceutical firms compete for downstream allocation of frankincense derivatives. This supply concentration enables origin-based price premiums for traceable resin batches, though regional security disruptions periodically force buyers into Moroccan argan or Kenyan pyrethrum substitutes.
Pricing Analysis
Long-term offtake contracts with resin indexation dominate Ethiopian frankincense procurement, while Moroccan argan oil trades on spot-plus-certification terms. Price differentiation rests on halal-compliance documentation and EU Green Deal geolocation verification, with compliant batches commanding 15-20% premiums over conventional grades. Cost compression in mid-tier cosmetic applications is intensifying because European fermentation-derived phytochemicals are capturing share where botanical provenance carries no premium. Generic drug manufacturers in Egypt and Nigeria exhibit highest price sensitivity due to cost-containment mandates, while Gulf cosmetics houses prioritize certification reliability over unit cost.
Supply Chain Analysis
Export-control regimes on supercritical CO2 extraction technology limit equipment flows into East African processing facilities, constraining local value-addition capacity. Raw material dependencies center on Ethiopian Boswellia resin, Moroccan argan kernels, and South African indigenous biome species. Single-source vulnerability concentrates in the Somali Region harvest zones, where regional security disruptions threaten 80% of global frankincense supply. Distribution runs through vertically integrated European extract houses serving North African pharmaceutical channels, regional specialists with captive cultivation, and Gulf-based halal-certified processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. SAHPRA and Egypt's drug authority maintain non-harmonized registration tracks that extend toxicology study timelines, raising barriers for new entrants.
For Market Incumbents: Insulate market position by deepening backward integration into GACP-certified cultivation in Kenya's Mount Kenya highlands before EU deforestation due diligence hardens. Prioritize blockchain-traceability infrastructure investment to preempt buyer-mandated documentation requirements. Synthetic substitution from European biotech suppliers threatens mid-tier cosmetic applications; defend by restructuring extraction lines for halal-certified alcohol-free methods that command Gulf premiums. For New Entrants and Emerging Players: Kenya's pyrethrum and Artemisia cultivation zones remain underdeveloped for GACP-certified extract supply, offering first-mover positioning with 12-18 month auditor backlogs protecting early investment. Target nutraceutical applications in South Africa's aging demographic segment, where immune-support positioning shows accelerated uptake. Enter through supercritical CO2 technology licensing partnerships that displace solvent-based methods and satisfy SAHPRA stability requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European extract houses seeking regional expansion into North African pharmaceutical channels. Long-term viability hinges on regulatory compliance infrastructure rather than commodity extraction economics. Monitor SAHPRA-Egypt harmonization negotiations as inflection indicator; successful convergence would compress multi-market operator compliance costs and revalue integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GACP-Certified Cultivation | Captures origin-based premiums and preempts EU Green Deal deforestation due diligence enforcement. |
| Supercritical CO2 Technology Licensing | Displaces solvent-based methods to meet SFDA heavy-metal protocols and SAHPRA stability requirements. |
| Blockchain Traceability Infrastructure | Enables real-time provenance verification for Gulf cosmetics manufacturers mandating halal supply chain documentation. |
| Halal-Certified Processing Line Restructuring | Captures 15-20% price premiums in Dubai and Riyadh formulation houses where religious compliance filters procurement. |
| Dual Registration Track Harmonization Investment | Reduces duplicate toxicology study burdens for multi-market operators serving South Africa and Egypt simultaneously. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with extract processors, pharmaceutical procurement managers, cosmetics formulation houses, and GACP certification auditors. Secondary validation drew from SAHPRA registration databases, SFDA import protocols, EU Green Deal due diligence guidance, and customs trade records for botanical material flows. Bottom-up volume modeling triangulated against top-down industry sizing across product type, application, and regional regulatory clusters.
Calibration anchored historical growth patterns against documented regulatory enforcement timelines and technology adoption curves for supercritical extraction systems. Segmentation dimensions spanned product type, application, form, and end user, with additional modeling for halal-certification tier and EU Green Deal compliance status. CAGRs were derived from regression analysis of procurement volume trends correlated with regulatory deadline proximity. Forecast inputs incorporated SAHPRA-Egypt harmonization probability assessments and synthetic substitution elasticity estimates for mid-tier cosmetic applications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European biotech suppliers into fermentation-derived phytochemicals would shift outcomes beyond modeled ranges. Material shifts in SAHPRA registration timelines or EU deforestation enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Ghost Pepper Salt Market