
 Egypt Food Colorants Market | 2026-2036
Egypt Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Colorants Market Foresight
Modular colorant dosing systems for small-batch bakery operations is shifting procurement patterns across Egypt's food manufacturing base. Chr. Hansen Holding A/S leverages its fermentation-derived pigment portfolio to anchor supply relationships with dairy processors in the Alexandria free zone. Sensient Technologies Corporation competes through localized technical service teams that support beverage reformulation projects. Mahickra Chemicals Limited specializes in lake pigments for heat-stable confectionery applications, occupying a defensible niche in chocolate coating segments.
Food colorants comprise chromophore-bearing compounds—natural extracts such as anthocyanins and carotenoids, or azo and triarylmethane synthetic dyes—formulated to impart visual identity at dosages typically ranging from 0.01% to 0.5% by weight. These substances serve commercial purposes including flavor expectation management, shelf-life signaling, and brand differentiation across packaged food categories. Natural Colors command premium positioning as Egyptian beverage producers face reformulation pressure from Gulf export markets demanding clean-label compliance. Synthetic Dyes retain volume dominance in confectionery and bakery segments where cost thresholds and heat stability requirements constrain substitution. Liquid formulations lead the Form dimension due to metering precision in automated dairy and soft-drink processing lines.
Egypt's national food safety regulator and the Egyptian Organization for Standardization and Quality enforce additive maximum limits aligned with Codex Alimentarius frameworks, while import inspections at Alexandria and Damietta ports screen for non-certified color batches. Compliance documentation requirements shape supplier selection criteria, particularly for European-owned manufacturers subject to dual jurisdiction. Stakeholders must monitor enforcement consistency across Egypt's regional health directorates and assess whether domestic natural extraction capacity can offset import dependency for carmine and turmeric-derived alternatives.
Market Dynamics
Reformulation pressure from Gulf export markets is restructuring procurement relationships across Egypt's food colorants value chain, as clean-label compliance requirements cascade downstream from Saudi and UAE buyers into Nile Delta manufacturing operations.
Growth Catalysts
- EFSA-aligned additive maximum limits:Egypt's national food safety regulator enforces Codex Alimentarius-aligned standards that elevate certified suppliers above uncertified competitors, creating procurement preference for documented compliance.
- Confectionery seasonal production cycles:Cairo and Alexandria manufacturers expand synthetic dye volumes for Ramadan and Eid sweets production, generating predictable demand spikes that stabilize supplier revenue streams.
- Fermentation-derived anthocyanins:Biotechnology advances reduce production costs for natural red pigments, narrowing the price gap with azo dyes in beverage applications.
Market Restraints
- Import dependency for carmine and turmeric:Domestic extraction capacity remains insufficient, exposing formulators to currency fluctuation risk and port inspection delays at Alexandria and Damietta.
- Heat stability limitations of natural alternatives:Anthocyanins degrade above 85°C, constraining substitution in chocolate coating and baked goods where lake pigments retain technical dominance.
- Dual jurisdiction compliance costs:European-owned manufacturers face overlapping Egyptian and EU documentation requirements, inflating administrative overhead relative to purely domestic competitors.
Strategic Opportunities
- Upper Egypt underpenetration:Industrial zones in Sohag and Aswan lack dedicated colorant technical service infrastructure, creating first-mover advantage for suppliers establishing localized dosing system support.
- Clean-label dairy reformulation:EFSA natural colorant approvals enable Egyptian processors to reposition yogurt and cheese exports for premium Gulf retail channels.
- Modular dosing system leasing:Equipment-as-a-service models reduce capital barriers for small-batch bakery adoption of precision liquid metering.
Industry Challenges
- Reformulation chemist scarcity:Technical expertise for natural-synthetic substitution in heat-sensitive applications concentrates in Alexandria and Cairo, limiting interior plant capabilities.
- Batch certification timeline compression:Egyptian Organization for Standardization and Quality documentation reviews extend lead times for new product launches, constraining seasonal responsiveness.
- Lake pigment wastewater treatment:Aluminum salt recovery requirements inflate environmental compliance capital expenditure for confectionery coating operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Colorants Market |
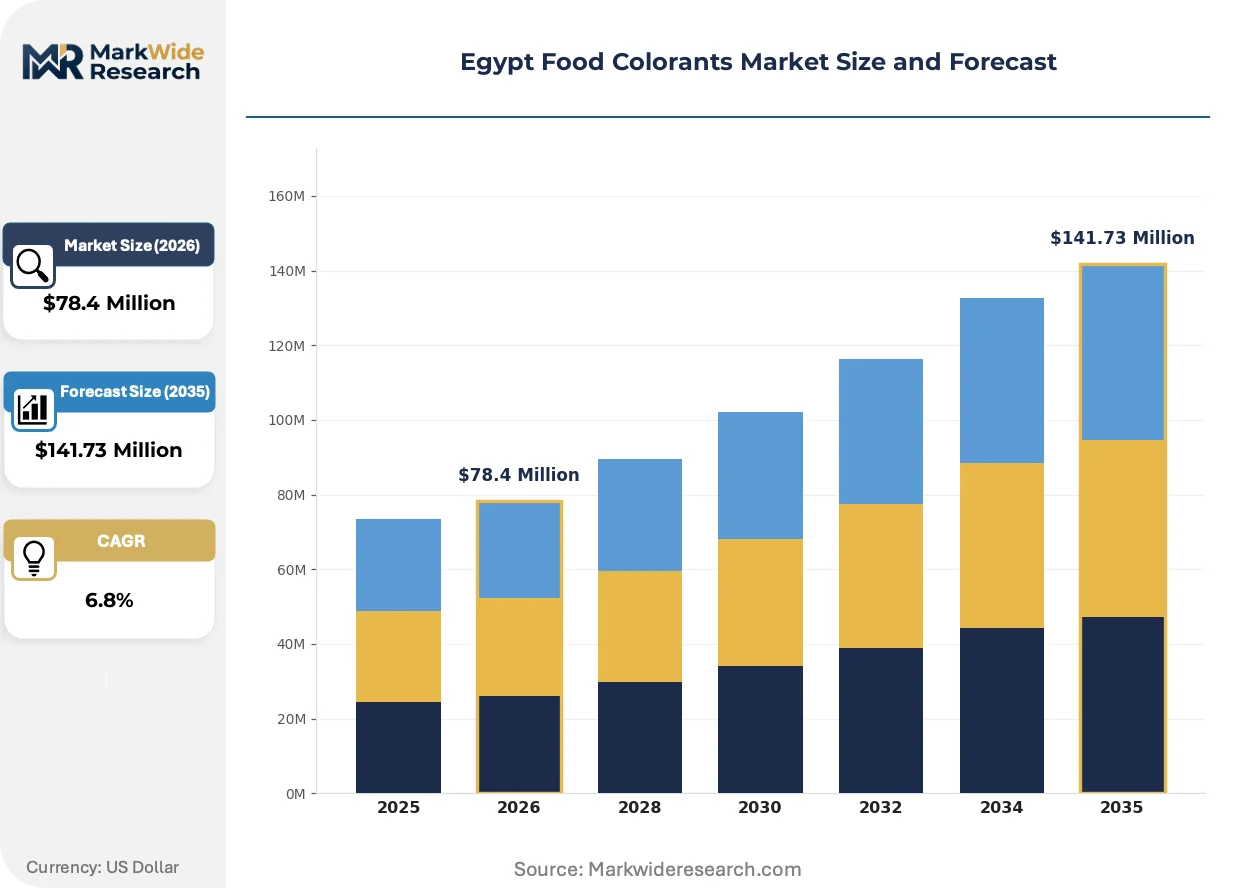
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Dyes, Lakes, Color Additives Application: Beverages, Bakery, Confectionery, Dairy Products Form: Liquid, Powder, Gel, Granules End User: Food Manufacturers, Beverage Producers, Restaurants, Pastry Shops |
| Companies Covered | JJT Group (Roha), REDSUN DYE CHEM, BASF SE, Döhler GmbH, Mahickra Chemicals Limited, Chr. Hansen Holding A/S, Kolorjet Chemicals Pvt Ltd, Archer Daniels Midland Company, Sensient Technologies Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Colorants Market Shifts & Advancements
Precision dosing hardware and biotechnology-derived pigments are converging to compress minimum viable production runs, enabling smaller Egyptian manufacturers to access colorant quality tiers previously reserved for multinational scale operations.
Modular colorant dosing systems integrate peristaltic pumps with IoT-enabled flow monitoring to deliver sub-milliliter accuracy in artisan bakery settings. Small-batch producers in Cairo's industrial quarters adopt these units to reduce waste and standardize shade consistency across production runs. The technology is modularizing equipment procurement, allowing manufacturers to scale dosing capacity incrementally rather than committing to centralized tank systems.
Egypt's updated consumer protection standards mandate additive disclosure thresholds that exceed previous labeling requirements, forcing reformulation documentation upgrades across the supply base. Domestic manufacturers serving European-owned clients must maintain dual compliance files to satisfy both Egyptian and EFSA audit protocols. Beverage exporters targeting Saudi and UAE markets face the steepest adaptation burden, as Gulf retailers enforce clean-label verification beyond statutory minimums.
Direct supplier relationships are displacing traditional distributor intermediaries in Alexandria's free zone dairy cluster. Processors negotiate volume commitments with fermentation-derived pigment specialists to secure technical service embedment, bypassing generalist chemical traders. This pattern concentrates most visibly in yogurt and flavored milk operations where shade consistency directly impacts shelf appeal in premium retail channels.
Egypt Food Colorants Market Segmentation
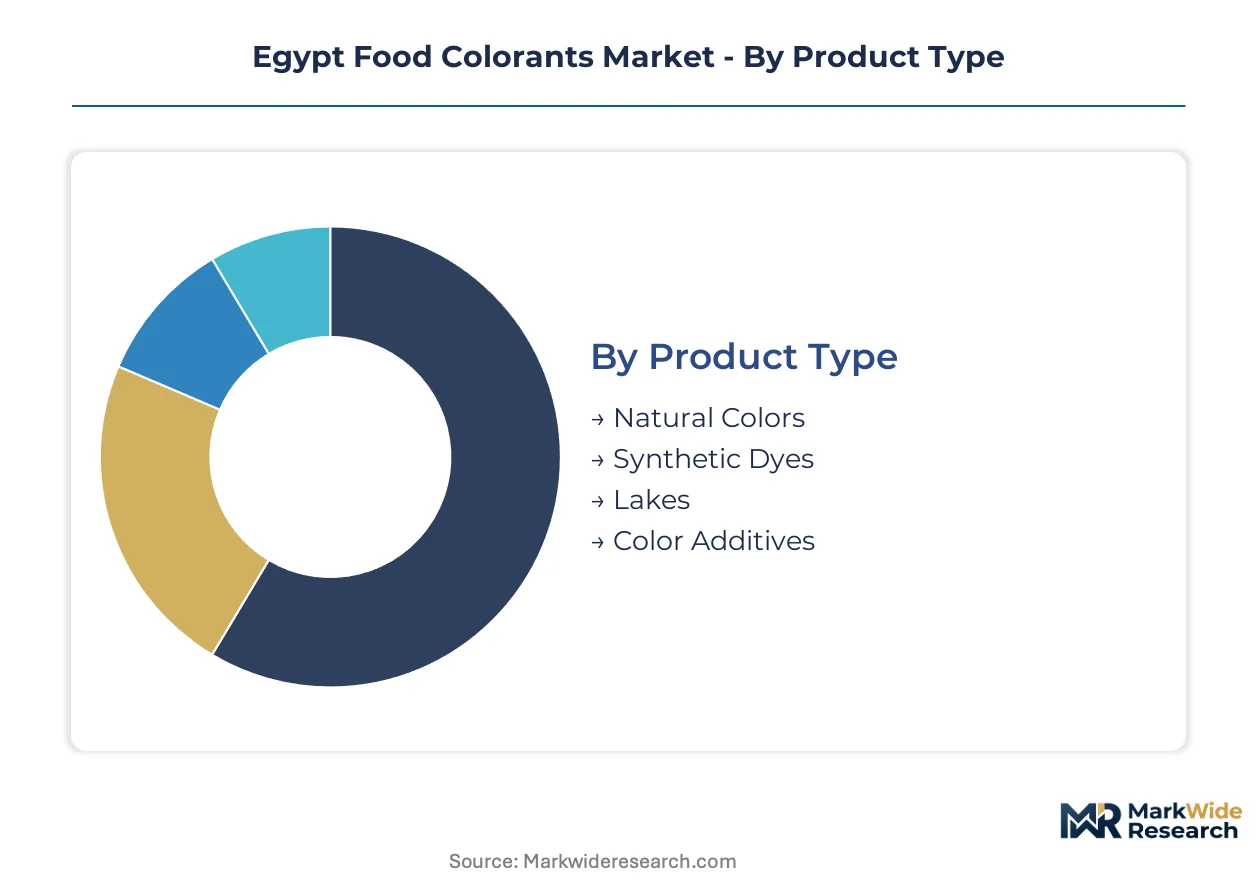
Segmentation in Egypt's food colorants market reveals how capital intensity, regulatory compliance burdens, and technical service requirements reshape supplier-procurement relationships. Manufacturers align colorant selection with heat stability demands, dosing precision needs, and export market labeling standards.
Product Type:
Capital intensity varies sharply across extraction and synthesis pathways, with fermentation infrastructure and lake pigment aluminum salt recovery systems demanding the heaviest upfront investment.
- Natural Colors:Anthocyanins, carotenoids, and turmeric-derived pigments require biotechnology fermentation capacity or agricultural extraction facilities. Beverage producers in the Nile Delta industrial corridor are reformulating with these alternatives to meet Gulf export clean-label requirements, though heat stability above 85°C remains problematic for baked goods applications.
- Synthetic Dyes:Azo and triarylmethane compounds dominate volume through cost efficiency and thermal resilience. Cairo and Alexandria confectionery manufacturers expand procurement for Ramadan and Eid seasonal production, where lake pigment heat stability proves essential for chocolate coating operations.
- Lakes:Aluminum salt complexes of water-soluble dyes provide insoluble color for fat-based applications. Alexandria free zone dairy processors favor these for butter and cheese surface coloring.
- Color Additives:Blended formulations and specialty compounds address niche functional requirements. Small-batch bakery operations in Cairo's industrial quarters adopt these for shade consistency across limited production runs.
Synthetic Dyes absorb the bulk of installed capacity; Natural Colors is expanding most quickly as fermentation-derived anthocyanins narrow the price gap with azo alternatives.
Application:
End-use differentiation centers on thermal processing intensity and export market compliance exposure, with beverage and dairy segments facing the steepest clean-label adaptation burdens.
- Beverages:Soft drinks, juices, and flavored waters demand liquid colorants with precise metering compatibility. Reformulation pressure from Saudi and UAE retail channels is restructuring procurement toward EFSA-aligned natural alternatives, particularly anthocyanins for red fruit shades.
- Confectionery:Seasonal sweets production in Cairo and Alexandria generates predictable demand spikes for heat-stable synthetic dyes and lake pigments. Chocolate coating applications require aluminum salt complexes that withstand tempering temperatures without degradation.
- Bakery:Bread, pastries, and biscuits utilize both liquid and powder formulations depending on mixing equipment. Upper Egypt industrial zones in Sohag and Aswan remain underpenetrated for technical service support.
- Dairy Products:Yogurt, cheese, and flavored milk operations in Alexandria's free zone prioritize shade consistency for premium retail shelf appeal. Direct supplier relationships are displacing traditional distributor intermediaries in this cluster.
Confectionery commands the largest volume share through seasonal production cycles; Beverages is climbing the fastest as export-oriented reformulation accelerates.
Form:
Processing automation levels and dosing precision requirements determine formulation selection, with liquid systems carrying higher equipment integration costs but superior metering accuracy.
- Liquid:Pump-compatible formulations dominate automated dairy and soft-drink processing lines. IoT-enabled flow monitoring systems enable sub-milliliter accuracy that reduces waste in high-volume operations.
- Powder:Dry blends suit bulk bakery and confectionery mixing where dissolution uniformity is less critical. Seasonal sweets manufacturers in Cairo favor these for cost efficiency in large-batch Ramadan production.
- Gel:Viscous concentrates target artisan applications requiring manual dosing control. Pastry shops in Alexandria use these for decorative finishing work.
- Granules:Free-flowing particles address specific dispersion challenges in dry mix applications. Limited adoption concentrates in specialty bakery premixes.
Liquid formulations hold the dominant installed base; Powder is gaining share fastest in cost-sensitive seasonal production segments.
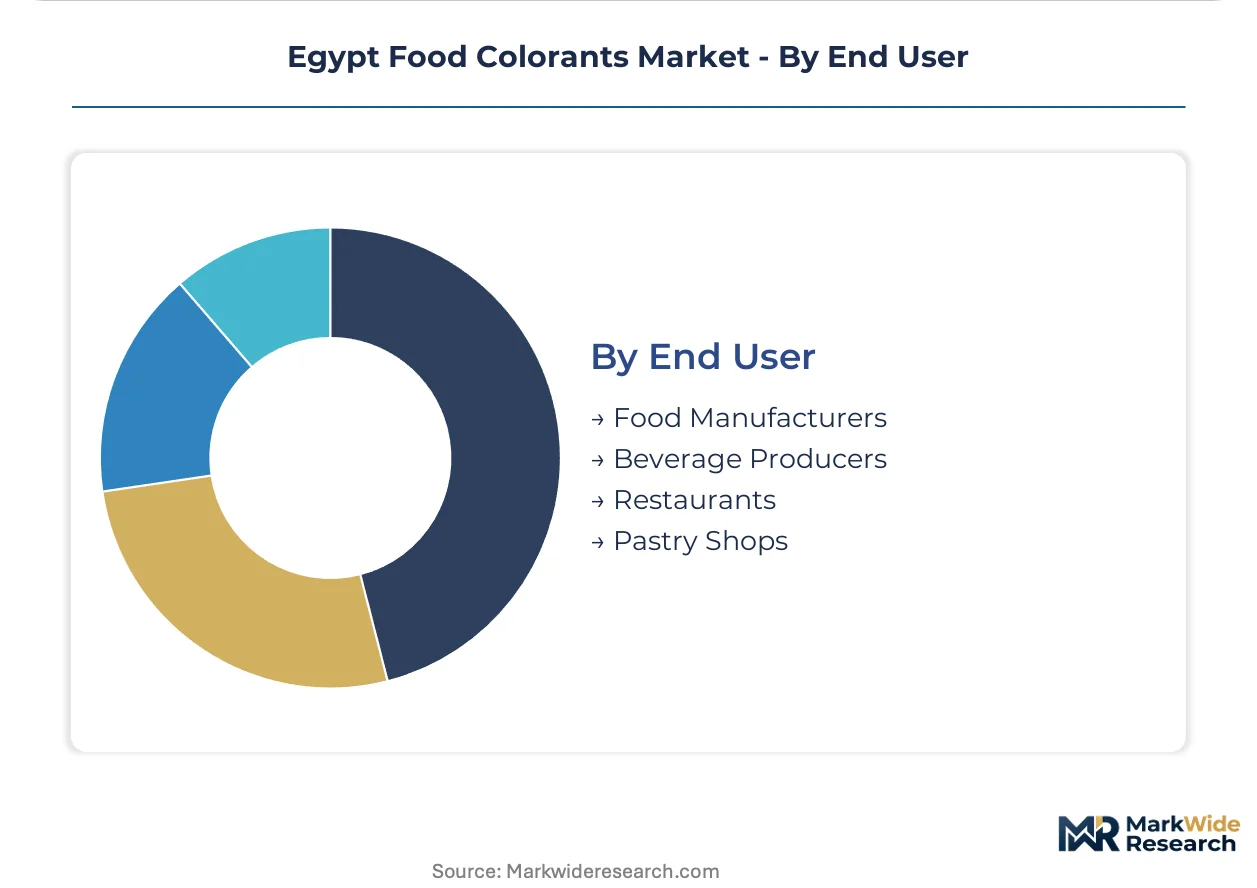
End User:
Customer scale and technical sophistication create distinct service requirements, with multinational food manufacturers demanding embedded formulation support unavailable to smaller operators.
- Food Manufacturers:Packaged goods producers across categories require batch certification documentation and dual jurisdiction compliance files. European-owned manufacturers face overlapping Egyptian and EU audit protocols that inflate administrative overhead.
- Beverage Producers:Soft drink and juice operations prioritize clean-label verification for Gulf export markets. Nile Delta facilities lead adoption of natural color alternatives.
- Restaurants:Food service operations utilize colorants for sauce, dessert, and beverage preparation. Procurement runs through general chemical distributors rather than direct supplier relationships.
- Pastry Shops:Artisan bakeries and confectioners favor gel and small-batch liquid formats. Modular dosing system leasing models are reducing capital barriers for precision metering adoption.
Food Manufacturers represent the largest customer category by volume; Beverage Producers show the steepest expansion trajectory as export reformulation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alexandria's free zone tax incentives anchor Egypt's food colorant procurement concentration, drawing multinational dairy processors and fermentation-derived pigment suppliers into clustered technical service relationships.
Cairo Governorate
Seasonal confectionery manufacturers drive synthetic dye volumes for Ramadan and Eid sweets production. Egypt's national food safety regulator enforces updated additive labeling standards that elevate certified suppliers. Industrial quarters in Cairo's eastern districts adopt modular dosing systems for small-batch bakery precision.
Alexandria
Dairy processors in the free zone prioritize shade consistency for yogurt and cheese export positioning. The Egyptian Organization for Standardization and Quality mandates dual compliance documentation for European-owned manufacturers. Direct supplier relationships displace distributor intermediaries in this cluster.
Nile Delta Industrial Corridor
Beverage producers reformulate with natural color alternatives to meet Gulf export clean-label requirements. EFSA-aligned natural colorant approvals enable premium retail channel access. Facilities in Damietta and Mansoura concentrate anthocyanin procurement for red fruit shades.
Upper Egypt
Industrial zones in Sohag and Aswan remain underpenetrated for colorant technical service infrastructure. The country's consumer protection standards extend enforcement to regional health directorates with variable consistency. First-mover suppliers establishing localized dosing system support capture undefended market positions.
Egypt Food Colorants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Egypt's food colorants procurement landscape. The vendor base fragments between multinational chemical conglomerates with broad additive portfolios and regional manufacturers occupying defensible niches in lake pigments and fermentation-derived natural colors. Three strategic archetypes dominate: fermentation technology specialists, synthetic dye volume suppliers, and integrated natural extract processors. Competitive moves concentrate on direct technical service embedment and modular equipment leasing partnerships.
Within the fermentation-derived pigment tier, Chr. Hansen Holding A/S anchors supply relationships with Alexandria free zone dairy processors through biotechnology expertise. Sensient Technologies Corporation exemplifies the technical service-intensive archetype with localized teams supporting beverage reformulation. Mahickra Chemicals Limited occupies a specialized position in lake pigments for heat-stable confectionery applications. BASF SE represents the diversified conglomerate model with synthetic dye volumes serving Cairo's seasonal sweets manufacturers.
| Leading Market Players |
|---|
| JJT Group (Roha) |
| REDSUN DYE CHEM |
| BASF SE |
| Döhler GmbH |
| Mahickra Chemicals Limited |
| Chr. Hansen Holding A/S |
| Kolorjet Chemicals Pvt Ltd |
| Archer Daniels Midland Company |
| Sensient Technologies Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists concentrated in Cairo's industrial quarters anchor supply discipline through long-standing distributor relationships, while their limited fermentation capacity constrains natural colorant availability and props pricing premiums for EFSA-certified alternatives. This ownership pattern insulates pricing from volatile spot-market swings but exposes buyers to allocation risk during seasonal demand spikes.
Pricing Analysis
Cost-down pressure on synthetic dye tiers accelerates because Cairo confectionery manufacturers consolidate procurement volumes ahead of Ramadan production cycles. Three-tier pricing structure across premium EFSA-certified natural extracts, standard Codex-aligned synthetics, and economy-grade uncertified dyes separates buyers by export compliance exposure. Pricing pressure stems from currency fluctuation risk on carmine and turmeric imports through Alexandria port. Beverage producers targeting Gulf retail channels show least price sensitivity; small-batch bakeries in Upper Egypt exhibit highest.
Supply Chain Analysis
Reverse-logistics infrastructure for aluminum salt recovery from lake pigment wastewater remains underdeveloped, inflating environmental compliance capital expenditure for confectionery coating operations. Supply concentrates in India for turmeric extraction, Peru for carmine, and China for synthetic azo intermediates. Raw material dependencies span cochineal insects, petroleum-derived aniline, and fermentation feedstocks. Single-source vulnerability on anthocyanin fermentation capacity poses structural risk. Distribution runs through Alexandria free zone bonded warehouses serving Nile Delta beverage clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: domestic fermentation capacity for natural red pigments caps available volume and props pricing premiums for EFSA-certified alternatives. Incumbents must defend position through capacity discipline rather than price competition.
For Market Incumbents: Cement supply relationships with Alexandria free zone dairy processors through embedded technical service teams that support shade consistency documentation for Gulf export compliance. Defend against fermentation-derived pigment specialists by securing exclusive volume commitments from Nile Delta beverage reformulation projects. Prioritize backward integration into aluminum salt recovery systems to offset wastewater treatment cost inflation in lake pigment operations. For New Entrants and Emerging Players: Direct-to-processor digital procurement platforms bypass traditional distributor markups in Upper Egypt's underpenetrated Sohag and Aswan industrial zones. Target small-batch bakery operations with modular dosing system leasing models that reduce capital barriers for precision liquid metering adoption. Anchor initial beachhead through seasonal sweets manufacturers seeking shade consistency standardization ahead of Ramadan production cycles. For Investors and Strategic Acquirers: Egyptian Organization for Standardization and Quality enforcement consistency across regional health directorates is the leading indicator that certification-premium pricing will sustain versus erode. Frame long-term viability around natural extraction capacity scarcity: fermentation infrastructure deployment timelines suggest a 5-10 year window where certified natural pigment supply remains structurally tight. Monitor port inspection throughput rates at Alexandria and Damietta for early signals of import dependency risk realization.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Chr. Hansen biotechnology expertise anchors supply security for Alexandria dairy processors facing Gulf clean-label mandates. |
| Modular Dosing System Leasing | Equipment-as-a-service models reduce capital barriers for Cairo artisan bakeries adopting precision liquid metering. |
| Direct Supplier Relationship Development | Bypassing distributor intermediaries concentrates technical service embedment in Nile Delta beverage reformulation projects. |
| Aluminum Salt Recovery Investment | Wastewater treatment compliance capital expenditure defends lake pigment cost position in chocolate coating segments. |
| Upper Egypt Technical Service Deployment | First-mover dosing system support captures undefended market positions in Sohag and Aswan industrial zones. |
Research Methodology
Trade databases, Egyptian Organization for Standardization and Quality regulatory filings, and Alexandria Port Authority import records formed the secondary backbone, cross-referenced against primary interviews with fermentation technology specialists, confectionery procurement managers, dairy processing engineers, and colorant distribution channel heads. Bottom-up and top-down triangulation validated volume estimates across natural and synthetic product tiers.
Bottom-up modeling anchored segment-level projections while top-down macro constraints ensured aggregate consistency across the analysis window. Segmentation dimensions spanned product type, application category, formulation form, and end-user scale. CAGRs derived from trend extrapolation of seasonal production cycles, export compliance adoption curves, and fermentation capacity deployment timelines. Forecast inputs incorporated Gulf retail clean-label verification intensity and Egyptian consumer protection standard enforcement consistency.
The model holds under sustained EFSA alignment and Codex Alimentarius framework stability; deviation in regional health directorate enforcement capacity or currency fluctuation severity on carmine imports would shift natural-to-synthetic substitution trajectories. Practitioners should monitor Alexandria port inspection backlog duration and fermentation-derived anthocyanin spot price spreads for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Bitter Apricot Extract Market