
 Security Market | 2026-2036
Security Market Size, Share, and Industry Trends Forecast 2026-2036
Security Market Intelligence
GDPR enforcement is hardening data residency mandates for cloud security providers across European financial institutions. Honeywell International leverages its building automation footprint to anchor integrated physical-cyber offerings in North American critical infrastructure. Securitas AB competes through its manned guarding density while Hikvision dominates video analytics manufacturing scale in Asian surveillance deployments.
Security encompasses protective systems, detection hardware, and response protocols engineered to safeguard assets, personnel, and information against unauthorized access or harm. Core functional parameters include mean-time-to-detection thresholds, encryption key lengths, and biometric false acceptance rates below 0.001%. Physical Security solutions sustain the largest revenue pool as perimeter hardening remains non-discretionary for utilities and transportation hubs. Cloud Security is expanding fastest as enterprise workload migration accelerates demand for zero-trust architecture implementation. Managed Security Services concentrates margin pools where 24/7 security operations center staffing creates recurring revenue stickiness with commercial enterprises.
FDA cybersecurity guidance for connected medical devices, FCC network reliability standards, and EU AI Act risk classification tiers collectively shape product certification timelines and cross-border market access for security vendors. The EU Green Deal's digital infrastructure efficiency mandates are pressing data center operators to embed energy-conscious cooling with physical access controls. Stakeholders must weigh sovereign data requirements against interoperability standards when architecting multi-jurisdiction deployment strategies.
Market Dynamics
AI-powered threat detection is absorbing capital allocation across financial services and critical infrastructure, compressing procurement cycles for legacy perimeter systems while forcing vendors to rearchitect software stacks for EU AI Act compliance.
Growth Catalysts
- EU AI Act risk classification:Automated surveillance platforms face mandatory conformity assessments, creating replacement demand for compliant biometric systems across European transportation hubs and utilities.
- Critical infrastructure hardening:Power grid operators and water treatment facilities are non-discretionary buyers of integrated physical-cyber platforms regardless of macroeconomic pressure.
- Zero-trust architecture mandates:Enterprise workload migration to cloud environments is pulling investment toward identity-centric security models and software-defined perimeters.
Market Restraints
- Semiconductor supply concentration:Video analytics hardware depends on specialized image processing chips sourced from a concentrated East Asian foundry base, exposing lead time volatility.
- GDPR data residency friction:Cross-border threat intelligence sharing faces sovereign data requirements that fragment cloud security vendor operating models.
- Biometric false acceptance thresholds:Sub-0.001% accuracy requirements for high-assurance authentication impose R&D cost burdens that disadvantage mid-tier technology providers.
Strategic Opportunities
- India critical infrastructure modernization:Smart city deployments and port digitization under national infrastructure programs are opening procurement channels for integrated surveillance and access control.
- Convergence of building automation and security:HVAC and lighting control systems are merging with access management, creating bundled solution opportunities for facility management providers.
- EU Green Deal efficiency mandates:Data center cooling and physical access control integration requirements are pressing operators toward energy-conscious security architecture.
Industry Challenges
- Security operations center staffing shortages:24/7 monitoring capabilities require specialized analyst talent that remains scarce relative to managed services demand expansion.
- Legacy system integration complexity:Brownfield deployments in industrial environments must bridge decades-old SCADA architectures with modern IP-based threat detection.
- Multi-jurisdiction certification timelines:Vendors face staggered FDA, FCC, and EU AI Act approval processes that delay product launches across key markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Market |
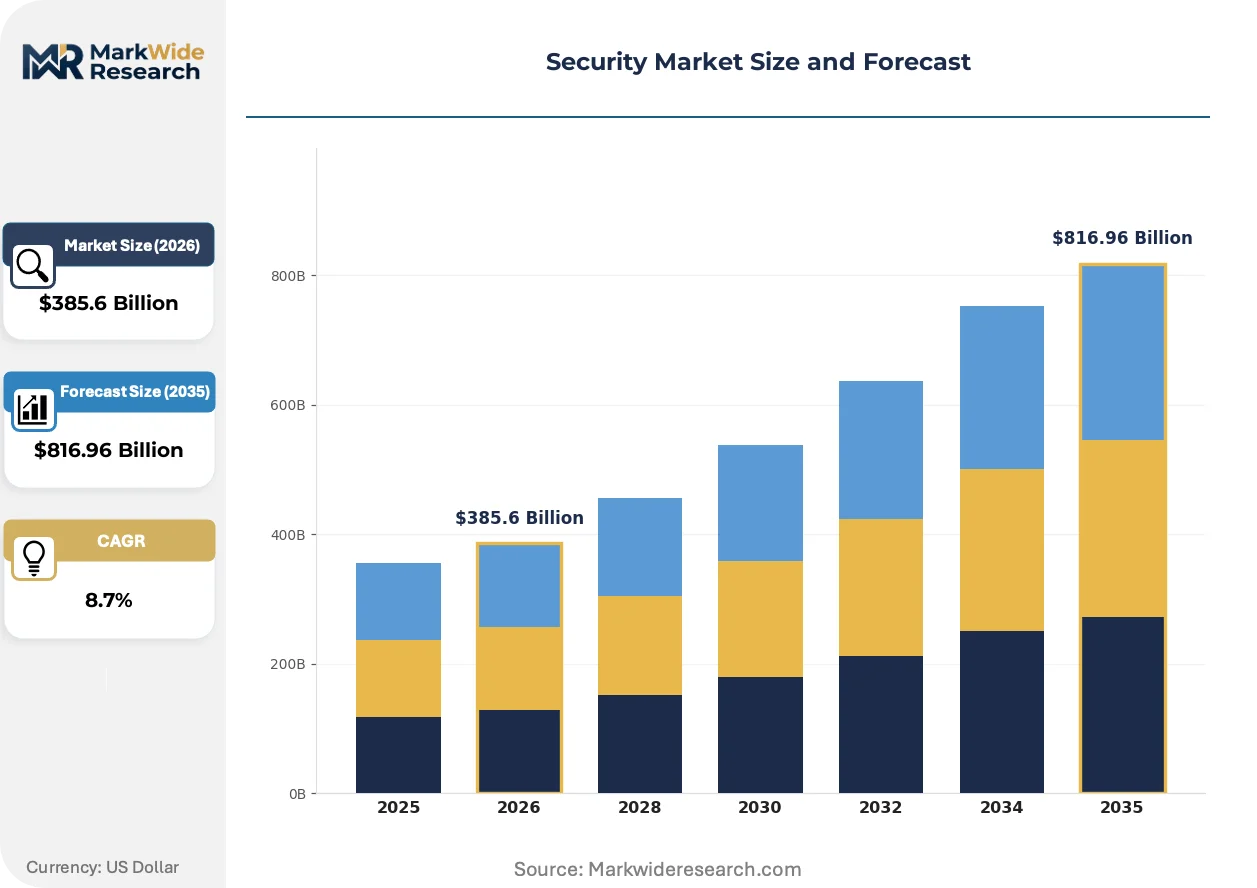
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $816.96 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Physical Security, Cybersecurity Solutions, Managed Security Services, Surveillance Systems End User: Government, Commercial Enterprises, Residential Users, Educational Institutions Technology: AI-Powered Surveillance, Biometric Systems, Encryption Technologies, Cloud Security Service Type: Consulting Services, Installation Services, Maintenance Services, Risk Assessment |
| Companies Covered | Johnson Controls, Honeywell International, Robert Bosch GmbH, ADT Security Services, Hangzhou Hikvision Digital Technology, Allied Universal Security Services, Securitas AB, Assa Abloy, Secom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Market Strategic Shifts & Innovations
Edge computing architectures are redistributing processing load from centralized data centers to distributed sensors, compressing latency for real-time threat response while complicating software update and patch management workflows across heterogeneous device fleets.
Behavioral biometrics is absorbing authentication workflows across mobile banking and remote workforce access, replacing static password and token methods. Financial institutions in Germany and Japan are deploying keystroke dynamics and gait analysis at scale. This technology is absorbing market share from fingerprint and facial recognition systems in high-friction use cases where users reject physical contact or visible enrollment.
The EU AI Act's risk-based classification framework is forcing surveillance vendors to reengineer training data governance and algorithmic transparency documentation. High-risk biometric applications face mandatory human-in-the-loop requirements and third-party conformity assessments. Critical infrastructure operators in France and Germany are prioritizing compliant platforms in procurement specifications, compressing sales cycles for certified vendors while freezing out non-compliant alternatives.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based service level agreements that transfer operational risk to security providers. Managed detection and response contracts now specify mean-time-to-containment guarantees rather than equipment delivery milestones. This pattern is most pronounced among United States healthcare systems navigating FDA cybersecurity guidance for connected medical devices, where liability concerns outweigh capital expenditure optimization.
Security Market Segmentation
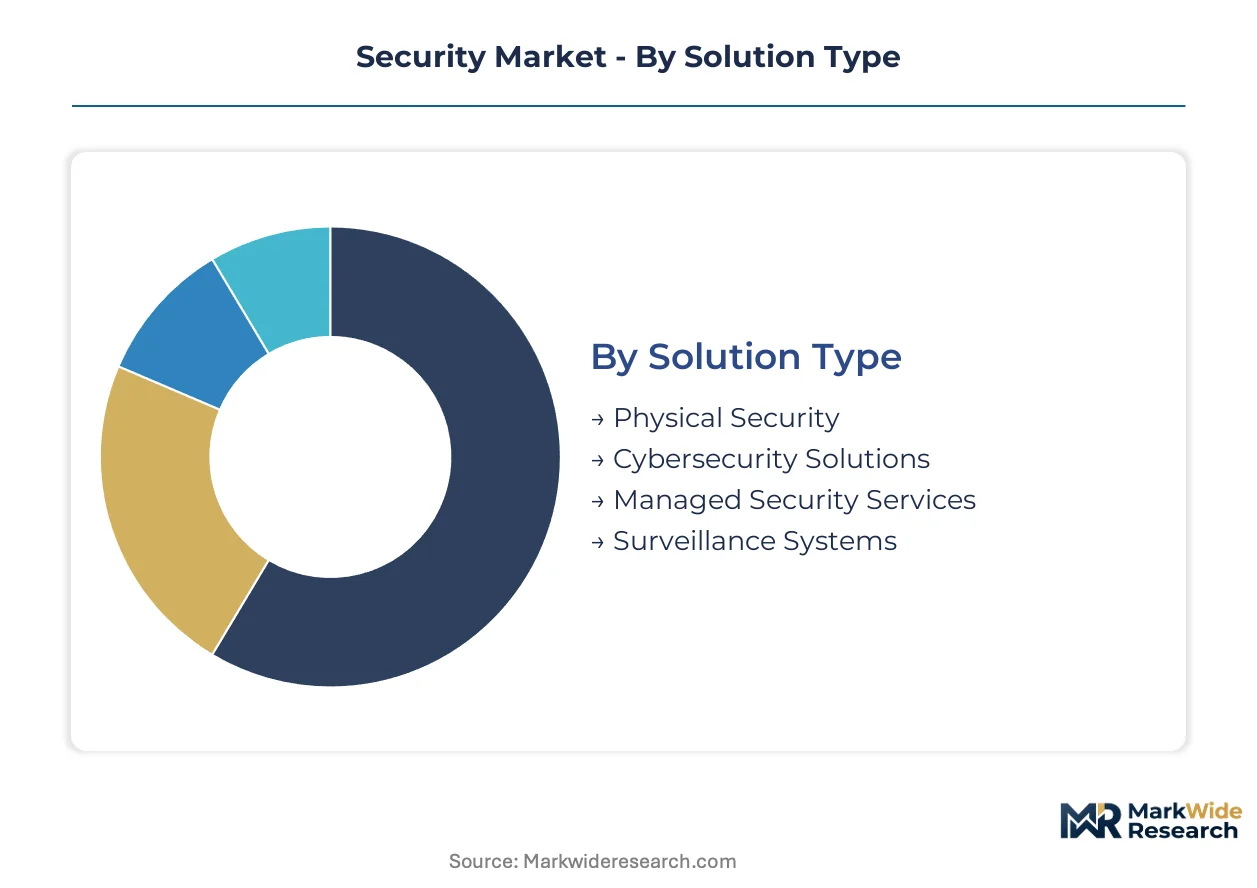
Security procurement decisions hinge on certification requirements that vary sharply across solution categories. Vendors must architect compliance roadmaps around FDA guidance for medical device cybersecurity, EU AI Act conformity assessments for biometric deployments, and FCC reliability standards for critical infrastructure networks.
Solution Type:
FDA cybersecurity guidance applies to connected medical devices within Cybersecurity Solutions, while EU AI Act risk tiers govern Physical Security and Surveillance Systems deployed in European transportation and utilities.
- Physical Security:Perimeter hardening systems integrate access control, intrusion detection, and environmental monitoring for utilities and transportation hubs. Power grid operators in the United States and Germany sustain non-discretionary procurement regardless of macroeconomic pressure, driven by critical infrastructure protection mandates.
- Cybersecurity Solutions:Software-defined platforms encompassing endpoint protection, network security, and threat intelligence engines. Enterprise workload migration to cloud environments across Japan and Germany accelerates demand for zero-trust architecture implementation and identity-centric security models.
- Managed Security Services:24/7 security operations center staffing creates recurring revenue stickiness with commercial enterprises facing analyst talent scarcity.
- Surveillance Systems:Video analytics hardware depends on specialized image processing chips from concentrated East Asian foundry bases, exposing lead time volatility.
Physical Security sits at the top of the volume ranking, with Cybersecurity Solutions climbing the fastest.
End User:
Government buyers impose the most stringent certification timelines, while Commercial Enterprises concentrate margin pools through outcome-based service level agreements.
- Government:National security agencies and defense departments require classified-cleared personnel and FedRAMP-compliant cloud architectures. Procurement specifications in France and Germany prioritize EU AI Act-certified biometric platforms, compressing sales cycles for compliant vendors.
- Commercial Enterprises:Financial services firms in the United States and Japan accelerate capital allocation toward AI-powered surveillance and behavioral biometric authentication. Outcome-based contracts now specify mean-time-to-containment guarantees rather than equipment delivery milestones.
- Residential Users:Smart home security adoption concentrates in connected device ecosystems with DIY installation preferences.
- Educational Institutions:Campus safety budgets prioritize integrated access control and emergency notification systems with grant-funded procurement cycles.
Government commands the largest contract values, with Commercial Enterprises expanding most quickly.
Technology:
Cost tiers separate mature encryption standards from emerging AI and biometric platforms requiring substantial R&D investment for sub-0.001% accuracy thresholds.
- AI-Powered Surveillance:Machine learning models trained on behavioral pattern recognition for real-time threat detection in critical infrastructure. EU AI Act's risk-based classification framework forces vendors to reengineer training data governance and algorithmic transparency documentation.
- Biometric Systems:Fingerprint, facial recognition, and iris scanning hardware with liveness detection capabilities. Financial institutions in Germany and Japan deploy keystroke dynamics and gait analysis at scale, absorbing authentication workflows from static password methods.
- Encryption Technologies:Post-quantum cryptographic standards and hardware security modules for data-at-rest protection.
- Cloud Security:Zero-trust architecture implementation and software-defined perimeters for enterprise workload migration.
Encryption Technologies dominates current deployment volumes, with AI-Powered Surveillance gaining share fastest.
Service Type:
Margin structures favor recurring Maintenance Services and Risk Assessment engagements over one-time Installation Services with compressed pricing.
- Consulting Services:Security architecture design and compliance readiness assessments for multi-jurisdiction deployment strategies. GDPR data residency mandates across European financial institutions create sovereign data requirements that fragment vendor operating models.
- Installation Services:Brownfield deployments in industrial environments bridge decades-old SCADA architectures with modern IP-based threat detection.
- Maintenance Services:Patch management and software update workflows for heterogeneous edge device fleets.
- Risk Assessment:Penetration testing and vulnerability management with liability transfer mechanisms for healthcare systems navigating FDA cybersecurity guidance.
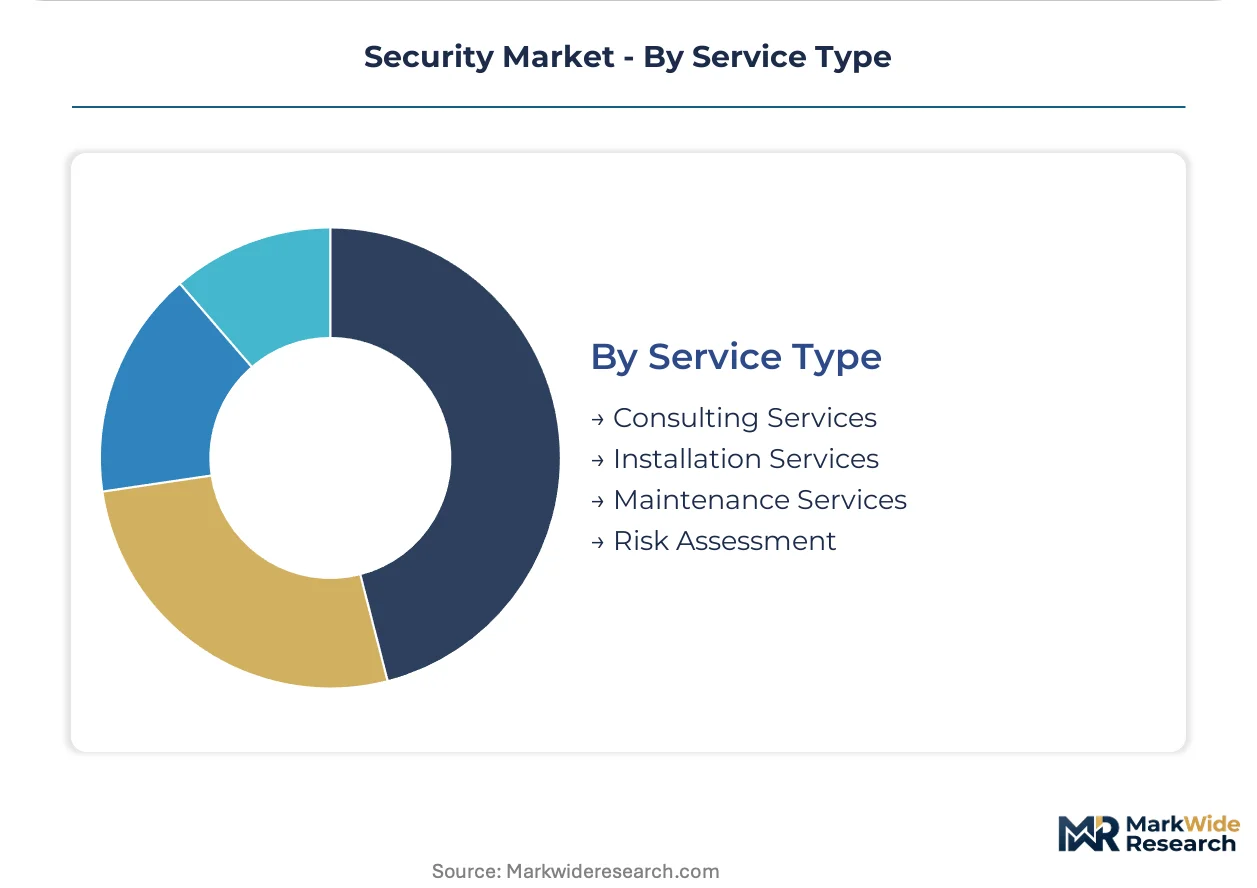
Maintenance Services anchors recurring revenue, with Risk Assessment showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The security industry traces its modern scaling to Cold War-era defense contracting clusters in the United States and subsequent commercialization through Japanese electronics manufacturing corridors. Contemporary demand patterns reflect this bifurcated heritage: North American software-centric platforms alongside Asian hardware production ecosystems.
United States
Critical infrastructure protection mandates from FERC and the Department of Homeland Security sustain non-discretionary procurement across power grid operators and water treatment facilities. FDA cybersecurity guidance for connected medical devices shapes hospital system security architecture requirements. The Washington D.C.-Northern Virginia corridor concentrates federal security contracting and cleared personnel staffing for government buyers.
Germany
EU AI Act risk classification tiers are compressing sales cycles for compliant biometric platforms across transportation hubs and utilities. The country's national data protection authority enforces GDPR data residency mandates that fragment cloud security vendor operating models. Industrial security procurement concentrates in Bavaria and North Rhine-Westphalia, where automotive and chemical manufacturing facilities bridge legacy SCADA with IP-based threat detection.
Japan
METI standards for critical infrastructure cybersecurity drive integrated physical-cyber platform adoption across port digitization and smart city deployments. Behavioral biometric authentication absorbs market share from fingerprint systems in Tokyo and Osaka financial services corridors. Keystroke dynamics and gait analysis scale rapidly where users reject physical contact enrollment.
India
National infrastructure programs under the Smart Cities Mission and port modernization initiatives open procurement channels for integrated surveillance and access control. The central bank's cybersecurity frameworks for financial institutions accelerate capital allocation toward AI-powered threat detection. Deployment activity concentrates in Maharashtra and Gujarat, where data center construction and manufacturing clusters expand physical security requirements.
United Kingdom
NCSC guidance for critical national infrastructure shapes vendor certification requirements across energy and telecommunications sectors. The Information Commissioner's Office enforces GDPR compliance timelines that delay product launches for biometric surveillance platforms. London's financial services density sustains demand for managed security services with 24/7 security operations center staffing.
Security Market Key Industry Players
The competitive structure tilts toward diversified conglomerates with building automation footprints anchoring integrated physical-cyber offerings. Mid-tier specialists compete through manned guarding density and regional service networks. Three archetypes dominate: automation-anchored platforms, guarding-centric service providers, and manufacturing-scale video analytics producers. Strategic moves concentrate on portfolio diversification into adjacent building systems and geographic expansion through national infrastructure program participation.
Among diversified conglomerates, Honeywell International and Johnson Controls occupy positions exemplifying the automation-anchored archetype. Robert Bosch GmbH represents European manufacturing heritage in security hardware. Within the guarding-centric tier, Securitas AB and Allied Universal Security Services exemplify service-scale competition. Hangzhou Hikvision Digital Technology anchors the video analytics manufacturing archetype. Assa Abloy and ADT Security Services sit within access control and residential monitoring specializations respectively. Secom represents integrated service models in Asian markets.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International |
| Robert Bosch GmbH |
| ADT Security Services |
| Hangzhou Hikvision Digital Technology |
| Allied Universal Security Services |
| Securitas AB |
| Assa Abloy |
| Secom |
| Others |
Cost & Logistics Intelligence
Critical infrastructure operators in the United States and Germany anchor procurement volume for integrated physical-cyber platforms, sustaining project-based pricing with outcome-based service level agreements that transfer operational risk to vendors. This buyer concentration compresses margins for standardized equipment while rewarding certified systems with EU AI Act and FDA cybersecurity compliance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified biometric systems with sub-0.001% false acceptance rates from uncertified alternatives. Price differentiation hinges on EU AI Act conformity assessment completion and FedRAMP cloud authorization status. Cost compression in the economy tier intensifies as mid-tier providers face R&D burdens for high-assurance authentication accuracy. Government buyers exhibit lowest price sensitivity due to non-discretionary critical infrastructure mandates, while residential DIY segments drive hardest bargain negotiations.
Supply Chain Analysis
Specialized security operations center analyst talent scarcity in India and Eastern European delivery hubs constrains managed services scaling regardless of hardware availability. Video analytics hardware draws from concentrated East Asian foundry bases for image processing chips, with encryption module production centered in Germany and Japan. Single-source vulnerability in semiconductor supply exposes lead time volatility for surveillance system deployments. Distribution runs through direct enterprise sales teams for critical infrastructure accounts and integrator channels for commercial mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement specifications harden around EU AI Act-certified biometric platforms and FDA cybersecurity guidance for connected medical devices, elevating compliant vendors above commodity competition.
For Market Incumbents: Hedge against margin erosion in legacy perimeter hardware by accelerating software-defined platform transitions and deepening backward integration into edge computing chip design. EU AI Act compliance investments create defensive moats against mid-tier challengers unable to bear conformity assessment costs. Channel control through certified system integrator networks protects installed base relationships in German and Japanese critical infrastructure accounts. For New Entrants and Emerging Players: Building automation integrators present the most accessible partnership pathway for cloud-native security software vendors seeking physical-cyber convergence traction. India's Smart Cities Mission and port modernization programs offer white-space procurement channels with less incumbent saturation than United States federal contracting. Behavioral biometrics specialization in keystroke dynamics and gait analysis bypasses fingerprint and facial recognition patent thickets held by established players. For Investors and Strategic Acquirers: Diversified industrial conglomerates with building automation footprints are the most active acquirer in this space, seeking security software capabilities to anchor integrated facility management platforms. Targets with EU AI Act pre-certified biometric platforms and cleared personnel staffing for government buyers command premium positioning. Monitor FDA cybersecurity guidance enforcement intensity for connected medical devices as inflection indicator for healthcare security services demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Conformity assessment completion compresses sales cycles for transportation hub and utility procurement in France and Germany. |
| Backward Integration into Edge Computing | In-house sensor processing chip design reduces latency dependency on concentrated East Asian foundry supply. |
| Building Automation Convergence | HVAC and lighting control bundling with access management creates facility management provider stickiness in North American commercial real estate. |
| Behavioral Biometrics Specialization | Keystroke dynamics and gait analysis scale rapidly in Tokyo and Osaka financial services corridors where users reject physical contact enrollment. |
| India National Infrastructure Program Participation | Smart city and port digitization deployments under central government programs open procurement channels for integrated surveillance vendors. |
Research Approach
Direct dialogue with security operations center directors, critical infrastructure protection officers, biometric system procurement leads, and building automation integrators grounded qualitative findings in operational reality. Secondary validation drew from FDA cybersecurity guidance documents, EU AI Act implementing acts, FERC reliability standards filings, and hyperscaler cloud security capex disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity estimates for security spending across utility, healthcare, and financial verticals.
Bottom-up demand modeling tracked solution type, end user category, technology tier, and service type across the projection horizon, with geographic clustering around United States federal contracting corridors, German industrial security procurement zones, and Japanese financial services authentication deployments. CAGRs were derived from elasticity-adjusted replacement cycles for legacy perimeter systems and penetration curves for zero-trust architecture adoption. Industry-specific inputs incorporated EU AI Act compliance timeline assumptions and semiconductor supply lead time volatility scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement intensity shifts and critical infrastructure protection budget allocation changes across FERC and Department of Homeland Security programs. Forecasts reflect documented assumptions regarding biometric accuracy threshold evolution and cloud workload migration pace. Material deviation in FDA cybersecurity guidance finalization or GDPR data residency mandate expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Body Armor Plates Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
North America Physical Security Market
Physical Security
Security Guard Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Europe Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Global Wearable Security Device Market
Physical Security
Physical Security Services Market
Physical Security
Border Security Technologies Market
Physical Security
Physical Security Equipment Market
Physical Security
Europe Cargo Inspection Market