
 Heat Shrink Sleeve Market | 2026-2036
Heat Shrink Sleeve Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Sleeve Market Analytics
Utility and renewable energy contractors are reorganizing procurement priorities around flame-retardant cable management, pulling volume away from traditional consumer-goods labeling. Berry Global leverages backward integration into resin compounding to secure polyolefin supply chains. Avery Dennison Corporation anchors North American demand through specialized electrical insulation grades. Huhtamaki Oyj competes in European pharmaceutical sleeving with cleanroom-certified production lines.
Heat shrink sleeve denotes a thermoplastic tube that contracts radially when heated, typically manufactured through extrusion and cross-linking of polyolefin, PVC, or polyethylene to achieve shrink ratios between 2:1 and 4:1, serving primarily to insulate, seal, and mechanically protect substrates. Polyolefin formulations dominate the product type landscape due to superior dielectric strength and chemical resistance, while composite variants capture premium margins in aerospace and defense applications. The end-user dimension shows automotive and electronics segments outpacing food and beverage, driven by high-voltage architecture proliferation and miniaturized component protection needs.
REACH restrictions on halogenated additives and RoHS substance limits are compelling European compounders to reformulate PVC and polyethylene grades, while FDA compliance requirements govern pharmaceutical sleeving contact surfaces in the United States. China's GB standards and MIIT directives on flame propagation in building wire are tightening product certification thresholds for both domestic and imported material. Stakeholders must weigh regional regulatory divergence against the capital cost of multi-certification production lines when allocating capacity expansion budgets.
Market Dynamics
Automotive electrification is compressing wire harness protection specifications, forcing sleeve manufacturers to reformulate polyolefin grades for 800-volt architectures while simultaneously satisfying REACH halogen restrictions and RoHS substance limits across multiple certification regimes.
Growth Catalysts
- EV High-Voltage Wiring:Electric vehicle platforms require flame-retardant sleeving for battery interconnects and motor windings, pulling volume from conventional automotive applications into specialized electrical insulation grades.
- REACH Compliance Deadlines:ECHA restrictions on halogenated flame retardants are compelling European compounders to certify halogen-free polyolefin formulations, creating first-mover certification premiums for compliant producers.
- China Infrastructure Buildout:MIIT directives on flame propagation in building wire and GB standards tightening are absorbing significant polyolefin sleeve volume through state-grid procurement and domestic appliance manufacturing clusters.
Market Restraints
- Resin Supply Concentration:Polyolefin feedstock availability concentrates among petrochemical complexes in the US Gulf Coast and Middle East, exposing converters to ethylene price volatility and force majeure disruptions.
- Cross-Linking Equipment Scarcity:Electron-beam irradiation capacity for achieving controlled shrink ratios remains limited to specialized facilities, capping expansion speed for mid-tier sleeve producers.
- Silicone Elastomer Substitution:High-temperature aerospace and defense applications increasingly specify silicone rubber tubing for extreme thermal cycling, displacing polyolefin in premium-margin segments.
Strategic Opportunities
- India Transmission Modernization:CEA mandates for fire-resistant cable management in urban distribution networks and renewable energy parks create import-substitution openings for localized sleeve production.
- Pharmaceutical Cleanroom Sleeving:FDA compliance requirements for contact surfaces and aseptic processing are expanding demand for certified cleanroom production lines in pharmaceutical packaging applications.
- Dual-Carbon Policy Alignment:China's MEE carbon intensity targets and SAMR green procurement guidelines favor low-emission manufacturing processes, rewarding converters with renewable energy-powered extrusion operations.
Industry Challenges
- Irradiation Technician Shortage:Qualified operators for electron-beam cross-linking systems are scarce, extending commissioning timelines for new production lines and elevating labor costs.
- Multi-Certification Overlap:Simultaneous pursuit of UL, VDE, and CCC approvals for global automotive contracts strains quality assurance resources and extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Sleeve Market |
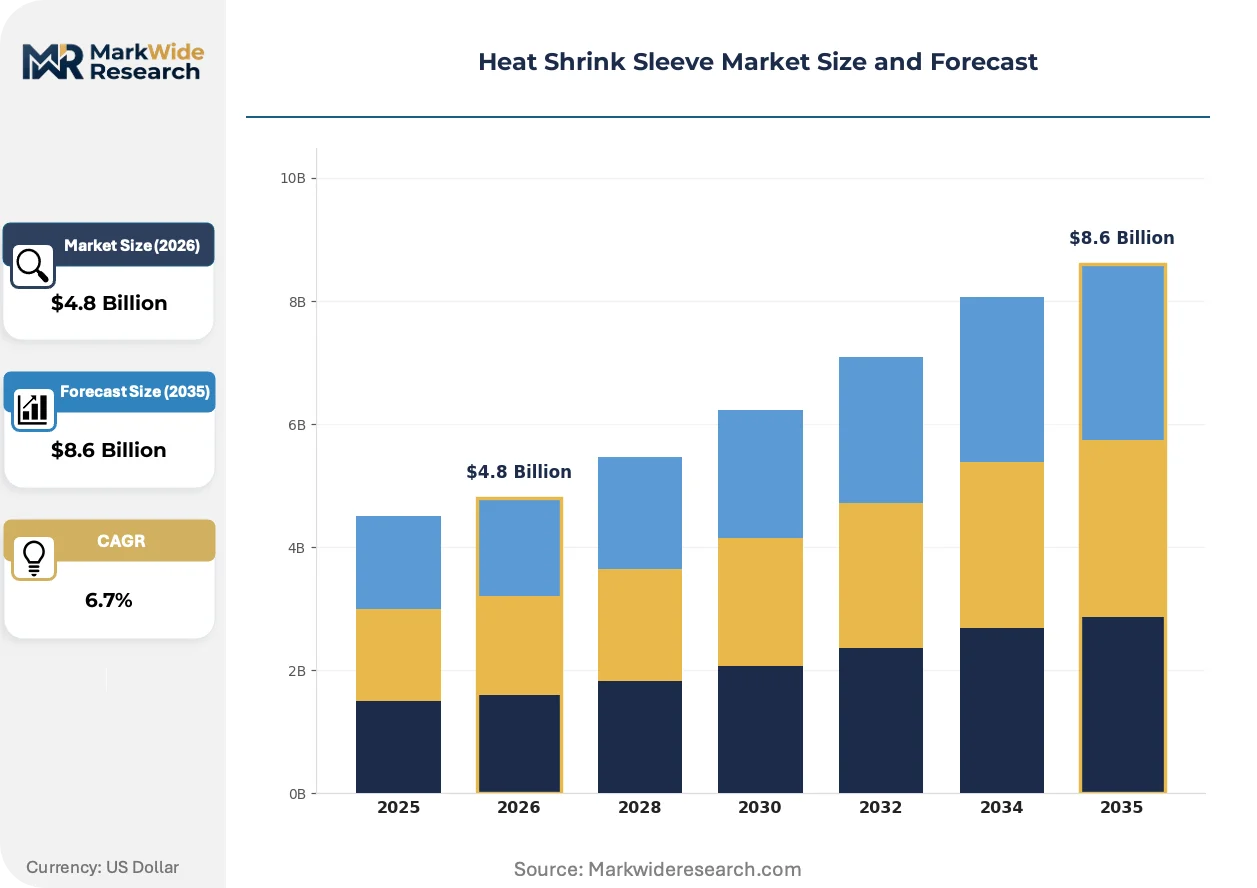
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, Polyethylene, Composite End User: Food & Beverage, Pharmaceuticals, Electronics, Automotive Application: Labeling, Wrapping, Insulation, Protection Thickness: Thin, Medium, Thick, Custom |
| Companies Covered | Berry Global, Fuji Seal International, CCL Industries, Avery Dennison Corporation, Huhtamaki Oyj, Multi-Color Corporation, Klöckner Pentaplast, Amcor Plc, Westrock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Sleeve Market Evolving Landscape
Material science advances and regulatory compression are converging to redefine performance benchmarks, with sleeve specifications now integrating thermal management, environmental compliance, and traceability into unified product platforms.
Dual-wall adhesive-lined polyolefin tubing is miniaturizing for microelectronics protection, with 1.6mm recovered diameter variants now standard for smartphone flex-circuit shielding. Medical device OEMs in South Korea and Taiwan are adopting these formats for catheter strain relief. The technology is miniaturizing component footprints while maintaining dielectric integrity, compressing design cycles for wearables and hearing aids.
RoHS substance limits and REACH SVHC candidate list expansions are forcing systematic reformulation of PVC and polyethylene grades across European supply chains. Compounders are substituting phosphorus-nitrogen synergists for traditional brominated retardants. Automotive wire harness suppliers in Germany and Czechia face the steepest recertification burdens, with 2026 compliance deadlines accelerating qualification timelines.
Utility procurement departments are consolidating cable management specifications under outcome-based performance contracts rather than material-centric purchasing. Contractors in Texas and California now specify flame-retardant sleeving by system-level burn-test results. This behavioral shift concentrates volume with integrated solution providers capable of warranting full harness protection rather than component-only suppliers.
Heat Shrink Sleeve Market Segmentation
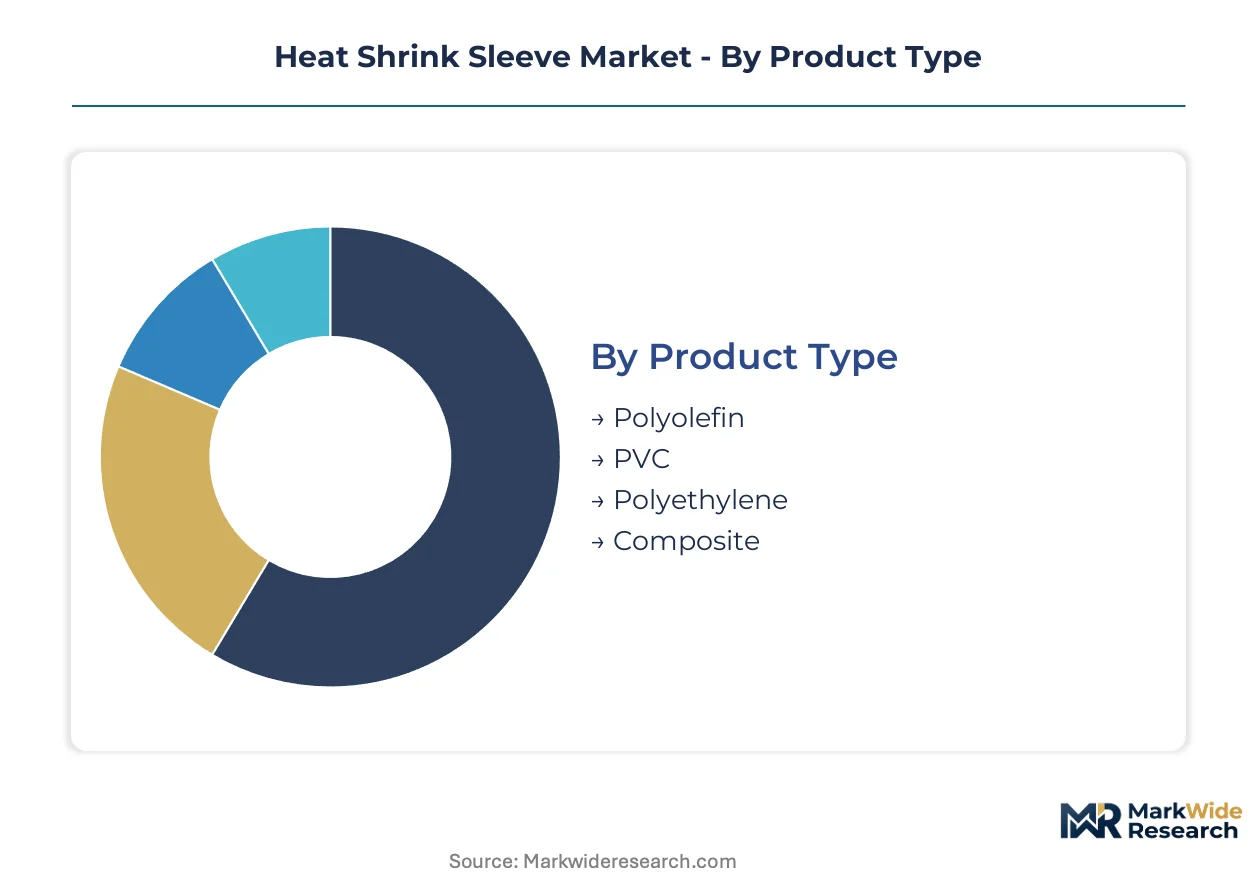
Heat shrink sleeve specifications fragment across voltage ratings, chemical exposure profiles, and regulatory certification tiers. Procurement teams in automotive and electronics sectors prioritize dielectric performance and flame-retardant compliance over cost minimization, compressing mid-tier commodity supply.
Product Type:
Silicone elastomer tubing is displacing traditional thermoplastics in aerospace thermal cycling applications, forcing polyolefin compounders to defend automotive and electronics strongholds through halogen-free reformulation.
- Polyolefin:Cross-linked polyolefin formulations deliver superior dielectric strength and chemical resistance across shrink ratios from 2:1 to 4:1. Automotive wire harness suppliers in Germany and the Czech Republic specify these grades for 800-volt EV architectures under REACH halogen restrictions.
- PVC:Flexible PVC sleeves retain cost advantage in consumer appliance labeling and low-voltage building wire. ECHA restrictions on phthalate plasticizers and brominated flame retardants are compelling European compounders toward reformulated grades with phosphorus-nitrogen synergists.
- Polyethylene:Medium-density polyethylene offers moisture barrier properties for underground utility cable protection. State-grid procurement in China absorbs significant volume through MIIT-compliant flame propagation standards.
- Composite:Multi-layer constructions with adhesive liners and metallic shielding capture premium margins in defense and satellite applications. These formulations resist extreme thermal cycling where silicone substitution pressure remains weakest.
Polyolefin anchors the volume base while composite formulations gain share at the steepest rate.
End User:
Customer procurement maturity varies sharply, with automotive and electronics buyers enforcing multi-certification requirements while food and beverage purchasers prioritize unit cost.
- Automotive:EV platform proliferation compresses wire harness protection specifications toward thinner walls and higher voltage tolerance. Battery interconnect and motor winding applications specify flame-retardant sleeving certified to UL, VDE, and CCC regimes simultaneously.
- Electronics:Miniaturized flex-circuit protection in smartphones and wearables drives demand for 1.6mm recovered diameter dual-wall tubing. Medical device OEMs in South Korea and Taiwan adopt these formats for catheter strain relief.
- Pharmaceuticals:Cleanroom-certified production lines supply aseptic processing applications with FDA-compliant contact surfaces. FDA validation requirements extend qualification timelines but secure multi-year supply contracts.
- Food & Beverage:Basic labeling and packaging applications specify commodity-grade PVC and polyethylene. Price sensitivity concentrates volume with integrated converters possessing captive resin compounding.
Automotive commands the certification burden while electronics expands most quickly through component miniaturization.
Application:
Utility procurement departments are consolidating specifications under system-level burn-test outcomes rather than material-centric purchasing, elevating insulation and protection over labeling.
- Insulation:High-voltage electrical insulation grades serve EV battery packs, renewable energy inverters, and grid-scale storage. Dielectric strength specifications now integrate thermal management and traceability into unified product platforms.
- Protection:Mechanical abrasion resistance and chemical sealing dominate wire harness and cable bundle applications. Contractors in Texas and California specify flame-retardant sleeving by full harness burn-test results rather than component-only ratings.
- Wrapping:General-purpose cable bundling in construction and industrial maintenance specifies medium-thickness polyolefin. Cost pressure from Asian imports compresses margins in this commoditized tier.
- Labeling:Consumer goods and logistics applications require printable sleeve surfaces for barcode and identification compliance. Digital printing compatibility now differentiates premium grades from commodity supply.
Protection captures the steepest margin expansion while labeling faces substitution from direct-print cable technologies.
Thickness:
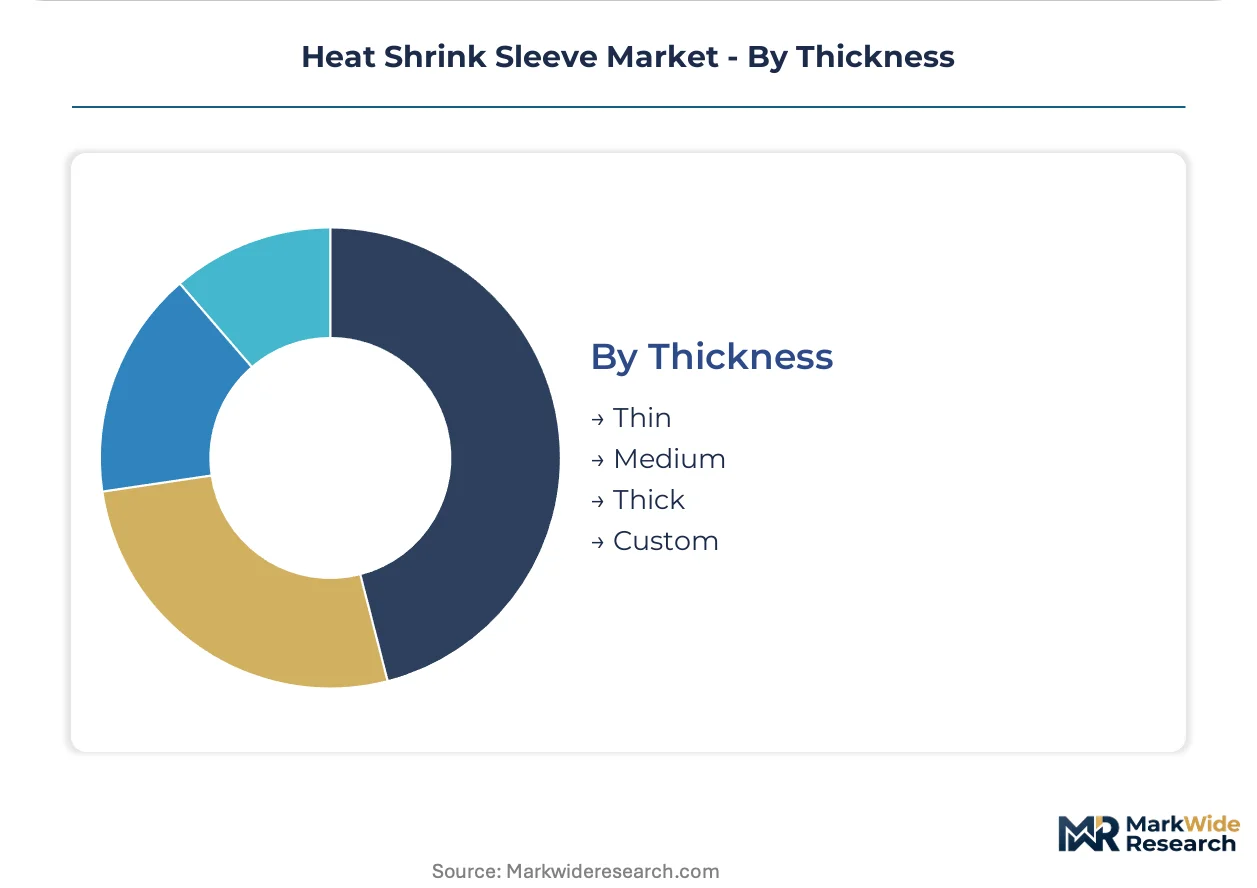
Wall thickness selection correlates directly with voltage rating and mechanical abuse exposure, creating natural tiering between infrastructure and consumer applications.
- Thin:Sub-millimeter walls serve microelectronics and medical device applications where space constraints dominate. Recovered diameters below 2mm enable smartphone flex-circuit shielding and hearing aid component protection.
- Medium:General industrial and automotive wire harness applications specify balanced mechanical and electrical properties. This tier absorbs the highest absolute volume across polyolefin formulations.
- Thick:Heavy-wall constructions protect mining, marine, and military cables from abrasion and hydrostatic pressure. Extended shrink ratios accommodate irregular substrate geometries.
- Custom:Project-specific extrusions serve aerospace and defense programs with non-standard shrink ratios and color coding. Low volume and high certification overhead sustain premium pricing.
Medium thickness dominates unit volume while thin-wall formats climb fastest through electronics miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export halogen-free polyolefin formulations to Czech and Hungarian automotive wire harness plants serving pan-European EV assembly. This trade corridor illustrates how regulatory compression in one jurisdiction reshapes procurement geography across supplier networks.
China
MIIT flame propagation standards and GB certification tightening absorb domestic polyolefin sleeve volume through state-grid procurement and appliance manufacturing clusters. The Yangtze River Delta hosts extrusion operations supplying infrastructure cable contractors with MIIT-compliant material.
Germany
ECHA REACH deadlines on halogenated additives compel compounders toward phosphorus-nitrogen synergist formulations for 800-volt EV architectures. Automotive wire harness suppliers in Bavaria and Baden-Württemberg face recertification burdens accelerating qualification timelines.
United States
Texas and California utility contractors specify flame-retardant sleeving by system-level burn-test outcomes rather than component ratings. FDA validation requirements govern pharmaceutical sleeving contact surfaces for domestic medical device OEMs.
India
CEA mandates for fire-resistant cable management in urban distribution networks create import-substitution openings for localized production. Maharashtra and Gujarat industrial corridors attract extrusion capacity targeting renewable energy park procurement.
South Korea
Medical device OEMs in Seoul and Suwon adopt miniaturized dual-wall tubing for catheter strain relief applications. MFDS compliance requirements extend qualification timelines but secure multi-year supply contracts for cleanroom-certified producers.
Heat Shrink Sleeve Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and resin supply security. The vendor base stratifies into three tiers: integrated compounders with captive resin operations, specialized sleeve converters with irradiation capacity, and commodity label printers without cross-linking capabilities. Dominant competitive moves include backward integration into resin compounding and multi-certification pursuit for automotive contracts spanning UL, VDE, and CCC regimes.
Within the integrated compounder tier, Berry Global and Avery Dennison Corporation exemplify scale-driven positioning through upstream control over polyolefin supply chains. Huhtamaki Oyj occupies a specialist position in European pharmaceutical sleeving where cleanroom certification creates defensive moats. Fuji Seal International represents the Asia-Pacific fabrication archetype, leveraging proximity to China infrastructure buildout and South Korean medical device clusters.
| Leading Market Players |
|---|
| Berry Global |
| Fuji Seal International |
| CCL Industries |
| Avery Dennison Corporation |
| Huhtamaki Oyj |
| Multi-Color Corporation |
| Klöckner Pentaplast |
| Amcor Plc |
| Westrock Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day resin order lead times concentrate pricing power with Gulf Coast and Middle Eastern petrochemical complexes, while converters without captive compounding operations absorb ethylene price volatility through compressed margins. This inventory-to-supply coupling forces sleeve manufacturers to choose between long-term offtake commitments and spot-market exposure.
Pricing Analysis
Next-generation halogen-free polyolefin formulations command certification premiums over legacy PVC and standard polyethylene grades. Three-tier pricing structure across premium, standard, and economy levels separates UL-VDE-CCC triple-certified automotive grades from single-certification industrial sleeves and commodity labeling stock. Pricing pressure stems from Asian import competition in medium-thickness construction applications. Food and beverage purchasers exhibit highest price sensitivity, while automotive wire harness buyers prioritize dielectric performance over unit cost.
Supply Chain Analysis
The United States and Saudi Arabia anchor polyolefin resin production, with South Korea and Taiwan hosting specialized electron-beam irradiation capacity for cross-linked tubing. Sleeve manufacturing draws from ethylene feedstock, additive masterbatches, and irradiation services as critical inputs. Single-source vulnerability concentrates in electron-beam facility access, where qualified technician scarcity extends commissioning timelines. Distribution runs through direct OEM supply contracts for automotive and electronics tiers, with industrial distributors serving maintenance and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
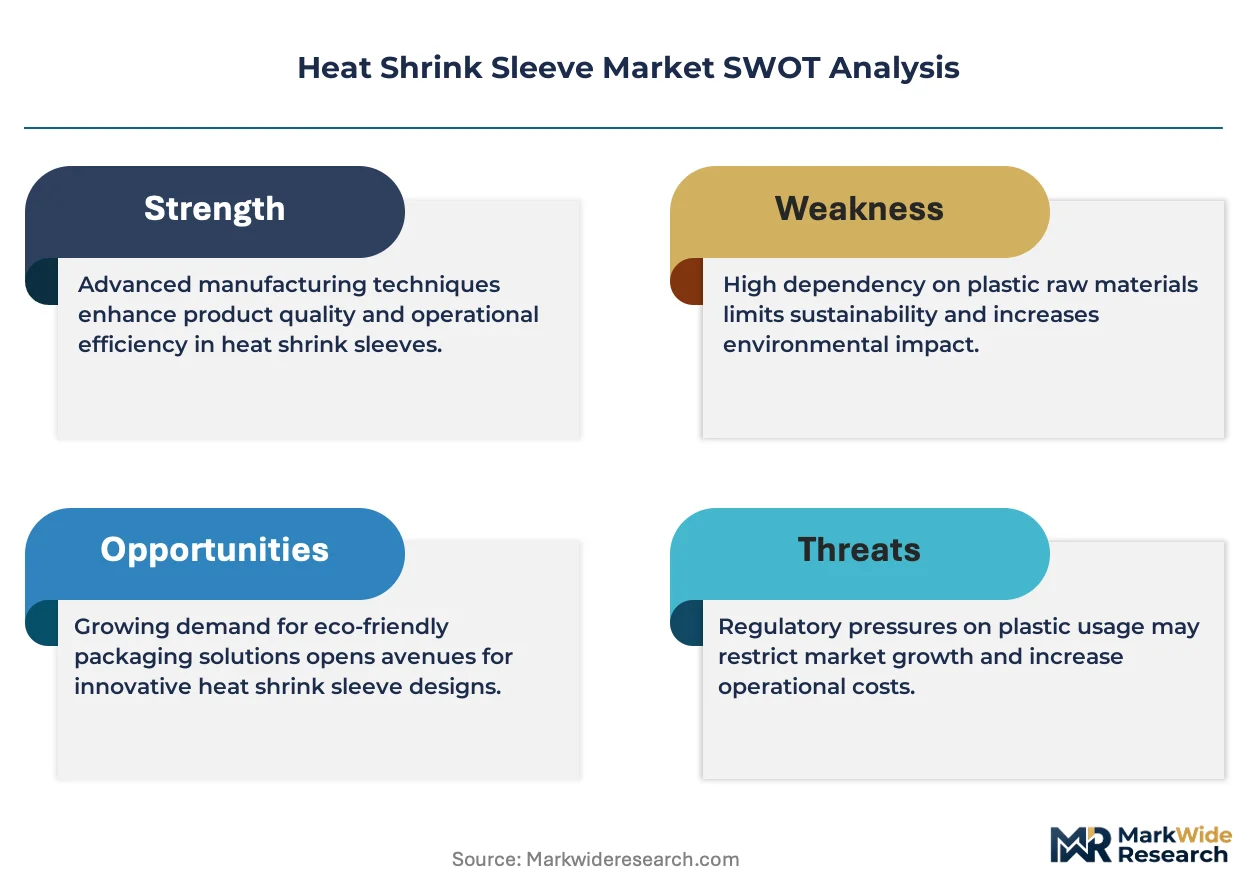
This market functions as a regulatory-entrenchment defensive moat. Multi-certification requirements and irradiation equipment scarcity create switching costs that protect qualified incumbents from commodity substitution.
For Market Incumbents: Fortify position through backward integration into halogen-free resin compounding and captive electron-beam capacity expansion in Czechia or Hungary. Silicone elastomer substitution in aerospace represents the most credible technology threat. Certification investment in India's CEA-compliant grades offers geographic diversification against European REACH compression.
For New Entrants and Emerging Players: Lead with cleanroom-certified pharmaceutical sleeving for South Korean and Taiwanese medical device OEMs, where FDA and MFDS validation requirements extend qualification timelines but secure multi-year supply contracts. India's transmission modernization under CEA mandates presents the most penetrable geography. Pursue joint development agreements with renewable energy EPC contractors rather than component-only supply.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because irradiation technician scarcity and multi-certification overhead favor scaled specialists over fragmented converters. Target acquisition archetype: mid-tier European compounders with REACH-compliant formulations and underutilized electron-beam capacity. The signal to watch is MIIT procurement volume shifts in China's state-grid cable buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyolefin supply secures margin control against Gulf Coast ethylene volatility. |
| Multi-Certification Investment | Simultaneous UL-VDE-CCC approval unlocks pan-European EV platform supply contracts. |
| Cleanroom Production Line Expansion | FDA-validated capacity captures pharmaceutical sleeving premiums in South Korean medical device clusters. |
| Electron-Beam Irradiation Capacity Addition | Specialized cross-linking capability defends against silicone substitution in high-temperature applications. |
| Geographic Manufacturing Footprint in India | Localized extrusion near Maharashtra and Gujarat industrial corridors serves CEA-mandated renewable energy procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed compounders, ECHA REACH substance registrations, and MIIT directive documentation. Conversations with automotive wire harness procurement leads, electron-beam facility operators, pharmaceutical cleanroom quality managers, and utility cable contractors informed demand-side validation. Bottom-up sleeve volume estimates triangulated against top-down polyolefin resin consumption patterns.
Segmentation dimensions modeled include material formulation grade, end-use industry vertical, wall thickness tier, shrink ratio specification, and regional regulatory cluster across the analysis window. CAGRs derived from elasticity-adjusted demand projections for EV platform proliferation, infrastructure cable buildout, and medical device miniaturization. Forecast inputs incorporated REACH SVHC candidate list expansion timelines and China's dual-carbon policy implementation intensity.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital deployment or abrupt REACH substance bans would require recalibration. Forecasts reflect assumptions on resin price stability and irradiation capacity expansion rates. Recalibration cycles align with material shifts in ECHA regulatory deadlines and MIIT procurement volume announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Sustainable Labels Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Global QR Code Labels Market
Labels
Inventory Tags Market
Labels
Booklet Labels Market
Labels
Global Security Labels Market
Labels
Shipping Label Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Water Dissolvable Labels Market
Labels
GHS Labels Market
Labels
Primary Packaging Labels Market
Labels
Self-Laminating Tags Market
Labels
Inspection and Inventory Labels Market
Labels
Wash Off Labels Market
Labels
Eco-Friendly Labels Market