
 Europe Unmanned Surface Vehicle (USV) Market | 2026-2036
Europe Unmanned Surface Vehicle (USV) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Unmanned Surface Vehicle (USV) Market Foresight
The EU AI Act is recalibrating the cost-of-entry calculus for autonomous maritime systems by imposing conformity requirements on machine-learning-based navigation decisions. Kongsberg Gruppen leverages decades of sonar integration heritage to dominate Norwegian naval procurement channels. ECA Group specializes in mine warfare USVs with proven operational deployment across French and Belgian fleets. ATLAS ELEKTRONIK GmbH anchors German defense export credibility through its SeaCat platform family.
An unmanned surface vehicle is a self-propelled craft operating on water without human occupants, typically measuring 2-16 meters in length and employing diesel-electric, battery, or solar propulsion to execute pre-programmed or dynamically adjusted missions. Its primary industrial purpose centers on performing hazardous, repetitive, or long-endurance maritime tasks—hydrographic surveying, pipeline inspection, mine detection—while eliminating crew risk and reducing operating cost. Autonomous vessels capture the largest addressable volume within product type segmentation, though electric USVs are gaining fastest traction as harbor authorities and research institutions face tightening emissions protocols. Within application segmentation, offshore infrastructure inspection commands premium pricing due to the specialized sensor payloads and certification requirements for subsea asset work.
CE marking under the EU Marine Equipment Directive shapes hardware eligibility for European-flagged vessels, while the F-Gas Regulation constrains refrigerant choices in sensor cooling systems aboard extended-endurance craft. ECHA's REACH framework governs composite hull materials and anti-fouling coatings, adding compliance layers for manufacturers sourcing across European supply chains. National regulators in France and Germany layer additional military certification standards for defense-destined platforms. Stakeholders must monitor how the EU Green Deal's tightening marine emission benchmarks redirect procurement specifications toward zero-emission propulsion architectures before competitor positioning solidifies.
Market Dynamics
Naval defense procurement across European littoral states is accelerating platform orders for mine countermeasures and maritime patrol missions. The EU Green Deal's tightening marine emission benchmarks are redirecting procurement specifications toward zero-emission propulsion architectures before competitor positioning solidifies.
Growth Catalysts
- EU Green Deal marine benchmarks:Harbor authorities in Norway and the Netherlands face binding emission reduction mandates that favor electric and solar-powered USV architectures over diesel alternatives.
- Mine countermeasure modernization:Belgian and French naval forces are retiring legacy minehunter fleets and specifying autonomous platforms for standoff ordnance disposal in contested littoral zones.
- Fjord-based testing infrastructure:Norway's concentrated autonomy engineering cluster provides validated proving grounds that compress development cycles for harsh-environment navigation algorithms.
Market Restraints
- Lithium-ion cell supply concentration:European USV manufacturers remain dependent on East Asian battery cell suppliers, exposing production schedules to geopolitical friction and raw material price volatility.
- EU AI Act conformity costs:Machine-learning-based navigation systems now require third-party assessment and CE marking under the EU AI Act, adding six-to-twelve month certification delays.
- Crewed vessel substitution economics:Harbor patrol and hydrographic survey missions in Southern European markets still favor small crewed craft due to lower upfront capital requirements and established maintenance networks.
Strategic Opportunities
- Polish and Baltic naval expansion:Estonia, Latvia, and Poland are drafting autonomous mine warfare requirements as part of NATO collective defense posture reinforcement in the eastern Baltic.
- Offshore wind farm inspection services:North Sea leaseholders face turbine foundation certification mandates that favor persistent USV presence over chartered crewed vessels for subsea cable and monopile assessment.
- Hybrid hydrogen-electric propulsion:Convergence of fuel cell stack efficiency gains with marinized battery management systems opens week-long endurance missions previously reserved for fossil-fuel platforms.
Industry Challenges
- Maritime autonomy software certification:National military certification authorities in France and Germany apply divergent safety integrity level standards, fragmenting development roadmaps for dual-use platforms.
- Sensor payload integration complexity:Subsea asset inspection contracts require simultaneous multibeam sonar, lidar, and optical sensor fusion that strains onboard power budgets and data processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Unmanned Surface Vehicle (USV) Market |
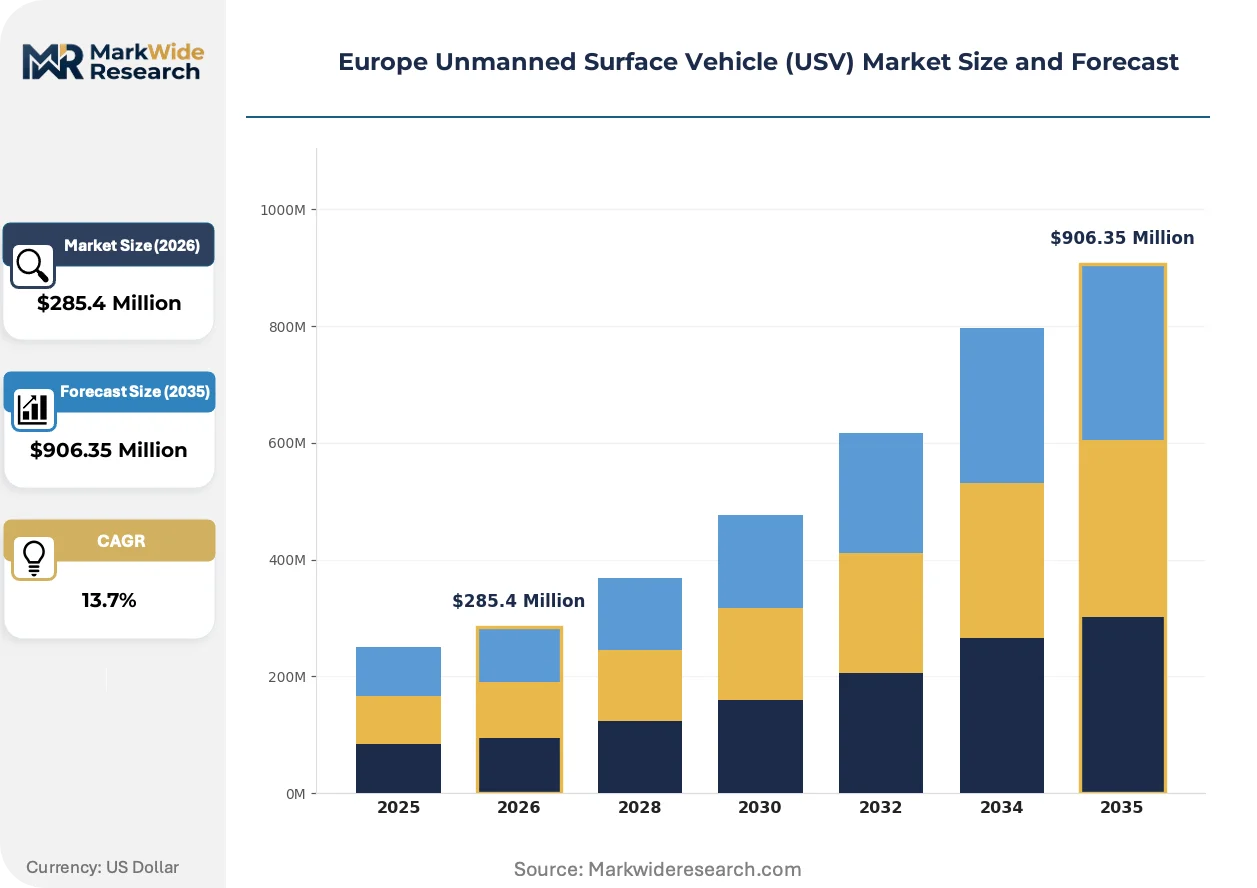
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Vessels, Remote-Controlled Boats, Hybrid USVs, Solar-Powered Craft, Electric USVs Technology: Radar Systems, Lidar Sensors, GPS Navigation, Acoustic Sensors, Machine Learning Algorithms Application: Maritime Surveillance, Environmental Monitoring, Hydrographic Surveying, Offshore Infrastructure Inspection, Security Enforcement End User: Coast Guard Agencies, Research Institutions, Energy Sector Operators, Defense Forces, Port Authorities |
| Companies Covered | Kongsberg Gruppen, L3Harris Technologies, Thales Group, ECA Group, ATLAS ELEKTRONIK GmbH, Saab AB, Fugro, Exail Technologies, Maritime Robotics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Unmanned Surface Vehicle (USV) Market Shifts & Advancements
Autonomous navigation architectures are converging with renewable propulsion systems to redefine operational endurance benchmarks. Platform developers are prioritizing sensor fusion capabilities that enable single-mission multi-objective execution.
Edge computing hardware is integrating directly into USV hull architectures to enable real-time machine-learning inference without satellite bandwidth dependency. Offshore wind leaseholders in the North Sea are adopting these platforms for continuous turbine foundation monitoring. This integration is compressing survey cycle times from quarterly crewed vessel charters to daily autonomous sorties.
The EU AI Act's risk-based classification system is mandating conformity assessment procedures for autonomous navigation decision engines. Hardware manufacturers must now document training data provenance and algorithmic transparency for platforms operating in European Economic Area waters. Defense-destined systems face additional national military certification layers that extend time-to-revenue by eight to fourteen months.
Harbor authorities are unbundling hydrographic survey contracts from integrated port service providers and awarding discrete autonomous platform charters to specialized survey firms. The Port of Rotterdam and Hamburg Port Authority have established separate tender categories for USV-based bathymetric data collection. This channel disintermediation is visible most acutely in Benelux and Northern German port complexes where emission monitoring requirements favor zero-crew operations.
Europe Unmanned Surface Vehicle (USV) Market Segmentation
USV procurement patterns diverge sharply between volume-driven harbor patrol contracts and premium-priced subsea inspection charters. Understanding these segment boundaries reveals where technology investments concentrate and which customer archetypes command platform customization.
Product Type:
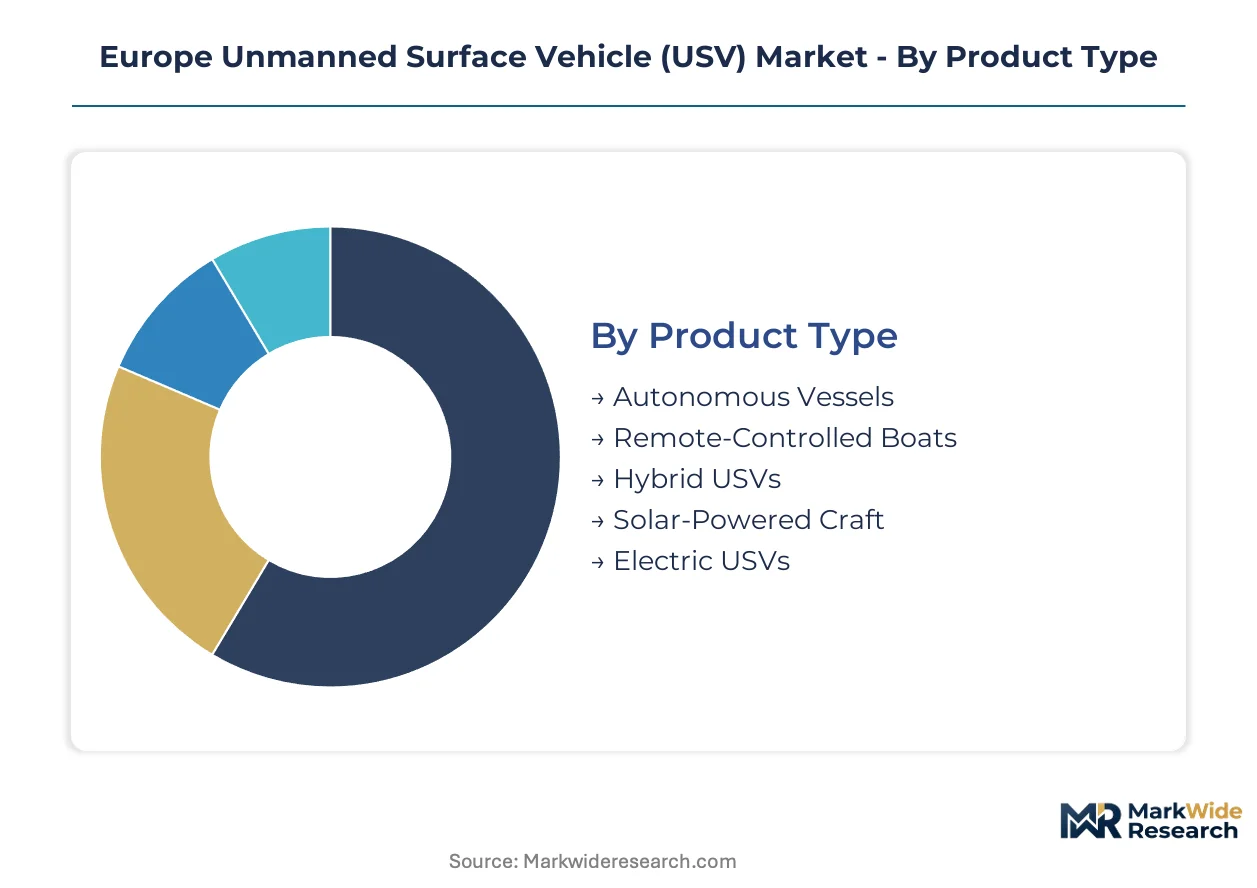
Autonomous vessels dominate contract volume while electric architectures capture the steepest expansion trajectory as emission mandates tighten across Norwegian and Dutch harbor authorities.
- Autonomous Vessels:Self-navigating platforms execute pre-programmed missions without real-time human intervention, typically spanning 4-16 meters with diesel-electric or battery propulsion. Norwegian fjord-based testing infrastructure validates these systems for NATO mine countermeasure tenders, compressing procurement qualification timelines.
- Electric USVs:Battery-dominant architectures eliminate onboard combustion, enabling zero-emission operation in EU Green Deal-regulated port zones. Rotterdam and Hamburg harbor authorities now specify electric propulsion in bathymetric survey tenders, displacing diesel alternatives.
- Remote-Controlled Boats:Operator-tethered platforms retain human-in-the-loop navigation for restricted maritime zones.
- Hybrid USVs:Dual-mode systems switch between autonomous and manual control for contested littoral operations.
- Solar-Powered Craft:Photovoltaic hull-integrated arrays extend endurance for persistent environmental monitoring missions.
Today's leader: Autonomous Vessels. Tomorrow's challenger: Electric USVs.
Technology:
Navigation and perception stacks differentiate platform pricing tiers, with sensor fusion complexity determining suitability for premium subsea inspection versus routine patrol applications.
- Machine Learning Algorithms:Neural network-based obstacle classification and path planning enable dynamic mission adaptation without satellite uplink dependency. Edge computing integration aboard North Sea wind farm inspection platforms compresses survey cycle times from quarterly crewed charters to daily autonomous sorties.
- Acoustic Sensors:Multibeam and side-scan sonar arrays deliver seabed imaging for pipeline and cable integrity assessment. Belgian and French naval procurement channels prioritize acoustic payload integration for standoff mine detection in contested waters.
- Radar Systems:X-band and S-band marine radar provide all-weather surface target detection for maritime surveillance missions.
- Lidar Sensors:Optical distance measurement enables high-precision shoreline mapping and structure proximity navigation.
- GPS Navigation:Satellite positioning with RTK correction supports hydrographic survey accuracy requirements.
Machine Learning Algorithms command premium platform pricing. Acoustic Sensors anchor naval procurement specifications.
Application:
Mission type dictates payload certification requirements and endurance specifications, with offshore energy contracts driving the most complex sensor integration demands.
- Offshore Infrastructure Inspection:Turbine foundation and subsea cable assessment requires simultaneous multibeam sonar, lidar, and optical sensor fusion that strains onboard power budgets. North Sea leaseholders face certification mandates favoring persistent USV presence over chartered crewed vessels.
- Hydrographic Surveying:Bathymetric data collection for port authorities and charting agencies emphasizes repeatable track-keeping and data quality assurance. Port of Rotterdam and Hamburg Port Authority tender categories now separate USV-based surveys from integrated port service contracts.
- Maritime Surveillance:Coastal patrol and illegal activity monitoring prioritize radar detection range and optical identification capabilities.
- Environmental Monitoring:Water quality sampling and marine ecosystem observation favor solar-extended endurance and minimal acoustic signature.
- Security Enforcement:Harbor perimeter protection and threat interdiction require rapid response speed and non-lethal deterrent integration.
Offshore Infrastructure Inspection carries the highest contract values. Hydrographic Surveying generates the most platform unit volume.
End User:
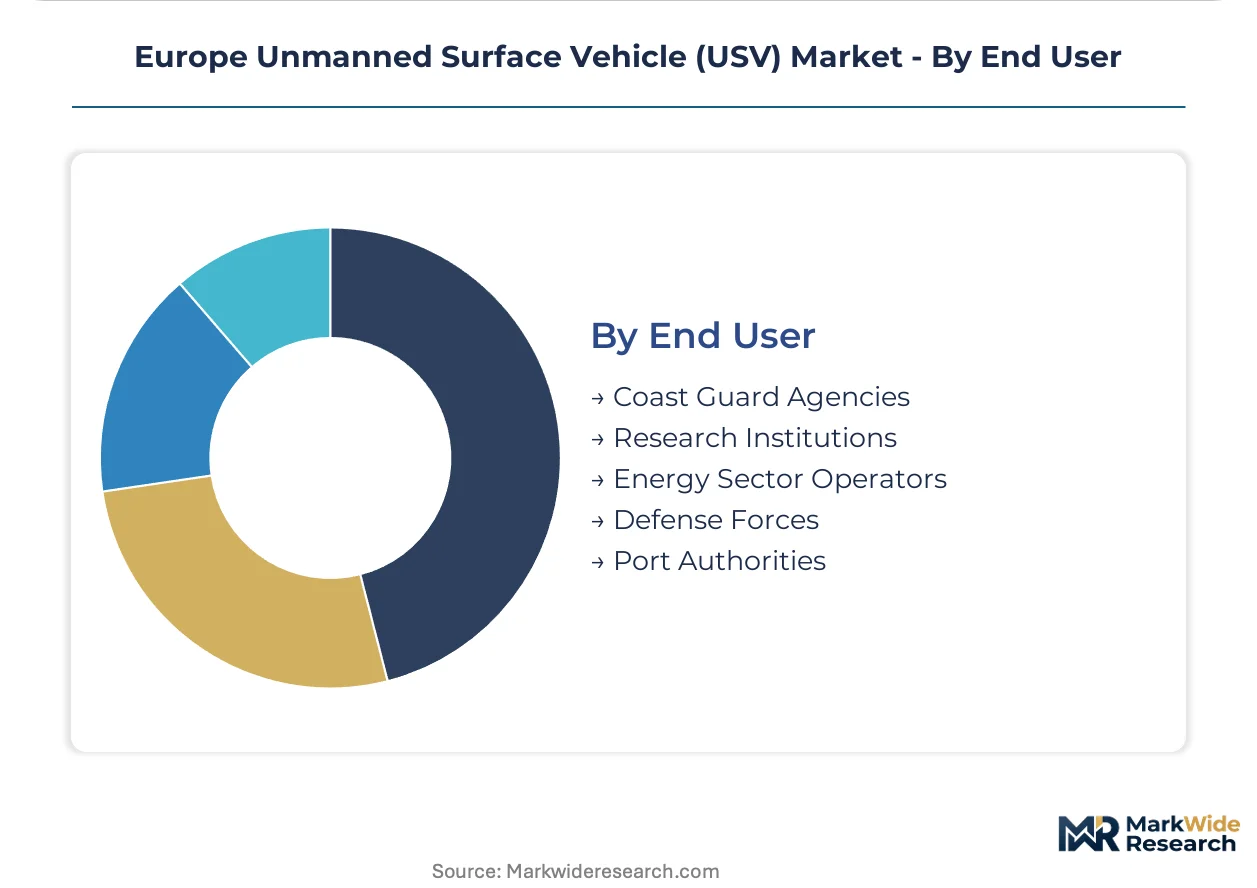
Defense and energy sector buyers drive platform specification complexity, while port authorities concentrate demand for standardized patrol configurations.
- Defense Forces:Naval procurement across European littoral states accelerates mine countermeasure and maritime patrol platform orders. French and German military certification authorities apply divergent safety integrity standards, fragmenting development roadmaps for dual-use platforms.
- Energy Sector Operators:Offshore wind leaseholders and subsea pipeline operators contract persistent inspection services rather than periodic crewed vessel charters. Subsea asset work demands specialized sensor payloads and certification requirements that inflate platform pricing.
- Coast Guard Agencies:Search and rescue and border patrol missions favor medium-endurance hybrid propulsion architectures.
- Port Authorities:Harbor patrol and bathymetric survey procurement concentrates in Benelux and Northern German complexes with binding emission monitoring requirements.
- Research Institutions:Oceanographic and climate science applications prioritize modular payload bays and open software architectures.
Defense Forces set the most demanding technical specifications. Energy Sector Operators offer the fastest contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian autonomy engineering talent anchors European USV development, with fjord-based testing infrastructure compressing algorithm validation cycles for harsh-environment navigation.
Norway
Naval mine countermeasure procurement and offshore energy inspection contracts drive platform demand around Kongsberg and Horten. The Norwegian Maritime Authority enforces strict autonomous vessel certification protocols under the Norwegian Maritime Code. Stavanger's subsea technology cluster hosts concentrated USV integration facilities serving North Sea oil and gas operators.
Germany
Defense export credibility and Baltic Sea maritime patrol requirements accelerate autonomous platform development in Kiel and Hamburg. ATLAS ELEKTRONIK GmbH operates under Bundesamt für Ausrüstung, Informationstechnik und Nutzung der Bundeswehr military certification standards. The Schleswig-Holstein littoral hosts dedicated test ranges for mine warfare USV validation.
France
Standoff ordnance disposal and naval fleet modernization programs sustain procurement momentum through Brest and Toulon. ECA Group navigates Direction Générale de l'Armement safety integrity requirements for defense-destined platforms. The Brittany maritime technology corridor concentrates sonar payload integration expertise for autonomous mine hunters.
United Kingdom
Offshore wind farm lease expansion and harbor authority emission mandates create dual demand channels in Aberdeen and Portsmouth. The Maritime and Coastguard Agency implements the UK Maritime Autonomy Regulation Lab framework for controlled testing environments. Scottish waters host persistent environmental monitoring trials for solar-extended endurance craft.
Netherlands
Rotterdam Port Authority bathymetric survey tenders and North Sea cable inspection contracts favor zero-crew electric architectures. Rijkswaterstaat enforces EU Green Deal marine emission benchmarks through harbor access regulations. The Delft maritime engineering cluster advances sensor fusion algorithms for multi-objective autonomous missions.
Europe Unmanned Surface Vehicle (USV) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across European naval procurement channels. The vendor base organizes around three strategic archetypes: defense-heritage systems integrators, subsea survey service providers, and autonomy software specialists. Consolidation pressure intensifies as harbor authorities unbundle integrated port service contracts and award discrete USV charters. Geographic expansion and technology licensing dominate competitive moves as manufacturers seek validated proving grounds and algorithm certification pathways.
Among defense-heritage systems integrators, Kongsberg Gruppen and ATLAS ELEKTRONIK GmbH occupy positions shaped by decades of sonar integration and military certification relationships. ECA Group exemplifies the mine warfare specialist archetype with proven operational deployment credentials. These three entities anchor the premium tier where national military procurement channels apply divergent safety integrity standards, fragmenting development roadmaps for dual-use platforms.
| Leading Market Players |
|---|
| Kongsberg Gruppen |
| L3Harris Technologies |
| Thales Group |
| ECA Group |
| ATLAS ELEKTRONIK GmbH |
| Saab AB |
| Fugro |
| Exail Technologies |
| Maritime Robotics |
| Others |
Supply & Pricing Matrix
Captive sonar payload manufacturing anchors both supply security and margin protection for established European systems integrators. Kongsberg Gruppen and ATLAS ELEKTRONIK GmbH maintain in-house multibeam array production, insulating platform pricing from sensor import volatility while commanding premium positioning in NATO procurement channels. This backward integration into acoustic hardware contrasts with smaller competitors sourcing lidar and optical components through distributor networks, compressing their pricing flexibility against emission-mandated electric propulsion cost premiums.
Pricing Analysis
Harbor authorities are unbundling hydrographic survey contracts from integrated port service providers, creating discrete charter categories that separate platform-only pricing from sensor-operator bundles. Rotterdam and Hamburg now specify electric USV architectures in standalone bathymetric tenders, with pricing stratifying across military-certified, commercial-grade, and research-tier configurations. Cost compression in commercial-grade segments runs through lithium-ion cell supply constraints and EU AI Act conformity assessment fees. Port authorities exhibit highest price sensitivity, while offshore wind leaseholders accept premium positioning for persistent inspection capabilities that displace quarterly crewed vessel charters.
Supply Chain Analysis
Domestic-content thresholds in French and German military procurement are reshaping component sourcing toward European-qualified suppliers. Battery cell supply concentrates in South Korea, China, and Japan, exposing production schedules to raw material price volatility and export licensing friction. Composite hull fabrication draws from Norwegian and German suppliers governed by ECHA REACH framework constraints on resin systems and anti-fouling coatings. Single-source vulnerability sits with solid-state lidar modules produced by limited qualified vendors. Distribution runs through defense systems integrators for naval contracts and direct manufacturer relationships for harbor authority procurements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe USV market compounds steadily as NATO collective defense posture reinforcement sustains mine countermeasure procurement across littoral states. Naval modernization programs provide predictable demand visibility that offsets commercial segment volatility.
For Market Incumbents: Acquire specialized autonomy software boutiques to compress EU AI Act certification timelines and neutralize emerging algorithm specialists threatening platform differentiation. Kongsberg Gruppen and ATLAS ELEKTRONIK GmbH should deepen backward integration into edge computing hardware to secure sensor fusion architectures against semiconductor supply friction. Military certification divergence between France and Germany fragments development roadmaps; incumbents must maintain dual-track qualification capacity to defend naval procurement channel access.
For New Entrants and Emerging Players: Begin with Polish and Baltic naval expansion programs where autonomous mine warfare requirements are newly drafted and incumbent relationships remain unsettled. Estonian, Latvian, and Polish defense procurement channels offer the most penetrable entry points for standoff ordnance disposal platforms. Target harbor patrol contracts in Southern European markets where crewed vessel substitution economics still favor small manned craft, positioning electric architectures against tightening EU Green Deal benchmarks as emission mandates harden.
For Investors and Strategic Acquirers: Consolidation pressure builds where harbor authorities unbundle integrated port service contracts and award discrete USV charters, fragmenting vendor relationships and creating rollup opportunities. Five-to-ten year viability favors platforms with validated NATO qualification credentials and fjord-proven harsh-environment navigation stacks. The signal to watch is Polish defense ministry tender releases for autonomous mine warfare systems, which would confirm eastern Baltic demand materialization and trigger portfolio reallocation toward Baltic-accessible integration facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Third-party assessment capability for machine-learning navigation engines accelerates CE marking timelines under Brussels risk-based classification. |
| Fjord Testing Infrastructure Expansion | Norwegian proving grounds validate harsh-environment algorithms for NATO mine countermeasure qualification requirements. |
| Hybrid Hydrogen-Electric Development | Fuel cell stack integration enables week-long endurance missions previously reserved for fossil-fuel platforms in North Sea wind farm inspection. |
| Sensor Fusion Architecture Patenting | Multibeam sonar, lidar, and optical integration protects subsea asset inspection margins against commodity platform competition. |
| Baltic Naval Partnership Programs | Estonian, Latvian, and Polish defense channels open autonomous mine warfare procurement outside established French-German-Norwegian vendor networks. |
Research Methodology
Bottom-up defense procurement and energy sector operator modeling reconciled against top-down autonomy platform production tracking forms the analytical core of this study. Primary interviews with naval program managers, harbor authority procurement officers, offshore wind leaseholder operations directors, and autonomy engineering leads informed demand segmentation and technology adoption timelines. Secondary validation drew from EU defense procurement databases, national military certification authority filings, port authority tender documentation, and North Sea offshore wind lease records. Cross-referencing manufacturer production disclosures against end-user contract awards verified volume assumptions.
Input-output matrices mapped propulsion architecture adoption, sensor payload integration complexity, and certification pathway duration across product type, technology, application, and end user dimensions. CAGRs were derived from segment-level demand buildups calibrated to announced naval modernization schedules and EU Green Deal implementation trajectories. Forecast inputs incorporated lithium-ion cell supply constraints, EU AI Act conformity timeline assumptions, and NATO collective defense posture reinforcement indicators without year-specific milestone anchoring.
Several conditions sit outside the modeled scope, including geopolitical disruption of East Asian battery supply chains, unilateral national military certification requirement changes, and breakthrough autonomous navigation algorithms that circumvent current conformity assessment frameworks. Forecasts reflect documented assumptions regarding procurement continuity and regulatory implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Lidar Drone Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Autonomous Technology Market