
 Hydration Belt Market | 2026-2036
Hydration Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Hydration Belt Market Intelligence
Moisture-wicking fabric integration and modular bottle-attachment systems are reshaping how hydration belts are engineered for endurance athletes. CamelBak leverages its reservoir heritage to anchor premium positioning in the technical trail-running segment. Nathan Sports competes through specialized belt geometries that minimize bounce during high-mileage events. Ultimate Direction dominates the ultramarathon niche with vest-compatible designs that extend carrying capacity beyond standard waist-worn formats.
A hydration belt is a waist-worn carrier system constructed from breathable synthetics, typically incorporating one to four BPA-free bottles, adjustable elastic straps, and zippered storage compartments for nutrition and electronics. These devices serve runners, hikers, and cyclists who require hands-free fluid access without the thermal burden or weight distribution issues of backpack-based hydration systems. Running belts occupy the largest revenue pool due to marathon participation rates, while fitness belts represent the fastest-expanding segment as gym-based interval training popularizes compact hydration solutions. Neoprene and nylon compositions command margin premiums over polyester alternatives because of superior sweat resistance and dimensional stability during repetitive motion.
The Consumer Product Safety Commission oversees chemical exposure limits in textile products sold in the United States, while California's Proposition 65 mandates disclosure of phthalates and flame retardants in synthetic materials. The EU's REACH regulation and OEKO-TEX Standard 100 certification constrain material sourcing for brands exporting into European markets, effectively filtering out suppliers lacking documented supply-chain transparency. Stakeholders must monitor evolving state-level chemical restrictions and third-party certification requirements as baseline conditions for market access rather than optional quality differentiators.
Market Dynamics
REACH chemical disclosure mandates and California Proposition 65 labeling requirements are forcing material sourcing overhauls across hydration belt supply chains. Manufacturers must now maintain documented compliance portfolios for every synthetic textile component, reshaping supplier qualification protocols and inventory management systems.
Growth Catalysts
- Trail running participation clusters:California and Colorado host the densest concentrations of ultra-running events in the United States, generating concentrated demand for technical waist-worn hydration systems. Event registration volumes in these states outpace national averages by substantial margins.
- REACH textile compliance:The EU's chemical safety framework elevates material transparency requirements, filtering out low-documentation suppliers and rewarding brands with verified supply-chain audit trails. This creates competitive separation between compliant and non-compliant manufacturers.
- Neoprene performance properties:Advanced synthetic compositions deliver superior sweat resistance and dimensional stability during repetitive motion, commanding margin premiums over polyester alternatives in marathon and ultra-running applications.
Market Restraints
- BPA-free bottle resin costs:Specialized food-grade polymers carry 15-25% price premiums over standard plastics, compressing margins at mid-tier price points and forcing trade-offs between material quality and retail accessibility.
- East Asian molding concentration:Injection molding capacity for ergonomic bottle geometries clusters in specific manufacturing zones, creating geographic supply risk and elongating lead times for design iterations.
- Backpack hydration substitution:Technical vests with integrated reservoirs displace waist-worn systems among ultramarathon participants seeking higher fluid capacity and weight distribution across the torso.
Strategic Opportunities
- Gym-based interval training expansion:Fitness belts represent the fastest-expanding segment as boutique studios and CrossFit affiliates popularize compact hydration solutions for high-intensity workouts. This channel remains underpenetrated by established running-focused brands.
- Modular attachment convergence:Magnetic and clip-based bottle docking systems are converging with smartphone stabilization technologies, enabling cross-licensing opportunities with mobile accessory manufacturers.
- EU Green Deal textile incentives:Circular economy funding streams and recycled content mandates create procurement advantages for brands sourcing post-consumer nylon and ocean-recovered polymers.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Third-party textile safety verification requires 8-14 week laboratory testing cycles, delaying seasonal product launches and complicating just-in-time manufacturing models.
- Multi-jurisdiction label compliance:Simultaneous adherence to California Proposition 65, EU REACH, and emerging state-level chemical restrictions demands specialized regulatory affairs personnel that smaller manufacturers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydration Belt Market |
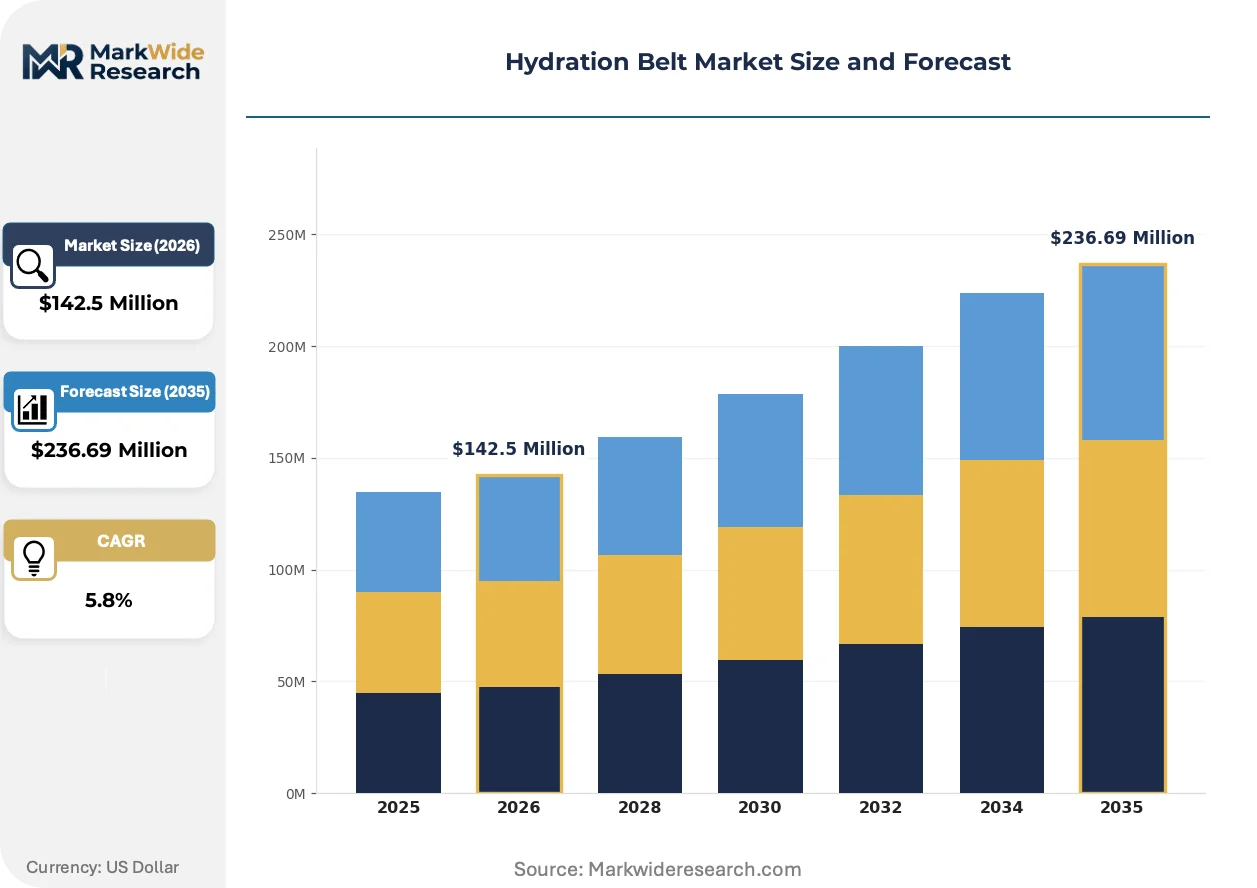
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Belts, Fitness Belts, Travel Belts, Cycling Belts Material: Neoprene, Polyester, Nylon, Silicone End User: Athletes, Hikers, Commuters, Travelers Distribution Channel: Online Retail, Sporting Goods Stores, Supermarkets, Specialty Shops |
| Companies Covered | Nathan Sports, Fitletic, URPOWER, Adalid Gear, CamelBak, Ultimate Direction, Salomon, Amphipod, Osprey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydration Belt Market Strategic Shifts & Innovations
Digital design workflows and predictive biomechanics modeling are compressing product development cycles for ergonomic belt geometries. These capabilities enable rapid iteration on bounce-minimization structures without extensive physical prototyping.
Computational fluid dynamics software is virtualizing the traditional mold-and-test approach to bottle shape optimization. Trail-running gear specialists adopt these simulation tools to refine hand-grip ergonomics and splash-resistant mouthpiece geometries. The technology is virtualizing months of physical sampling into weeks of digital refinement, collapsing time-to-market for seasonal collections.
California's Proposition 65 enforcement actions against phthalate-containing synthetic textiles have intensified disclosure obligations for brands selling into the state. Industrial consequence includes mandatory reformulation of elastic strap compounds and zippered pouch linings. Marathon-focused product lines face the highest compliance exposure due to California's outsized share of domestic event participation.
Direct-to-consumer subscription models for seasonal gear replacement are displacing traditional retail replenishment cycles. Endurance athletes in Colorado and Oregon demonstrate highest subscription adoption rates, receiving quarterly belt and bottle refreshes tied to training periodization. This channel shift concentrates customer lifetime value data with brands while reducing wholesale margin erosion.
Hydration Belt Market Segmentation
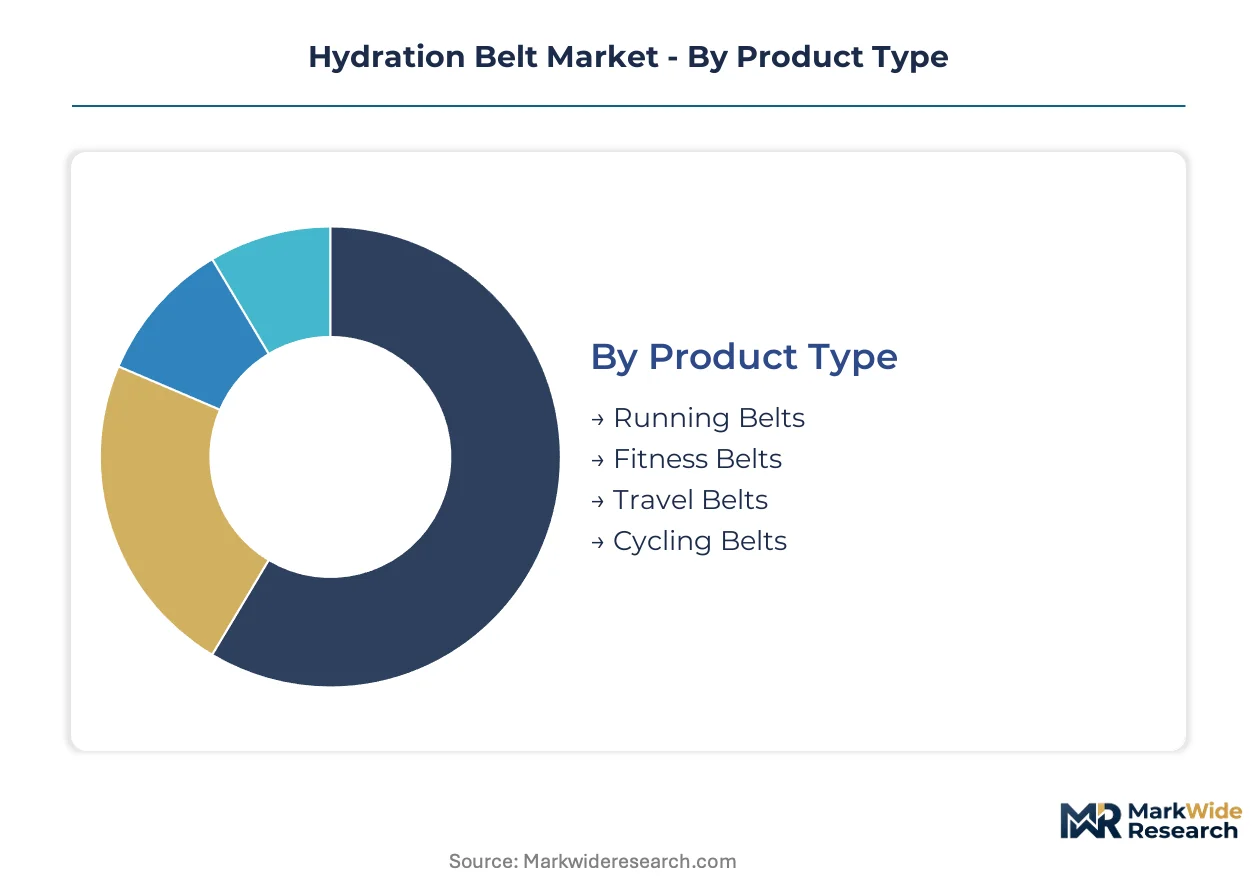
Hydration belt manufacturers engineer distinct product architectures for each use case, with after-sales service intensity varying sharply between technical athletic segments and casual travel applications. Replacement part availability and fit-adjustment support drive loyalty in high-mileage user cohorts.
Product Type:
After-sales service intensity peaks in technical athletic belts requiring periodic component replacement and fit recalibration, while travel-oriented designs demand minimal post-purchase support.
- Running Belts:Engineered with bounce-minimization geometries and moisture-wicking back panels for marathon and ultra-running distances. Demand concentrates in California and Colorado where trail running event density exceeds national averages, with users prioritizing chafe-resistant seams and modular bottle docking. Replacement strap and buckle programs sustain brand loyalty across training cycles.
- Fitness Belts:Compact waist-worn systems optimized for gym-based interval training and CrossFit workouts, featuring slim profiles that clear weightlifting equipment. Boutique studio adoption in urban markets accelerates volume expansion as interval training popularizes compact hydration solutions. Minimal adjustment needs reduce service touchpoints compared to technical running formats.
- Travel Belts:Security-focused designs with RFID-blocking pockets and hidden compartments for passport and currency storage. Leisure travelers in European markets drive procurement for anti-theft features during urban exploration.
- Cycling Belts:Aerodynamic low-profile constructions with side-mounted bottle access for road and gravel bike disciplines. Recreational cyclists in Pacific Northwest markets favor weather-resistant materials for variable climate conditions.
Running belts hold the largest share; momentum sits with fitness belts.
Material:
Cost tier stratification separates premium synthetic compositions from commodity alternatives, with performance properties commanding measurable price premiums across athletic applications.
- Neoprene:Closed-cell synthetic rubber delivering superior sweat resistance and dimensional stability during repetitive motion. Marathon and ultra-running applications in humid climates justify 20-30% price premiums over polyester alternatives. REACH compliance documentation requirements filter supplier pools to audited manufacturers with verified chemical disclosure portfolios.
- Nylon:High-tenacity polyamide fibers offering abrasion resistance and rapid drying characteristics for multi-hour events. Ultramarathon participants in mountainous terrain prioritize tear strength for technical trail conditions.
- Polyester:Cost-optimized synthetic with adequate moisture management for casual fitness and entry-level running applications. Price-sensitive gym users accept reduced durability for accessibility.
- Silicone:Elastomer compounds molded into grip strips and bottle retention rings for secure fluid access at speed. Cycling disciplines leverage vibration-damping properties for rough-surface stability.
Neoprene commands the highest unit economics; nylon gains share fastest among technical users.
End User:
Volume concentration varies dramatically across user types, with professional and dedicated amateur athletes driving replacement cycles at 2-3x the frequency of occasional recreational users.
- Athletes:Competitive runners, triathletes, and obstacle course racers requiring race-day performance optimization and training-log consistency. Seasonal event calendars in Texas and Florida sustain replacement demand through year-round competition schedules.
- Hikers:Day-hiking enthusiasts prioritizing weight distribution and hands-free navigation for trail systems in national park corridors. Colorado's fourteeners community generates concentrated demand for high-capacity configurations.
- Commuters:Urban cyclists and transit riders seeking discrete hydration access without backpack bulk. Metropolitan areas with bike-share infrastructure show elevated adoption.
- Travelers:International tourists and business travelers integrating hydration with security features for extended itineraries. Asia-Pacific origin-destination corridors drive seasonal procurement spikes.
Athletes generate the highest lifetime value per customer; commuters represent the steepest expansion trajectory.
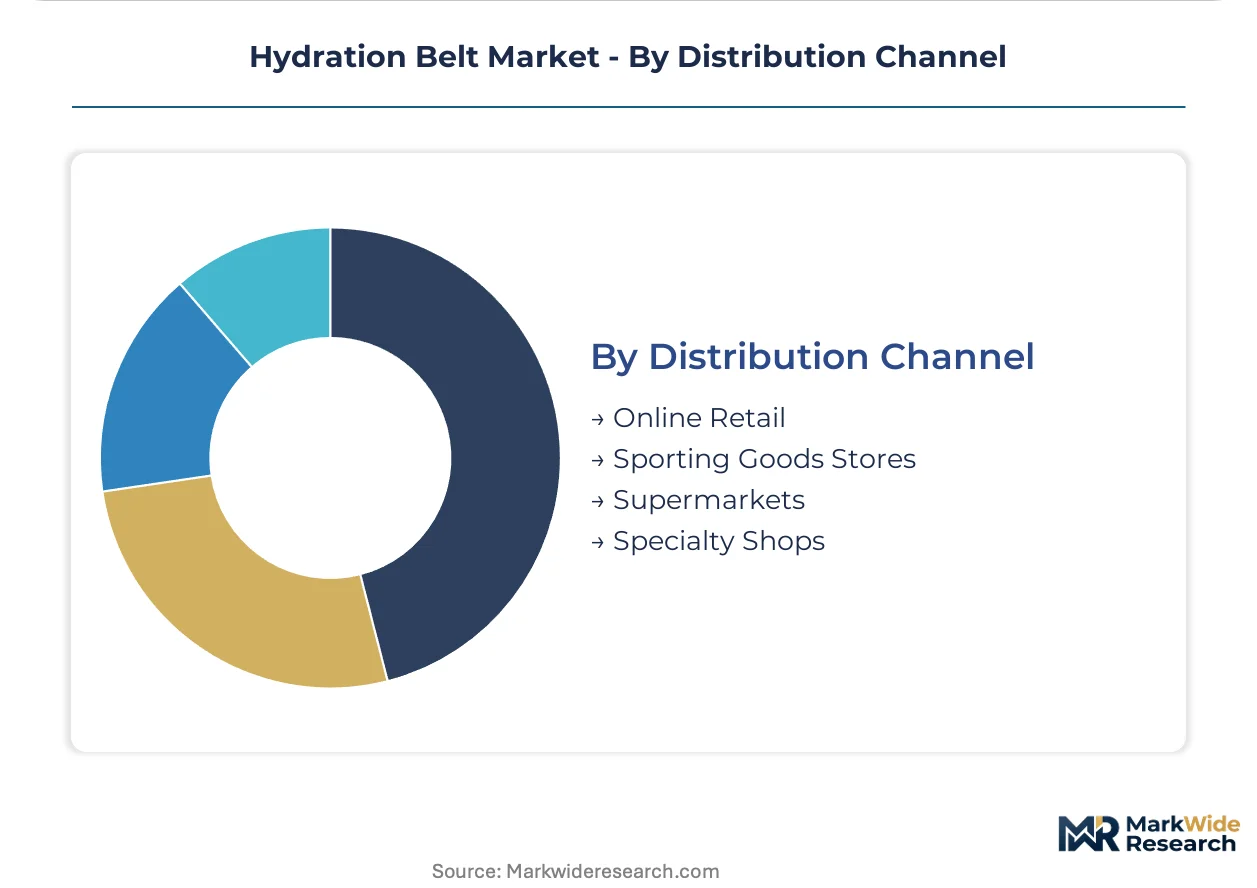
Distribution Channel:
Margin structure diverges sharply between direct digital relationships and wholesale sporting goods partnerships, with inventory risk allocation determining channel strategy.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling fit-guide tools and subscription replenishment models. Endurance athletes in Oregon and Colorado demonstrate highest subscription adoption rates for seasonal gear replacement.
- Sporting Goods Stores:Specialty retailers providing in-person fitting services and immediate product comparison for technical athletic purchases. Marathon expo partnerships concentrate volume around event calendars.
- Supermarkets:Mass-market placement for entry-level fitness belts and impulse travel accessories. Price-competitive positioning limits premium material penetration.
- Specialty Shops:Independent running and cycling boutiques offering curated assortments and community event sponsorship integration. Local trail system knowledge builds consultative selling credibility.
Online retail captures the fastest-growing transaction volume; sporting goods stores retain the highest average order value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export neoprene and nylon belt assemblies to specialty retailers across North America and Western Europe, with containerized freight routing through Los Angeles and Rotterdam absorbing 12-18% of landed costs.
United States
California and Colorado host the densest concentrations of ultra-running events nationwide, driving concentrated procurement of bounce-minimization belt geometries. The Consumer Product Safety Commission enforces chemical exposure limits in textile products, while California's Proposition 65 mandates phthalate disclosure in synthetic strap compounds. Boulder and Denver metropolitan areas anchor technical gear distribution networks serving Rocky Mountain trail systems.
Germany
Outdoor retail chains in Bavaria and Baden-Württemberg stock premium hydration systems for Alpine trail running and cycling disciplines. ECHA administers REACH compliance documentation for all imported synthetic textiles, filtering supplier pools to audited manufacturers with verified chemical portfolios. Munich's specialty sporting goods corridor concentrates buying power for technical endurance equipment.
United Kingdom
Marathon participation in London and Southeast England sustains replacement demand for moisture-wicking belt systems. The Office for Product Safety and Standards aligns with EU REACH transitional requirements for chemical disclosure in post-Brexit imports. The Peak District and Lake District trail networks generate seasonal procurement spikes among hiking-oriented user segments.
Australia
Trail running communities in New South Wales and Victoria prioritize sweat-resistant materials for humid climate conditions. The ACCC enforces mandatory safety standards for consumer goods including textile chemical content. Sydney and Melbourne specialty retailers anchor Pacific distribution for technical hydration equipment serving ultramarathon training circuits.
Japan
Metropolitan Tokyo and Osaka running clubs drive demand for compact, discrete belt profiles suited to urban training environments. METI oversees textile labeling requirements and chemical safety standards under the Household Goods Quality Labeling Act. The Hakone and Kyoto trail corridors concentrate technical gear adoption among dedicated amateur athlete cohorts.
Hydration Belt Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered price bands defined by material certification and biomechanical engineering intensity. Market structure consolidates around heritage outdoor brands with reservoir expertise and specialized running-equipment fabricators with event-sponsorship relationships. Three archetypes dominate: technical trail-running specialists, multi-sport outdoor conglomerates, and direct-to-consumer fitness-focused entrants. Competitive moves concentrate on strategic partnerships with marathon expos and portfolio diversification into modular attachment systems.
Among heritage reservoir specialists, CamelBak anchors premium positioning through technical trail-running heritage, while Nathan Sports exemplifies the specialized running-equipment archetype with event-sponsorship integration. Ultimate Direction occupies the ultramarathon niche through vest-compatible design extensions. These three companies represent distinct competitive vectors—reservoir heritage, running-specialist focus, and capacity-optimized formats—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Nathan Sports |
| Fitletic |
| URPOWER |
| Adalid Gear |
| CamelBak |
| Ultimate Direction |
| Salomon |
| Amphipod |
| Osprey |
| Others |
Cost & Logistics Intelligence
East Asian injection molding clusters for ergonomic bottle geometries concentrate capacity for food-grade BPA-free resins, anchoring margin pools with brands that have secured multi-year supplier commitments and documented REACH compliance portfolios. Premium neoprene compositions command 20-30% price premiums over polyester alternatives, with California Proposition 65 enforcement actions intensifying disclosure obligations that filter supplier pools to audited manufacturers.
Pricing Analysis
Current-generation modular magnetic docking systems price at substantial premiums over prior-generation clip-based attachments, while next-generation smartphone-stabilization convergence technologies command early-adopter positioning. Three-tier pricing structure across premium neoprene, standard nylon, and economy polyester levels stratifies the market, with certification grade under OEKO-TEX Standard 100 and volume scale driving price differentiation. Cost compression in mid-tier polyester belts is intensifying because of BPA-free resin premiums, with gym-based fitness users demonstrating highest price sensitivity and ultramarathon participants in California and Colorado showing lowest sensitivity to performance-grade pricing.
Supply Chain Analysis
Petrochemical feedstocks for synthetic textiles draw from Chinese, Vietnamese, and South Korean manufacturing bases, with neoprene and nylon yarn production resting on specialized polymer inputs and textile finishing chemicals. Raw material dependencies center on closed-cell synthetic rubber compounds, high-tenacity polyamide fibers, and food-grade bottle resins. Single-source vulnerability concentrates in East Asian molding zones for ergonomic bottle geometries, elongating design iteration lead times. Distribution runs through direct-to-consumer subscription platforms and specialty sporting goods retailers, with marathon expo partnerships concentrating volume around event calendars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical hydration vests with integrated reservoirs represent an accelerating substitution threat that waist-worn belt incumbents must navigate through capacity-optimized format innovation and vest-compatible design extensions.
For Market Incumbents: Entrench position through backward integration into neoprene compounding and captive supply of REACH-compliant textile finishing, defending against vest-format substitution by extending carrying capacity through modular attachment convergence. Prioritize certification investment in OEKO-TEX Standard 100 and California Proposition 65 disclosure protocols to filter competitor supplier pools. For New Entrants and Emerging Players: Gym-based interval training studios in metropolitan markets represent the most penetrable entry point, with boutique fitness operators in urban corridors underserved by established running-focused brands. Target white-space procurement through direct-to-consumer subscription models with seasonal replenishment tied to training periodization, leveraging smartphone stabilization cross-licensing for magnetic bottle docking differentiation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor conglomerates seeking portfolio rationalization, particularly those with reservoir heritage but diluted running-specialist focus. Long-term viability over a multi-year horizon hinges on subscription customer lifetime value concentration and compliance documentation moats. Watch for inflection signals in direct-to-consumer subscription adoption rates among endurance athletes in Colorado and Oregon.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Concentrates customer lifetime value data with brands while reducing wholesale margin erosion in marathon-focused segments. |
| REACH Compliance Certification Investment | Creates procurement barriers against non-compliant manufacturers seeking European market access under ECHA administration. |
| Modular Attachment System Development | Enables cross-licensing opportunities with mobile accessory manufacturers converging magnetic docking with smartphone stabilization. |
| Neoprene Compounding Backward Integration | Secures margin pools from petrochemical feedstock volatility and filters supplier pools to audited REACH-compliant manufacturers. |
| Vest-Compatible Design Extension | Defends against technical hydration vest substitution among ultramarathon participants seeking higher fluid capacity. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade records, specialty sporting goods retail audit data, and marathon event registration databases, combining structured interviews with product development executives at hydration equipment manufacturers, regulatory affairs leads managing REACH and Proposition 65 compliance, and category buyers at specialty running retailers. Bottom-up demand modeling from event participation rates and replacement cycle frequencies triangulates against top-down market sizing from trade flow analysis and distributor shipment data.
Forecast inputs include trail running event density by state, gym-based interval training studio expansion rates, and compliance certification timelines across OEKO-TEX and REACH frameworks, with segmentation dimensions spanning product architecture, material composition, end-user athletic commitment level, and distribution channel margin structure. CAGRs derive from elasticity modeling of gear replacement frequency against participation growth across the projection horizon, incorporating seasonal collection launch cycles and just-in-time manufacturing constraints.
Practitioners should monitor regulatory enforcement intensity under California Proposition 65 and EU REACH for early signals of supplier pool contraction, with forecasts reflecting assumptions about certification timeline stability and resin cost trajectories. Cross-checking against marathon event registration benchmarks from Running USA and specialty retail sell-through data from Circana is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rowing Machine Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Padel Balls Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Ice Cleat Market