
 Autonomous Underwater Vehicle (AUV) Market | 2026-2036
Autonomous Underwater Vehicle (AUV) Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Underwater Vehicle (AUV) Market Analysis
Multi-source procurement for pressure-rated sensor arrays is decoupling from traditional single-source defense contracts across the AUV supply base. Kongsberg Gruppen leverages its Norwegian maritime heritage to dominate deep-water acoustic navigation systems. Teledyne Technologies competes through in-house production of sonar modules and underwater connectors. Saab anchors Nordic defense demand with specialized military AUV programs for mine countermeasures.
An autonomous underwater vehicle is a self-propelled, untethered robotic system operating below the water surface, typically rated for pressures from 300 to 6,000 meters depth depending on hull construction, and powered by lithium-ion or silver-zinc battery packs for endurance spanning 10 to 70 hours. Its primary purpose is to execute pre-programmed survey, inspection, or reconnaissance missions without real-time operator control through a physical tether. Unmanned AUV configurations capture the largest share of current procurement volumes, while hybrid AUV platforms represent the fastest-expanding category as navies and research institutions demand modular payload bays switching between autonomous and remotely operated modes. Oil and gas end users concentrate margin pools in deep-water deployment contracts, where extended-duration seabed mapping commands premium pricing over coastal survey work.
The International Maritime Organization shapes AUV certification pathways through SOLAS amendments governing autonomous vessel traffic separation. The US Navy's Unmanned Maritime Autonomy Architecture sets interoperability standards that filter into commercial procurement specifications. ISO 13628-8 provides subsea production system guidelines that AUV manufacturers reference for pressure vessel design and material selection. Stakeholders must monitor how classification societies reconcile autonomous underwater operations with existing collision liability frameworks before committing fleet expansion capital.
Market Dynamics
The offshore energy sector's transition from crewed survey vessels to autonomous seabed mapping platforms is compressing operational timelines and reconfiguring fleet economics for marine service contractors.
Growth Catalysts
- SOLAS amendments:The International Maritime Organization's updated safety protocols mandate certified autonomous navigation systems for vessels operating in international waters, accelerating AUV certification investments.
- Subsea pipeline integrity management:North Sea operators deploy extended-duration AUVs for continuous corrosion monitoring of aging infrastructure at depths exceeding 500 meters.
- Lithium-sulfur battery chemistry:Next-generation energy density improvements extend mission endurance from 70 hours toward 150-hour deployments without hull redesign.
Market Restraints
- Pressure-rated sensor supply concentration:Norwegian and Scottish subsea engineering clusters control 80% of qualified deep-water acoustic navigation component production.
- Silver-zinc battery raw material volatility:Zinc price fluctuations and silver supply constraints from South American mining operations create input cost instability for long-endurance AUV configurations.
- Collision liability framework gaps:Existing maritime insurance treaties lack clear fault allocation protocols for autonomous underwater operations in shared seabed corridors.
Strategic Opportunities
- Brazil pre-salt field expansion:Petrobras and international consortium partners require autonomous survey capacity for ultra-deepwater blocks beyond 2,000 meters where crewed operations face safety limitations.
- Hybrid AUV-ROV convergence:Modular payload architectures enable single-platform switching between fully autonomous seabed mapping and tethered intervention modes.
- US Navy Unmanned Maritime Autonomy Architecture adoption:Interoperability standards filter into commercial procurement specifications, creating specification advantages for compliant vendors.
Industry Challenges
- Subsea robotics engineering talent scarcity:Deep-water pressure vessel design and acoustic signal processing expertise concentrates among retiring specialists in Norway and Scotland.
- Classification society certification timelines:Bureau Veritas and DNV GL review processes for autonomous underwater pressure hulls extend 18-24 months, delaying fleet deployment schedules.
- Legacy ROV infrastructure integration:Existing vessel-based launch and recovery systems require mechanical and software retrofitting to accommodate autonomous platform interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Underwater Vehicle (AUV) Market |
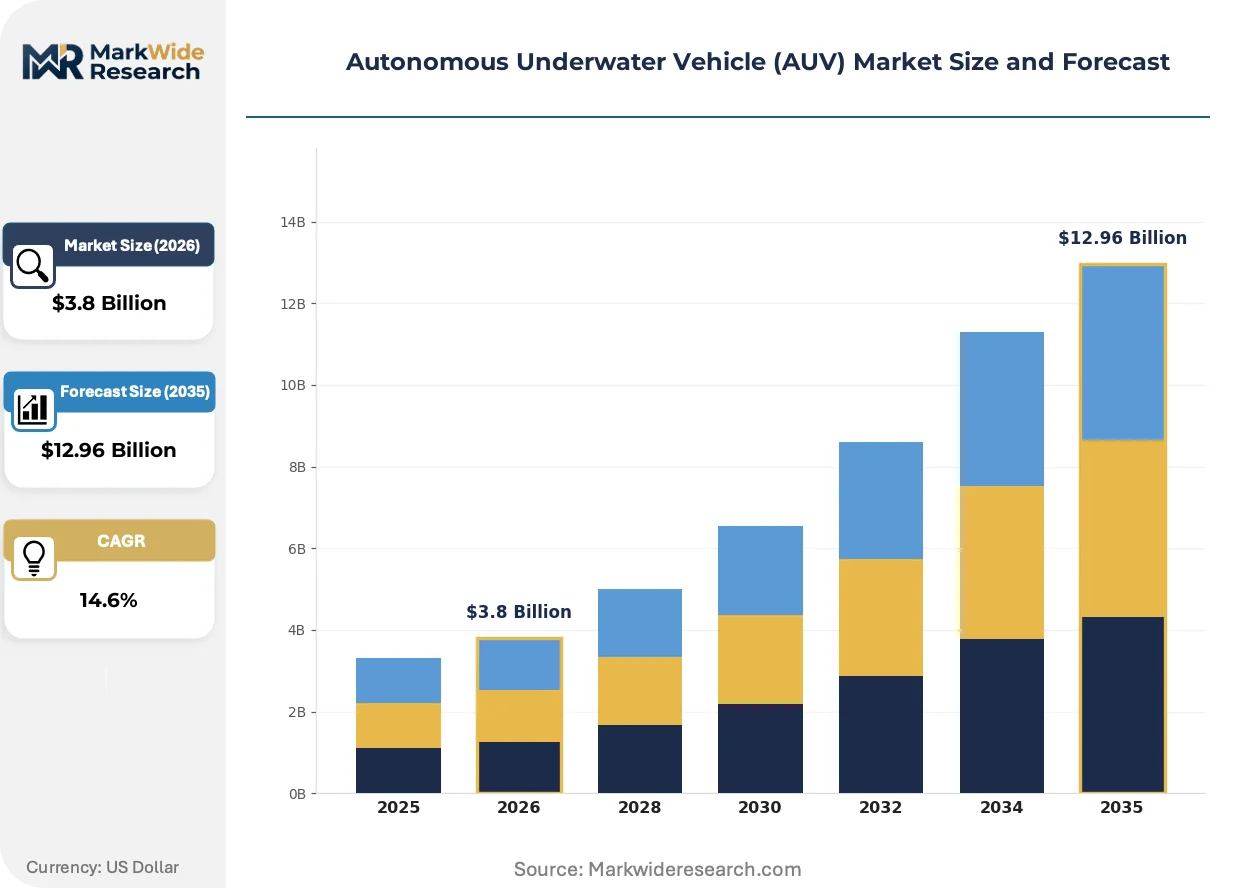
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro AUV, Manned AUV, Unmanned AUV, Hybrid AUV End User: Military, Research Institutions, Oil & Gas, Environmental Monitoring Technology: Acoustic Navigation, Optical Systems, Sonar, GPS Deployment: Shallow Waters, Deep Waters, Coastal Areas, Urban Waterways |
| Companies Covered | Hydroid, Thales Group, Kongsberg Gruppen, Oceaneering International, The Boeing Company, Teledyne Technologies, Fugro, Saab, Exail Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Underwater Vehicle (AUV) Market Emerging Trajectories
Autonomous underwater platforms are evolving from single-purpose survey tools toward reconfigurable seabed work systems, with hardware modularity and software-defined mission architectures displacing fixed-configuration procurement.
Swappable payload bay architectures are modularizing AUV mission capability. Oil and gas operators in the Gulf of Mexico and North Sea now specify standardized mechanical and electrical interfaces enabling rapid sensor reconfiguration between geophysical, visual, and chemical sensing missions. This modularity is compressing vessel downtime between survey campaigns from days to hours, shifting competitive advantage toward platform-agnostic payload vendors rather than integrated system suppliers.
REACH substance restrictions and the EU Green Deal's circular economy requirements are reshaping material selection for pressure vessel construction. Composite hull manufacturers must now document full supply chain chemical compliance and end-of-life recyclability pathways. Norwegian AUV builders face particular pressure as Bergen-to-Stavanger production clusters export into EU markets requiring extensive technical documentation.
Marine survey contractors are unbundling AUV operations from integrated vessel charter packages. Independent platform operators now offer pay-per-line-kilometer seabed mapping services, displacing traditional day-rate vessel contracts. This consumption shift concentrates procurement authority with offshore field development engineers rather than marine logistics coordinators, most visibly in Australia's offshore wind site characterization programs where developers directly contract autonomous survey capacity.
Autonomous Underwater Vehicle (AUV) Market Segmentation
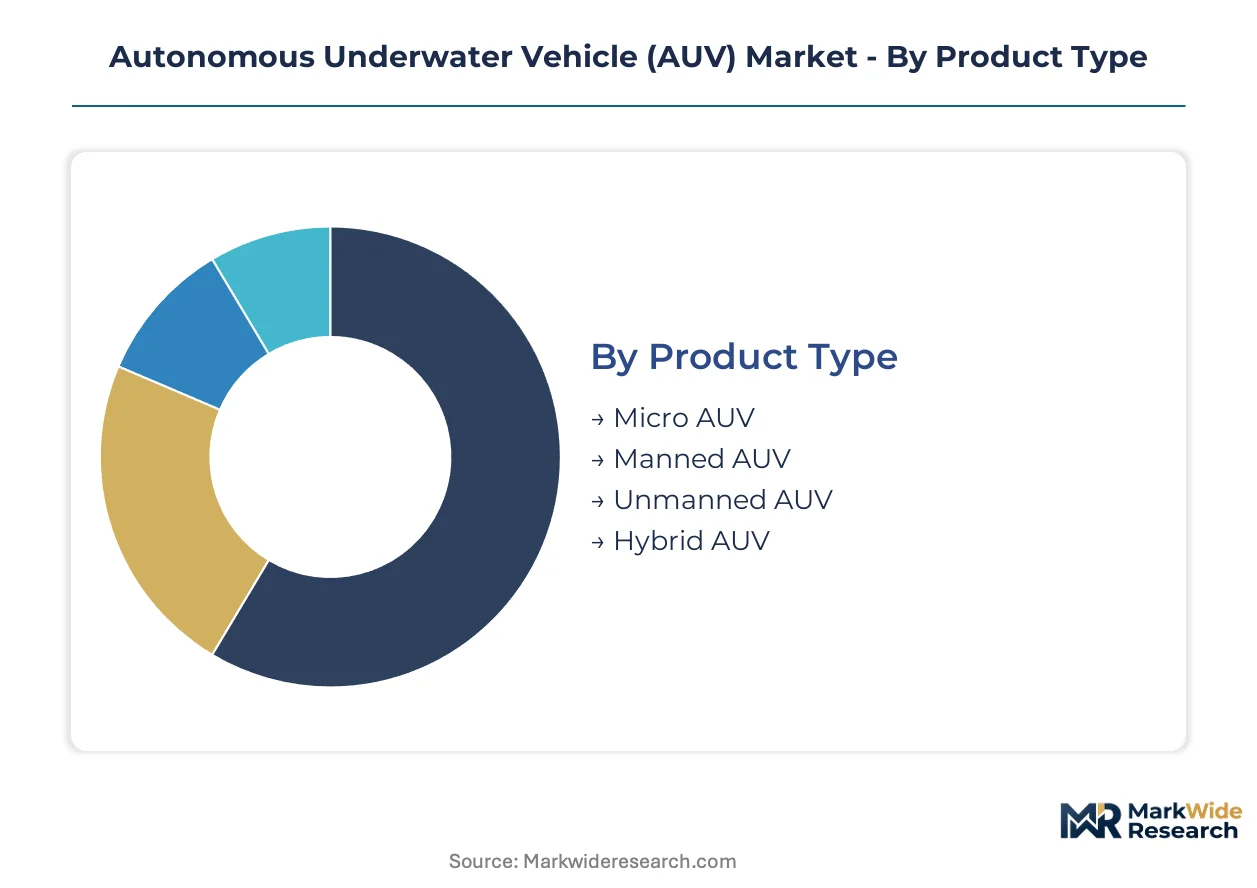
AUV procurement patterns diverge sharply across operational depth, payload flexibility, and mission autonomy requirements. Buyers prioritize pressure rating and endurance specifications over brand heritage when evaluating platform configurations for specific seabed survey contracts.
Product Type:
Platform scale and crew accommodation requirements drive initial purchase decisions, with operational depth rating and mission duration serving as secondary filters.
- Unmanned AUV:Self-propelled robotic systems operate without physical tether or real-time operator control, typically rated for pressures from 300 to 6,000 meters depending on hull construction. Oil and gas operators in Norway's North Sea fields deploy these platforms for continuous pipeline integrity monitoring where crewed alternatives face safety limitations at depths exceeding 500 meters.
- Hybrid AUV:Modular payload architectures enable switching between fully autonomous seabed mapping and tethered intervention modes through standardized mechanical and electrical interfaces. Navies and research institutions in the Bergen-to-Stavanger technology corridor specify these configurations for mine countermeasures and adaptive research missions where mission parameters shift mid-deployment.
- Micro AUV:Compact platforms with reduced pressure ratings serve coastal environmental monitoring and harbor security applications where launch constraints limit hull dimensions.
- Manned AUV:Occupied pressure vessels support deep-water intervention and subsea construction oversight where direct human judgment remains operationally critical.
Volume sits with Unmanned AUV configurations; growth tilts toward Hybrid AUV platforms as navies and offshore operators demand operational flexibility.
End User:
Procurement authority concentrates with technical specialists who specify pressure vessel certification and sensor integration requirements rather than general marine logistics coordinators.
- Oil & Gas:Offshore field development engineers contract autonomous survey capacity directly for ultra-deepwater block characterization beyond 2,000 meters, displacing traditional integrated vessel charter packages with pay-per-line-kilometer seabed mapping services.
- Military:Naval procurement offices specify interoperability standards aligned with the US Navy's Unmanned Maritime Autonomy Architecture for mine countermeasures and reconnaissance programs, creating specification advantages for compliant vendors.
- Research Institutions:Academic and government laboratories prioritize modular payload bays for multi-disciplinary oceanographic data collection across varying seabed terrains.
- Environmental Monitoring:Regulatory compliance programs drive demand for chemical sensing configurations in coastal watershed management and marine protected area surveillance.
Revenue concentration favors Oil & Gas contracts; procurement velocity is climbing fastest among Environmental Monitoring programs responding to tightened maritime safety protocols.
Technology:
Navigation and sensing subsystem selection determines mission success rates in GPS-denied underwater environments where acoustic propagation characteristics vary by depth and seabed composition.
- Acoustic Navigation:Deep-water positioning systems leverage Norwegian maritime heritage for long-baseline and ultra-short-baseline configurations that maintain accuracy at depths exceeding 6,000 meters.
- Sonar:Side-scan and multibeam echo sounder modules from specialized subsea engineering clusters capture seabed morphology data for pipeline route surveys and archaeological site documentation.
- Optical Systems:High-resolution camera payloads and structured light scanners support visual inspection of subsea infrastructure corrosion and biological fouling.
- GPS:Surface-integrated positioning provides mission initialization and recovery coordination, though underwater segments rely on dead reckoning between acoustic fixes.
Platform differentiation depends on Acoustic Navigation integration; Sonar payload specifications command the steepest premium pricing in deep-water deployment contracts.
Deployment:
Depth rating and operational environment dictate pressure vessel design standards, battery chemistry selection, and launch and recovery system compatibility.
- Deep Waters:Extended-duration missions at depths beyond 500 meters require lithium-sulfur battery chemistry and titanium or composite pressure hulls certified to ISO 13628-8 subsea production system guidelines.
- Shallow Waters:Coastal survey operations benefit from reduced pressure rating requirements and shorter mission endurance specifications, compressing platform acquisition costs for environmental baseline studies.
- Coastal Areas:Nearshore deployment zones demand collision avoidance systems compliant with International Maritime Organization SOLAS amendments for autonomous vessel traffic separation.
- Urban Waterways:Harbor and inland waterway applications prioritize compact hull dimensions and reduced acoustic signatures for infrastructure inspection and security patrol.
Margin pools concentrate in Deep Waters contracts; certification timelines and talent scarcity constrain supply expansion across all depth categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian titanium and composite material suppliers anchor Atlantic basin AUV manufacturing. Deep-water testing infrastructure clusters along North Sea coastlines. Pacific Rim battery chemistry development shapes next-generation endurance specifications.
Norway
Statoil-operated North Sea fields drive demand for 6,000-meter-rated autonomous survey platforms. The Norwegian Maritime Authority enforces certification timelines extending 18-24 months for pressure hull validation. Kongsberg Gruppen anchors the Bergen-to-Stavanger corridor where acoustic navigation system production concentrates.
United States
Petrobras pre-salt field requirements and Gulf of Mexico ultra-deepwater blocks sustain procurement of extended-duration AUV configurations. The US Navy's Unmanned Maritime Autonomy Architecture sets interoperability standards filtering into commercial specifications. Houston-based marine service contractors unbundle autonomous survey operations from integrated vessel charter packages.
Brazil
Pre-salt carbonate reservoirs beyond 2,000 meters depth create safety limitations for crewed survey alternatives. ANVISA and the national petroleum regulator enforce subsea equipment certification aligned with ISO 13628-8 production system guidelines. Rio de Janeiro anchors South American AUV deployment capacity for Petrobras and international consortium partners.
United Kingdom
Aging North Sea pipeline infrastructure demands continuous corrosion monitoring through autonomous platforms. The Health and Safety Executive mandates subsea integrity management protocols accelerating AUV fleet expansion. Aberdeen subsea engineering clusters control qualified deep-water acoustic navigation component production alongside Norwegian suppliers.
China
MIIT-funded marine robotics programs expand domestic AUV manufacturing capacity for seabed resource mapping. GB standards and SAMR certification requirements shape pressure vessel design specifications for regional export markets. Qingdao and Shanghai anchor Yangtze River Delta and Shandong Peninsula production clusters serving Asia-Pacific offshore energy contracts.
Autonomous Underwater Vehicle (AUV) Market Vendor Landscape
Global majors compete with regional champions across acoustic navigation and pressure-rated sensor integration. The vendor base stratifies between integrated system suppliers and modular payload specialists. Defense-heritage conglomerates and subsea engineering pure-plays represent distinct strategic archetypes. Competitive moves center on M&A for sensor technology access and strategic partnerships for battery chemistry advancement.
Within the Nordic defense-heritage tier, Kongsberg Gruppen and Saab exemplify maritime technology conglomerates with established subsea navigation expertise. Teledyne Technologies occupies a position among North American diversified technology groups with in-house sonar module production. Hydroid represents the specialist archetype, anchoring Massachusetts-based AUV platform development for research and commercial survey applications.
| Leading Market Players |
|---|
| Hydroid |
| Thales Group |
| Kongsberg Gruppen |
| Oceaneering International |
| The Boeing Company |
| Teledyne Technologies |
| Fugro |
| Saab |
| Exail Technologies |
| Others |
Supply Flow & Price Mechanics
EU Green Deal circular economy requirements gate qualified supply and premium-tier pricing access for pressure-rated composite hulls, as Norwegian and Scottish manufacturers must document full chemical compliance and recyclability pathways before contracting with offshore energy buyers.
Pricing Analysis
Extended warranty and field service bundling separate premium-tier AUV configurations from unbundled platform-only procurement, with ISO 13628-8 pressure vessel certification and lithium-sulfur battery chemistry commanding steep premiums over silver-zinc alternatives. Price differentiation rests on certification grade and mission endurance specifications, with deep-water rated platforms capturing margin pools unavailable to coastal survey configurations. Cost compression in shallow-water segments is intensifying because environmental monitoring programs prioritize acquisition cost over extended operational envelopes. Research institutions exhibit highest price sensitivity, while oil and gas field development engineers prioritize pressure rating and reliability over upfront capital expenditure.
Supply Chain Analysis
Dual-sourcing mandates from Petrobras and major North Sea operators require qualification of at least two acoustic navigation component suppliers, pressuring procurement teams to maintain relationships with both Norwegian and Scottish engineering clusters. Geographic supply concentration centers on Norway, the United Kingdom, and the United States for titanium pressure hulls and deep-water sonar modules. Raw material dependencies draw from South American silver mining operations, lithium carbonate from Chilean salares, and carbon fiber prepreg from US and Japanese suppliers. Single-source vulnerability in qualified deep-water sensor arrays creates structural exposure, as 18-24 month certification timelines prevent rapid supplier substitution. Distribution runs through marine service contractors and direct platform operators offering pay-per-line-kilometer seabed mapping services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure hull certification bottlenecks at Bureau Veritas and DNV GL prop pricing power for qualified suppliers, as 18-24 month validation timelines constrain fleet expansion regardless of capital availability.
For Market Incumbents: Deepen captive supply arrangements for lithium-sulfur battery chemistry through strategic partnerships with Pacific Rim cell manufacturers, insulating against silver-zinc raw material volatility while accelerating extended-duration platform development. Fortify acoustic navigation expertise against emerging optical sensing substitutes by investing in software-defined signal processing architectures that leverage existing long-baseline infrastructure. For New Entrants and Emerging Players: Begin with harbor security and coastal environmental monitoring applications where reduced pressure ratings and shorter certification pathways lower barriers to qualified supply. Brazil's pre-salt field expansion presents the most penetrable geography, as ANVISA-aligned certification requirements favor new suppliers willing to navigate ISO 13628-8 validation alongside established operators. A direct sales model targeting offshore wind site characterization programs bypasses entrenched marine service contractor relationships. For Investors and Strategic Acquirers: DNV GL certification backlog clearance is the leading indicator that capacity constraints are easing and pricing power is shifting toward volume suppliers. Long-term viability favors platform-agnostic payload vendors over integrated system suppliers, as modularity compresses vessel downtime and concentrates procurement authority with field development engineers. Acquisition targets should display software-defined mission architectures and established relationships with Bergen-to-Stavanger testing infrastructure. Monitor lithium-sulfur battery chemistry commercialization timelines as the critical inflection signal for endurance specification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Hull Certification Investment | DNV GL validation accelerates fleet deployment schedules for deep-water contracts. |
| Lithium-Sulfur Battery Partnership | Pacific Rim cell suppliers enable 150-hour mission endurance without hull redesign. |
| Modular Payload Architecture Development | Swappable sensor bays compress vessel downtime from days to hours for North Sea operators. |
| Direct Platform Operator Model | Pay-per-line-kilometer contracts displace day-rate vessel charters in Australian offshore wind. |
| Acoustic Navigation Software Investment | Signal processing expertise defends against optical sensing substitution in GPS-denied environments. |
Methodological Framework
Independent corroboration across subsea engineering executives, offshore field development engineers, marine service contractor operations directors, and acoustic navigation system specialists underwrites the qualitative findings, validated against International Maritime Organization SOLAS amendment documentation, ISO 13628-8 technical specifications, US Navy Unmanned Maritime Autonomy Architecture publications, and classification society certification records. Bottom-up platform deployment tallies triangulate with top-down offshore energy capital expenditure assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by platform type, operational depth rating, end-use sector, and battery chemistry configuration. CAGRs derive from weighted average of historical deployment patterns and forward-projected offshore field development schedules, with particular sensitivity to Petrobras pre-salt capital commitments and North Sea pipeline integrity management program expansions.
Underlying measurement precision varies by segment; deep-water oil and gas contracts carry tighter precision than emerging environmental monitoring applications due to disclosed contract values and established procurement cycles. Forecasts reflect documented assumptions regarding certification timeline stability and lithium-sulfur chemistry commercialization schedules. Deviation in DNV GL or Bureau Veritas review capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Mooring Ropes Market
Marine
Tele-Operated Marine Drone Market
Marine
Marine Shackle Market
Marine
Europe Recreational Boating Market
Marine
Asia-Pacific Electric Boat Market
Marine
Military Marine Engine Market
Marine
Jet Boat Market
Marine
Boat Hook Market
Marine
Marine Chronometers Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Marine VFD Market
Marine
Sea Skimmer Market
Marine
Boat Control Lever Market
Marine
Marine Navigation System Market
Marine
Rescue Boats Market
Marine
Marine Shaft Power Meter Market