
 Marine Filter Market | 2026-2036
Marine Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Filter Market Analytics
Modular cartridge-to-bulkhead upgrade bundles is consolidating buyer preference across mid-size commercial fleets. MANN+HUMMEL Group leverages its automotive filtration heritage to dominate marine-specific media development. Pall Corporation anchors its position through membrane technology leadership in ballast water applications. Donaldson Company, Inc. competes on aftermarket channel density in port-heavy geographies.
Marine filters are pressure-rated fluid and air purification devices constructed from pleated synthetic media, sintered metal mesh, or wound fiberglass elements, designed to remove particulate, microbial, and chemical contaminants from fuel, lubrication, hydraulic, intake air, and ballast systems aboard seagoing vessels. Fuel filters and water filters represent the fastest-growing product categories, driven by IMO 2020 low-sulfur fuel compatibility mandates and ballast water management convention enforcement. Stainless steel and fiberglass materials command premium positioning due to saltwater corrosion resistance and extended service intervals in heavy-duty commercial installations.
The International Maritime Organization, the US Coast Guard, and the EU MRV regulation collectively tighten emissions verification and ballast water discharge standards, forcing filter OEMs to certify against successive protocol tiers. Classification societies including DNV and Lloyd's Register now embed filtration performance into vessel compliance scoring, redirecting procurement toward certified suppliers. Stakeholders must monitor regulatory harmonization gaps between flag-state requirements and port-state enforcement to anticipate certification-driven demand spikes.
Market Dynamics
Classification societies now embed filtration performance into vessel compliance scoring, redirecting procurement toward certified suppliers and compressing the vendor base for commercial fleet operators.
Growth Catalysts
- IMO MARPOL Annex VI sulfur regulations:Tightening emissions compliance requirements force fleet operators to upgrade fuel filtration systems for low-sulfur fuel compatibility.
- Ballast water management convention enforcement:Port-state control inspections in major shipping hubs drive replacement demand for membrane-based treatment filters.
- Stainless steel media adoption:Saltwater corrosion resistance extends service intervals in heavy-duty commercial installations, reducing total lifecycle costs for deep-sea operators.
Market Restraints
- Specialized alloy input costs:Nickel and molybdenum price volatility compresses margins for stainless steel filter housings used in corrosive marine environments.
- Membrane supply concentration:Hollow-fiber membrane production clusters in East Asian chemical parks, exposing OEMs to single-source risk during port disruptions.
- Hydraulic filter technical limitations:High-pressure rating requirements above 420 bar restrict media options to sintered metal mesh, limiting cost-down opportunities.
Strategic Opportunities
- Modular cartridge-to-bulkhead upgrade bundles:Mid-size commercial fleets in Southeast Asia seek retrofit solutions that minimize dry-dock time and labor costs.
- EU Green Deal maritime decarbonization incentives:Fleet renewal subsidies in European waters favor filter systems with verified emissions reduction credentials.
- Digital sensor convergence with filtration hardware:Pressure-differential monitoring integration enables predictive maintenance contracts for container shipping lines.
Industry Challenges
- Classification society certification timelines:DNV and Lloyd's Register type-approval processes for new filter media formulations extend product launch cycles by 12-18 months.
- Ballast water treatment system integration complexity:Retrofit installations on legacy bulk carriers require custom manifold designs that strain engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Filter Market |
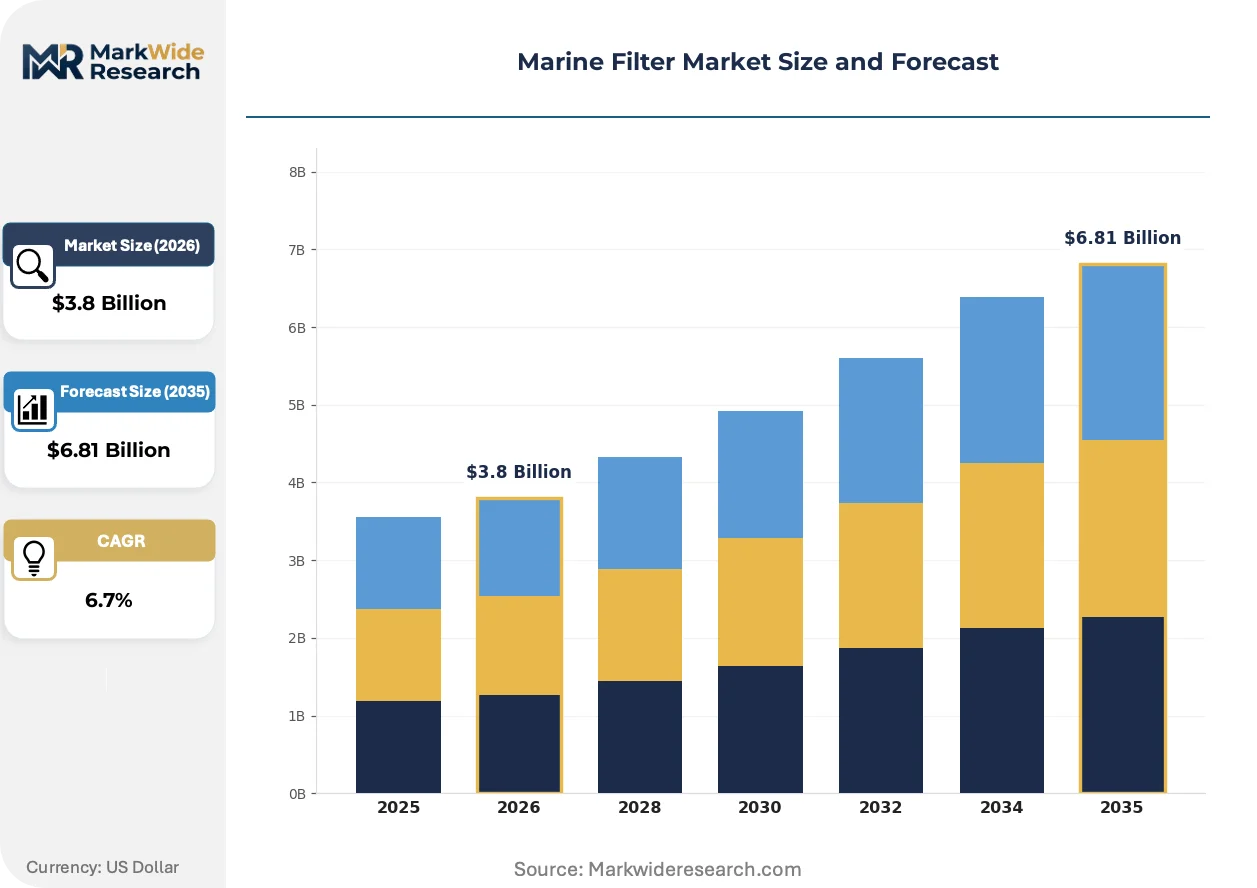
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Filters, Fuel Filters, Water Filters, Air Filters End User: Commercial Vessels, Recreational Boats, Fishing Boats, Service Providers Installation Type: In-line Filters, Cartridge Filters, Bulkhead Filters, Compact Filters Material: Stainless Steel, Polypropylene, Fiberglass, Carbon |
| Companies Covered | MANN+HUMMEL Group, Pall Corporation, Parker Hannifin Corporation, Filtrec S.p.A., Bosch Rexroth AG, Donaldson Company, Inc., Mahle GmbH, HAISTAR MARINE LTD, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Filter Market Evolving Landscape
Active sensor integration and predictive maintenance architectures are compressing traditional filter replacement cycles while elevating aftermarket service revenue as a strategic priority for equipment suppliers.
Self-cleaning backflush filtration technology is automating particulate removal in heavy fuel oil systems without vessel shutdown. Deep-sea tanker operators are retrofitting these units during scheduled dry-dock windows to minimize port time penalties. The technology is automating labor-intensive manual filter changeouts that previously required engine room crew intervention.
The US Coast Guard's enhanced ballast water discharge standards are forcing treatment system OEMs to recertify membrane configurations against successive organism concentration thresholds. Shipyards in Gulf Coast states now specify only pre-approved filter skids to avoid commissioning delays. Bulk carrier segments operating Great Lakes routes face the tightest compliance windows and have accelerated filter media replacement frequencies.
Fleet operators are consolidating vendor relationships around single-source service contracts that bundle filtration hardware with condition monitoring. This model displaces spot procurement through ship chandlers in port-heavy geographies like Singapore and Rotterdam. Container shipping lines with centralized technical management in Hamburg and Copenhagen have pioneered this approach, extracting volume pricing and guaranteed availability commitments.
Marine Filter Market Segmentation
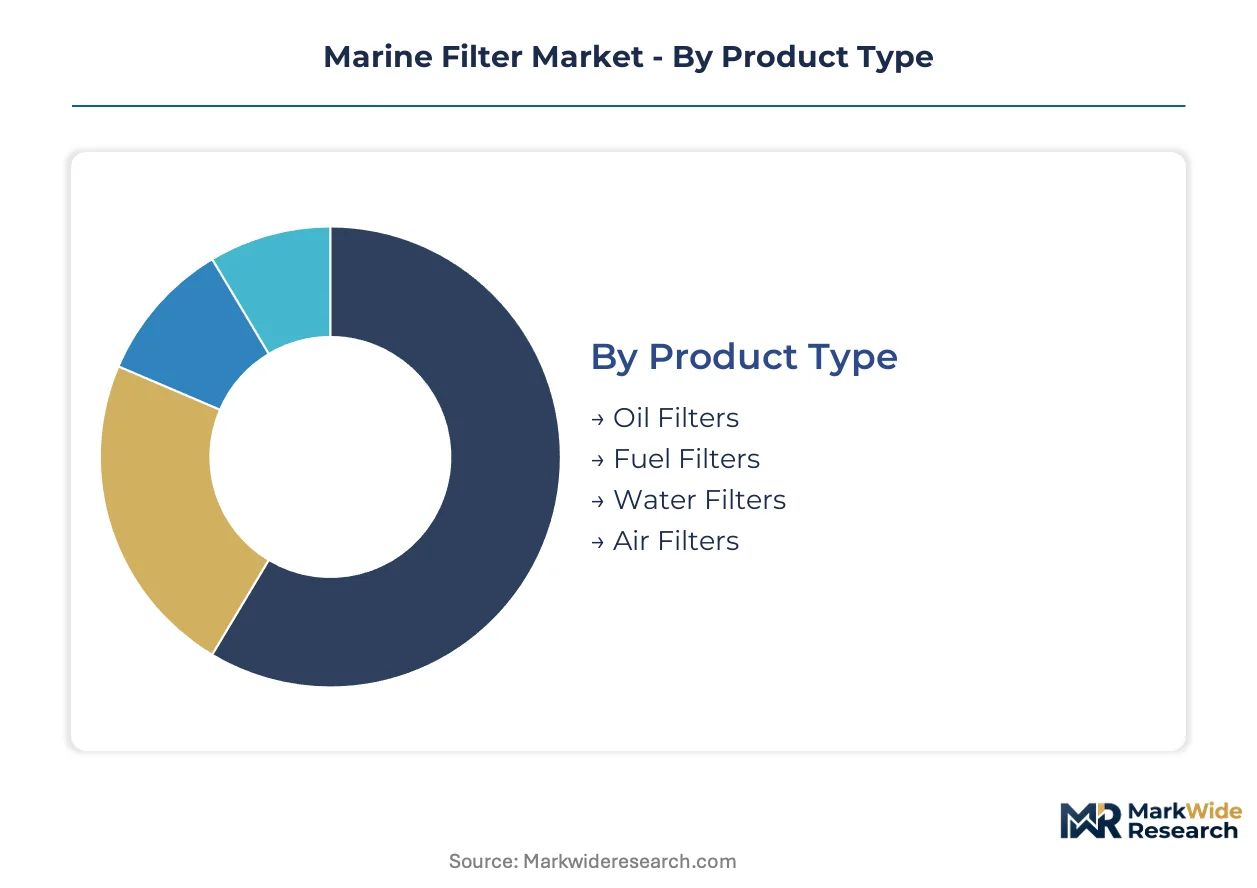
Marine filter procurement patterns diverge sharply between deep-sea commercial operators seeking standardized certification bundles and coastal fleets demanding customized retrofit configurations. Understanding these segment boundaries clarifies why vendor consolidation concentrates in specific technology-material pairings while fragmentation persists elsewhere.
Product Type:
Customization intensity spans from commodity cartridge replacements to engineered bulkhead systems requiring vessel-specific manifold design.
- Fuel Filters:Pleated synthetic media and sintered metal mesh configurations handle low-sulfur fuel compatibility mandates under IMO MARPOL Annex VI. Deep-sea container operators in Singapore and Hamburg drive specification tightening as they consolidate fleet procurement around single-source service contracts.
- Water Filters:Hollow-fiber membrane and wound fiberglass elements remove microbial and chemical contaminants from ballast systems. Port-state control inspections in Chinese and US Coast Guard jurisdictions accelerate replacement cycles for bulk carriers on Great Lakes routes.
- Oil Filters:Pressure-rated assemblies protect lubrication systems in heavy-duty commercial installations.
- Air Filters:Intake purification devices for engine room and HVAC applications aboard seagoing vessels.
Leading the category by volume: Fuel Filters. Growing fastest: Water Filters.
End User:
Customer scale determines whether procurement flows through centralized technical management or decentralized ship chandler networks.
- Commercial Vessels:Deep-sea tankers, container ships, and bulk carriers operating under DNV and Lloyd's Register compliance scoring. Fleet renewal programs in Hamburg and Copenhagen headquarters extract volume pricing and guaranteed availability commitments from certified suppliers.
- Recreational Boats:Yacht and pleasure craft operators prioritize compact footprint and ease of field serviceability. Mediterranean and Caribbean marinas favor aftermarket channel density over OEM-direct relationships.
- Fishing Boats:Coastal and deep-water fishing fleets with intermittent dry-dock schedules.
- Service Providers:Shipyards and maintenance contractors executing retrofit installations on legacy vessels.
Dominant procurement scale: Commercial Vessels. Steepest expansion trajectory: Recreational Boats.
Installation Type:
Physical integration depth separates drop-in replacements from structural hull modifications requiring classification society recertification.
- Cartridge Filters:Modular elements designed for rapid exchange without system shutdown. Southeast Asian mid-size fleets favor these for minimizing dry-dock time and labor costs during scheduled maintenance windows.
- Bulkhead Filters:Permanently mounted housings integrated into vessel fuel and ballast manifolds. Retrofit complexity on legacy bulk carriers strains engineering capacity and extends commissioning timelines.
- In-line Filters:Straight-through configurations for space-constrained engine room layouts.
- Compact Filters:Reduced-footprint units for recreational and small commercial applications.
Highest replacement frequency: Cartridge Filters. Gaining share fastest: Bulkhead Filters.
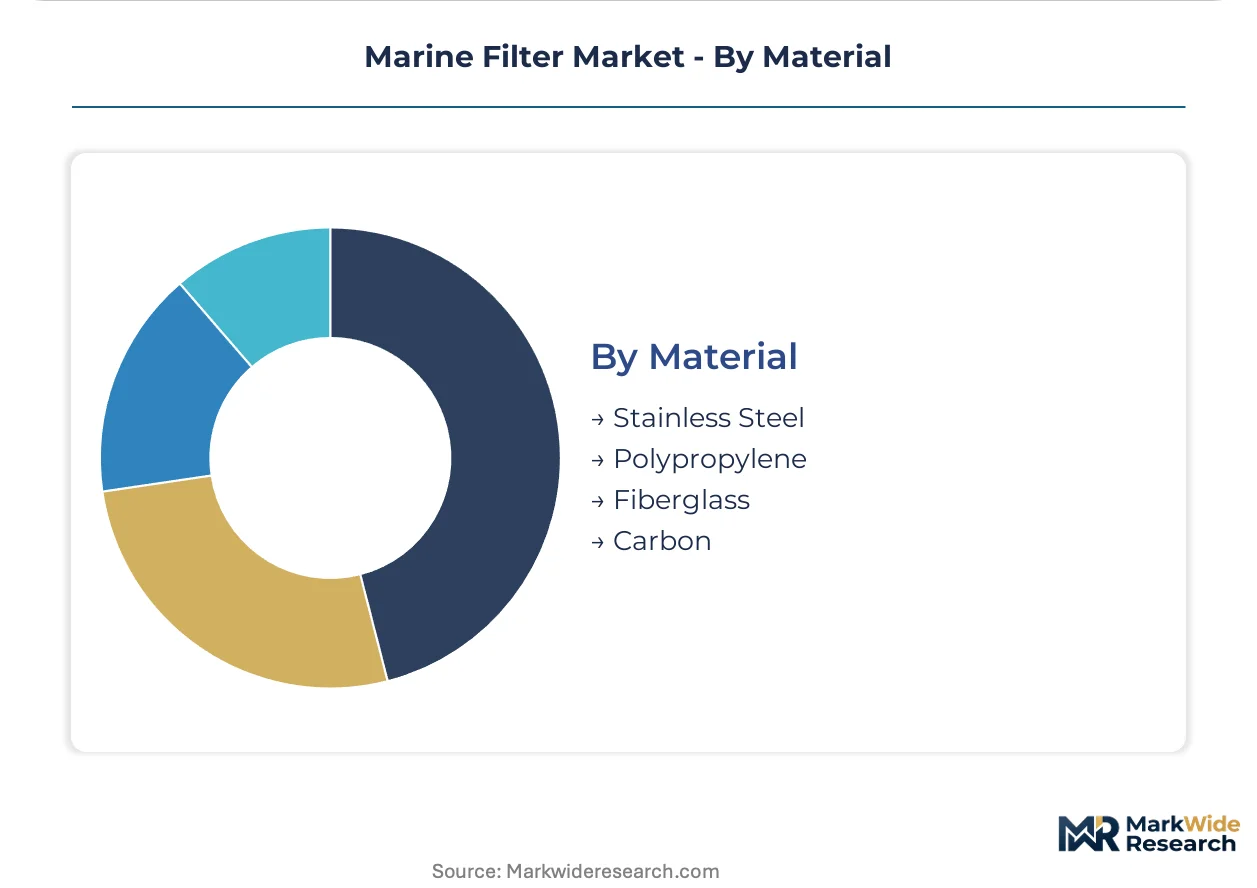
Material:
Corrosion resistance requirements and pressure ratings segment material selection between premium alloys and commodity polymers.
- Stainless Steel:Nickel-alloyed housings and sintered mesh deliver saltwater corrosion resistance for heavy-duty commercial installations. Nickel and molybdenum price volatility compresses margins for OEMs serving deep-sea operators.
- Fiberglass:Wound composite elements combine chemical inertness with extended service intervals in ballast water applications. Production clusters in East Asian chemical parks expose supply chains to single-source risk during port disruptions.
- Polypropylene:Injection-molded components for cost-sensitive cartridge and compact filter categories.
- Carbon:Specialized media for adsorption-based contaminant removal in niche fuel conditioning systems.
Premium positioning: Stainless Steel. Climbing the fastest: Fiberglass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of marine filter components and membrane substrates, while fleet operators in Germany, Japan, and the United States drive specification tightening through centralized procurement offices. This production-consumption split shapes trade flows and certification requirements across the value chain.
China
Shipyards in Shanghai and Dalian expand output of bulk carriers and container vessels requiring certified filtration systems. The Ministry of Ecology and Environment enforces stricter port-state control on ballast water treatment compliance. Hollow-fiber membrane production clusters in Jiangsu province expose OEMs to concentration risk during port disruptions.
Germany
Container shipping lines headquartered in Hamburg consolidate fleet procurement around single-source service contracts with guaranteed availability commitments. The EU Green Deal maritime decarbonization incentives favor filter systems with verified emissions reduction credentials. Engineering consultancies in Munich specialize in custom manifold designs for retrofit installations on legacy vessels.
United States
The US Coast Guard enforces enhanced ballast water discharge standards forcing treatment system recertification against successive organism concentration thresholds. Shipyards in Gulf Coast states specify only pre-approved filter skids to avoid commissioning delays. Bulk carriers operating Great Lakes routes face the tightest compliance windows and accelerate filter media replacement frequencies.
Japan
Deep-sea tanker operators retrofit self-cleaning backflush filtration units during scheduled dry-dock windows to minimize port time penalties. METI coordinates fleet renewal programs emphasizing stainless steel media adoption for saltwater corrosion resistance. Classification society type-approval processes in Tokyo extend product launch cycles for new filter media formulations.
Singapore
Port-heavy geography concentrates aftermarket channel density for cartridge filter replacements serving Southeast Asian mid-size fleets. Fleet operators seek modular upgrade bundles that minimize dry-dock time and labor costs during scheduled maintenance windows. Maritime service providers bundle filtration hardware with condition monitoring displacing spot procurement through traditional ship chandlers.
Marine Filter Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with cross-sector filtration expertise. Tiered positioning separates membrane technology specialists from aftermarket channel operators. Three archetypes dominate: automotive-derived marine media developers, ballast water membrane leaders, and port-density aftermarket service networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as players seek classification society certification coverage.
Among diversified industrial filtration groups, MANN+HUMMEL Group, Pall Corporation, and Donaldson Company, Inc. occupy positions reflecting distinct strategic origins. MANN+HUMMEL represents the automotive heritage archetype applying passenger vehicle media expertise to marine specifications. Pall Corporation exemplifies membrane technology leadership anchored in ballast water treatment applications. Donaldson Company, Inc. sits within the aftermarket density archetype leveraging port-proximate distribution networks. These three entities illustrate how parent-industry DNA shapes competitive positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| MANN+HUMMEL Group |
| Pall Corporation |
| Parker Hannifin Corporation |
| Filtrec S.p.A. |
| Bosch Rexroth AG |
| Donaldson Company, Inc. |
| Mahle GmbH |
| HAISTAR MARINE LTD |
| Eaton Corporation |
| Others |
Value Network & Pricing Analysis
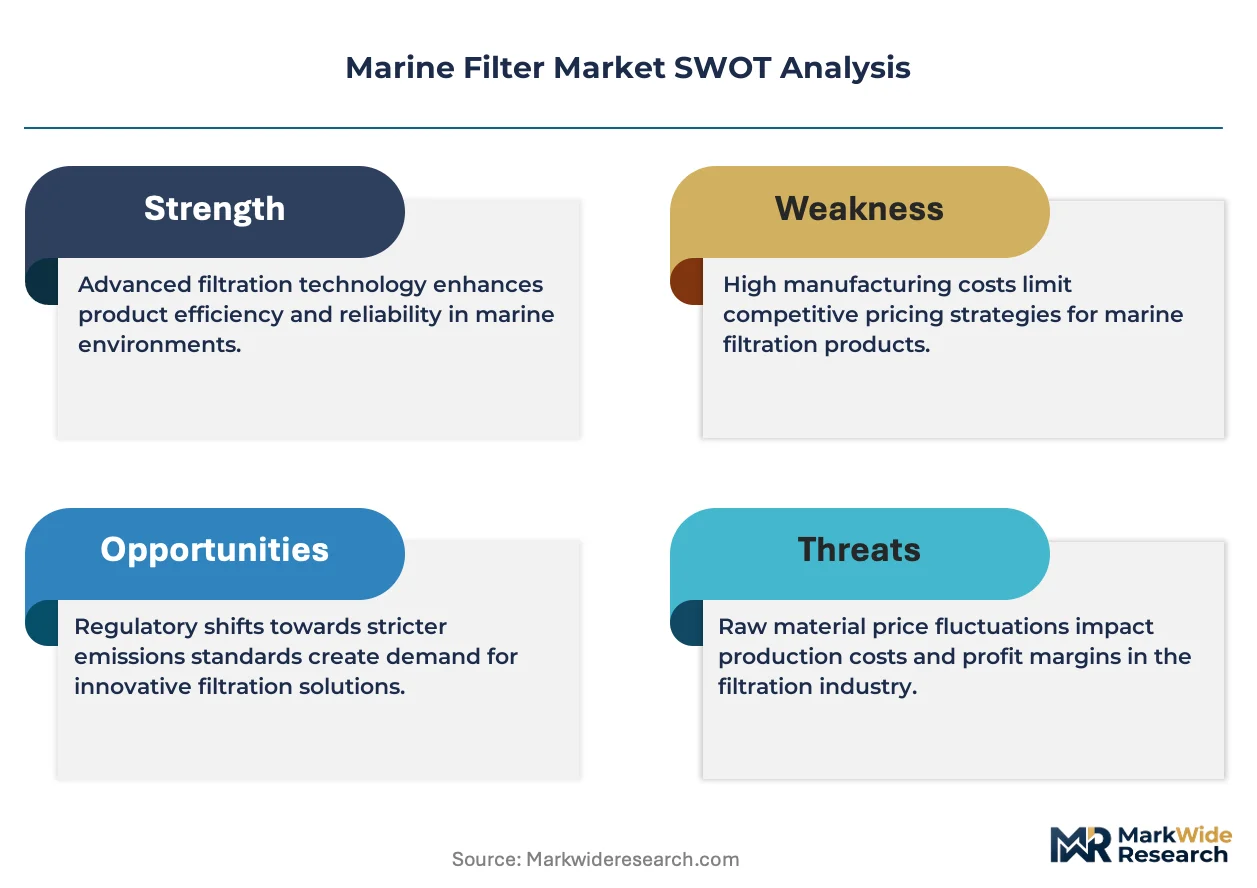
Captive membrane production in Jiangsu province anchors both supply security and pricing power for hollow-fiber ballast water treatment filters, forcing OEMs to absorb nickel-molybdenum alloy volatility or cede margin to stainless steel housing competitors serving deep-sea operators.
Pricing Analysis
Cost-down pressure on cartridge filter tiers accelerates because Southeast Asian mid-size fleets prioritize dry-dock time reduction over media longevity, compressing aftermarket margins for port-proximate distributors. Three-tier pricing structure across IMO-certified premium, Lloyd's-registered standard, and uncertified economy levels separates procurement flows in Hamburg from spot buying in Singapore. Nickel price volatility squeezes stainless steel housing margins while polypropylene cartridge producers defend volume through ship chandler rebates. Commercial vessel operators with centralized technical management show lowest price sensitivity; recreational boat owners in Mediterranean marinas exhibit highest.
Supply Chain Analysis
Refurbishment flows for self-cleaning backflush units concentrate in Japanese dry-dock yards, creating secondary parts markets that compete with OEM cartridge sales. Hollow-fiber membrane substrate production clusters in China and South Korea, while stainless steel sintered mesh draws from German and Japanese metallurgical specialists. Single-source vulnerability in Jiangsu chemical park membrane supply exposes treatment system OEMs to port disruption contagion. Distribution runs through certified supplier networks displacing traditional ship chandler spot procurement in Rotterdam and Singapore hub markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Classification society certification timelines compress the vendor base, forcing sub-scale membrane formulators and uncertified housing fabricators toward exit or acquisition.
For Market Incumbents: Anchor ballast water membrane capacity in dual-source geographies to mitigate Jiangsu concentration risk. Deepen captive sintered metal mesh production for hydraulic filters above 420 bar ratings where technical barriers exclude Asian competitors. Defend against automotive-derived entrants leveraging pleated media scale economies by accelerating DNV type-approval for proprietary formulations. For New Entrants and Emerging Players: Maritime service providers in Southeast Asian port clusters represent the most penetrable channel archetype for modular cartridge-to-bulkhead upgrade bundles. Target mid-size commercial fleets with intermittent dry-dock schedules seeking predictive maintenance integration without classification society recertification complexity. Pursue white-label sensor convergence partnerships with established filtration hardware OEMs to bypass 12-18 month certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial filtration conglomerates seeking ballast water membrane capabilities or Southeast Asian aftermarket density. Five-to-ten year viability favors suppliers with dual certification coverage across DNV and Lloyd's Register protocols. Monitor IMO MARPOL Annex VI sulfur tier enforcement timelines as inflection indicators for fuel filtration upgrade demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Certification Investment | DNV type-approval compresses product launch cycles against 12-18 month baseline timelines. |
| Backward Integration into Membrane Substrate | Captive hollow-fiber production in dual-source geographies mitigates Jiangsu concentration risk. |
| Predictive Maintenance Platform Partnership | Pressure-differential sensor integration enables recurring service contracts with container lines. |
| Southeast Asian Channel Acquisition | Port-proximate aftermarket density displaces spot procurement through Singapore ship chandlers. |
| Stainless Steel Alloy Supply Agreement | Long-term nickel-molybdenum offtake hedges margin compression in heavy-duty commercial segments. |
Research Methodology
Document review covered IMO MARPOL regulatory filings, Lloyd's Register type-approval databases, and ballast water treatment system commissioning records, complemented by interviews with fleet technical managers at Hamburg and Copenhagen headquarters, shipyard procurement officers in Shanghai and Dalian, and aftermarket distribution heads in Singapore and Rotterdam. Secondary validation drew from customs trade data for stainless steel filter housing imports, SEC filings of diversified industrial filtration groups, and classification society annual reports. Bottom-up vessel fleet segmentation triangulated against top-down OEM revenue attribution across the analysis window.
Cross-referencing historical replacement cycle data with panel input from commercial vessel operators yielded volume projections across fuel, water, oil, and air filter categories. Segmentation dimensions modeled include product type, installation configuration, material grade, and end-user fleet scale. CAGRs were derived from regression against fleet renewal program announcements and regulatory enforcement phase-in schedules. Industry-specific forecast inputs incorporated nickel price futures curves and ballast water treatment system retrofit penetration rates by vessel age cohort.
Caveats apply where IMO regulatory harmonization gaps between flag-state requirements and port-state enforcement could materially shift the outlook for certification-driven demand spikes. Forecasts reflect assumptions about stainless steel alloy input cost stability and membrane substrate supply continuity. Practitioners should monitor US Coast Guard ballast water discharge standard tier advances and EU Green Deal maritime decarbonization subsidy allocation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sliding Fender Market
Marine
Freighter Conversions Market
Marine
Boat Steering Systems Market
Marine
Marine Dynamic Positioning System Market
Marine
Global Maritime Information Market
Marine
Marine Airbags Market
Marine
Marine Communication Market
Marine
India Boat Davits Market
Marine
Azimuth Thrusters Market
Marine
North America Naval Vessels Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Marine Strip Market
Marine
Digital Nautical Charts Market
Marine
Marine Salvage Services Market
Marine
Asia-Pacific Electric Boat Market
Marine
Steel Ship Plate Market