
 Polyolefin Battery Separator Films Market | 2026-2036
Polyolefin Battery Separator Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Battery Separator Films Market Analytics
East Asian wet-process separator capacity is decoupling from dry-process supply chains as battery OEMs demand thinner, more uniform films. Asahi Kasei Corporation leverages its biaxial stretching expertise to dominate premium ceramic-coated grades. SK ie technology anchors Korean supply through integrated relationships with domestic cell makers. UBE Corporation sustains cost competitiveness via captive polypropylene resin streams.
Polyolefin battery separator films are microporous membranes, typically 12–40 microns thick, manufactured through wet or dry extrusion of polyethylene and polypropylene to enable ion transport while preventing electrode contact in electrochemical cells. The laminated and coated product types command margin premiums as OEMs specify ceramic or PVDF layers for thermal shutdown safety. Automotive end users represent the fastest-expanding demand pool, while consumer electronics applications remain mature with thinner-film specifications. The 25 micron and 30 micron thickness segments lead volume as cell designers optimize energy density against mechanical integrity.
The EU Battery Regulation and REACH chemical compliance frameworks are reshaping material traceability requirements for separator imports into Europe. China's NMPA enforces mandatory thermal abuse testing that favors coated separator architectures over uncoated alternatives. South Korea's KATS aligns national standards with IEC 62660 cell safety protocols, creating harmonized certification burdens for regional exporters. Stakeholders must monitor evolving solid-state battery timelines, as oxide or polymer electrolyte maturation would eliminate conventional separator demand entirely.
Market Dynamics
Automotive OEMs are consolidating separator procurement around ceramic-coated architectures as thermal runaway containment becomes a non-negotiable cell design parameter. This demand compression is forcing film manufacturers to reconfigure extrusion and coating capacity in parallel.
Growth Catalysts
- NMPA thermal abuse mandates:China's mandatory testing protocols favor coated separator stacks over uncoated alternatives, accelerating specification upgrades across domestic cell production.
- EV platform standardization:Cell-to-pack architectures require thinner, mechanically robust films that wet-process lines deliver with superior thickness uniformity.
- PP resin feedstock proximity:Korean petrochemical clusters provide captive polypropylene supply chains that compress working capital cycles for integrated separator producers.
Market Restraints
- Oil-indexed resin volatility:Polypropylene feedstock costs fluctuate with naphtha cracking margins, compressing separator gross margins during upstream price spikes.
- Dry-process capacity abandonment:Battery OEMs are disqualifying uniaxially stretched PE films from automotive qualifications, stranding legacy extrusion assets in Japan and the US.
- Solid-state electrolyte timelines:Oxide and sulfide ceramic electrolyte maturation threatens to eliminate conventional microporous separator demand entirely by the mid-2030s.
Strategic Opportunities
- Indian cell manufacturing:PLI scheme incentives for ACC battery plants create first-mover advantage for separator suppliers establishing local coating operations.
- Stationary storage thermal management:Grid-scale lithium iron phosphate systems specify thicker ceramic-coated separators that command margin premiums over automotive grades.
- EU Battery Regulation traceability:Digital product passport requirements favor suppliers with integrated resin-to-film documentation systems.
Industry Challenges
- Thin-film metrology expertise:Sub-16 micron coating uniformity requires specialized gauging instrumentation that few quality engineering teams currently possess.
- Dual certification timelines:Simultaneous IEC 62660 and UN 38.3 testing protocols extend qualification cycles by 8-14 months for new separator grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Battery Separator Films Market |
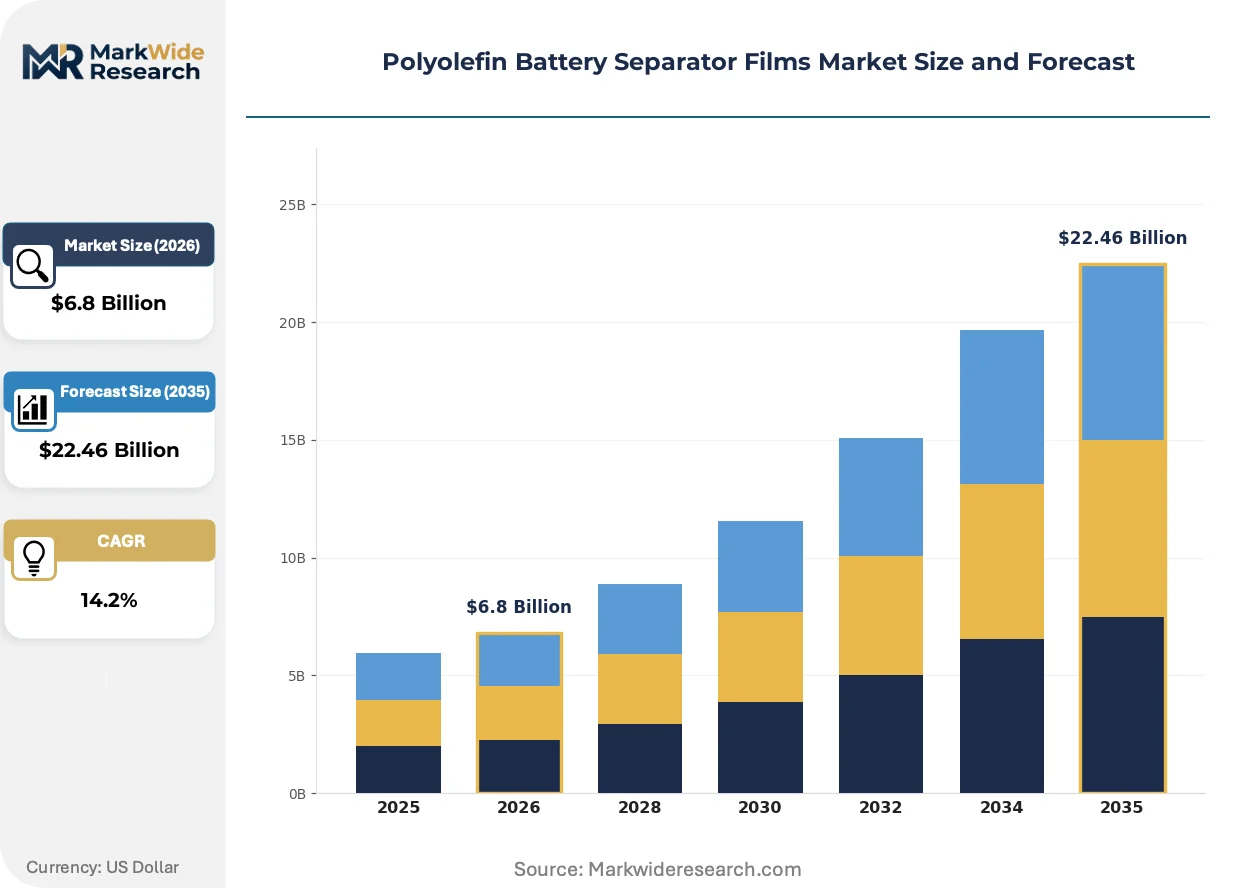
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Laminated, Coated Thickness: 25 Micron, 30 Micron, 40 Micron, 50 Micron End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Application: Li-ion Batteries, Lead-acid Batteries, Hybrid Batteries, Others |
| Companies Covered | SK ie technology, UBE Corporation, Toray Industries, W-Scope Corporation, Freudenberg Performance Materials, Asahi Kasei Corporation, ENTEK International, Shanghai Energy New Materials Technology, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Battery Separator Films Market Evolving Landscape
Separator architecture is bifurcating along performance tiers as automotive cell designs diverge from consumer electronics specifications. This technical stratification is compressing the addressable market for commodity-grade uncoated films while expanding premium coating capacity.
Ceramic-polymer hybrid coatings are unifying thermal shutdown protection with mechanical puncture resistance in single-layer architectures. Korean cell makers specify these grades for 800V platform batteries where dendrite penetration risks intensify. The technology is unifying what previously required separate substrate and safety layer procurement decisions.
REACH SVHC disclosure requirements are forcing resin suppliers to document phthalate and halogen content across polyolefin feedstock streams. European importers now demand batch-level chemical analysis certificates that most Asian compounders cannot provide without laboratory infrastructure investment. Separator manufacturers serving Mercedes-Benz and BMW facilities in Germany and Hungary face the steepest compliance ramps.
Cell makers are consolidating vendor panels from six-plus qualified sources to two or three strategic partnerships with volume commitments. SK On and Samsung SDI have both moved to sole-source ceramic-coated separators for flagship EV platforms, displacing spot-market purchasing. This concentration is most visible in South Korea's integrated battery corridor where separator suppliers co-locate coating lines adjacent to electrode production.
Polyolefin Battery Separator Films Market Segmentation
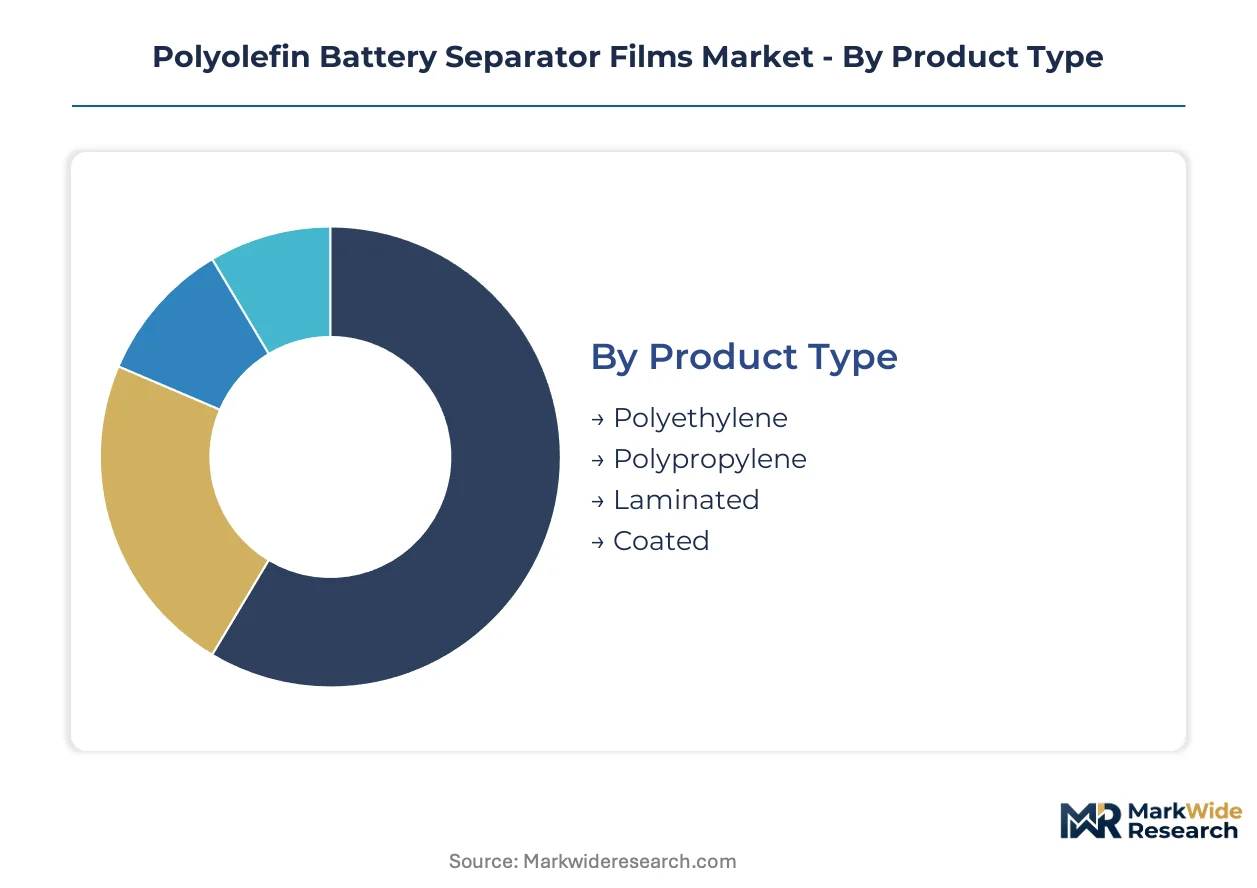
Polyolefin battery separator films segment along material chemistry, physical dimensions, and end-use specifications that dictate thermal stability requirements. Each dimension creates distinct margin profiles and qualification barriers that reshape supplier competitive positioning.
Product Type:
Upgrade cycles from uncoated to ceramic-coated architectures are compressing procurement timelines as automotive OEMs mandate thermal runaway containment.
- Polyethylene:Wet-process ultra-high molecular weight PE delivers sub-20 micron substrates with uniform pore distribution. Automotive cell-to-pack designs concentrate demand in South Korea where SK On and Samsung SDI specify PE bases for 800V platforms.
- Coated:Ceramic-polymer hybrid layers unify thermal shutdown with mechanical puncture resistance in single-layer stacks. China's NMPA thermal abuse mandates accelerate specification upgrades across domestic cell production lines.
- Polypropylene:Dry-process biaxially stretched PP retains cost advantage in stationary storage applications with thicker film tolerances.
- Laminated:PE-PP multilayer constructions balance shutdown temperature with mechanical integrity for premium automotive grades.
Polyethylene sits at the top of the volume ranking, with coated climbing the fastest.
Thickness:
Cost tiers separate automotive specifications demanding mechanical precision from industrial applications tolerating thicker, lower-unit-cost films.
- 25 Micron:Wet-process lines achieve thickness uniformity critical for high-nickel cathode cells. Korean integrated battery corridors anchor procurement volume for 800V EV platforms.
- 30 Micron:Balances energy density gains against manufacturing yield in mid-range automotive cell designs. Chinese cell makers specify this grade for LFP packs in mass-market EVs.
- 40 Micron:Grid-scale lithium iron phosphate stationary storage systems specify thicker ceramic-coated separators commanding margin premiums.
- 50 Micron:Lead-acid battery retrofits and industrial forklift applications sustain demand for commodity-grade uncoated films.
25 micron dominates automotive procurement volume, with 40 micron gaining share fastest in stationary storage.
End User:
Application maturity diverges sharply between saturated consumer electronics and expansion-phase automotive electrification.
- Automotive:Cell-to-pack architectures require thinner, mechanically robust films that wet-process lines deliver. OEM consolidation around ceramic-coated stacks compresses vendor panels to two or three strategic partnerships.
- Consumer Electronics:Smartphone and laptop specifications remain locked at 12-16 micron thicknesses with mature procurement patterns.
- Renewable Energy:Grid-scale battery installations specify thicker separators with enhanced thermal management for 20-year operational lifecycles.
- Industrial:Forklift and material handling equipment sustains demand for commodity-grade uncoated films with less stringent safety requirements.
Automotive commands the steepest expansion trajectory, with renewable energy climbing fastest behind it.
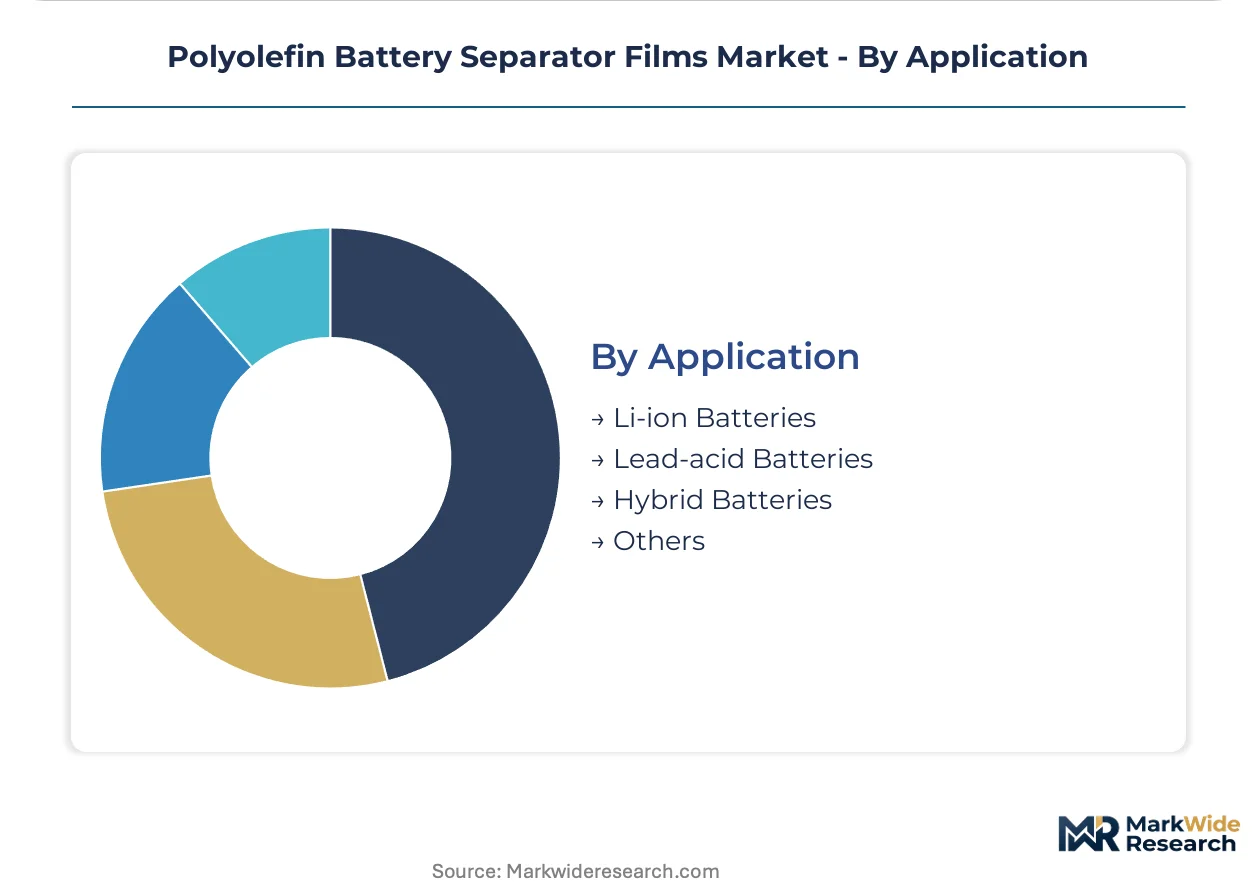
Application:
Customer type segmentation separates qualification-intensive lithium-ion supply chains from legacy lead-acid replacement markets.
- Li-ion Batteries:NMC and LFP chemistries drive specification diversity across automotive and stationary storage. EU Battery Regulation traceability requirements favor suppliers with integrated resin-to-film documentation.
- Lead-acid Batteries:Mature replacement market tolerates thicker, lower-cost separators with minimal coating requirements.
- Hybrid Batteries:Dual-chemistry systems create intermediate specification demands bridging conventional and solid-state transition timelines.
- Others:Emerging sodium-ion and solid-state prototypes require separator architecture modifications still in qualification phases.
Li-ion batteries sit at the top of the volume ranking, with hybrid batteries climbing the fastest as dual-chemistry platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with lower compliance costs for ceramic-coated separator qualification. China's NMPA mandates and the EU Battery Regulation create divergent cost-of-compliance landscapes that favor integrated Asian supply corridors over fragmented Western capacity.
China
Domestic cell makers Ningde and BYD are scaling wet-process separator procurement for LFP and high-nickel platforms. NMPA thermal abuse testing mandates favor ceramic-coated architectures over uncoated alternatives. The Yangtze River Delta cluster around Shanghai anchors coating capacity expansion adjacent to electrode production lines.
South Korea
SK On and Samsung SDI have consolidated vendor panels to two strategic separator partnerships with volume commitments. KATS alignment with IEC 62660 protocols creates harmonized certification burdens for regional exporters. The integrated battery corridor between Seoul and Ulsan co-locates separator coating operations with cell assembly facilities.
Japan
Toray Industries and Asahi Kasei leverage biaxial stretching expertise to dominate premium ceramic-coated grades for automotive OEMs. METI battery supply chain resilience programs subsidize domestic separator capacity retention. The Nagoya-Osaka industrial belt concentrates wet-process R&D alongside petrochemical feedstock integration.
Germany
Mercedes-Benz and BMW procurement teams enforce REACH SVHC disclosure requirements that strain Asian compounder documentation capabilities. The EU Battery Regulation's digital product passport mandates favor suppliers with integrated resin-to-film traceability systems. The Stuttgart-Munich corridor hosts qualification laboratories for automotive-grade separator testing.
United States
IRA domestic content bonuses for battery cell production are pulling separator coating investments toward Michigan and Ohio assembly zones. NHTSA battery safety guidance aligns with UN 38.3 testing protocols that extend qualification cycles. The Great Lakes industrial corridor is attracting Korean and Japanese separator makers seeking tariff-advantaged supply positions.
Polyolefin Battery Separator Films Market Competitive Landscape
East Asian producers anchor the premium ceramic-coated tier; European and North American specialists hold residual positions in industrial-grade uncoated films. Market structure concentrates around integrated petrochemical-to-film players with captive polypropylene supply chains. Three archetypes dominate: Korean chaebol-affiliated separators with domestic cell-maker partnerships, Japanese diversified chemical conglomerates with biaxial stretching heritage, and Chinese state-linked entities scaling wet-process capacity. Competitive moves center on M&A for coating technology access and parallel extrusion-coating capacity reconfiguration.
Among Japanese diversified chemical groups, Asahi Kasei Corporation and Toray Industries exemplify the premium-tier archetype through biaxial stretching heritage. SK ie technology represents the Korean chaebol-affiliated model with integrated domestic cell-maker relationships. These three entities occupy positions that mirror the geographic split between Japanese technical specialization and Korean supply-chain integration.
| Leading Market Players |
|---|
| SK ie technology |
| UBE Corporation |
| Toray Industries |
| W-Scope Corporation |
| Freudenberg Performance Materials |
| Asahi Kasei Corporation |
| ENTEK International |
| Shanghai Energy New Materials Technology |
| Sumitomo Chemical |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement consolidation around ceramic-coated architectures anchors contract-based long-term offtake pricing. Tier 1 cell makers negotiate volume commitments that compress spot-market exposure for integrated separator suppliers.
Pricing Analysis
Distributor margins for commodity-grade uncoated films compress against direct-to-OEM contract discounts for ceramic-coated grades. Three-tier pricing structure across premium, standard, and economy levels separates automotive qualification-intensive specifications from industrial lead-acid retrofits. Pricing pressure stems from oil-indexed polypropylene resin volatility that squeezes wet-process line economics. Mass-market LFP cell makers exhibit highest price sensitivity, while 800V platform OEMs accept premium tiers for thermal shutdown reliability.
Supply Chain Analysis
Single-source vulnerability sits with Korean petrochemical clusters feeding captive polypropylene streams to integrated separator producers. Manufacturing concentrates in China, South Korea, and Japan where wet-process extrusion and ceramic coating capacity co-locates with electrode production. Raw material dependencies span ultra-high molecular weight polyethylene resin, ceramic oxide powders, and PVDF binder systems. Tariff exposure on Chinese-coated separator imports into the EU and US threatens cost competitiveness. Distribution runs through just-in-time supply corridors linking coating facilities to cell assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive cell designs bifurcate toward ceramic-coated thermal management specifications. OEM consolidation around two-to-three vendor panels rewards incumbents with qualification heritage and stranded capital risks for commodity-grade specialists.
For Market Incumbents: Extend ceramic coating capacity adjacent to Korean and Chinese electrode production corridors to defend share against emerging Chinese state-linked wet-process scale players. Deepen backward integration into polypropylene resin streams to buffer oil-indexed feedstock volatility. Prioritize IEC 62660 and UN 38.3 dual certification investment to compress qualification cycles for new separator grades. For New Entrants and Emerging Players: Launch via Indian PLI scheme-linked coating operations targeting ACC battery plant procurement windows before incumbent Korean and Japanese suppliers establish local footprints. White-space concentration sits with stationary storage LFP systems specifying 40-micron ceramic-coated separators commanding margin premiums over automotive grades. Pursue grid-scale battery integrators as anchor customers to bypass automotive qualification barriers. For Investors and Strategic Acquirers: Korean chemical conglomerates and Chinese battery material platforms are the most active acquirers in this space, seeking coating technology access and captive separator supply. Long-term viability hinges on 5-10 year solid-state electrolyte transition timelines that threaten conventional microporous demand. Monitor oxide and sulfide ceramic electrolyte maturation signals as inflection indicators for separator demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | UBE Corporation's captive feedstock streams compress working capital cycles against oil-indexed volatility. |
| Ceramic Coating Capacity Expansion | SK ie technology co-locates coating lines with Samsung SDI electrode production to enforce just-in-time supply. |
| Dual Certification Investment | Asahi Kasei accelerates IEC 62660 and NMPA thermal abuse testing to qualify for Chinese EV platform procurement. |
| Geographic Manufacturing Footprint | Japanese suppliers leverage METI supply chain resilience subsidies to retain domestic wet-process R&D capacity. |
| Long-term Supply Agreement | Toray Industries locks in Mercedes-Benz and BMW procurement through REACH-compliant batch-level documentation systems. |
Research Methodology
Multiple input streams — technical interviews with separator plant managers, procurement leads at Korean cell makers, ceramic oxide powder suppliers, and distribution channel partners — were reconciled against customs trade data, Korean petrochemical association reports, SEC 10-K filings, and NMPA regulatory bulletins. Bottom-up capacity buildouts by wet-process line and top-down automotive cell demand projections were cross-validated to anchor volume estimates.
Data-stream reconciliation across product type, thickness segment, end-use vertical, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EV platform battery capacity announcements, solid-state electrolyte development timelines, and ceramic coating yield improvement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated solid-state battery commercialization or polypropylene feedstock price spike scenarios. Forecasts reflect documented assumptions regarding separator thickness migration patterns and automotive OEM vendor panel consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Specialty Films Polymer Market
Poly film
MOPP Packaging Films Market
Poly film
Tube Laminating Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polycarbonate Films Market
Poly film
Easy Peel Film Packaging Market
Poly film
Germany Plastic Packaging Films Market
Poly film
China BOPP Film Market
Poly film
MDO-PE Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Timber Wrap Films Market
Poly film
Polyester Film Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
United Kingdom Plastic Packaging Films Market