
 Blow Moulded Plastic Packaging Market | 2026-2036
Blow Moulded Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Blow Moulded Plastic Packaging Market Outlook
Contract packagers for pharmaceuticals and personal care brands are bifurcating from traditional food and beverage buyers as the fastest-growing demand archetype. Berry Global specializes in healthcare-compliant barrier bottles with multi-layer co-injection technology. Graham Packaging dominates North American dairy and juice container supply through its captive blow molding network. ALPLA extends its position via in-house rPET flake production integrated across European and Latin American plants.
Blow moulded plastic packaging denotes hollow thermoplastic articles formed by extruding or injecting a molten polymer parison into a cooled split mold, then inflating it with compressed air to achieve wall thicknesses between 0.25 mm and 2.5 mm depending on structural requirements; this process yields seamless, lightweight vessels engineered for containment, distribution, and shelf display of liquids, powders, and semi-solids. Bottles capture the dominant volume share across food, beverage, and personal care applications due to their versatility in neck finish standardization and label adhesion surfaces. Containers for industrial chemicals and pharmaceutical intermediates command premium pricing through UN-certified stacking strength and child-resistant closure compatibility. Jars in the cosmetics segment compete through thick-walled clarity and offset-printed decoration that signals brand positioning at point of sale.
The FDA enforces food-contact notification requirements for virgin and recycled resins used in blow moulded packaging, while the EPA regulates volatile organic compound emissions from extrusion blow molding operations under Clean Air Act standards; REACH in Europe restricts phthalate plasticizers and mandates substance registration for imported packaging articles, reshaping material selection for exporters serving dual markets. Stakeholders must monitor evolving extended producer responsibility schemes and recyclability labeling mandates to preempt compliance-driven redesign cycles and secure preferred supplier status with sustainability-focused retail procurement teams.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing a material transition across blow moulded packaging supply chains, compressing virgin resin demand while elevating post-consumer recycled flake and bio-based alternatives as primary feedstocks for compliant production.
Growth Catalysts
- EU Green Deal packaging mandates:Mandatory recycled content thresholds for beverage bottles are pulling investment into rPET flake washing and extrusion infrastructure across Germany, France, and Italy.
- Pharmaceutical barrier specifications:Multi-layer co-injection blow molding for moisture-sensitive drug formulations is expanding contract packaging demand from CDMOs and specialty pharma brands.
- India domestic manufacturing clusters:PLI scheme incentives for packaging materials are drawing blow molding equipment and resin compounding capacity to Gujarat and Maharashtra industrial corridors.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in Southern and Eastern Europe limit flake availability, forcing converters to absorb premium pricing or blend down ratios below compliance thresholds.
- Polyolefin price volatility:Ethane and naphtha feedstock swings tied to Gulf Coast petrochemical outages transmit directly to HDPE and PP blow molding resin costs.
- Mechanical recycling degradation:PET chain scission through repeated thermal processing constrains food-contact approval for high-percentage recycled content in sensitive applications.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and glycolysis routes to virgin-quality PET and polyolefin feedstocks are opening food-contact pathways that mechanical methods cannot satisfy.
- Refill station infrastructure:Concentrated retail networks in Germany and Scandinavia are normalizing bulk dispensing formats that favor standardized, durable blow molded returnable bottles.
- Digital watermarks and AI sorting:HolyGrail 2.0 pilot deployments across France and Denmark are improving post-consumer package identification, directly boosting rPET yield rates for bottle-to-bottle recycling.
Industry Challenges
- Food-contact notification timelines:FDA and EFSA parallel review processes for novel bio-based resins extend qualification cycles to 18-24 months, delaying commercial launches.
- Multi-layer delamination in recycling streams:EVOH and PA barrier layers in pharmaceutical and cosmetic bottles complicate mechanical recycling, requiring design-for-recycling retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow Moulded Plastic Packaging Market |
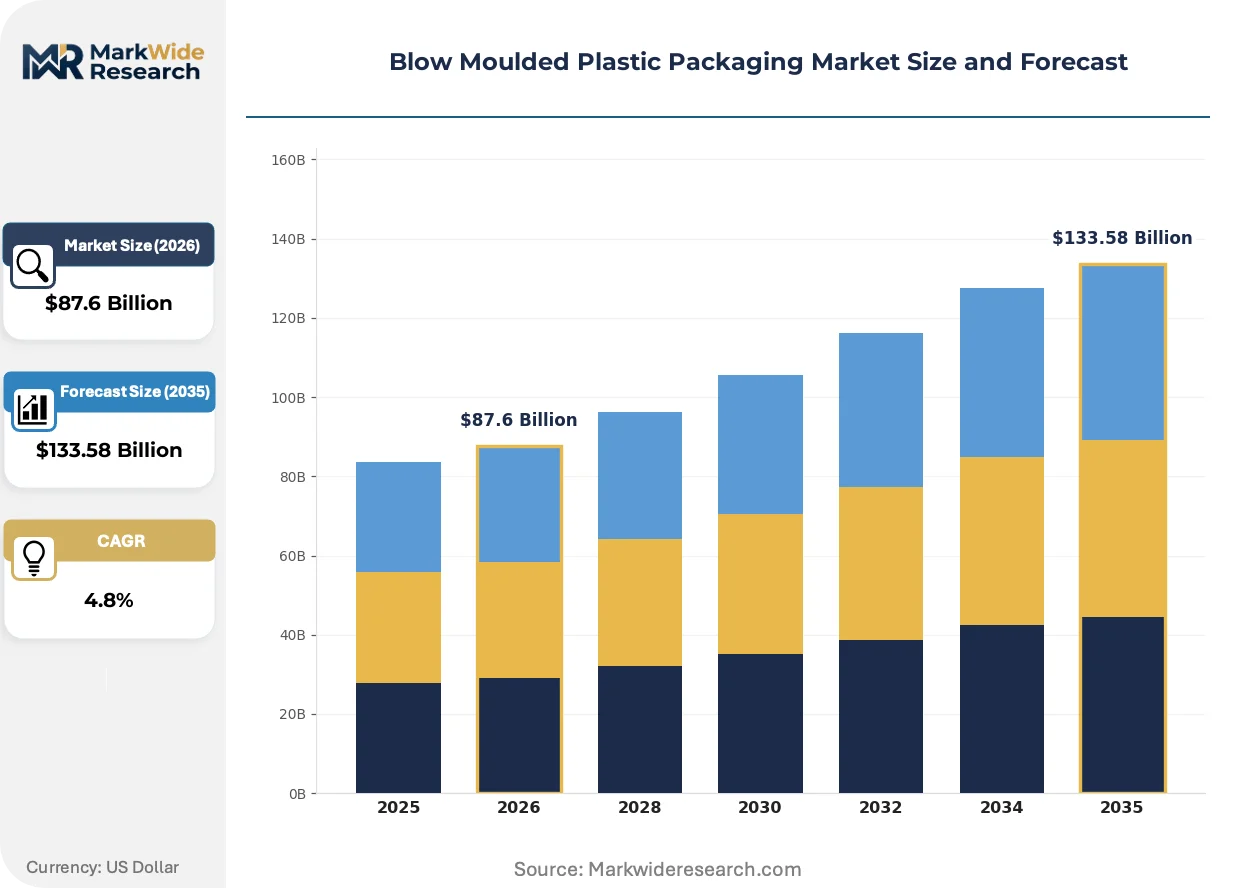
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Blisters Application: Food & Beverage, Personal Care, Pharmaceuticals, Industrial End User: Manufacturers, Retailers, Distributors, E-commerce Material: PE, PP, PVC, PET |
| Companies Covered | Amcor, Berry Global, Graham Packaging, ALPLA, Plastipak Holdings, Alpha Packaging, Comar, Resilux, Apex Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow Moulded Plastic Packaging Market Strategic Shifts
Active and intelligent packaging integration, coupled with closed-loop recycling system buildouts, is reconfiguring how blow molded containers are specified, tracked, and recovered across their lifecycle.
Digital printing on blow molded bottles is fragmenting the dominance of pressure-sensitive labels and shrink sleeves. Beverage and personal care brands in the UK and Netherlands are adopting direct-to-shape inkjet for SKU proliferation and regional customization. This technology is compressing minimum order quantities and enabling micro-batch production runs that were previously uneconomical at blow molding scale.
REACH restrictions on intentionally added microplastics are reshaping material selection for personal care packaging. The European Chemicals Agency's 2023-2027 implementation timeline is accelerating substitution of conventional glitter and exfoliant carriers with biodegradable alternatives. Cosmetic blow molders serving EU markets are reformulating masterbatches and validating new additive packages ahead of enforcement deadlines.
Concentrated refill formats are displacing unit-dose primary packaging in household cleaning and personal care. Unilever and Henkel pilot programs in Germany and France are normalizing 10x concentrate pods paired with durable blow molded dispenser bottles. This model is visible most acutely in German drugstore and supermarket chains, where shelf space allocation now favors permanent bottle-plus-refill systems over traditional single-use formats.
Blow Moulded Plastic Packaging Market Segmentation
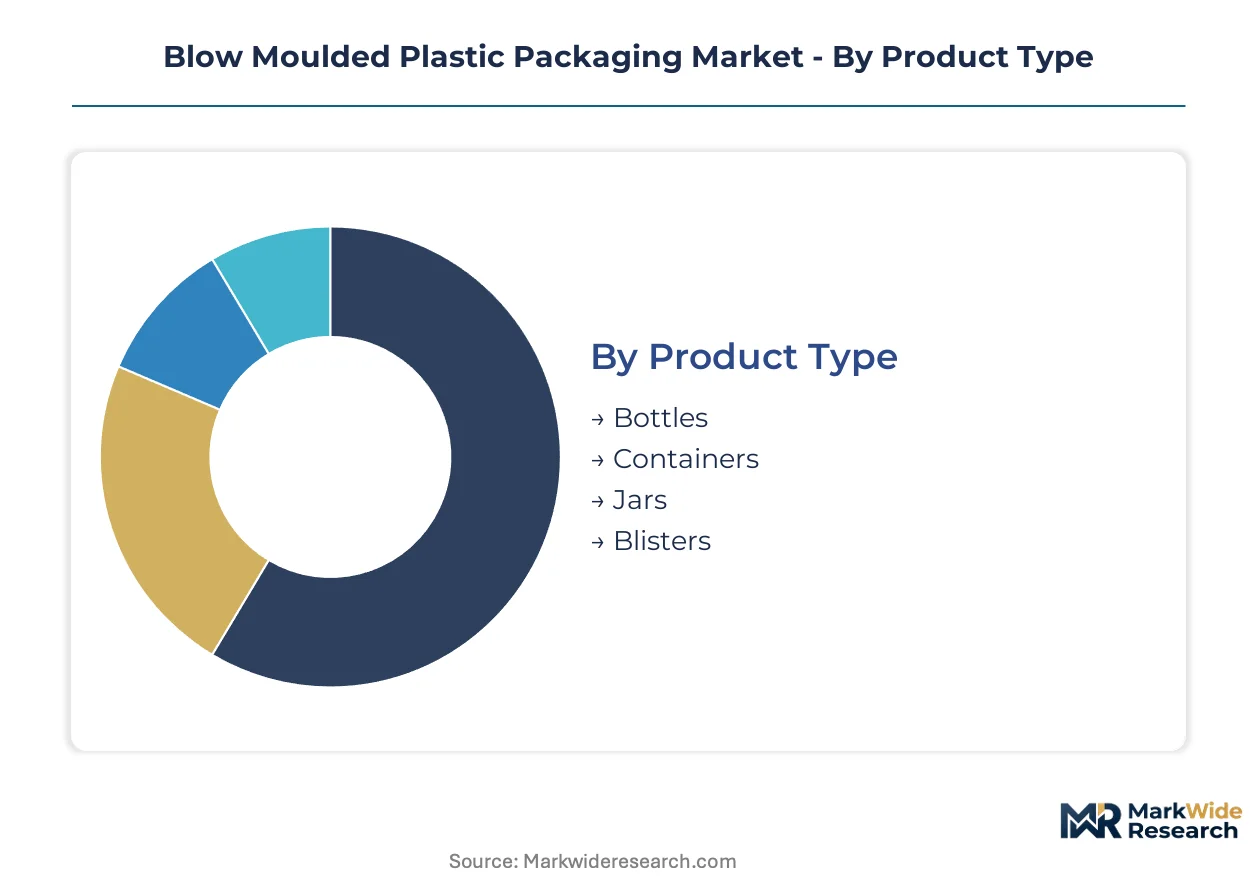
Blow moulded plastic packaging serves distinct functional requirements across liquid containment, shelf display, and barrier protection. Channel economics and regulatory compliance reshape how each segment is specified, produced, and recovered.
Product Type:
Channel mix varies sharply: bottles and containers flow predominantly through retail and foodservice distribution, while jars and blisters concentrate in pharmacy and beauty specialty channels.
- Bottles:Seamless hollow vessels with standardized neck finishes dominate liquid containment across beverages, dairy, and household chemicals. Demand concentrates in Asia-Pacific manufacturing clusters where expanding domestic consumption and export-oriented production draw multilayer co-investment from converters in China and India.
- Containers:Rectangular and cylindrical formats engineered for stacking strength and UN-certified hazardous material transport command premium positioning. Industrial chemical and pharmaceutical intermediate applications in Germany and the United States drive specification for EVOH barrier layers and child-resistant closure compatibility.
- Jars:Wide-mouth thick-walled formats compete through clarity and decoration in cosmetics.
- Blisters:Thermoformed cavity formats with lidding seal surfaces serve unit-dose pharmaceuticals.
Bottles dominate installed base. Containers are where expansion concentrates.
Application:
Cost tier stratification separates commodity food-grade specifications from premium healthcare-compliant barriers.
- Food & Beverage:Single-serve and family-size formats for carbonated drinks, juices, and edible oils represent the volume anchor. rPET integration accelerates fastest here as EU Green Deal mandates force post-consumer recycled content thresholds across German, French, and Italian beverage supply chains.
- Personal Care:Shampoo, conditioner, and lotion bottles prioritize shelf differentiation through shape innovation and surface decoration.
- Pharmaceuticals:Moisture-sensitive drug formulations require multi-layer co-injection technology with desiccant integration.
- Industrial:Chemical resistance and drop-test certification dominate specification.
Food & Beverage anchors production volume. Pharmaceuticals is climbing the fastest on contract packaging demand from CDMOs.
End User:
Customer type determines order economics and customization depth across the value chain.
- Manufacturers:Brand owners and contract packagers specify primary packaging with direct converter relationships.
- Retailers:Private-label procurement teams drive standardization and cost compression.
- Distributors:Industrial and institutional channels aggregate fragmented demand.
- E-commerce:Durable secondary packaging requirements reshape primary bottle specifications for drop-test performance.
Manufacturers control specification authority. E-commerce is gaining share fastest on fulfillment durability demands.
Material:
Supply concentration and recycling infrastructure maturity differentiate resin economics.
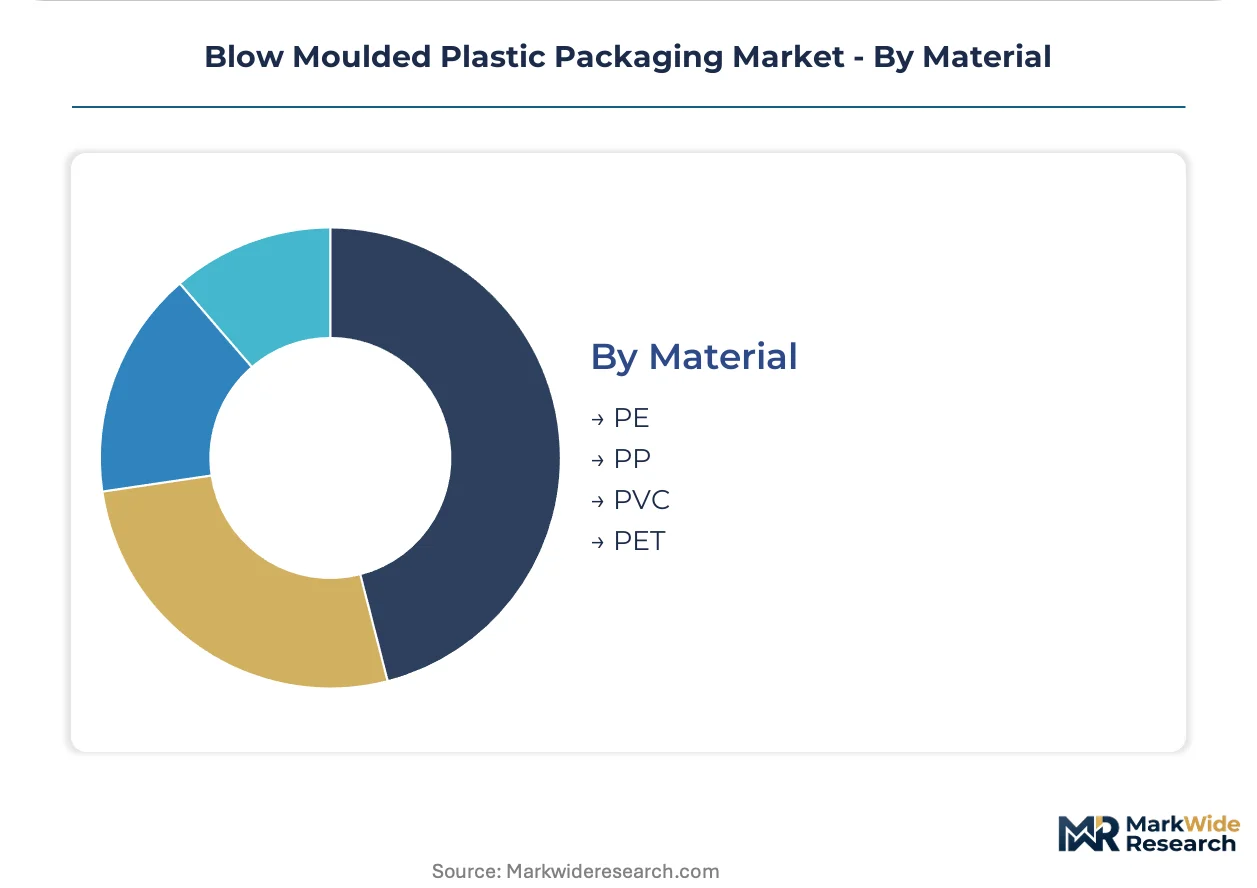
- PE:HDPE and LDPE grades dominate milk bottles and industrial drums with established mechanical recycling streams.
- PP:High clarity and chemical resistance serve pharmaceutical and cosmetic applications.
- PVC:Declining share in food contact on regulatory pressure; persists in industrial and medical niches.
- PET:Bottle-to-bottle recycling leadership and rPET flake availability make this the pivot material for EU compliance.
PET leads circular economy investment. PP is expanding most quickly on pharmaceutical barrier specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Installed blow molding capacity clusters in China, Germany, and the United States, with emerging conversion investment accelerating in India and Brazil as domestic consumption scales and export positioning strengthens.
China
Beverage brand localization and dairy sector expansion drive container demand across Zhejiang and Guangdong provinces. The Ministry of Ecology and Environment enforces dual carbon goals that compress virgin resin permits while elevating rPET infrastructure mandates. Yangtze River Delta manufacturing corridors host multilayer co-investment from converters scaling food-grade barrier production for export markets.
Germany
Pharmaceutical contract packaging and concentrated refill formats pull specialized barrier specifications from CDMOs and FMCG brands. The EU Green Deal packaging mandates enforce 25% recycled content thresholds for PET beverage bottles from 2025. North Rhine-Westphalia chemical parks integrate pyrolysis pilots with existing resin compounding infrastructure to secure food-contact compliant feedstocks.
United States
E-commerce fulfillment durability requirements and dairy processor consolidation reshape primary bottle specifications across Midwest and Southeast distribution networks. FDA food-contact notification timelines extend qualification cycles for novel bio-based resins to 18-24 months. Gulf Coast petrochemical corridors transmit ethane feedstock volatility directly into HDPE and PP blow molding resin contract pricing.
India
Expanding middle-class consumption and edible oil processor investment drive single-serve and family-size format demand. The PLI scheme for packaging materials draws blow molding equipment and resin compounding capacity to Gujarat and Maharashtra industrial corridors. Mumbai-Pune manufacturing clusters attract multinational converter joint ventures targeting domestic FMCG supply and Middle East export positioning.
Brazil
Personal care brand localization and household chemical processor expansion sustain container demand despite macroeconomic headwinds. ANVISA pharmaceutical packaging regulations align with FDA stability study requirements for moisture-sensitive drug formulations. São Paulo state industrial districts concentrate blow molding conversion capacity serving Mercosur distribution networks.
Blow Moulded Plastic Packaging Market Competitive Environment
Concentration sits with integrated resin-to-package converters and specialized healthcare barrier specialists, with mid-tier regional fabricators occupying fragmented niches in emerging markets. Two strategic archetypes dominate: multinational resin-integrated players controlling flake-to-bottle supply chains, and healthcare-focused specialists commanding premium positioning through multi-layer co-injection technology. Dominant competitive moves include backward integration into rPET flake washing infrastructure and geographic expansion through joint ventures in Indian and Brazilian manufacturing corridors.
Within the integrated multinational tier, Amcor and Berry Global exemplify archetypes spanning healthcare barrier specialization and resin-integrated circular supply chains. ALPLA occupies a position between these models through in-house rPET flake production across European and Latin American plant networks. Graham Packaging represents the North American dairy and juice container specialist archetype through captive blow molding network density.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Graham Packaging |
| ALPLA |
| Plastipak Holdings |
| Alpha Packaging |
| Comar |
| Resilux |
| Apex Plastics |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day rPET flake procurement lead times concentrate pricing power with converters controlling in-house washing infrastructure, while buyers without captive flake supply absorb volatility from European collection infrastructure gaps. This inventory compression cascades through to finished bottle pricing, where EU Green Deal compliance thresholds reshape contract negotiations between brand owners and resin-integrated suppliers.
Pricing Analysis
The EU Green Deal packaging mandates dictate the pricing tier structure across blow moulded packaging supply chains, with three-tier pricing separating pharmaceutical barrier specifications from commodity food-grade bottles and economy industrial formats. Price differentiation rests on certification grade—FDA food-contact notification tiers versus standard industrial specifications—and volume scale, with dairy processor consolidation in the United States compressing minimum efficient scale thresholds. Cost compression in standard food-grade PET bottles is intensifying because rPET feedstock scarcity forces converters to absorb premium flake pricing or blend down below compliance thresholds. Private-label procurement teams at European retailers exhibit the highest price sensitivity, while pharmaceutical CDMOs prioritize barrier performance over unit cost.
Supply Chain Analysis
Forty-five-day virgin resin inventory cycles at Yangtze River Delta converters anchor supply responsiveness to Gulf Coast petrochemical corridor disruptions. Geographic supply concentration centers on China, Germany, and the United States for installed blow molding capacity, with emerging conversion investment accelerating in India and Brazil. Raw material dependencies draw from ethane and naphtha feedstocks for polyolefin resins, rPET flake from European collection networks, and bio-based resin pilot volumes from North Rhine-Westphalia chemical parks. Single-source vulnerability runs through mechanical recycling degradation constraints that limit food-contact approval for high-percentage recycled content. Distribution feeds from converter direct sales to brand owner procurement teams, with industrial chemical channels aggregating through specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in blow moulded packaging are expanding faster than container hardware, with rPET flake supply contracts and digital watermark tracking systems emerging as recurring-revenue layers that deepen converter-customer relationships beyond transactional bottle supply.
For Market Incumbents: Fortify barrier technology differentiation against emerging chemical recycling entrants by deepening multi-layer co-injection expertise for pharmaceutical applications, while securing backward integration into rPET flake washing infrastructure to defend margin position against feedstock volatility. Capacity addition in Gujarat and Maharashtra industrial corridors captures PLI scheme incentives before multinational joint ventures saturate domestic Indian supply. For New Entrants and Emerging Players: FDA food-contact notification fast-tracks for novel bio-based resins open white-space positioning ahead of 18-24 month qualification cycles that delay incumbent launches. Target concentrated refill station infrastructure in German and Scandinavian retail networks, where standardized returnable bottle formats favor agile converters over resin-integrated giants. Go-to-market leverage rests on digital printing partnerships enabling micro-batch SKU proliferation for regional beverage brands. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because EU extended producer responsibility schemes and recyclability labeling mandates are restructuring competitive advantage around flake-to-bottle supply chain control rather than molding equipment scale. Acquisition targets should screen for in-house rPET washing capacity and pharmaceutical barrier certification tiers. The signal to watch is chemical recycling pyrolysis pilot yields achieving food-contact parity with virgin resin, which would reset mechanical recycling's constrained positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Washing | Captures EU Green Deal compliance premiums by securing food-grade recycled feedstock supply. |
| Multi-Layer Co-Injection Capacity Expansion | Serves pharmaceutical CDMO contract packaging demand for moisture-sensitive drug formulations. |
| Digital Watermark Technology Deployment | Aligns with HolyGrail 2.0 pilot standards to boost post-consumer package identification yields. |
| Concentrated Refill Format Partnerships | Locks in durable bottle supply agreements with Unilever and Henkel German pilot programs. |
| Joint Venture in Indian Manufacturing Corridors | Accesses PLI scheme incentives and positions for Middle East export market expansion. |
Study Parameters
The analysis maps blow molding equipment tiers, resin grade specifications, and barrier technology categories, each validated through converter procurement directors, brand owner packaging engineers, and regulatory affairs specialists at multinational suppliers. Primary fieldwork combined structured interviews with secondary validation against customs trade data, FDA food-contact notification filings, EU Green Deal implementation directives, and SEC disclosures from resin-integrated packaging conglomerates. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-verify volume estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with segmentation dimensions spanning product type, application vertical, material resin, and regional production hub. CAGRs were derived from installed capacity growth rates, end-use consumption elasticities, and regulatory compliance timeline impacts. Forecast inputs incorporated rPET flake availability constraints, pharmaceutical barrier specification expansion rates, and concentrated refill format adoption curves in German retail.
Underlying assumptions cover EU Green Deal recycled content threshold enforcement, PLI scheme incentive continuity in India, and mechanical recycling degradation limits for food-contact applications, with deviation risk concentrated in chemical recycling scale-up timelines and bio-based resin qualification delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Europe PET Packaging Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Reusable Plastic Water Bottles Market