
 Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market | 2026-2036
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market Foresight
Hospital procurement consolidation among integrated delivery networks is expanding the addressable base for non-invasive H. pylori testing across North America and Western Europe. Abbott Laboratories leverages its installed immunoassay platform base to sustain recurring revenue streams in high-throughput laboratories. Thermo Fisher Scientific anchors molecular diagnostics growth through PCR-based detection workflows. Meridian Bioscience competes on point-of-care accessibility with simplified specimen collection protocols.
Helicobacter pylori non-invasive testing encompasses diagnostic methods that detect active infection through breath, stool, or blood specimens without endoscopic tissue biopsy, typically measuring carbon isotope ratios in urea breath assays or H. pylori-specific antigens in fecal samples to confirm colonization status. These tests serve primary clinical purposes of initial infection diagnosis, treatment efficacy confirmation, and recurrence monitoring in dyspepsia and ulcer management. Urea breath testing leads the test type landscape due to superior sensitivity for active infection, while molecular diagnostics represents the fastest-expanding technology segment as laboratories adopt PCR workflows for antibiotic resistance profiling. Stool antigen testing occupies a mature margin pool in pediatric and primary care settings where breath collection proves impractical.
FDA premarket review pathways for in vitro diagnostics shape product entry timelines and clinical validation requirements for US manufacturers, while EMA's In Vitro Diagnostic Regulation enforces post-market surveillance and performance documentation across European markets. ISO 13485 quality management standards govern manufacturing consistency for global kit suppliers. Stakeholders must monitor evolving antimicrobial stewardship guidelines that tie H. pylori test reimbursement to resistance-guided therapy protocols.
Market Dynamics
Antimicrobial stewardship protocols are forcing diagnostic laboratories to pivot from empirical H. pylori treatment toward resistance-guided therapy, compressing demand for conventional serology while expanding molecular testing infrastructure. This structural shift rewards test manufacturers with PCR-based antibiotic susceptibility panels and penalizes legacy immunoassay suppliers lacking resistance profiling capability.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Post-market surveillance mandates under IVDR are accelerating laboratory consolidation toward standardized, CE-marked stool antigen and urea breath platforms that streamline procurement across European hospital networks.
- Pediatric dyspepsia protocols:Stool antigen testing is displacing endoscopy in children with recurrent abdominal pain, as breath collection proves impractical in this population and non-invasive alternatives reduce anesthesia exposure.
- Clarithromycin resistance surveillance:National health systems in Japan and Germany now mandate resistance testing prior to first-line triple therapy, creating institutional demand for molecular diagnostics integrated into treatment algorithms.
Market Restraints
- Reimbursement compression:Medicare and commercial payors in the United States have narrowed coverage for urea breath testing to post-treatment confirmation only, constraining initial diagnosis volumes and pressuring laboratory revenue per test.
- Isotope supply concentration:Carbon-13 urea production concentrates among three European chemical suppliers, exposing breath test manufacturers to input cost volatility and geographic supply disruption risk.
- Serology substitution threat:Low-cost antibody testing persists in resource-constrained settings despite inferior accuracy, diverting budget share from higher-value antigen and molecular alternatives in primary care.
Strategic Opportunities
- Point-of-care expansion in India:Underpenetrated rural clinic networks present white space for simplified stool antigen lateral flow devices that bypass cold-chain logistics and centralized laboratory infrastructure.
- Fluoropyrimidine resistance profiling:Convergent PCR and next-generation sequencing workflows enable simultaneous H. pylori detection and gyrA mutation analysis, supporting precision quadruple therapy selection in refractory infections.
- Direct-to-consumer channel emergence:Regulatory sandbox frameworks in Switzerland and the United Kingdom are permitting supervised home collection kits for stool antigen testing, opening patient-initiated diagnostic pathways outside traditional clinical channels.
Industry Challenges
- IVDR technical documentation burden:Small and mid-sized IVD manufacturers face 18-24 month certification timelines for performance evaluation studies under European notified body backlogs, delaying market entry.
- Laboratory information system integration:Molecular diagnostics platforms require HL7 FHIR connectivity upgrades that strain hospital IT capex budgets and extend sales cycles for diagnostic vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market |
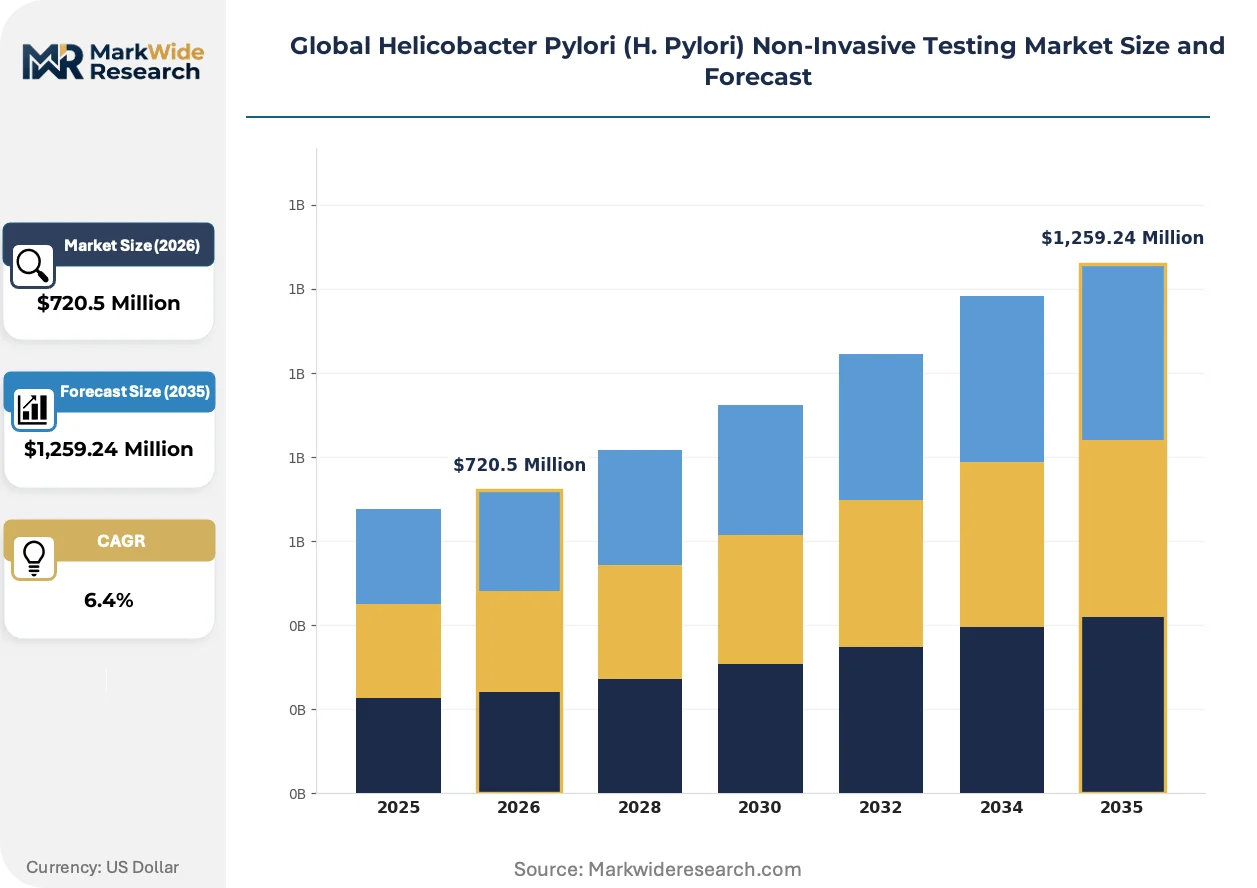
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,259.24 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Urea Breath Test, Stool Antigen Test, Serology Test, Molecular Test, Enzyme Immunoassay Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Chemiluminescence Immunoassay, Microarray-Based Diagnosis, Immunochromatographic Assay Clinical Application: Gastrointestinal Disorder Diagnosis, Peptic Ulcer Detection, Gastric Cancer Screening, Dyspepsia Evaluation, Chronic Gastritis Monitoring End User: Diagnostic Laboratories, Gastroenterology Clinics, Research Institutes, Specialized Testing Centers, Outpatient Care Facilities |
| Companies Covered | DiaSorin S.p.A., Meridian Bioscience Inc., Abbott Laboratories, Thermo Fisher Scientific, Bio-Rad Laboratories Inc., QuidelOrtho Corporation, Sekisui Diagnostics, Certest Biotec, Coris BioConcept, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market Shifts & Advancements
Digital PCR platforms are absorbing share from conventional quantitative PCR in reference laboratories, enabling absolute quantification of H. pylori load without calibration curves. This shift compresses turnaround time for resistance reporting while demanding new capital equipment commitments from hospital systems.
Digital PCR is absorbing the high-complexity molecular diagnostics segment as Thermo Fisher and bioMérieux deploy absolute quantification workflows that eliminate standard curve variability in H. pylori viral load assessment. Major academic medical centers in Germany and Japan are adopting these platforms for antibiotic resistance surveillance studies. The technology is absorbing capital budgets previously allocated to conventional real-time PCR systems, forcing mid-tier laboratories into rental or service contract models.
REACH regulation amendments governing fluorinated greenhouse gases are constraining availability of sulfur hexafluoride tracer compounds used in some specialized breath testing research applications. Industrial gas suppliers are reformulating tracer mixtures to maintain European market access. Urea breath test manufacturers with isotope-based alternatives face reduced competitive pressure from tracer-dependent methods in EU member states.
Hospital procurement departments are consolidating vendor contracts under integrated delivery network frameworks that bundle H. pylori testing with broader gastrointestinal diagnostic panels. This behavior compresses standalone test pricing while favoring suppliers with multi-analyte immunoassay menus. The United States exhibits the most advanced IDN concentration, with similar structures emerging in NHS England sustainability and transformation partnerships.
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market Segmentation
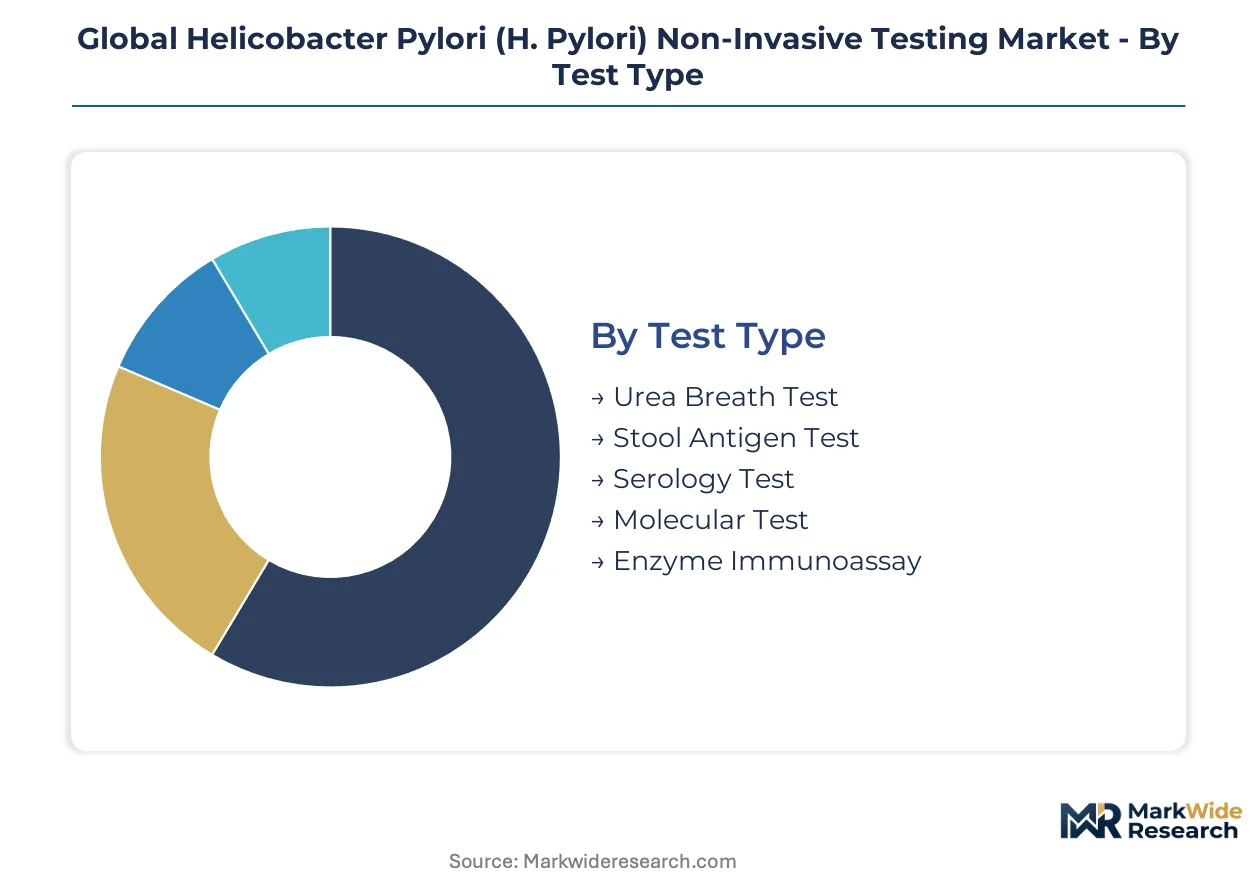
Segmentation in H. pylori non-invasive testing reveals distinct procurement patterns across test methodologies and care settings. Laboratories prioritize workflow integration and reimbursement alignment when selecting between breath, stool, and molecular platforms.
Test Type:
Urea breath and stool antigen tests anchor standalone diagnostic workflows, while serology and molecular methods embed into broader laboratory menus or specialized resistance panels.
- Urea Breath Test:Carbon-13 or carbon-14 isotope detection measures urease activity with high specificity for active infection. Demand concentrates in Germany and Japan where national guidelines mandate post-treatment confirmation via breath sampling. Reimbursement restrictions in the United States limit initial diagnosis use.
- Stool Antigen Test:Monoclonal antibody detection of H. pylori antigens in fecal specimens suits pediatric populations and primary care settings. Pediatric dyspexia protocols in France and Italy are displacing endoscopy with stool collection, reducing anesthesia exposure in children.
- Serology Test:IgG antibody detection persists in resource-constrained primary care despite inability to distinguish active from past infection.
- Molecular Test:PCR-based detection with simultaneous clarithromycin and fluoroquinolone resistance profiling supports precision therapy selection.
- Enzyme Immunoassay:Laboratory-based antigen detection offers batch processing efficiency for high-throughput reference laboratories.
Volume placements concentrate in stool antigen testing; the faster expansion belongs to molecular diagnostics with resistance profiling capability.
Technology:
Cost tiers separate capital-intensive molecular platforms from consumable-driven immunoassay workflows, with mid-tier laboratories facing equipment acquisition constraints.
- Polymerase Chain Reaction:Real-time and digital PCR enable absolute quantification of bacterial load with simultaneous antibiotic resistance mutation detection. Digital PCR absorption in German and Japanese academic centers is compressing turnaround times for surveillance studies.
- Enzyme-Linked Immunosorbent Assay:Microplate-based antibody detection dominates high-volume screening in centralized laboratories with established automation infrastructure.
- Chemiluminescence Immunoassay:Automated random-access analyzers deliver rapid turnaround for stool antigen detection in integrated delivery networks.
- Microarray-Based Diagnosis:Multiplexed resistance gene panels support epidemiological surveillance and outbreak investigation in reference laboratories.
- Immunochromatographic Assay:Lateral flow devices enable point-of-care deployment in outpatient settings with limited cold-chain requirements.
Installed base concentration favors chemiluminescence platforms; steepest expansion trajectory belongs to digital PCR for resistance-guided therapy protocols.
Clinical Application:
Application segmentation tracks disease severity progression, with screening applications commanding premium pricing and monitoring applications driving recurring test volume.
- Gastrointestinal Disorder Diagnosis:Initial dyspepsia workup represents the highest test volume indication across primary care and gastroenterology settings.
- Peptic Ulcer Detection:Confirmation testing in symptomatic patients drives urea breath and stool antigen utilization before and after eradication therapy.
- Gastric Cancer Screening:H. pylori detection in high-risk populations, particularly in Japan and South Korea, integrates into national screening programs with endoscopic follow-up protocols.
- Dyspepsia Evaluation:Functional dyspepsia differentiation from organic disease supports test-versus-treat strategies in cost-conscious healthcare systems.
- Chronic Gastritis Monitoring:Surveillance testing in persistent infection cases tracks treatment response and recurrence in specialized gastroenterology practices.
Procedure volume clusters around diagnosis and ulcer detection; cancer screening applications are climbing the fastest as risk-stratified protocols expand.
End User:
Customer type determines purchasing authority and workflow requirements, with integrated networks consolidating procurement across multiple test categories.
- Diagnostic Laboratories:High-throughput reference laboratories in the United States and Germany aggregate testing from multiple collection sites, prioritizing automation and LIS integration.
- Gastroenterology Clinics:Specialty practices perform on-site urea breath testing with immediate results, capturing reimbursement for both technical and professional components.
- Research Institutes:Academic medical centers in Japan and Germany deploy molecular platforms for antimicrobial resistance surveillance and novel biomarker discovery.
- Specialized Testing Centers:Dedicated gastrointestinal diagnostic facilities offer comprehensive testing menus with rapid turnaround commitments.
- Outpatient Care Facilities:Primary care and urgent care settings favor simplified stool antigen collection with courier transport to centralized laboratories.
Test volume concentrates in diagnostic laboratories; outpatient care facilities are gaining share fastest as point-of-care accessibility expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic demand concentrates in health systems with mature antimicrobial stewardship programs and established reimbursement for resistance-guided therapy. Japan, Germany, and the United States account for the majority of molecular diagnostics adoption, while India and Brazil represent expansion frontiers for simplified point-of-care protocols.
United States
Medicare reimbursement restrictions on urea breath testing for initial diagnosis have compressed laboratory revenue per test while redirecting volume toward stool antigen alternatives. FDA premarket review pathways for in vitro diagnostics extend product entry timelines, favoring established manufacturers with clinical validation resources. The Southeast and Midwest regions host the densest concentration of integrated delivery networks consolidating gastrointestinal diagnostic procurement.
Germany
National guidelines mandate clarithromycin resistance testing prior to first-line triple therapy, institutionalizing molecular diagnostics within treatment algorithms. EMA In Vitro Diagnostic Regulation enforcement accelerates laboratory consolidation toward CE-marked platforms with standardized performance documentation. Bavaria and Baden-Württemberg anchor academic medical center adoption of digital PCR for surveillance studies.
Japan
Gastric cancer screening programs integrate H. pylori detection with endoscopic follow-up protocols, driving premium pricing for high-sensitivity molecular methods. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance requirements. The Kanto region surrounding Tokyo concentrates reference laboratory capacity and pharmaceutical industry diagnostic partnerships.
India
Rural clinic networks present white space for lateral flow stool antigen devices that bypass cold-chain logistics and centralized laboratory infrastructure. CDSCO regulatory pathways for in vitro diagnostics are streamlining import substitution for domestic kit manufacturers. Maharashtra and Karnataka host emerging diagnostic distributors targeting tier-two city outpatient facilities.
Brazil
Primary care substitution of low-cost serology for antigen testing persists despite accuracy limitations, constraining premium test penetration. ANVISA medical device registration requirements create entry barriers for molecular platform suppliers without local representation. São Paulo and Rio de Janeiro concentrate private laboratory chains expanding gastrointestinal testing menus.
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue resistance profiling specialization and point-of-care accessibility. The vendor base stratifies across three archetypes: diversified diagnostics conglomerates with multi-analyte immunoassay menus, molecular specialists anchoring PCR-based antibiotic susceptibility workflows, and regional point-of-care suppliers with simplified specimen collection protocols. Competitive moves concentrate on strategic partnerships for laboratory information system integration and geographic licensing arrangements for isotope supply security.
Among diversified diagnostics conglomerates, Abbott Laboratories and Thermo Fisher Scientific exemplify scale-driven positioning with installed platform bases sustaining recurring revenue streams. Meridian Bioscience occupies a position within the accessibility-focused tier, representing point-of-care specialization with pediatric-friendly specimen collection protocols. DiaSorin S.p.A. anchors the European molecular diagnostics segment, exemplifying resistance-guided therapy alignment through PCR-based detection workflows.
| Leading Market Players |
|---|
| DiaSorin S.p.A. |
| Meridian Bioscience Inc. |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories Inc. |
| QuidelOrtho Corporation |
| Sekisui Diagnostics |
| Certest Biotec |
| Coris BioConcept |
| Others |
Supply & Pricing Matrix
Backward integration into isotope production by European breath test manufacturers anchors both supply security and premium pricing power for urea-based diagnostic platforms. This captive sourcing strategy insulates leading suppliers from carbon-13 urea volatility while supporting sustained margin structures in Germany and Japan where resistance-guided therapy mandates concentrate demand.
Pricing Analysis
Volume placements cluster in economy-tier stool antigen consumables while margins concentrate in premium molecular resistance panels. Three-tier pricing structure across premium, standard, and economy levels separates digital PCR antibiotic profiling from automated chemiluminescence platforms and basic lateral flow devices. Cost compression in the standard tier intensifies because integrated delivery networks bundle H. pylori testing into broader gastrointestinal panels. Primary care clinics exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to stewardship-mandated precision requirements.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping sourcing patterns for lateral flow kit components toward Maharashtra and Karnataka manufacturing clusters. Carbon-13 urea production draws from Germany, France, and the Netherlands; monoclonal antibody reagents rest on Chinese and South Korean bioproduction capacity. Single-source vulnerability concentrates in isotope enrichment facilities. Distribution runs through diagnostic laboratory networks and hospital procurement consortia with cold-chain requirements for molecular reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where digital PCR resistance profiling displaces conventional urea breath confirmation in stewardship-mature health systems. Molecular platforms are replacing legacy immunoassay workflows across Japan and Germany.
For Market Incumbents: To counter margin erosion from procurement consolidation, deepen installed platform connectivity through HL7 FHIR laboratory information system integration and secure multi-year reagent supply contracts with isotope producers in Germany and France. CE marking investment under IVDR technical documentation requirements anchors European market retention. For New Entrants and Emerging Players: Direct-to-consumer digital health channels in Switzerland and the United Kingdom offer the most penetrable entry route for supervised home collection stool antigen kits. Target rural Indian outpatient facilities with cold-chain-independent lateral flow devices. Telehealth platform partnerships enable patient-initiated diagnostic pathways outside traditional clinical channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified diagnostics conglomerates seeking molecular resistance profiling capability. The five-to-ten year viability window favors platforms with simultaneous detection and antibiotic susceptibility workflows. Watch clarithromycin resistance surveillance mandate expansion across OECD health systems as the inflection indicator for molecular diagnostics valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | CE marking pathways under EMA regulation secure European laboratory procurement access. |
| Isotope Supply Security Agreement | Long-term carbon-13 urea contracts with German and French chemical suppliers reduce input volatility. |
| Digital PCR Platform Deployment | Absolute quantification workflows in Japanese academic centers compress resistance reporting turnaround. |
| Point-of-Care Lateral Flow Expansion | Simplified stool antigen collection protocols penetrate Indian rural clinic networks. |
| Laboratory Information System Integration | HL7 FHIR connectivity upgrades anchor hospital system vendor consolidation decisions. |
Research Methodology
Multi-period observation of antimicrobial stewardship guideline adoption, reimbursement policy shifts, and molecular platform installation rates anchored the trend analysis, supplemented by interviews with diagnostic laboratory directors, hospital procurement managers, gastroenterology clinic administrators, and regulatory affairs specialists at IVD manufacturers. Secondary validation drew from FDA premarket notification databases, EMA IVDR performance documentation, Japanese PMDA medical device registrations, and CMS Medicare coverage determinations. Bottom-up test volume modeling and top-down market sizing triangulated segment estimates.
Segment-weighting across test type, technology platform, clinical application, and end-user channel shaped the analytical framework throughout the forecast period. Modeled dimensions included resistance-guided therapy penetration rates, integrated delivery network consolidation trajectories, and point-of-care accessibility expansion patterns. CAGRs were derived from logistic diffusion curves for molecular adoption and linear extrapolation for mature immunoassay segments. Industry-specific inputs incorporated clarithromycin resistance surveillance mandate timelines and isotope supply contract renewal cycles.
The model holds under stable antimicrobial stewardship policy continuity; deviation in Medicare reimbursement expansion or EMA IVDR enforcement intensity would shift volume trajectories. Forecasts reflect documented assumptions regarding resistance testing mandate geographic spread and digital PCR capital equipment replacement cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Home Blood Testing Devices Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Vials Leak Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Influenza Home Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Active B12 Test Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Phenytoin Testing Market
Testing Services
Creatinine Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Test Strips Market