
 Blood Coagulants Market | 2026-2036
Blood Coagulants Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Coagulants Market Analysis
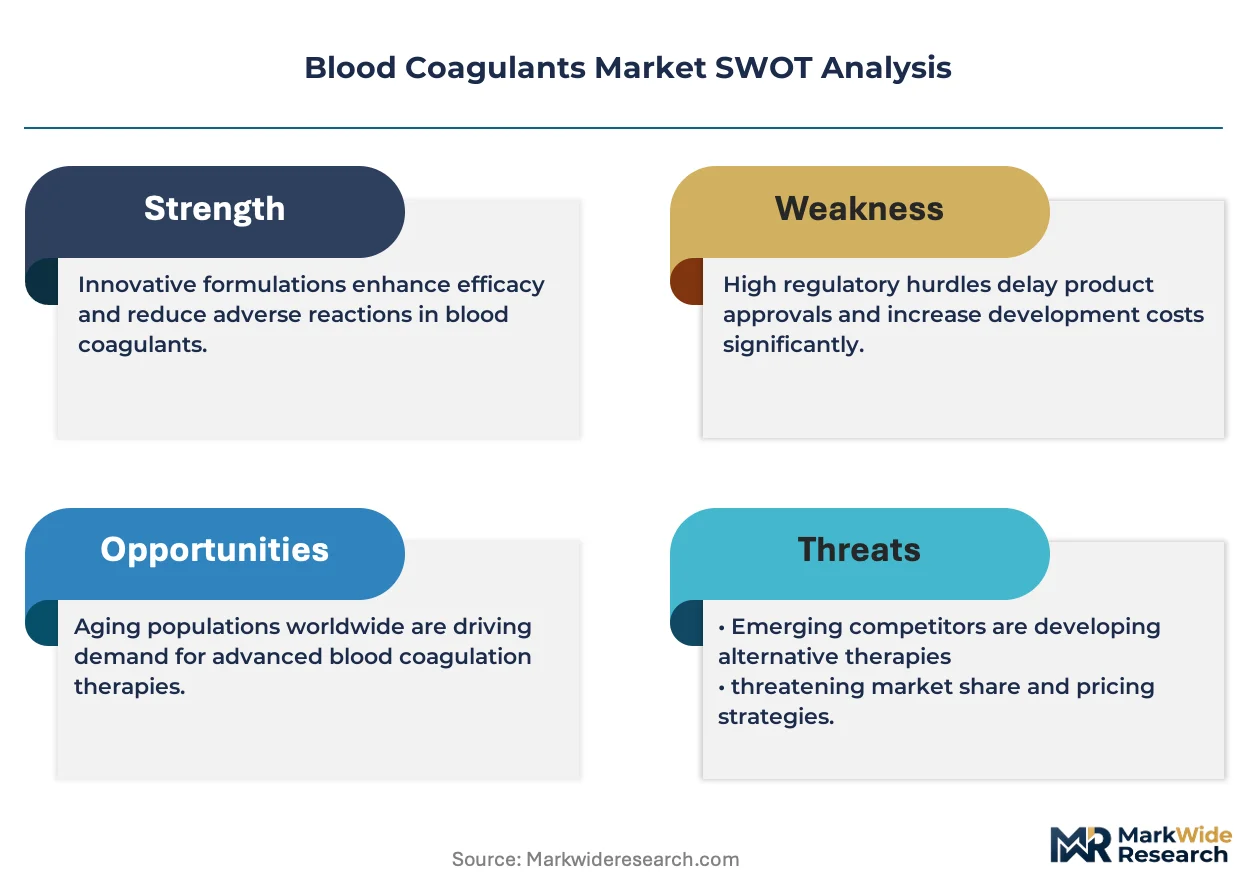
Recombinant factor VIII and IX specifications are rotating toward extended half-life formulations across the blood coagulants landscape. CSL Behring leverages its plasma fractionation infrastructure to sustain bulk concentrate supply. Novo Nordisk A/S anchors European recombinant production capacity. Grifols S.A. specializes in plasma-derived portfolio breadth across hemophilia and rare bleeding disorders.
Blood coagulants comprise biologically active proteins, synthetic peptides, and concentrated plasma fractions engineered to restore hemostasis through fibrin clot formation, typically standardized by international unit potency and viral inactivation protocols. Recombinant Factors command premium positioning due to reduced infection risk and consistent supply chains, while Plasma-Derived Factors retain cost-sensitive volume in emerging systems. Hemophilia therapy generates the deepest margin pools, though Trauma applications represent the fastest-growing demand vector as battlefield and emergency protocols expand factor concentrate use.
FDA plasma derivative guidance and EMA's Biologicals framework enforce viral safety and potency labeling standards that shape manufacturer compliance costs and market access timelines. The EU F-Gas Regulation and REACH chemical stewardship protocols additionally constrain synthetic coagulant solvent and stabilizer selections. Stakeholders must monitor evolving pharmacovigilance requirements for extended half-life products as real-world evidence frameworks mature.
Market Dynamics
Extended half-life recombinant factor concentrates are compressing dosing frequency requirements and reshaping hemophilia treatment economics across hospital procurement channels.
Growth Catalysts
- EMA Biologicals Framework Harmonization:Cross-border approval streamlining accelerates recombinant factor concentrate market entry across European hemophilia treatment centers.
- Trauma Protocol Expansion:Battlefield and emergency medicine applications are pulling factor concentrates into pre-hospital settings previously served by plasma transfusion.
- Japan's Specialized Treatment Center Density:Concentrated patient access infrastructure anchors reimbursement security and sustained volume commitment for advanced coagulant therapies.
Market Restraints
- Plasma Fractionation Concentration:Bulk plasma supply chains cluster in limited geographic corridors, exposing concentrate production to collection volatility.
- EU F-Gas Regulation Constraints:Solvent and stabilizer selection for synthetic coagulant manufacturing faces chemical stewardship restrictions that inflate formulation costs.
- Recombinant Premium Compression:Cost-sensitive health systems in emerging markets retain plasma-derived factor volume despite infection risk differentials.
Strategic Opportunities
- Real-World Evidence Framework Maturation:Pharmacovigilance data collection for extended half-life products opens differentiated labeling pathways.
- India Hemophilia Center Expansion:Underpenetrated patient populations present volume growth potential as CDSCO streamlines biologic approval timelines.
- Gene Therapy Convergence:Coagulant concentrate manufacturers can anchor transition partnerships as curative modalities enter late-stage development.
Industry Challenges
- Viral Inactivation Validation Complexity:FDA plasma derivative guidance demands continuous process verification that extends facility commissioning timelines.
- Cold Chain Integrity Requirements:Factor concentrate stability protocols necessitate specialized logistics infrastructure that constrains distribution reach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Coagulants Market |
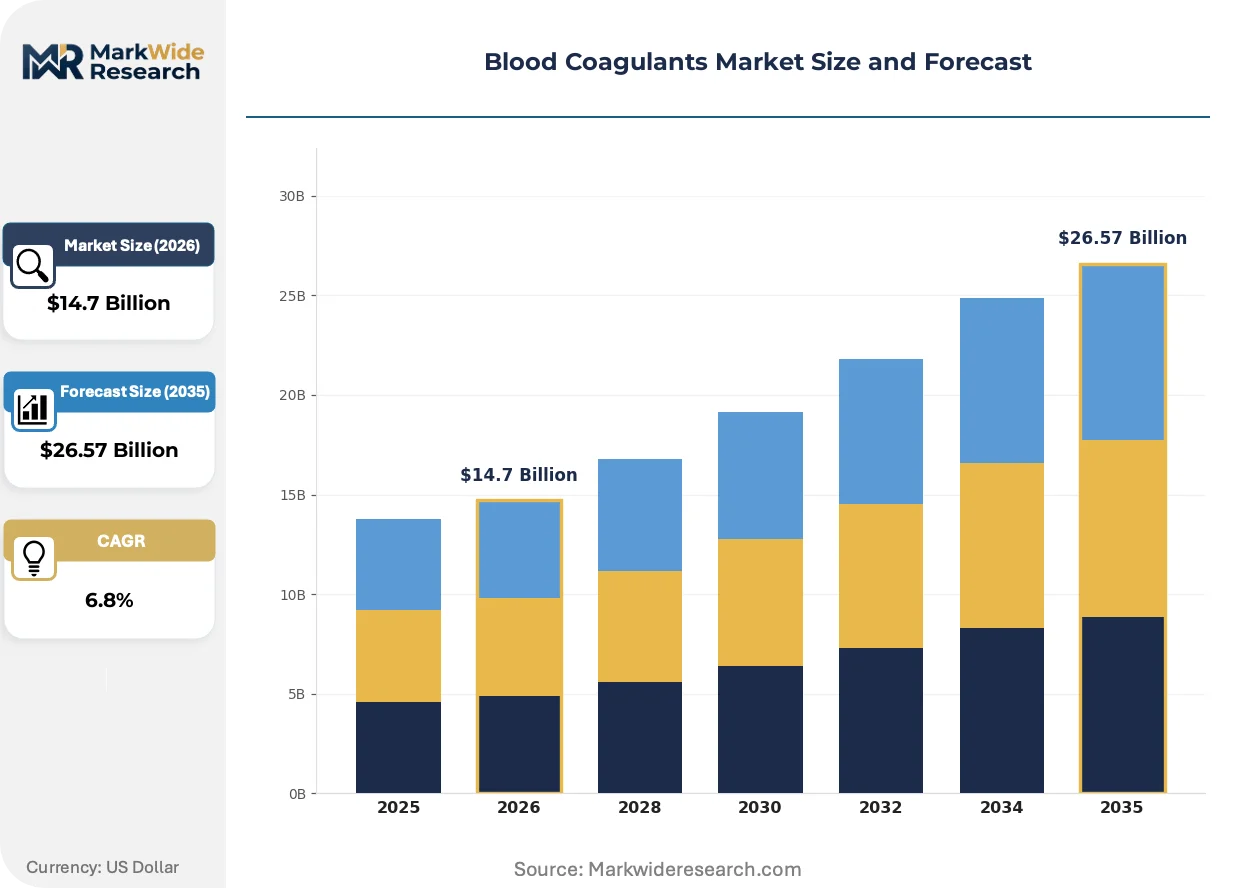
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Factors, Plasma-Derived Factors, Synthetic Coagulants, Prothrombin Complex Concentrates Therapy Area: Hemophilia, Trauma, Surgery, Liver Disease End User: Hospitals, Clinics, Blood Banks, Home Care Administration Route: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | CSL Behring, Bristol-Myers Squibb Company, Johnson & Johnson, Bayer AG, Sanofi S.A., Baxter International Inc., Grifols S.A., Novo Nordisk A/S, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Coagulants Market Emerging Trajectories
Bioconjugation chemistry and novel half-life extension technologies are rewriting the competitive hierarchy in hemophilia therapeutics, compressing the gap between prophylactic convenience and on-demand rescue therapy.
PEGylation and Fc-fusion technologies for recombinant factor VIII and IX are supplanting standard half-life formulations in prophylactic regimens. Pediatric hemophilia treatment centers in the United States and Germany are adopting extended-interval dosing protocols that reduce infusion burden. This technology shift is compressing annual factor consumption volumes per patient while elevating per-unit pricing power.
REACH chemical stewardship protocols and the EU F-Gas Regulation are constraining solvent selection for synthetic coagulant stabilizers. Manufacturers reformulating excipient compositions face extended EMA compliance verification timelines. Plasma-derived concentrate producers with established viral inactivation dossiers are exploiting this regulatory friction to defend European market position against synthetic entrants.
Hospital procurement committees are consolidating factor concentrate purchasing through specialized hemophilia treatment center networks. Traditional distributor intermediaries face disintermediation as direct manufacturer agreements anchor volume commitments. Germany's integrated care structures and Japan's designated institution systems exhibit this channel compression most acutely, with procurement authority concentrating at fewer decision nodes.
Blood Coagulants Market Segmentation
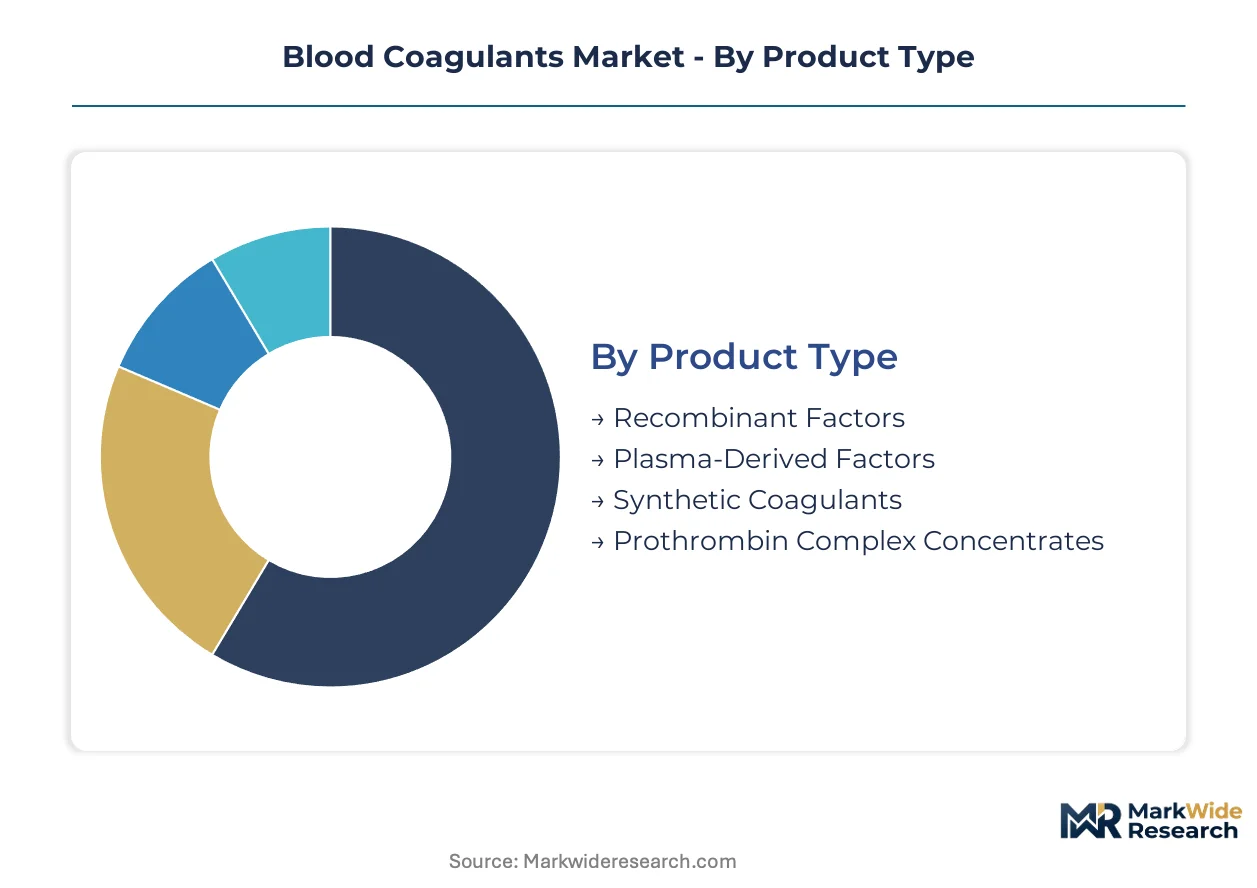
Blood coagulants segment across four critical dimensions that shape procurement patterns and regulatory pathways. Product type and therapy area determine reimbursement tiers, while end user and administration route dictate cold chain requirements and dosing economics.
Product Type:
Recombinant concentrates dominate developed market hospital procurement, while plasma-derived volumes concentrate in cost-sensitive systems across Asia and Latin America. Synthetic alternatives face EMA solvent restrictions that constrain European manufacturing scale-up.
- Recombinant Factors:Genetically engineered factor VIII and IX proteins produced in mammalian cell lines with PEGylation or Fc-fusion half-life extension. United States hemophilia treatment centers anchor demand as extended-interval prophylaxis protocols reduce annual infusion burdens. FDA pathway harmonization with EMA accelerates cross-border approval timelines for novel constructs.
- Plasma-Derived Factors:Concentrated clotting factors isolated from human plasma through Cohn fractionation and viral inactivation. Germany's integrated care structures and Japan's designated institution systems sustain volume commitment despite recombinant competition. Plasma collection volatility in limited geographic corridors exposes supply security risks.
- Synthetic Coagulants:Small-molecule hemostatic agents and peptide-based clotting accelerators. REACH chemical stewardship constrains excipient selection for European manufacturing.
- Prothrombin Complex Concentrates:Vitamin K-dependent factor cocktails (II, VII, IX, X) for rapid warfarin reversal and bleeding control. Trauma protocol expansion in battlefield medicine pulls volumes into pre-hospital settings.
Recombinant Factors command the established base. The steepest expansion runs through Prothrombin Complex Concentrates.
Therapy Area:
Margin pools concentrate in chronic prophylaxis regimens, while acute intervention applications expand addressable patient populations. Hemophilia centers in the United States, Germany, and Japan anchor reimbursement security for high-value therapies.
- Hemophilia:Inherited factor VIII or IX deficiency requiring lifelong replacement therapy. Pediatric treatment centers adopt extended half-life formulations that compress dosing frequency from thrice-weekly to once-weekly or longer intervals. Real-world evidence frameworks for novel constructs mature through FDA pharmacovigilance requirements.
- Trauma:Massive hemorrhage and coagulopathy of trauma requiring rapid factor replacement. Military medical protocols and civilian emergency medicine guidelines expand factor concentrate use beyond traditional plasma transfusion. Battlefield applications in active conflict zones drive procurement through defense health channels.
- Surgery:Perioperative bleeding management in cardiac, orthopedic, and hepatic procedures. Hospital blood management committees consolidate purchasing through specialized coagulation laboratories.
- Liver Disease:Coagulopathy secondary to synthetic dysfunction in cirrhosis and acute liver failure. Compensated and decompensated cirrhotic populations present distinct bleeding risk profiles.
Hemophilia anchors value concentration. Trauma applications are climbing the fastest as emergency protocols evolve.
End User:
Channel compression concentrates procurement authority at fewer decision nodes, disintermediating traditional distributor networks. Direct manufacturer agreements with integrated delivery networks reshape contract structures.
- Hospitals:Academic medical centers and specialized hemophilia treatment centers with in-house coagulation laboratories and pharmacy compounding capabilities. Germany's integrated care structures and Japan's designated institution systems exhibit the most acute procurement concentration.
- Clinics:Outpatient infusion centers and community hematology practices managing stable prophylaxis patients. United States accountable care organization penetration shifts site-of-care decisions toward lower-cost settings.
- Blood Banks:Regional blood centers with plasma fractionation partnerships or direct concentrate distribution agreements. Cold chain infrastructure requirements constrain independent blood bank participation.
- Home Care:Self-infusion programs for hemophilia patients with established venous access and caregiver training. Extended half-life formulations reduce nursing visit frequency and improve adherence metrics.
Hospitals retain volume dominance. Home Care is gaining share fastest as patient training programs mature.
Administration Route:
Delivery technology determines dosing convenience, patient adherence, and reimbursement coding. Intravenous remains standard for factor concentrates, while subcutaneous formulations enter late-stage development.
- Intravenous:Direct venous infusion of factor concentrates through peripheral or central access. Standard of care for hemophilia prophylaxis and acute bleeding episodes requiring rapid peak levels.
- Subcutaneous:Depot formulations and novel delivery systems under investigation for factor VIII and IX. Reduced infusion burden targets patient populations with poor venous access or needle phobia.
- Intramuscular:Limited application for specific hemostatic agents in surgical and trauma settings where intravenous access is delayed.
- Oral:Small-molecule hemostatics and tranexamic acid formulations for mild bleeding disorders and perioperative prophylaxis. Bioavailability constraints limit application for severe hemophilia.
Intravenous administration commands the established base. Subcutaneous delivery shows the steepest development trajectory as formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation infrastructure in the United States exports recombinant factor concentrates to specialized hemophilia treatment centers across Germany and Japan. European collection networks supply plasma-derived volumes to hospital systems in the United Kingdom and France. Asian markets import both recombinant and plasma-derived concentrates through regulated procurement channels in Japan and emerging distribution frameworks in India.
United States
Academic medical centers in Boston and New York Metro anchor recombinant factor VIII and IX procurement for extended half-life prophylaxis protocols. FDA plasma derivative guidance enforces viral inactivation standards that shape manufacturer compliance timelines. The Research Triangle in North Carolina concentrates plasma fractionation R&D facilities where process verification protocols advance.
Germany
Integrated care structures in Bavaria and North Rhine-Westphalia consolidate purchasing authority at specialized hemophilia treatment centers. EMA Biologicals framework harmonization with FDA pathways accelerates cross-border approval timelines for novel constructs. The Frankfurt-Rhine-Main cluster hosts plasma fractionation infrastructure serving hospital networks across Central Europe.
Japan
Designated institution systems in Tokyo and Osaka anchor reimbursement security for advanced coagulant therapies. PMDA streamlined biologic approval pathways reduce market entry timelines for extended half-life formulations. The Kansai region concentrates specialized treatment center density that sustains volume commitment for premium factor concentrates.
United Kingdom
NHS England blood management committees in London and the Midlands consolidate factor concentrate procurement through specialized coagulation laboratories. MHRA post-Brexit regulatory alignment with EMA standards maintains cross-border supply continuity. The Oxford-Cambridge arc hosts translational research programs advancing novel half-life extension technologies.
India
Underpenetrated hemophilia populations in Maharashtra and Karnataka present volume growth potential as CDSCO streamlines biologic approval timelines. National health mission programs expand access to plasma-derived factors in tier-two cities. The Hyderabad-Visakhapatnam corridor attracts contract manufacturing investments serving domestic and export markets.
Blood Coagulants Market Vendor Landscape
Listed leaders compete with private specialists across plasma fractionation and recombinant production capacity. The market structure consolidates around integrated plasma collectors with captive fractionation infrastructure and biotechnology firms with mammalian cell line expertise. Three archetypes dominate: plasma-derived volume players leveraging collection network density, recombinant technology specialists commanding premium positioning, and diversified pharmaceutical conglomerates with hybrid portfolios. Competitive moves center on M&A to secure plasma supply security and strategic partnerships anchoring gene therapy transition pathways.
Within the plasma-derived tier, CSL Behring and Grifols S.A. represent integrated collection-to-concentrate operators. Among recombinant specialists, Novo Nordisk A/S occupies a position exemplifying European production capacity for extended half-life formulations. These three anchors illustrate the competitive tension between supply security through plasma verticality and technology differentiation through bioconjugation chemistry.
| Leading Market Players |
|---|
| CSL Behring |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Bayer AG |
| Sanofi S.A. |
| Baxter International Inc. |
| Grifols S.A. |
| Novo Nordisk A/S |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Plasma fractionation scale economies in the United States and Germany anchor global supply concentration and establish price floors that emerging-market producers cannot undercut without sacrificing viral safety validation. Recombinant mammalian cell-line capacity utilization rates directly determine per-unit cost structures, compressing margins for sub-scale operators while rewarding integrated biologics manufacturers with captive production infrastructure.
Pricing Analysis
The technology-generation pricing gap separates extended half-life recombinant factors commanding premium positioning against standard half-life formulations and legacy plasma-derived concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects FDA versus EMA pathway differentiation, volume procurement scale, and cold chain service bundling. Cost compression in plasma-derived tiers is intensifying because recombinant substitution accelerates in developed-market hemophilia treatment centers. Emerging-market hospital systems exhibit highest price sensitivity, while pediatric specialized treatment centers in Japan and Germany demonstrate lowest sensitivity due to reimbursement security.
Supply Chain Analysis
The United States and Germany anchor plasma fractionation infrastructure, while Switzerland and Denmark concentrate recombinant mammalian cell-line production. Bulk plasma supply draws from United States collection networks, European donor pools, and emerging Australian operations. Single-source vulnerability concentrates in limited geographic corridors for plasma collection, exposing concentrate production to donor availability volatility. Distribution runs through specialized hemophilia treatment center networks with direct manufacturer agreements displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of validated viral inactivation expertise and cold chain logistics capability constrains competitive entry and sustains incumbent pricing power. Manufacturers lacking plasma collection network density or recombinant cell-line development experience face extended facility commissioning timelines that delay market access.
For Market Incumbents: Consolidate plasma collection network density through regional donor center acquisitions in under-tapped United States corridors. Deepen backward integration into recombinant cell-line development to reduce dependency on contract manufacturing organizations as gene therapy convergence threatens replacement demand. For New Entrants and Emerging Players: Home care service-layer gaps in India and Southeast Asia present white-space targets where incumbents under-serve patient self-infusion training and nursing support. CDSCO streamlined biologic approval timelines reduce regulatory friction for contract manufacturers establishing Hyderabad-Visakhapatnam corridor presence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors plasma-derived volume players with established viral inactivation dossiers over synthetic entrants facing EMA solvent restrictions. Long-term viability hinges on gene therapy transition partnership anchoring rather than pure replacement exposure. Watch real-world evidence framework maturation for extended half-life products as inflection indicator for differentiated labeling pathways and pricing persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | United States donor center density secures bulk supply against collection volatility in European corridors. |
| Extended Half-Life Formulation Development | PEGylation and Fc-fusion technologies reduce dosing frequency and anchor pediatric prophylaxis adoption. |
| EMA-FDA Pathway Harmonization | Cross-border approval streamlining accelerates recombinant factor concentrate market entry timelines. |
| Gene Therapy Transition Partnership | Coagulant concentrate manufacturers anchor patient relationships as curative modalities enter late-stage development. |
| Home Care Service Infrastructure Buildout | Self-infusion training programs and nursing support reduce site-of-care costs and improve adherence metrics. |
Methodological Framework
A spread of perspectives from plasma fractionation executives, hemophilia treatment center pharmacy directors, regulatory affairs leads at biologics manufacturers, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interview insights triangulated against FDA plasma derivative guidance documents, EMA Biologicals framework submissions, ClinicalTrials.gov gene therapy protocols, and hospital procurement database records. Bottom-up patient population estimates and top-down plasma collection volume data cross-validated market sizing across the analysis window.
Segmentation dimensions modeled include product type tier, therapy area severity, end-user channel, and administration route technology generation across the projection horizon. CAGRs derived from patient population growth, dosing frequency compression from extended half-life adoption, and trauma protocol expansion rates. Forecast inputs incorporated plasma collection yield trends and recombinant cell-line productivity improvements.
Forecasts assume regulatory continuity in FDA plasma derivative guidance and EMA Biologicals framework enforcement; material policy shifts would require re-modeling. Gene therapy approval timelines and real-world evidence framework maturation present specific revision triggers. Recalibration cycles align with material shifts in hemophilia treatment protocol adoption and plasma collection network configuration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Global Oxytocin Market