
 Block Sack Market | 2026-2036
Block Sack Market Size, Share, and Industry Trends Forecast 2026-2036
Block Sack Market Outlook
Asset-light leasing models for bulk packaging fleets is reconfiguring competitive dynamics among block sack suppliers. Starlinger Company leverages its Austrian engineering heritage to dominate circular weaving machinery and captive sack production systems. Mondi Group anchors European demand through integrated kraft paper and industrial packaging operations with certified sustainability chains. Tianjin Jia Tai Feng Plastic Woven Co., Ltd. competes on polyethylene and polypropylene woven volumes directed at Asian construction material logistics.
Block sacks are multi-wall industrial containers, typically constructed from woven polypropylene tapes or kraft paper plies with a block-bottom square construction that enables stable palletized stacking and discharge through bottom spouts. Standard specifications include 25 kg to 50 kg rated load capacity, UV-stabilized fabric for outdoor storage, and heat-cut or hemmed top closures suited to automated filling lines. Woven polypropylene sacks sustain the largest volume position due to moisture resistance and tensile strength in cement and chemical handling, while paper sacks occupy premium niches where biodegradability and food-contact compliance command margin premiums. Non-woven alternatives represent the fastest-expanding structural category, displacing conventional woven formats in agricultural seed and fertilizer applications where breathability reduces spoilage.
REACH and the EU Packaging and Packaging Waste Directive in Europe, alongside FDA food-contact regulations in the United States and BIS certification requirements for woven sacks in India, collectively shape material selection, recyclability mandates, and market access thresholds. The EU Green Deal's extended producer responsibility frameworks are forcing reformulation of plastic-heavy block sack constructions toward mono-material or paper-based alternatives. Stakeholders must monitor divergence between regional recycling infrastructure readiness and tightening single-use packaging restrictions to calibrate product portfolio and geographic prioritization decisions.
Market Dynamics
Asset-light leasing models for bulk packaging fleets are reconfiguring how cement producers and chemical distributors contract block sack supply, compressing traditional ownership economics and favoring integrated service providers over standalone manufacturers.
Growth Catalysts
- India's PLI scheme for technical textiles:Domestic woven sack manufacturing capacity is scaling rapidly under production-linked incentives, reducing import dependency for construction material logistics.
- Woven polypropylene UV stabilization:Extended outdoor storage tolerance is expanding cement sector procurement in tropical infrastructure corridors where warehouse capacity remains constrained.
- REACH recyclability mandates:European reformulation requirements are accelerating mono-material block sack designs that simplify end-of-life processing and unlock circular economy premiums.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings tied to naphtha and propylene markets compress margin predictability for woven sack converters.
- Circular weaving machinery concentration:Austrian and German equipment suppliers control critical loom technology, creating supply bottlenecks for capacity expansion in emerging manufacturing bases.
- Kraft paper moisture sensitivity:Structural limitations in humid climates restrict paper-based block sack penetration in Southeast Asian and Latin American construction markets.
Strategic Opportunities
- Non-woven breathable formats:Agricultural seed and fertilizer applications are adopting spunbond alternatives that reduce spoilage through vapor transmission control.
- EU Green Deal extended producer responsibility:Packaging waste frameworks are creating certified sustainable product premiums for compliant suppliers.
- Automated filling line integration:Heat-cut and hemmed closure specifications aligned with robotic handling systems are opening industrial chemical sector contracts.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous BIS, FDA, and REACH compliance requirements extend product qualification cycles for exporters.
- Legacy equipment retrofit complexity:Existing woven tape lines require substantial modification to produce mono-material constructions meeting recyclability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Block Sack Market |
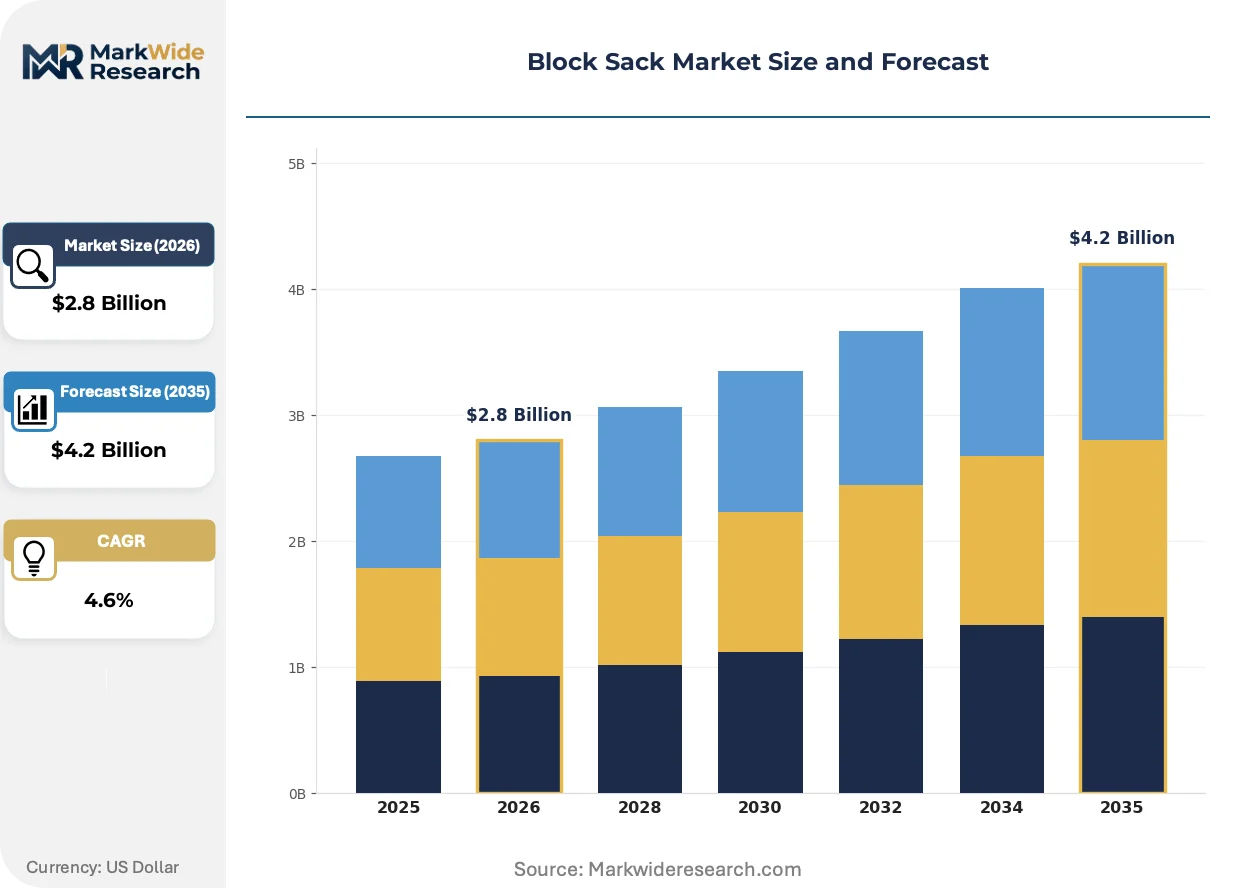
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Sacks, Non-Woven Sacks, Paper Sacks, Plastic Sacks Size: Small Bags, Medium Bags, Large Bags, Extra Large Bags Application: Agriculture, Construction, Industrial Packaging, Food Packaging Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Starlinger Company, East Riding Sacks Limited, Shouman Company, Dyna Polyplast Pvt Ltd., Segezha Group, Flexipol Packaging Limited, AB Group Packaging, Tianjin Jia Tai Feng Plastic Woven Co., Ltd., Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Block Sack Market Strategic Shifts
Material science advances and regulatory tightening are converging to transform block sack construction, with breathability engineering and circular design principles displacing conventional specifications across end-use verticals.
Spunbond non-woven polypropylene with calibrated pore structures is rendering obsolete traditional woven formats in agricultural seed packaging. European and North American seed distributors are transitioning procurement specifications toward breathable alternatives that reduce fungal contamination during extended storage. This technology compression is fragmenting supplier tiers between commodity woven producers and specialized non-woven converters.
REACH authorization procedures and the EU Packaging and Packaging Waste Directive are forcing reformulation of multi-layer block sack constructions. Industrial chemical handlers face restricted market access for non-recyclable composite designs, driving consolidation around mono-material polypropylene or pure kraft paper specifications. German and French packaging compliance auditors are rejecting legacy constructions that complicate mechanical recycling streams.
Outcome-based fleet management contracts are replacing outright purchase arrangements among cement distributors. Leasing providers now assume responsibility for sack maintenance, tracking, and reverse logistics, compressing working capital requirements for construction material handlers. This procurement transformation is most advanced in Indian and Brazilian infrastructure corridors where project financing constraints favor operational expenditure models.
Block Sack Market Segmentation
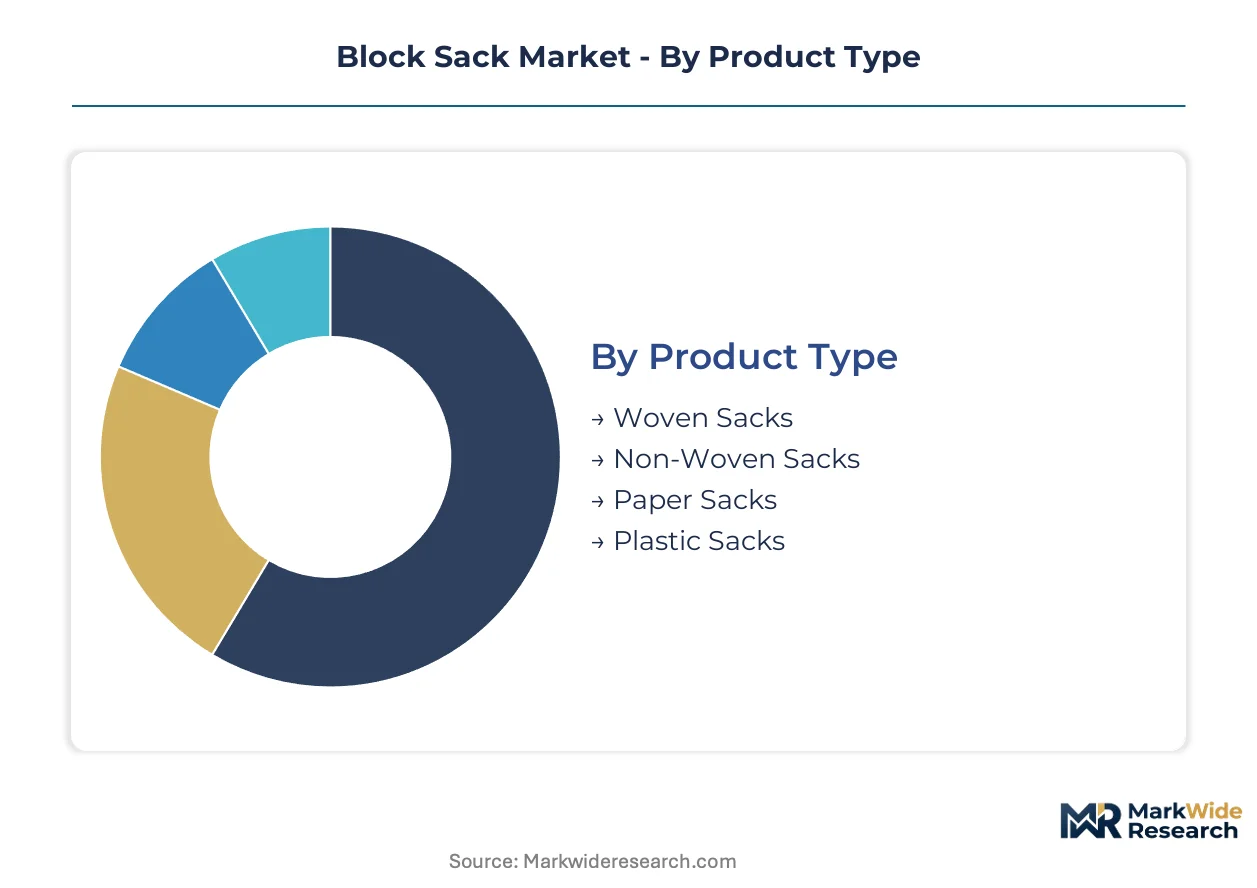
Block sack procurement patterns diverge sharply across material formats, dimensional classes, and end-use verticals, with regulatory compliance and handling automation requirements reshaping supplier prioritization. Construction and agricultural buyers drive distinct specification clusters that favor moisture resistance or breathability respectively.
Product Type:
Mature woven formats dominate cement logistics while emerging non-woven and paper alternatives capture premium niches demanding sustainability credentials or agricultural breathability.
- Woven Sacks:Polypropylene tape constructions deliver tensile strength above 50 kg load ratings with UV stabilization for tropical outdoor storage. Cement distributors across Indian infrastructure corridors specify these for aggregate handling where warehouse capacity remains constrained.
- Non-Woven Sacks:Spunbond polypropylene with engineered pore structures enables vapor transmission control that reduces seed spoilage during extended agricultural storage. European seed distributors are transitioning procurement specifications toward these breathable alternatives.
- Paper Sacks:Multi-ply kraft constructions with food-contact compliance command margin premiums in specialty chemical and food-grade applications.
- Plastic Sacks:Mono-material polyethylene formats simplify mechanical recycling streams under EU Packaging and Packaging Waste Directive requirements.
Woven sacks retain volume leadership; non-woven alternatives hold the steepest expansion curve.
Size:
Cost tier differentiation separates automated filling line formats from manual handling specifications across construction and agricultural supply chains.
- Small Bags:10-25 kg rated capacities serve specialty chemical and seed sampling applications where precision dosing outweighs per-unit logistics efficiency.
- Medium Bags:Standard 25-50 kg specifications align with palletized stacking norms and robotic handling systems in cement distribution. Indian construction material logistics concentrates procurement here under PLI scheme manufacturing scale-up.
- Large Bags:50-100 kg formats reduce per-ton packaging costs for bulk industrial chemical handlers with automated discharge infrastructure.
- Extra Large Bags:Flexible intermediate bulk container alternatives above 100 kg challenge rigid packaging in grain and mineral logistics.
Medium bags capture the dominant procurement volume; extra large formats are expanding most quickly in automated bulk handling installations.
Application:
End-use concentration patterns split between weather-exposed construction logistics and controlled-environment agricultural storage with diverging material specifications.
- Agriculture:Seed and fertilizer packaging demands breathability engineering that reduces fungal contamination through moisture vapor transmission. Non-woven spunbond formats displace woven alternatives here.
- Construction:Cement and aggregate handling specifies UV-stabilized woven polypropylene with block-bottom square construction for stable palletized stacking. REACH recyclability mandates are forcing mono-material reformulation in European procurement.
- Industrial Packaging:Chemical and mineral logistics prioritize heat-cut closure compatibility with automated filling lines and bottom spout discharge mechanisms.
- Food Packaging:Food-contact compliance under FDA and FSSAI regulations restricts material selection to certified kraft paper or virgin polypropylene with migration testing documentation.
Construction retains volume leadership; agriculture holds the steepest expansion curve as breathable formats penetrate seed distribution.
Distribution Channel:
Customer type stratification separates project-based bulk procurement from spot purchasing across contractor, farmer, and industrial buyer segments.
- Online Retail:E-commerce platforms serve small-lot agricultural and specialty chemical buyers with standardized specifications and rapid fulfillment.
- Supermarkets:Consumer-facing retail channels move small-format food-grade and garden supply sacks with branded packaging requirements.
- Wholesale Distributors:Volume aggregation for construction and agricultural cooperatives dominates Indian and Brazilian infrastructure corridors where project financing constraints favor operational expenditure models.
- Specialty Stores:Technical packaging suppliers serve industrial chemical handlers with certified compliance documentation and custom specification engineering.
Wholesale distributors retain volume leadership; online retail is gaining share fastest in fragmented agricultural procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European converters extract margin premiums through REACH-compliant mono-material designs while Indian manufacturers undercut on polypropylene woven volumes. This pricing-power asymmetry redirects export flows and reshapes procurement geography for cement distributors.
India
Construction material logistics drives woven polypropylene consumption across cement and aggregate handling corridors. The PLI scheme for technical textiles subsidizes domestic tape extrusion and circular weaving capacity expansion. Manufacturing clusters in Gujarat and Maharashtra are scaling output for infrastructure projects along the Delhi-Mumbai Industrial Corridor.
Germany
Industrial chemical handlers demand certified recyclable packaging under extended producer responsibility frameworks. ECHA enforcement of REACH authorization procedures blocks non-recyclable multi-layer sack imports. The Rhine-Ruhr packaging engineering belt concentrates reformulation R&D for mono-material alternatives.
China
Evolving GB standards for load-bearing capacity and recyclability tighten specifications for domestic and export-bound production. The dual carbon goals policy accelerates energy-efficient weaving machinery replacement. Manufacturing bases in Zhejiang and Shandong provinces dominate polyethylene and polypropylene woven output for Asian construction markets.
United States
Food-contact compliance under FDA regulations restricts material selection for agricultural seed and specialty chemical applications. Automated filling line integration specifications favor heat-cut closure engineering. Midwest agricultural logistics hubs in Iowa and Illinois are transitioning procurement toward breathable non-woven formats for spoilage reduction.
Brazil
Infrastructure financing constraints favor operational expenditure models for bulk packaging procurement. Asset-light leasing contracts compress working capital requirements for cement distributors. São Paulo-state construction material handlers are aggregating demand through wholesale distributor networks serving the Southeast infrastructure corridor.
Block Sack Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in machinery and resin supply. The vendor base organizes around three archetypes: Austrian and German engineering houses controlling circular weaving loom technology, integrated European packaging groups with certified sustainability chains, and Asian volume converters competing on polypropylene woven scale. Consolidation pressures favor backward integration into captive tape extrusion, while technology licensing agreements unlock emerging market capacity expansion without direct capital deployment.
Among Austrian engineering specialists, Starlinger Company occupies the machinery and captive production systems tier. Mondi Group anchors European demand through integrated industrial packaging operations. Tianjin Jia Tai Feng Plastic Woven Co., Ltd. represents the Chinese volume converter archetype competing on polyethylene and polypropylene woven output for regional construction logistics.
| Leading Market Players |
|---|
| Starlinger Company |
| East Riding Sacks Limited |
| Shouman Company |
| Dyna Polyplast Pvt Ltd. |
| Segezha Group |
| Flexipol Packaging Limited |
| AB Group Packaging |
| Tianjin Jia Tai Feng Plastic Woven Co., Ltd. |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin price volatility tied to naphtha and propylene feedstock markets compresses margin predictability for woven sack converters while simultaneously forcing tiered pricing stratification across UV-stabilized, mono-material, and standard-grade specifications. This commodity exposure determines both the premium commanded by Austrian-engineered circular weaving output and the supply chain's geographic reconfiguration toward Indian PLI-subsidized capacity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels where REACH-compliant mono-material designs extract sustainability premiums from European chemical handlers. Price differentiation hinges on certification grade under ECHA enforcement and volume scale under cement distributor fleet contracts. Cost compression in economy-tier woven polypropylene is intensifying because Indian domestic manufacturing scale-up under the PLI scheme floods Asian construction corridors with lower-specification output. Small-lot agricultural buyers exhibit highest price sensitivity; integrated leasing providers securing multi-year fleet contracts show lowest.
Supply Chain Analysis
Extended payment terms from cement distributors in Brazilian infrastructure corridors and supply-chain finance facilities arranged through Indian wholesale networks are restructuring working capital flows across the value chain. Manufacturing concentrates in China, India, and Austria where Zhejiang and Shandong provinces dominate polyethylene and polypropylene woven output, Gujarat and Maharashtra clusters scale under PLI subsidies, and Starlinger engineering houses control circular loom technology. Raw material sourcing draws from naphtha-derived propylene, kraft pulp for paper alternatives, and spunbond non-woven feedstocks. Single-source vulnerability sits with Austrian and German equipment suppliers controlling critical loom technology. Distribution runs through wholesale distributor networks aggregating construction and agricultural cooperative demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light fleet management platforms are reconfiguring procurement toward outcome-based contracts, creating ecosystem lock-in effects where integrated service providers capture recurring revenue streams previously fragmented across standalone manufacturers and distributor intermediaries.
For Market Incumbents: Harden certification moats by accelerating mono-material reformulation to meet EU Green Deal extended producer responsibility deadlines before legacy equipment retrofit costs escalate. Deepen upstream control over captive tape extrusion capacity in Gujarat and Maharashtra manufacturing clusters to defend margin position against PLI-subsidized domestic entrants. Channel control through exclusive leasing partnerships with Brazilian cement distributors represents the critical defensive lever against platform disintermediation.
For New Entrants and Emerging Players: Build out non-woven breathable format production for North American agricultural seed distributors where FDA compliance requirements and spoilage-reduction value propositions create penetrable white space. Target Midwest logistics hubs in Iowa and Illinois transitioning procurement specifications away from woven alternatives. A technical sales motion emphasizing vapor transmission engineering and fungal contamination reduction metrics unlocks initial contract traction against commodity incumbent resistance.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with captive circular weaving machinery and certified sustainability chains. Long-term viability over a multi-year window hinges on exposure to regulatory compliance premiums rather than commodity volume positioning. Acquisition targets should demonstrate mono-material design capabilities and established ECHA audit relationships. The signal to watch is divergence between regional recycling infrastructure readiness and tightening single-use packaging restriction timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Reformulation | ECHA REACH enforcement blocks non-recyclable multi-layer imports from German chemical handlers. |
| Backward Integration into Tape Extrusion | Captive polypropylene tape production insulates margin from naphtha-propylene feedstock volatility. |
| Leasing Platform Development | Outcome-based fleet contracts compress working capital requirements for Brazilian cement distributors. |
| Non-Woven Capacity Expansion | Spunbond breathable formats penetrate Iowa and Illinois agricultural seed distribution specifications. |
| PLI-Subsidized Manufacturing Scale-Up | Gujarat and Maharashtra clusters reduce import dependency for Delhi-Mumbai Industrial Corridor logistics. |
Study Parameters
A standing panel of plant managers at woven sack converters, procurement leads at cement and chemical distributors, circular weaving machinery engineers, and technical R&D directors at packaging compliance consultancies provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, BIS certification registries, ECHA REACH authorization filings, and SEC disclosures from integrated packaging groups. Bottom-up volume modeling across material formats and end-use verticals triangulated against top-down macroeconomic indicators.
Scenario-bracketing around regulatory enforcement intensity and feedstock price volatility informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include material construction type, load capacity tier, end-use vertical, and regional regulatory cluster. CAGRs were derived through logarithmic trend fitting of historical shipment data and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated PLI scheme disbursement timelines and EU Green Deal implementation pacing.
Sensitivities concentrate around propylene price spike duration, ECHA audit enforcement consistency, and Indian domestic manufacturing quality maturation. Forecasts reflect documented assumptions regarding substitution elasticity between woven and non-woven formats. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Ventilated Bulk Bags Market