
 Block Former Market | 2026-2036
Block Former Market Size, Share, and Industry Trends Forecast 2026-2036
Block Former Market Analytics
Modular equipment bundling is consolidating buyer preference across the block former landscape, with purchasers favoring integrated systems that combine forming, curing, and handling functions into single procurement packages. Block leverages its hardware-software integration to anchor premium positioning in mobile operations. Toast sustains channel control through restaurant-adjacent contractor networks that cross-sell construction payment solutions. Shopify POS competes by extending e-commerce logistics expertise into small-scale manufacturing equipment financing.
A block former is a specialized machine that compresses and molds concrete, cement, or aggregate mixtures into standardized masonry units using hydraulic pressure or mechanical vibration, typically achieving densities of 1,800–2,200 kg/m³ for load-bearing applications. These machines serve primary industrial purposes in residential and commercial construction, infrastructure rehabilitation, and precast manufacturing where dimensional consistency and compressive strength compliance determine structural integrity. Mechanical block formers occupy mature demand pools among cost-sensitive contractors, while electric block formers capture fastest-growing interest where grid reliability and carbon accounting tighten operational specifications. Hydraulic systems still dominate manufacturing firms requiring high-throughput continuous production, with margin pools concentrating in aftermarket parts and remote diagnostics services.
EPA emissions standards and OSHA workplace safety regulations in the United States compel equipment upgrades toward enclosed, automated forming systems that reduce silica dust exposure and diesel particulate output. India's BIS certification requirements and CEA electrical safety mandates shape import eligibility and domestic manufacturing compliance for block former producers seeking market access. Stakeholders must monitor how municipal procurement rules in high-growth construction corridors redefine total-cost-of-ownership calculations beyond upfront equipment pricing.
Market Dynamics
Modular equipment bundling is compressing procurement cycles as construction firms consolidate forming, curing, and handling functions into single-vendor packages, forcing standalone machine suppliers to defend margin pools through aftermarket services.
Growth Catalysts
- India's PLI Scheme:Production-linked incentives for construction machinery manufacturing are accelerating domestic assembly capacity and import substitution for hydraulic block formers.
- Smart Cities Mission:Municipal infrastructure spending across Indian urban corridors sustains equipment procurement volumes for standardized masonry production.
- Electric forming systems:Grid-reliable electric block formers are capturing specification share where carbon accounting and EPA emissions standards tighten operational requirements.
Market Restraints
- Steel and cement input volatility:Raw material cost swings compress equipment margin predictability for manufacturers dependent on commodity-exposed supply chains.
- Hydraulic component concentration:Precision valve and pump sourcing clusters in German and Japanese supplier bases create vulnerability to logistics disruption.
- Silica dust exposure regulations:OSHA workplace safety mandates compel costly enclosed-system retrofits that extend payback periods for smaller contractors.
Strategic Opportunities
- Remote diagnostics convergence:Telematics integration with predictive maintenance algorithms is opening recurring revenue streams beyond equipment sale.
- BIS certification pathways:Streamlined Indian standards compliance for imported electric systems creates first-mover positioning for foreign manufacturers.
- Precast manufacturing expansion:Off-site construction adoption in commercial building verticals is diversifying demand beyond traditional masonry contractors.
Industry Challenges
- Electromechanical technician scarcity:Hybrid hydraulic-electric system maintenance requires cross-trained service personnel that regional labor pools currently lack.
- Legacy equipment integration:Retrofitting automated forming controls into existing plant layouts demands custom engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Block Former Market |
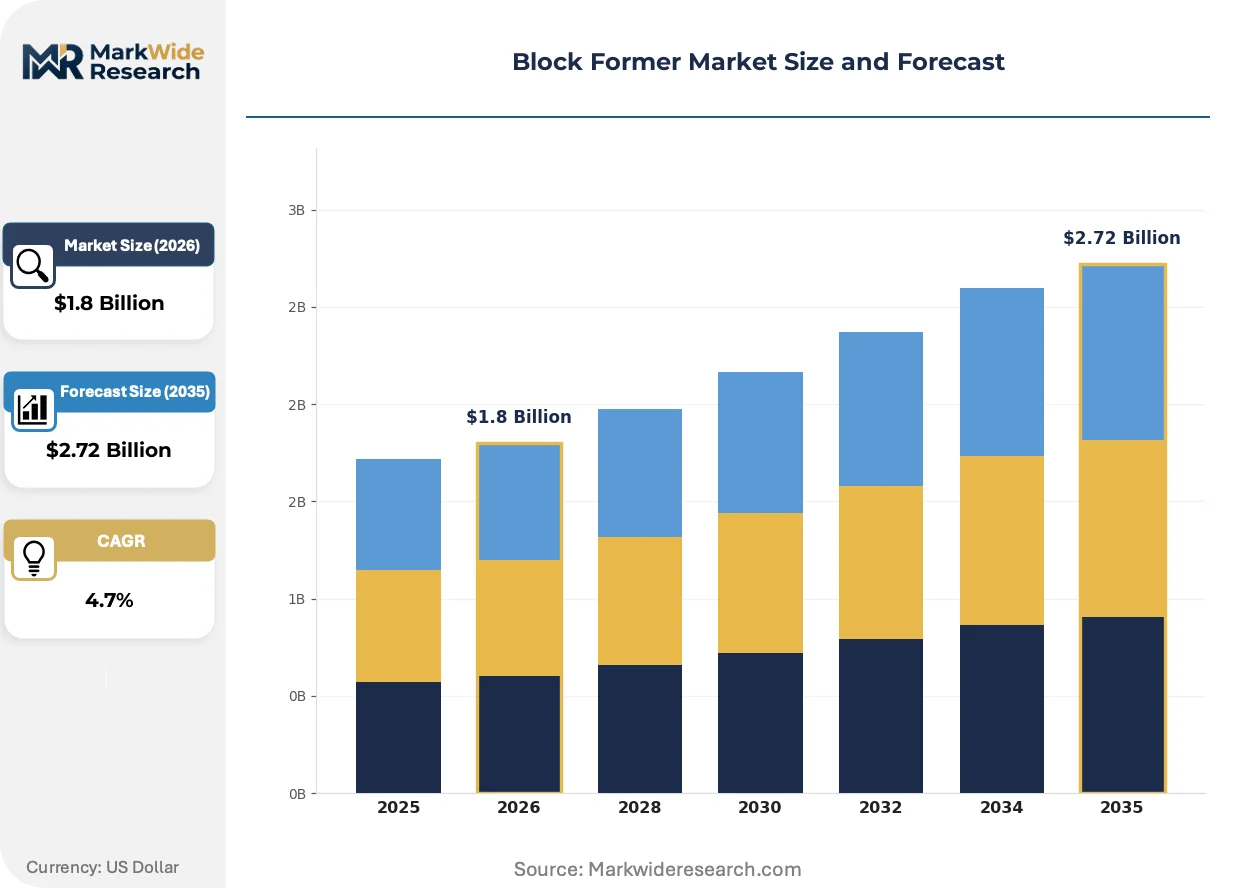
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Block Formers, Hydraulic Block Formers, Pneumatic Block Formers, Electric Block Formers End User: Construction Companies, Manufacturing Firms, Municipalities, Contractors Application: Concrete Production, Brick Making, Lightweight Aggregate, Block Customization Deployment: On-Site, Off-Site, Mobile Operations, Stationary Operations |
| Companies Covered | Block, Shopify POS, Toast, Lightspeed, Clover, Stripe, PayPal, SumUp, Global Payments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Block Former Market Evolving Landscape
Hardware-software integration is redefining competitive differentiation as block former suppliers embed remote monitoring and automated quality control into standard equipment specifications.
Closed-loop hydraulic recovery systems are rewriting energy efficiency benchmarks in continuous production environments. High-throughput manufacturers in the United States are specifying these systems to preempt EPA enforcement actions on diesel particulate output. The technology is compressing operating cost differentials between hydraulic and electric forming architectures.
REACH chemical compliance and F-Gas Regulation phase-down schedules in Europe are accelerating refrigerant and lubricant formulation changes across imported equipment lines. Machinery destined for EU member states must now certify compatibility with low-global-warming-potential fluids. German precast manufacturers are front-running these requirements through early equipment refresh cycles.
Integrated financing packages are displacing traditional equipment leasing for small-scale block producers. Channel intermediaries in India are bundling BIS-certified machines with working capital facilities that match repayment schedules to construction seasonality. This restructuring is most visible among municipal contractors participating in Smart Cities Mission tenders.
Block Former Market Segmentation
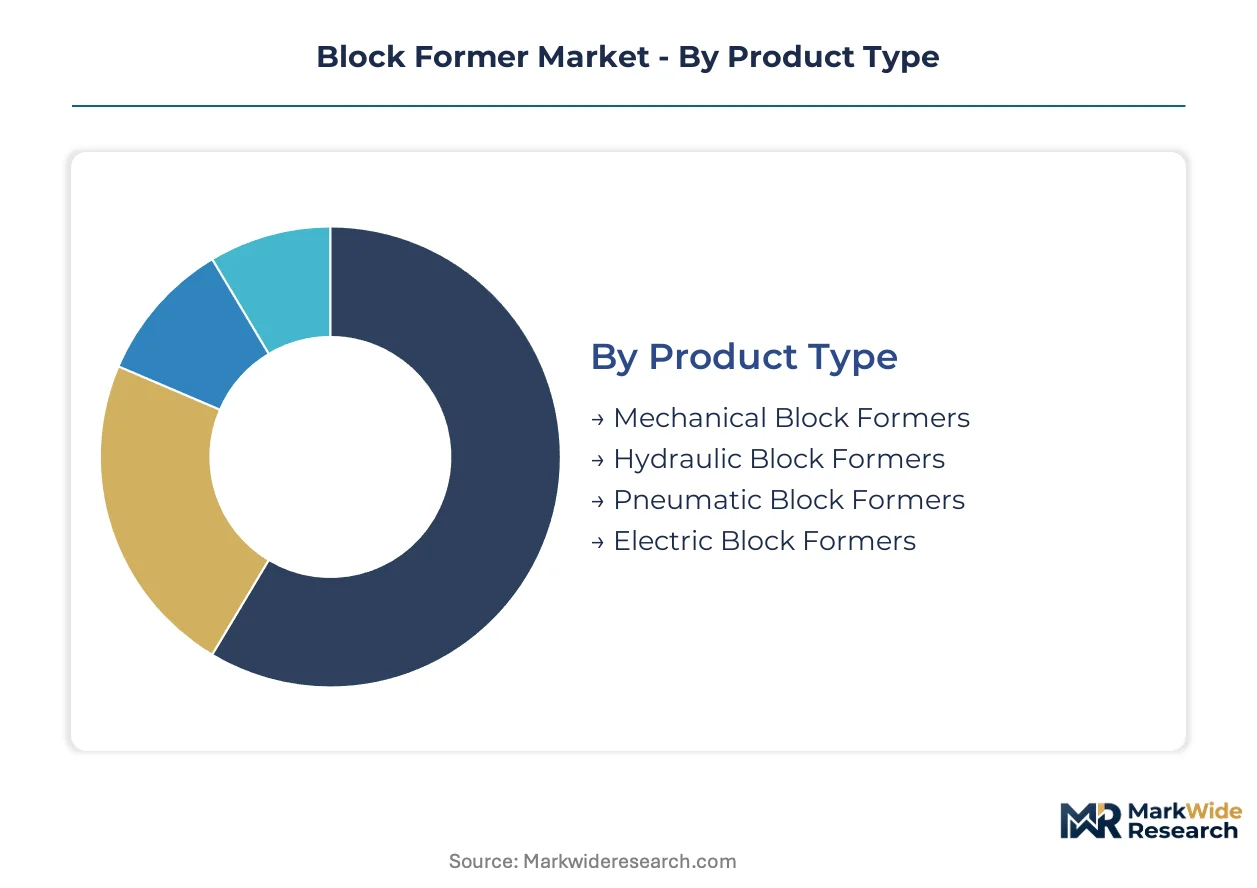
Block former procurement splits sharply between standardized commodity equipment and engineered-to-order systems. Specification choices cascade through energy architecture, mobility requirements, and end-use compliance obligations. Understanding these fracture lines exposes where margin pools concentrate and where technology substitution threatens incumbent positions.
Product Type:
Customization intensity spans from fixed-mechanical platforms to software-configurable electric architectures that adapt forming parameters in real time.
- Hydraulic Block Formers:High-pressure fluid systems deliver compressive forces exceeding 15 MPa for dense structural units. Demand concentrates among German and Japanese precast manufacturers where continuous throughput requirements override energy efficiency concerns. EPA emissions enforcement on diesel-powered auxiliary systems is accelerating retrofit demand for closed-loop hydraulic recovery.
- Electric Block Formers:Servo-motor driven compression achieves precision tolerances within ±1 mm while eliminating hydraulic fluid maintenance. Grid-reliable installations in Indian Smart Cities corridors are specifying these systems to satisfy CEA electrical safety mandates and municipal carbon accounting requirements.
- Mechanical Block Formers:Cam-and-lever architectures dominate cost-sensitive contractor segments in emerging construction markets where capital constraints override automation preferences.
- Pneumatic Block Formers:Compressed-air systems occupy niche applications in lightweight aggregate production where lower compression forces suffice and maintenance simplicity matters.
Most installed capacity flows through hydraulic systems. Expansion is steepest in electric architectures.
End User:
Procurement authority concentrates differently across volume-contracting construction conglomerates and fragmented specialty trade contractors.
- Construction Companies:Large-scale residential and commercial developers specify integrated forming-curing-handling bundles to compress project timelines. Indian PLI scheme beneficiaries are consolidating equipment procurement through domestic assembly partnerships that satisfy BIS certification requirements.
- Manufacturing Firms:Precast concrete producers demand continuous-duty systems with predictive maintenance integration. OSHA silica dust exposure mandates are forcing enclosed-system specifications that smaller fabricators struggle to justify financially.
- Municipalities:Smart Cities Mission procurement in Indian urban corridors favors standardized masonry units with documented compressive strength compliance for infrastructure tenders.
- Contractors:Project-based equipment utilization drives rental market participation and mobile system preferences where deployment flexibility outweighs per-unit efficiency metrics.
Construction companies deploy the dominant share of stationary capacity. Manufacturing firms are gaining specification influence fastest.
Application:
Product mix requirements dictate forming pressure ranges, mold changeover frequency, and surface finish specifications.
- Concrete Production:Standard masonry units for load-bearing walls require densities of 1,800–2,200 kg/m³ achievable through high-pressure hydraulic or advanced electric compression. Indian municipal infrastructure spending sustains volume demand for standardized concrete block specifications.
- Lightweight Aggregate:Expanded clay and shale applications demand lower forming pressures with specialized mold release systems to prevent surface fracturing.
- Brick Making:Fired clay alternatives using cementitious binders require forming systems compatible with abrasive aggregate mixtures and extended mold life cycles.
- Block Customization:Architectural finish blocks with split-face or colored surface treatments need rapid mold changeover capabilities and precision dimension control.
Concrete production absorbs the majority of installed base. Lightweight aggregate applications are climbing the fastest.
Deployment:
Mobility requirements fragment procurement between fixed-plant automation investments and field-deployable forming capabilities.
- Stationary Operations:High-throughput manufacturing facilities in Germany and Japan specify fully automated forming lines with integrated quality control and remote diagnostics. REACH chemical compliance and F-Gas Regulation phase-down schedules are accelerating equipment refresh cycles.
- Mobile Operations:Trailer-mounted or skid-based systems serve remote infrastructure projects and disaster reconstruction where material transport costs exceed equipment mobilization expenses.
- On-Site:Project-specific forming eliminates finished block logistics and enables just-in-time production matching construction sequencing.
- Off-Site:Centralized precast manufacturing achieves economies of scale and quality consistency for multi-project supply contracts.
Stationary operations retain the largest equipment base. Mobile systems are gaining share fastest among specialty contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered hydraulic forming machinery for precast concrete during the post-war reconstruction era, establishing technical standards that still govern high-density compression specifications across industrialized markets.
United States
EPA emissions enforcement and OSHA silica dust mandates are accelerating fleet turnover toward enclosed electric systems. Construction conglomerates in Texas and Florida specify integrated forming-curing bundles to compress multi-project timelines. The Southeast corridor anchors replacement demand as federal infrastructure spending flows through state procurement channels.
Germany
Precast manufacturers in Bavaria and North Rhine-Westphalia demand continuous-duty hydraulic systems with predictive maintenance integration. REACH chemical compliance and F-Gas Regulation phase-down schedules are forcing early equipment refresh cycles. Stuttgart-based machinery clusters supply closed-loop hydraulic recovery systems to preempt regulatory enforcement.
India
PLI scheme incentives and Smart Cities Mission tenders sustain municipal infrastructure spending across Maharashtra and Gujarat. CEA electrical safety mandates and BIS certification requirements shape import eligibility for electric block formers. Domestic assembly partnerships in Tamil Nadu consolidate procurement through certified vendor networks.
China
Dual carbon goals and MIIT industrial efficiency standards redirect capacity expansion toward servo-motor electric architectures. Yangtze River Delta manufacturers supply standardized masonry equipment to Belt and Road construction corridors. Shandong Province clusters dominate mechanical platform production for cost-sensitive export markets.
Japan
METI energy efficiency directives and JIS quality standards sustain premium positioning for precision forming systems. Kansai region precast producers specify automated quality control integration for commercial building contracts. Aging workforce demographics accelerate demand for remote diagnostics and reduced manual intervention.
Block Former Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with hardware-software convergence separating recurring revenue models from equipment-only transactions. The vendor base spans German hydraulic specialists, Chinese scale fabricators, and Indian domestic assemblers. Three archetypes dominate: integrated system bundlers, component-focused suppliers, and financing-anchored distributors. Consolidation pressure is driving strategic partnerships between machinery producers and telematics providers, while geographic expansion through certified assembly partnerships secures BIS and REACH compliance access.
Within the integrated system tier, Block exemplifies hardware-software bundling for mobile operations, while Toast occupies a position adjacent to restaurant-contractor networks that cross-sell payment infrastructure. Shopify POS anchors the financing-anchored archetype by extending e-commerce logistics expertise into small-scale equipment procurement workflows.
| Leading Market Players |
|---|
| Block |
| Shopify POS |
| Toast |
| Lightspeed |
| Clover |
| Stripe |
| PayPal |
| SumUp |
| Global Payments |
| Others |
Value Network & Pricing Analysis
Steel and cement price indices cascade through block former manufacturing costs, compressing margin buffers for hydraulic system producers while amplifying pricing power for electric architecture suppliers with certified component sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hardware-software integrated bundles from standalone mechanical platforms and basic pneumatic units. Price differentiation rests on BIS certification grade and after-sales service bundling rather than raw performance specifications alone. Cost compression in economy-tier mechanical systems is intensifying because Indian domestic assemblers exploit PLI scheme subsidies. Municipal contractors participating in Smart Cities Mission tenders exhibit highest price sensitivity, while German precast manufacturers demonstrate lowest sensitivity due to total-cost-of-ownership calculations.
Supply Chain Analysis
CE marking and BIS certification requirements gate market access for imported electric block formers, forcing upstream qualification investments before downstream pricing authority materializes. Precision hydraulic valves and servo motors concentrate in German, Japanese, and Chinese supplier bases. Component sourcing draws from specialized pump manufacturers in Stuttgart, motor specialists in Osaka, and control system fabricators in Shenzhen. Single-source vulnerability around precision valve clusters creates logistics disruption exposure. Distribution runs through certified assembly partnerships in India and direct OEM channels in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The block former market functions as a stable compounder anchored by municipal infrastructure spending cycles that refresh equipment fleets predictably across decade-long urbanization waves.
For Market Incumbents: Cement aftermarket service revenue streams through predictive maintenance algorithms and remote diagnostics platforms that lock in replacement part demand. Defend specification share in Indian Smart Cities corridors by deepening domestic assembly partnerships that satisfy BIS certification requirements. Electric forming system substitution threatens hydraulic incumbent positions most acutely in grid-reliable urban corridors. For New Entrants and Emerging Players: Telematics providers present partnership opportunities for software-native entrants lacking field service infrastructure. Municipal contractors in tier-two Indian cities represent the most penetrable buyer segment due to fragmented procurement authority and limited incumbent relationships. Financing-anchored distribution models that match repayment schedules to construction seasonality offer viable go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where electromechanical technician scarcity fragments service capabilities across regional labor pools. The five-to-ten year investment horizon favors targets with integrated hardware-software architectures and recurring revenue foundations. Acquisition target archetypes include electric system specialists with CEA electrical safety certifications and established Indian assembly partnerships. The signal to watch is municipal procurement rule changes that elevate total-cost-of-ownership criteria above upfront equipment pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Valve Manufacturing | Captures margin pools concentrated in German and Japanese supplier clusters while reducing logistics disruption exposure. |
| CEA Electrical Safety Certification Investment | Unlocks import eligibility for electric block formers targeting Indian municipal infrastructure tenders. |
| Predictive Maintenance Platform Launch | Converts equipment sales into recurring revenue streams through remote diagnostics and automated quality control integration. |
| Domestic Assembly Partnership in Tamil Nadu | Satisfies PLI scheme requirements and BIS certification pathways for cost-competitive positioning in Indian Smart Cities corridors. |
| Closed-Loop Hydraulic Recovery System Development | Preempts EPA enforcement actions on diesel particulate output while compressing operating cost differentials against electric architectures. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement team discussions, aftermarket service head conversations, and municipal contractor surveys — were reconciled against customs records, BIS certification databases, SEC equipment manufacturer filings, and construction machinery trade association reports. Primary fieldwork with maintenance directors and technical R&D directors validated secondary data on hydraulic component sourcing patterns. Bottom-up equipment shipment tallies and top-down construction spending allocation models were triangulated to anchor volume estimates.
Data-stream reconciliation across product type, end user category, energy architecture, and geographic deployment dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle analysis and infrastructure spending elasticity models. Forecast inputs incorporated EPA emissions enforcement timelines, PLI scheme incentive trajectories, and Smart Cities Mission procurement schedules without year-specific pinning.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel and cement commodity volatility, hydraulic component logistics disruptions, and municipal procurement rule evolutions. A model refresh is warranted upon material change in India's PLI scheme structure or OSHA silica dust exposure mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Europe Real Estate Brokerage Market
Real Estate
Europe Luxury Residential Real Estate Market
Real Estate
Affordable Housing Market
Real Estate
Qatar Co-Working Office Spaces Market
Real Estate
Real Estate Investment Trust (REIT) Market
Real Estate
Egypt Condominiums and Apartments Market
Real Estate
Slovak Republic Facility Management Market
Real Estate
Europe Self Storage Market
Real Estate
China Office Real Estate Market
Real Estate
North America Office Real Estate Market
Real Estate
Europe REIT Market
Real Estate
Malta Facility Management Market
Real Estate
South Korea Residential Real Estate Market
Real Estate
Latin America Soft Facility Management Market
Real Estate
GCC Luxury Market
Real Estate
Sweden Facility Management Market