
 Affordable Housing Market | 2026-2036
Affordable Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Affordable Housing Market Analysis
LEED certification and Enterprise Green Communities standards are unwinding the competitive landscape for affordable housing developers, raising the bar for energy efficiency and material sourcing. Starwood Capital Group leverages its institutional scale to aggregate scattered-site portfolios across high-cost metros. The Michaels Organization anchors its pipeline through long-term public housing authority partnerships. Dominium specializes in adaptive reuse of historic properties, converting obsolete commercial stock into income-restricted residences.
Affordable housing denotes residential units priced below market rates through subsidy mechanisms, rent restrictions, or income-qualified occupancy, typically constructed with cost-engineered materials such as modular wall panels and standardized HVAC packages to hit per-unit budget ceilings below conventional multifamily. Its primary purpose is to bridge the gap between household earnings and housing costs in supply-constrained geographies. Multi-family units dominate transaction volume owing to economies of scale in land acquisition and construction labor, while single-family homes command premium subsidy allocation per door in rural and exurban markets. The financing model segment shows the steepest structural shift as private institutional capital displaces traditional public funding sources in mixed-income developments.
The Department of Housing and Urban Development sets income eligibility thresholds and fair market rent benchmarks that directly determine project feasibility for developers seeking federal tax credits. State housing finance agencies layer additional qualification requirements, including local hiring mandates and community benefit agreements, that extend compliance timelines. Enterprise Green Communities and LEED standards now function as de facto prerequisites for accessing the most competitive subsidy pools. Stakeholders must monitor how evolving environmental justice mapping tools reshape site selection criteria and capital stack composition.
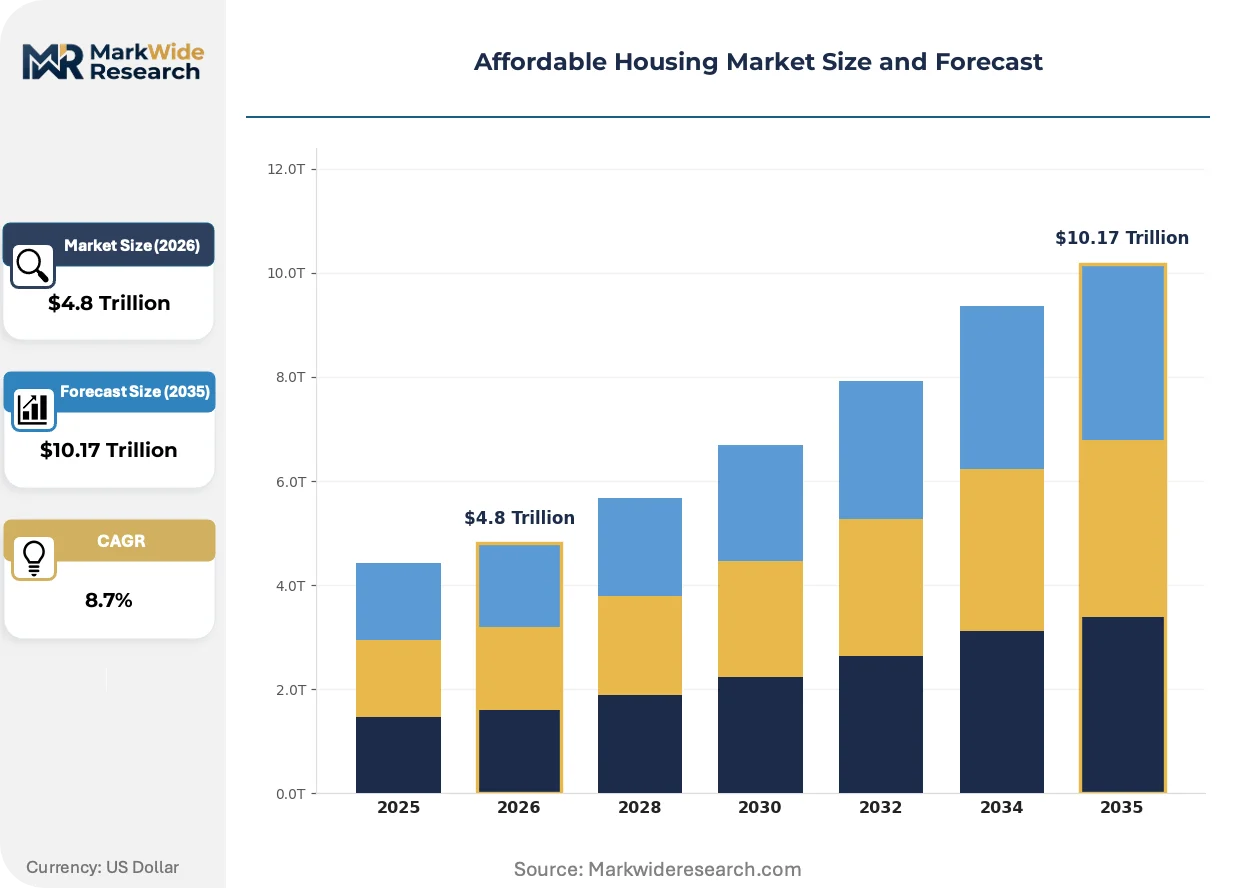
Market Dynamics
Institutional capital displacement of traditional public funding is restructuring project finance, with private investors now controlling capital stack composition in mixed-income developments across high-barrier metros.
Growth Catalysts
- Low-Income Housing Tax Credit:The United States program continues reshaping developer participation criteria, expanding eligible project types and attracting new institutional sponsors into income-restricted housing.
- Modular wall panel systems:Factory-built components compress construction timelines by standardizing envelope assemblies, enabling faster lease-up and reduced carrying costs for subsidy-dependent projects.
- India's housing missions:Government-backed programs targeting informal settlement populations concentrate demand in urban corridors, creating scalable pipeline opportunities for mission-driven developers.
Market Restraints
- Lumber and steel input volatility:Cost-engineered materials face price swings that breach per-unit budget ceilings, forcing value engineering that compromises durability specifications.
- State housing finance agency concentration:Limited allocator capacity in high-demand states extends compliance timelines, creating queue risk for developers competing for annual tax credit allocations.
- Enterprise Green Communities threshold:Energy efficiency mandates function as de facto barriers for small-scale developers lacking technical capacity to model whole-building performance.
Strategic Opportunities
- Adaptive reuse of obsolete commercial:Historic property conversions unlock existing infrastructure, bypassing greenfield land scarcity in supply-constrained central business districts.
- Scattered-site portfolio aggregation:Institutional scale enables acquisition of dispersed small buildings, capturing rental upside in gentrifying neighborhoods while maintaining income restrictions.
- Community benefit agreement mandates:Local hiring requirements create partnership opportunities with workforce development intermediaries, securing site control through political alignment.
Industry Challenges
- Environmental justice mapping complexity:Evolving site selection tools require new analytical capabilities, extending pre-development phases and increasing carry risk.
- LEED documentation burden:Certification timelines compress construction windows, creating coordination friction with subsidy compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Affordable Housing Market |
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $10.17 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Townhouses, Subsidized Housing End User: Low-Income Families, Seniors, First-Time Buyers, Students Distribution Channel: Real Estate Agents, Online Listings, Government Programs, Non-Profits Financing Model: Public Funding, Private Investments, Grants, Low-Interest Loans |
| Companies Covered | Starwood Capital Group, The Michaels Organization, Dominium, L+M Development Partners, The Richman Group Affordable Housing Corporation, Citi Community Capital, KeyBank Real Estate Capital, Genesis Companies, The Community Builders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Affordable Housing Market Emerging Trajectories
Digital design-to-fabrication workflows are collapsing traditional construction phases, compressing project delivery timelines while enabling mass customization of standardized housing components.
Cross-laminated timber (CLT) structural systems are miniaturizing on-site labor requirements, reducing crew sizes and skill thresholds for mid-rise affordable housing envelopes. Workforce housing developers in the Pacific Northwest and Nordic markets are specifying CLT for projects under five stories. The technology is miniaturizing the traditional concrete-and-steel subcontractor base, shifting competitive advantage toward manufacturers with CNC fabrication capacity.
The Department of Housing and Urban Development's evolving fair market rent benchmarks are compressing feasibility margins in high-cost metros. Developers must now underwrite to rent ceilings that lag market reality by twelve to eighteen months. Projects in coastal California and Northeast corridor cities face the steepest underwriting pressure, forcing creative capital stack structuring.
Long-term public housing authority partnerships are displacing speculative development as the dominant pipeline strategy. Anchor tenants with voucher portability provide revenue certainty that attracts private equity into otherwise risk-averse income-restricted assets. This structural preference shift is most visible in southeastern United States markets, where housing authorities control substantial site portfolios and maintain political support for mixed-income redevelopment.
Affordable Housing Market Segmentation
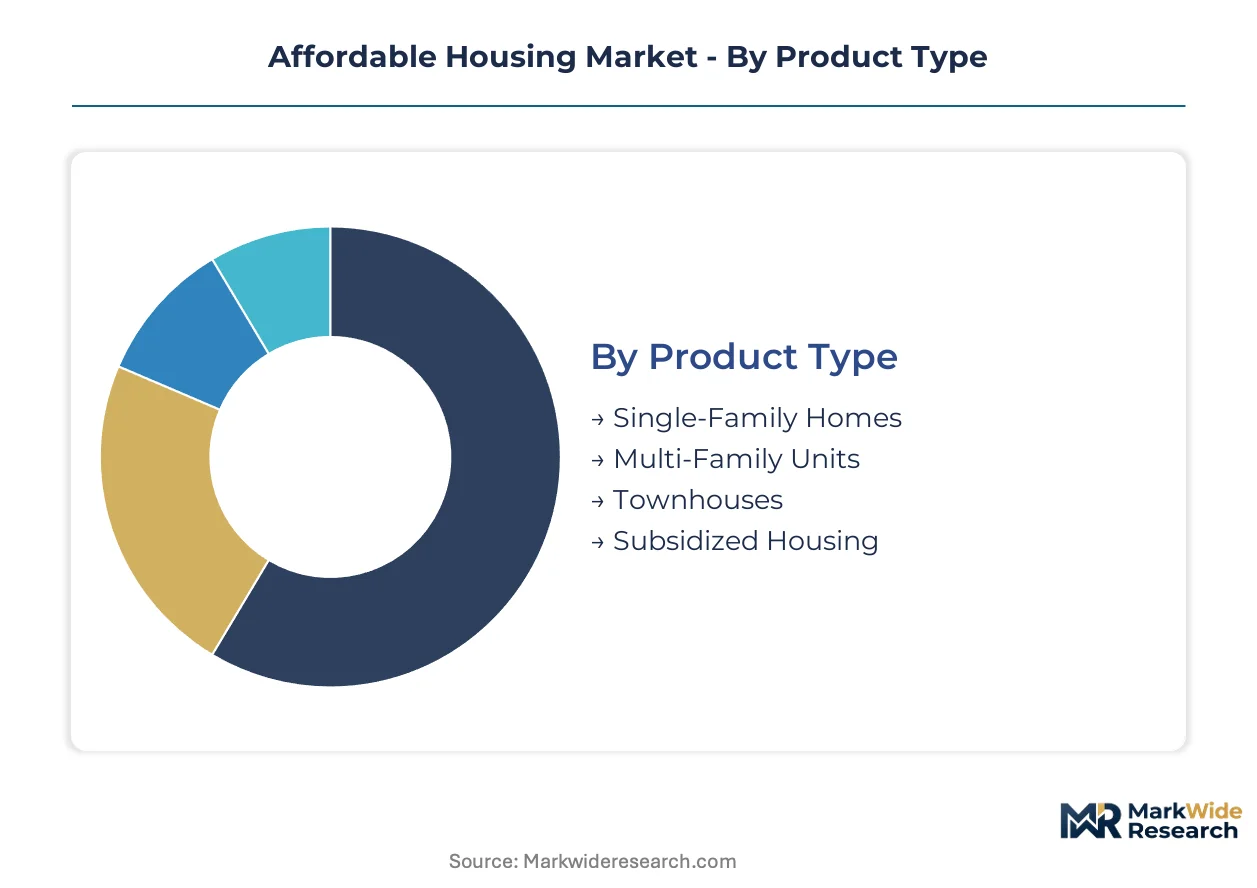
Segmentation in affordable housing reveals how subsidy mechanisms, eligibility criteria, and construction economics allocate capital across distinct housing typologies and beneficiary pools. Developers optimize capital stack composition by matching product type to financing model and distribution channel to end-user qualification pathways.
Product Type:
Margin pools concentrate in multi-family construction where economies of scale in land acquisition and standardized HVAC packages compress per-unit delivery costs below single-family thresholds.
- Multi-Family Units:Mid-rise structures with modular wall panel systems dominate transaction volume through repeatable envelope assemblies and centralized utility infrastructure. Demand concentrates in urban corridors across India and high-cost United States metros where land scarcity forces vertical density.
- Single-Family Homes:Detached structures command premium subsidy allocation per door in rural and exurban markets, though scattered-site aggregation challenges institutional capital deployment. Demand centers on southeastern United States markets where housing authorities control substantial land portfolios for mixed-income redevelopment.
- Townhouses:Attached dwellings balance density with household privacy through stacked floorplates and shared party walls. These units attract first-time buyers in supply-constrained suburban nodes.
- Subsidized Housing:Deeply income-restricted inventory operates under federal rent ceilings set by the Department of Housing and Urban Development. These properties anchor long-term public housing authority partnerships that de-risk private equity participation.
Multi-family units hold installed capacity. Single-family homes are rotating up the share rankings in rural subsidy programs.
End User:
Eligibility thresholds determine project feasibility, with income qualification bands directly shaping unit mix and amenity specifications across development pipelines.
- Low-Income Families:Households earning below area median income thresholds drive the steepest demand expansion as urbanization accelerates informal settlement growth. India's government-backed housing missions target this population specifically, creating scalable pipeline opportunities in Mumbai and Delhi corridors.
- Seniors:Age-restricted communities require accessibility modifications and healthcare proximity that elevate construction costs. Demand clusters in United States sunbelt metros where voucher portability programs anchor revenue certainty.
- First-Time Buyers:Entry-level ownership candidates access down-payment assistance and mortgage credit certificates through state housing finance agencies. These buyers concentrate in markets with active community land trust activity.
- Students:Near-university affordable inventory competes with market-rate purpose-built student housing through income-restricted bed leases. University partnerships in Pacific Northwest markets specify cross-laminated timber construction for projects under five stories.
Low-income families command the largest addressable pool. Seniors are climbing the fastest as demographic aging reshapes eligibility demand.
Distribution Channel:
Channel selection determines compliance burden and lease-up velocity, with government-program pathways extending timelines but securing subsidy capture.
- Government Programs:Low-Income Housing Tax Credit allocations through state housing finance agencies constitute the primary pipeline gate for institutional developers. These channels layer local hiring mandates and community benefit agreements that extend pre-development phases.
- Real Estate Agents:Broker networks facilitate scattered-site portfolio aggregation for private investors targeting gentrifying neighborhoods. These channels capture rental upside while maintaining income restrictions through deed covenants.
- Online Listings:Digital platforms compress vacancy periods for market-rate affordable units not tied to waitlist-managed public inventory. Property management software integration enables real-time income verification.
- Non-Profits:Mission-driven developers leverage 501(c)(3) status to access philanthropic capital and land donations. These channels dominate adaptive reuse of historic properties where tax credit stacking requires complex partnership structures.
Government programs hold installed capacity. Online listings are gaining share fastest as digital verification tools reduce administrative friction.
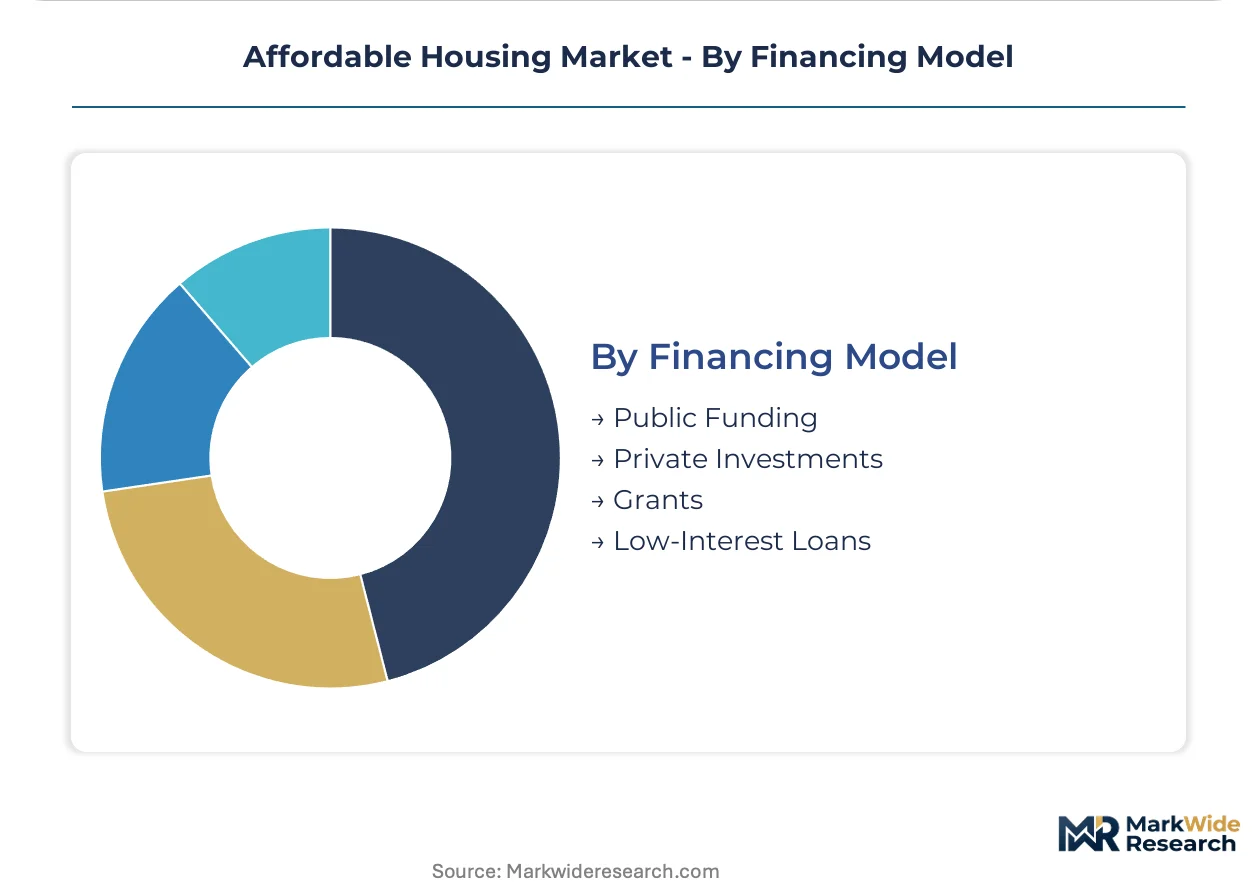
Financing Model:
Capital stack composition is rotating toward private institutional sources as traditional public funding faces federal budget pressure and allocation queue risk.
- Private Investments:Institutional sponsors now control capital stack composition in mixed-income developments across high-barrier metros. Starwood Capital Group leverages this shift to aggregate scattered-site portfolios at scale.
- Public Funding:Direct federal appropriations for public housing capital repairs have contracted, displacing speculative development as a pipeline strategy. Remaining allocations concentrate in housing authority redevelopment partnerships.
- Grants:Philanthropic and community development financial institution capital fills gap financing for projects exceeding Low-Income Housing Tax Credit basis limits. These sources prioritize environmental justice mapping compliance.
- Low-Interest Loans:State housing finance agency bond proceeds offer below-market debt for qualifying borrowers. These instruments face capacity constraints in high-demand states that extend compliance timelines.
Private investments hold installed capacity. Low-interest loans are rotating up the share rankings as state agencies expand bond issuance capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional investors and mission-driven developers concentrate in markets where subsidy programs align with land scarcity pressures. Buyer archetypes span public housing authorities seeking mixed-income redevelopment partners, private equity aggregating scattered-site portfolios, and non-profits leveraging philanthropic capital for adaptive reuse projects.
United States
Low-income families and voucher-portable seniors drive demand across high-cost coastal metros and southeastern sunbelt markets. The Department of Housing and Urban Development sets fair market rent benchmarks and income eligibility thresholds that determine project feasibility for developers seeking federal tax credits. Pipeline concentration clusters in California's coastal cities and the Northeast corridor, where rent ceilings lag market reality by twelve to eighteen months.
India
Urbanization accelerates informal settlement growth, concentrating demand among households earning below area median income thresholds in Mumbai and Delhi corridors. Government-backed housing missions targeting informal settlement populations reshape developer participation criteria and create scalable pipeline opportunities. Construction activity concentrates in Maharashtra and Gujarat, where vertical density mandates force mid-rise multifamily development.
Germany
Aging demographics and refugee integration programs expand eligibility demand for income-restricted inventory in supply-constrained central business districts. EU Green Deal energy efficiency mandates and KfW development bank financing programs layer compliance requirements onto subsidy-dependent projects. Adaptive reuse of obsolete commercial stock dominates pipeline activity in Berlin and the Ruhr industrial region.
United Kingdom
First-time buyers and low-income families compete for entry-level ownership through community land trusts and shared equity schemes. Homes England grant programs and local authority planning obligations require community benefit agreements that extend pre-development phases. Development gravity centers on London's outer boroughs and Greater Manchester, where greenfield land scarcity forces brownfield remediation.
Canada
Students and young professionals drive demand for near-university affordable inventory competing with market-rate purpose-built student housing. Canada Mortgage and Housing Corporation financing programs and provincial rent supplement agreements anchor revenue certainty for mixed-income developments. Pipeline activity concentrates in Ontario's Golden Horseshoe and British Columbia's Lower Mainland, where foreign buyer taxes redirected capital toward rental construction.
Affordable Housing Market Vendor Landscape
Player mix skews toward institutional capital sponsors and mission-driven non-profits competing for tax credit allocations and public housing authority partnerships. Market structure fragments across scattered-site aggregators, adaptive reuse specialists, and vertically integrated developers controlling land through long-term public land leases. Dominant archetypes include institutional scale players leveraging balance sheet capacity, public-private partnership specialists anchoring pipelines through housing authority relationships, and non-profit mission-driven developers accessing philanthropic capital. Competitive moves concentrate on portfolio aggregation through scattered-site acquisition and adaptive reuse of obsolete commercial properties to bypass greenfield land scarcity.
Within the institutional capital tier, Starwood Capital Group and L+M Development Partners occupy positions exemplifying scale-driven scattered-site portfolio aggregation across high-barrier metros. The Michaels Organization anchors the public-private partnership archetype through long-term housing authority relationships that de-risk private equity participation. Dominium represents the adaptive reuse specialization, converting historic commercial properties into income-restricted residences through complex tax credit stacking structures.
| Leading Market Players |
|---|
| Starwood Capital Group |
| The Michaels Organization |
| Dominium |
| L+M Development Partners |
| The Richman Group Affordable Housing Corporation |
| Citi Community Capital |
| KeyBank Real Estate Capital |
| Genesis Companies |
| The Community Builders |
| Others |
Supply Flow & Price Mechanics
Factory-built component scale in modular wall panel manufacturing compresses per-unit envelope costs below site-built alternatives, concentrating supply leverage with CNC-enabled fabricators while anchoring price floors to steel and lumber indexation. This scale dynamic forces smaller developers into cost-plus pass-through contracts that transfer commodity volatility risk downstream to housing finance agencies and institutional equity partners.
Pricing Analysis
Cost-plus contracts indexed to Random Lengths lumber futures and Midwest hot-rolled coil steel dominate project procurement, with developers layering 15-20% overhead margins atop material pass-throughs. Price differentiation rests on LEED certification tier and modular fabrication scale, with Enterprise Green Communities-rated projects commanding 8-12% construction cost premiums. Pricing pressure intensifies as HUD fair market rent benchmarks lag actual market rents by twelve to eighteen months in coastal California and Northeast corridor metros, squeezing feasibility margins. Low-income housing tax credit syndicators exhibit highest price sensitivity due to yield compression requirements, while institutional permanent equity shows lowest sensitivity given long-dated hold periods.
Supply Chain Analysis
Great Lakes waterway transit underwrites bulk material delivery to upper Midwest modular fabrication clusters, creating seasonal chokepoints when winter ice restricts barge movement. Factory-built envelope assembly concentrates in Michigan, Indiana, and Ohio, drawing from Canadian softwood lumber and domestic steel coil. Cross-laminated timber feedstock rests on Pacific Northwest Douglas fir harvest cycles and Nordic spruce import channels. Single-source vulnerability runs through concentrated HVAC package suppliers in Mexico and Texas. Distribution runs through housing finance agency-mandated general contractor networks that layer compliance documentation onto material procurement timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The affordable housing sector is undergoing high-growth disruption as Low-Income Housing Tax Credit program expansion attracts institutional capital displacement of traditional public funding, creating structural openings for new capital stack architects.
For Market Incumbents: Compound scattered-site portfolio scale through accelerated acquisition of dispersed small buildings in gentrifying neighborhoods, leveraging balance sheet capacity to underwrite longer hold periods than emerging competitors. Defend against modular fabrication entrants by anchoring exclusive relationships with state housing finance agencies through community benefit agreement commitments. Vertical integration into in-house property management of income-restricted assets secures lease-up velocity and compliance documentation quality that tax credit syndicators prioritize. For New Entrants and Emerging Players: Adaptive reuse project pipelines represent the most penetrable white-space target, as incumbent developers under-serve historic property conversions due to complex tax credit stacking requirements and extended entitlement timelines. Target southeastern United States housing authority partnerships where political alignment and voucher portability programs de-risk revenue certainty. Enter through joint venture structures with established non-profit 501(c)(3) entities that control site access and philanthropic capital relationships. For Investors and Strategic Acquirers: Public-private partnership specialists with embedded housing authority relationships constitute the highest-conviction acquisition archetype, as long-term pipeline visibility commands premium valuations in fragmented markets. Frame five-to-ten year viability around demographic aging and urbanization tailwinds that expand voucher-eligible populations. Monitor state housing finance agency allocation queue depth as the critical inflection signal—capacity expansion or allocation formula changes would re-rate development feasibility across high-demand states.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Reuse Pipeline Development | Historic property conversions bypass greenfield land scarcity in supply-constrained central business districts. |
| Modular Fabrication Scale-Up | Factory-built envelope assemblies compress construction timelines and reduce on-site labor cost exposure. |
| Housing Authority Partnership Deepening | Long-term public land leases and voucher portability agreements anchor revenue certainty for mixed-income developments. |
| Green Certification Investment | Enterprise Green Communities and LEED compliance unlocks most competitive Low-Income Housing Tax Credit subsidy pools. |
| Scattered-Site Portfolio Aggregation | Institutional scale acquisition of dispersed small buildings captures rental upside while maintaining income restrictions. |
Methodological Framework
The analysis maps multi-family unit construction, single-family scattered-site development, adaptive reuse conversion, and subsidized housing inventory segments, each validated through developer executives, state housing finance agency allocation officers, tax credit syndication specialists, and property management operators. Primary interview intelligence combines with secondary validation against HUD fair market rent databases, state QAP allocation records, LIHTC syndication pricing indices, and modular fabrication capacity registries. Bottom-up project pipeline enumeration triangulates against top-down subsidy allocation flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by product type, end-user income qualification band, distribution channel pathway, and financing model composition. CAGRs derive from subsidy allocation trajectory analysis, urbanization rate projections, and demographic eligibility expansion patterns. Forecast inputs incorporate LIHTC basis limit adjustments, state bond issuance capacity expansion, and environmental justice mapping tool adoption curves.
Forecasts assume regulatory continuity in HUD income eligibility and fair market rent methodologies, state housing finance agency allocation formulas, and Low-Income Housing Tax Credit program authority; material policy shifts would require re-modeling. Specific risk factors include federal appropriation contractions for public housing capital repairs, state allocator capacity constraints extending compliance timelines, and commodity price volatility breaching per-unit budget ceilings. Practitioners should keep alternative scenarios live as LIHTC program reauthorization debates and green building standard evolution reshape capital stack composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
India Manufactured Homes Market
Real Estate
South Africa Facility Management Market
Real Estate
Latin America Facility Management Market
Real Estate
Global Office Space Market
Real Estate
Norway Facility Management Market
Real Estate
Spain Manufactured Homes Market
Real Estate
GCC REIT Market
Real Estate
Residential Property Management Market
Real Estate
Indonesia Residential Real Estate Market
Real Estate
Saudi Arabia Flexible Office Space Market
Real Estate
Japan Office Real Estate Market
Real Estate
France Residential Real Estate Market
Real Estate
China Facility Management Market
Real Estate
Bahrain Co-Working Office Space Market
Real Estate
Proptech Market
Real Estate
Denmark Luxury Residential Real Estate Market