
 Sweden Facility Management Market | 2026-2036
Sweden Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Facility Management Market Analytics
Healthcare facilities is broadening its share of outsourced facility management across Swedish county councils, driven by aging infrastructure and staffing constraints. Coor Service Management leverages its integrated service platforms to anchor large public sector contracts in Stockholm and Gothenburg. ISS Facility Services AB sustains nationwide coverage through dense branch networks and standardized operating protocols. Securitas differentiates by bundling security services with broader facility operations for corporate clients.
Facility management encompasses the professional coordination of building operations, maintenance, cleaning, security, and energy systems through integrated service delivery models, typically governed by ISO 41001 standards for facility management systems and Swedish building code requirements for energy performance. Its primary commercial purpose centers on optimizing building lifecycle costs while ensuring regulatory compliance and occupant productivity. Maintenance services and cleaning services represent mature revenue pools with stable contract renewal rates, while smart building solutions and IoT applications capture accelerating investment as Swedish property owners pursue operational transparency and predictive asset management. Outsourced contracts dominate the procurement landscape, though managed services arrangements are gaining traction among institutional clients seeking outcome-based accountability.
The Swedish Work Environment Authority enforces occupational health standards that directly shape cleaning protocols and maintenance scheduling across commercial properties. Boverket's building regulations and the EU Energy Performance of Buildings Directive mandate systematic energy auditing and retrofit planning, creating compliance-driven demand for technical facility services. Sweden's Environmental Code imposes waste sorting and circular economy obligations that facility managers must operationalize on-site. Stakeholders should monitor how the EU AI Act and evolving Swedish data protection interpretations affect automated building management systems and vendor liability frameworks.
Market Dynamics
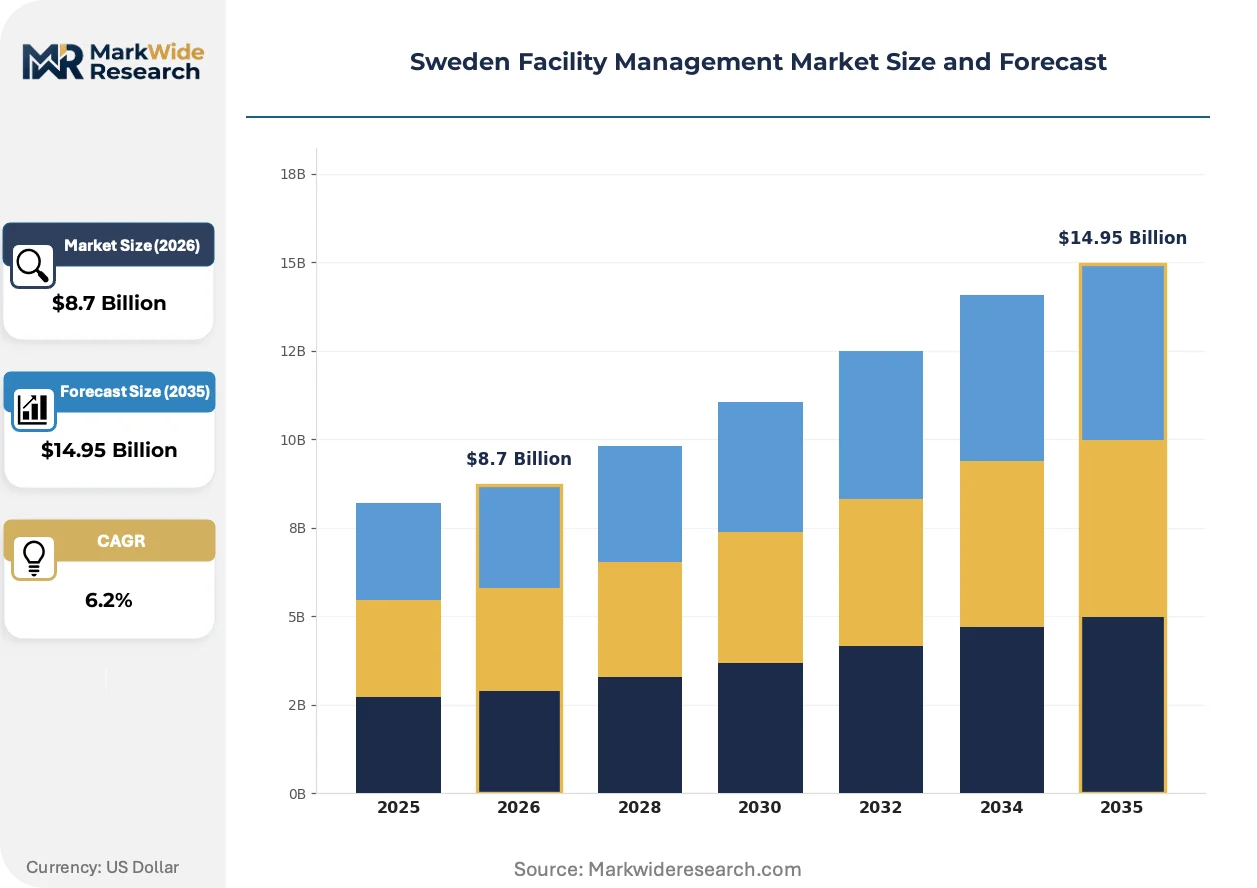
Sweden's facility management sector is pivoting toward predictive asset management as EU Green Deal retrofit mandates compress building energy performance timelines. Public sector outsourcing accelerates while IoT platforms rewrite operational accountability standards.
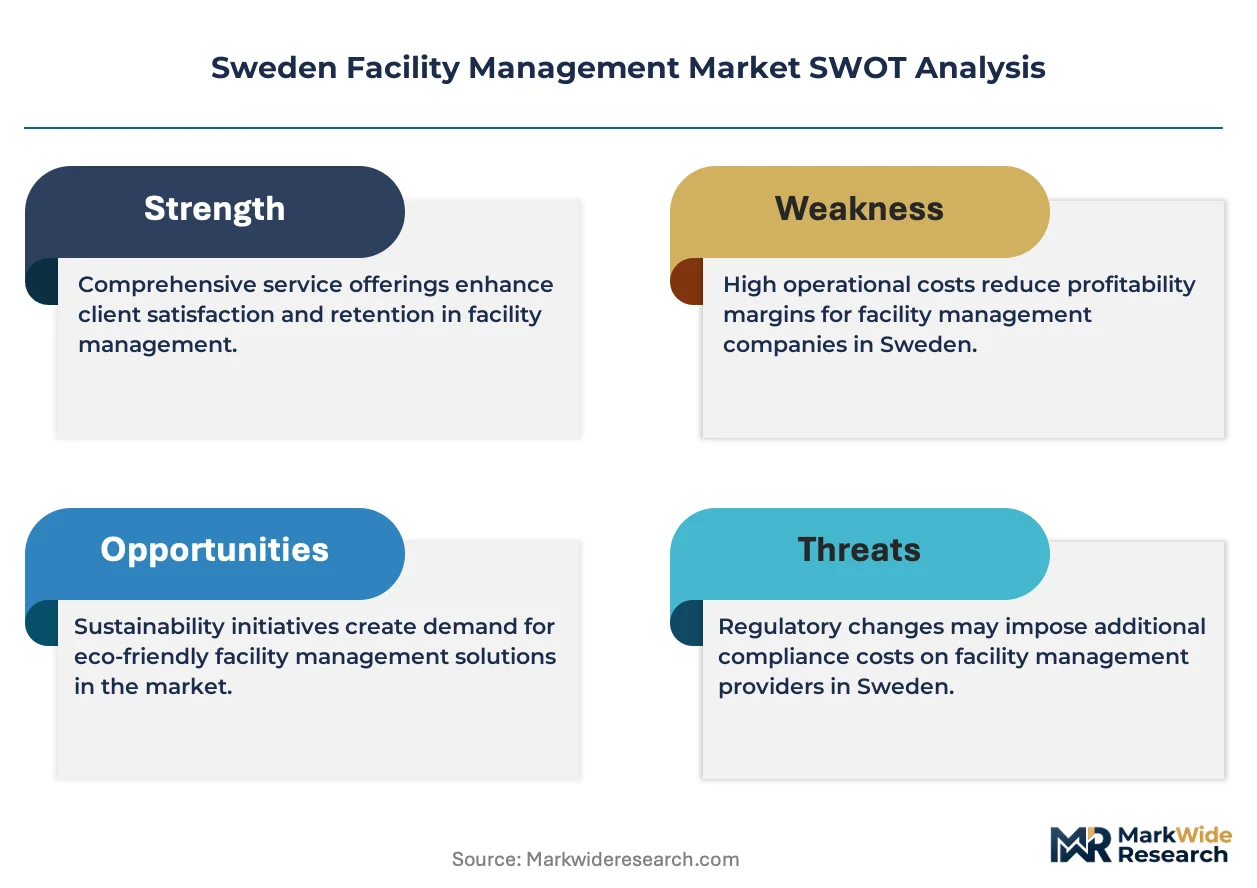
Growth Catalysts
- EU Energy Performance of Buildings Directive:Sweden's systematic energy auditing requirements for public buildings create compliance-driven demand for technical facility services and retrofit coordination.
- Healthcare infrastructure aging:Swedish county councils are expanding outsourced maintenance portfolios as hospital staffing constraints intensify and capital renewal backlogs mount.
- Stockholm commercial density:Concentrated premium office stock in the capital region sustains integrated service contract volumes and multi-site account consolidation.
Market Restraints
- Specialized technician scarcity:Sweden's tight labor market limits availability of certified building automation engineers and energy systems specialists.
- Input cost volatility:District heating tariffs and electricity price fluctuations compress fixed-margin service contracts.
- Legacy system interoperability:Proprietary building management protocols from 1990s-era installations obstruct seamless IoT integration.
Strategic Opportunities
- University city expansion:Uppsala and Lund present underpenetrated markets where research campus energy optimization mandates outpace local service capacity.
- EU AI Act compliance services:Automated building systems classification requirements create advisory revenue streams for facility managers deploying predictive maintenance algorithms.
- Circular economy operationalization:Sweden's Environmental Code waste sorting obligations position facility managers as on-site circular economy coordinators.
Industry Challenges
- ISO 41001 certification timelines:Swedish facility management providers face extended audit cycles as accreditation bodies adapt to integrated service scope expansions.
- Multi-vendor platform integration:Corporate clients demand unified dashboards across security, cleaning, and energy systems, straining middleware development resources.
- Work Environment Authority protocol compliance:Occupational health enforcement intensifies documentation burdens for cleaning and maintenance scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Facility Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, Landscaping Services End User: Healthcare Facilities, Educational Institutions, Corporates, Retail Spaces Contract Type: Outsourced Contracts, In-house Services, Managed Services, Consulting Agreements Technology: Smart Building Solutions, Energy Management Systems, Integrated Software Platforms, IoT Applications |
| Companies Covered | Lassila & Tikanoja, Nordic Facility Management, ISS Facility Services AB, Kiona, Vallmo, Coor Service Management, Newsec Property Asset Management, Bentley Systems Incorporated, Securitas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Facility Management Market Evolving Landscape
Digital twin technology and outcome-based contracting models are restructuring how Swedish property owners evaluate facility service partnerships. Regulatory pressure and labor scarcity accelerate automation investment across building portfolios.
IoT sensor networks deployed across HVAC and lighting systems are rewriting operational transparency standards in Swedish commercial real estate. Property owners in Stockholm's financial district are adopting these platforms fastest, compressing traditional reactive maintenance cycles into predictive intervention schedules. The technology is rewriting competitive positioning by privileging vendors with proprietary data analytics capabilities over conventional service scale.
The EU AI Act's risk classification framework for automated building management systems imposes new liability structures on facility managers deploying algorithmic controls. Swedish property owners must now document human oversight protocols for AI-driven energy optimization. Healthcare facilities face the steepest compliance burden as patient safety considerations elevate building system classifications.
Corporate procurement departments are consolidating multi-site facility contracts under unified key performance indicator frameworks. Real estate investment trusts are displacing fragmented local vendor relationships with national integrated service agreements. This concentration is most visible in Gothenburg's logistics corridor, where distribution center operators prioritize single-accountability models over specialized subcontractor networks.
Sweden Facility Management Market Segmentation
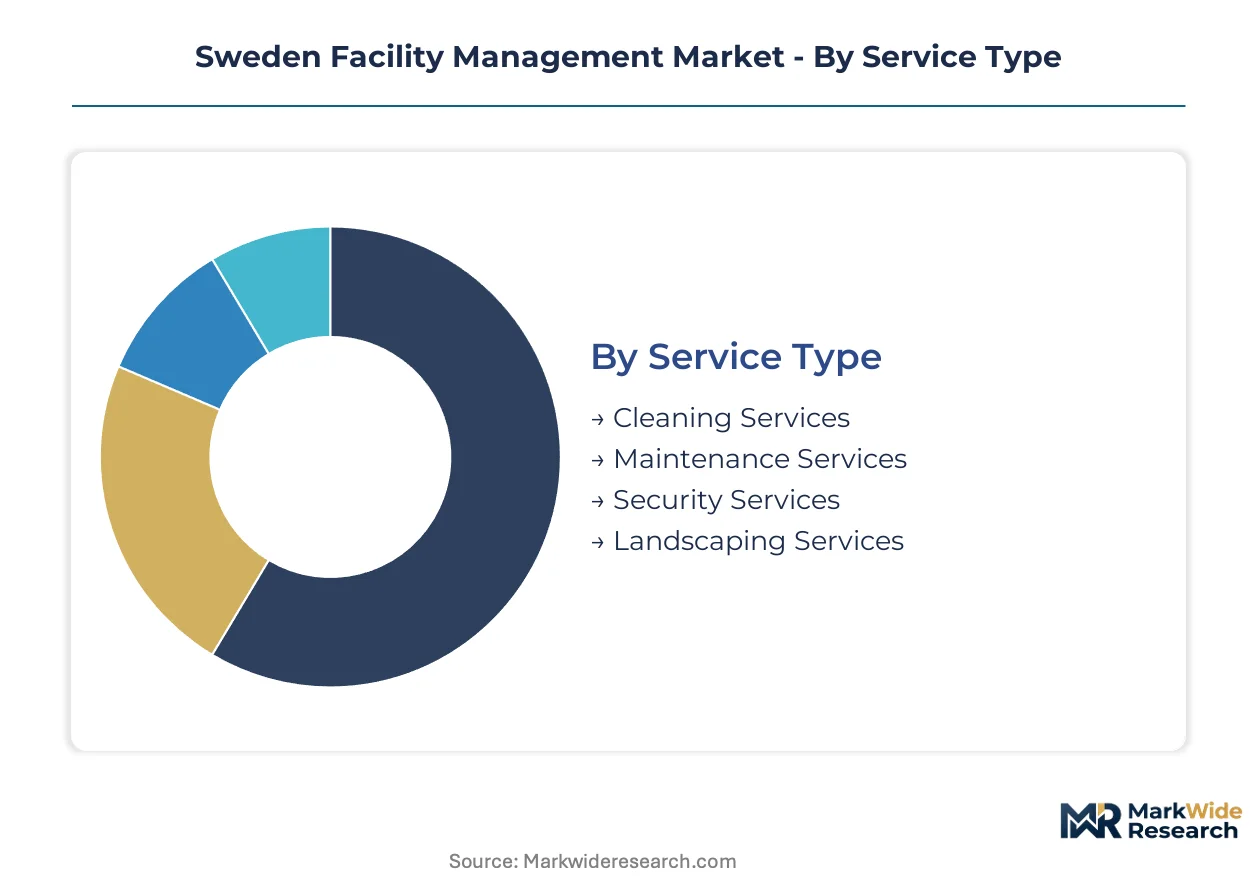
Facility management procurement in Sweden follows distinct logics across service categories, end-use verticals, and technology integration levels. Contract structure and technology adoption increasingly determine vendor selection criteria and margin profiles.
Service Type:
Buyer decisions in this category pivot on labor cost predictability versus specialized technical capability requirements.
- Cleaning Services:Labor-intensive operations governed by Swedish Work Environment Authority protocols for chemical handling and shift scheduling. County council healthcare facilities in Stockholm and Västra Götaland concentrate demand as outsourcing expands to address staffing gaps.
- Maintenance Services:Technical asset preservation spanning HVAC, electrical, and building fabric systems. Commercial property owners in Stockholm's financial district prioritize predictive maintenance platforms to compress lifecycle costs under EU Green Deal retrofit timelines.
- Security Services:Personnel-based and technology-augmented protection for corporate campuses and public infrastructure.
- Landscaping Services:Seasonal exterior maintenance with growing integration of sustainable water management under Sweden's Environmental Code.
Maintenance Services leads on scale; Smart Building Solutions (within Technology) leads on momentum.
End User:
Vertical specialization requirements create divergent procurement patterns across institutional buyer types.
- Healthcare Facilities:County council hospitals and primary care centers with stringent infection control and 24/7 operational continuity mandates. Aging infrastructure across Swedish regions drives technical facility services expansion.
- Corporates:Premium office occupiers in Stockholm CBD and logistics operators in Gothenburg corridor. These buyers consolidate multi-site contracts under unified KPI frameworks.
- Educational Institutions:Universities in Uppsala and Lund with research campus energy optimization requirements.
- Retail Spaces:Shopping centers and grocery chains with high-frequency cleaning cycles and seasonal demand fluctuation.
Healthcare Facilities leads on contract value concentration; Corporates leads on procurement consolidation velocity.
Contract Type:
Risk transfer preferences and outcome accountability standards shape arrangement selection.
- Outsourced Contracts:Full-service delegation with fixed-price or cost-plus structures. Dominant across Swedish public sector procurement where county councils transfer operational risk to specialized providers.
- Managed Services:Outcome-based accountability with performance-linked remuneration. Gaining traction among institutional real estate investors seeking operational transparency.
- In-house Services:Direct employment models retained primarily for strategic or sensitive facilities.
- Consulting Agreements:Advisory engagements for energy auditing and compliance planning under Boverket regulations.
Outsourced Contracts leads on volume; Managed Services leads on growth trajectory steepness.
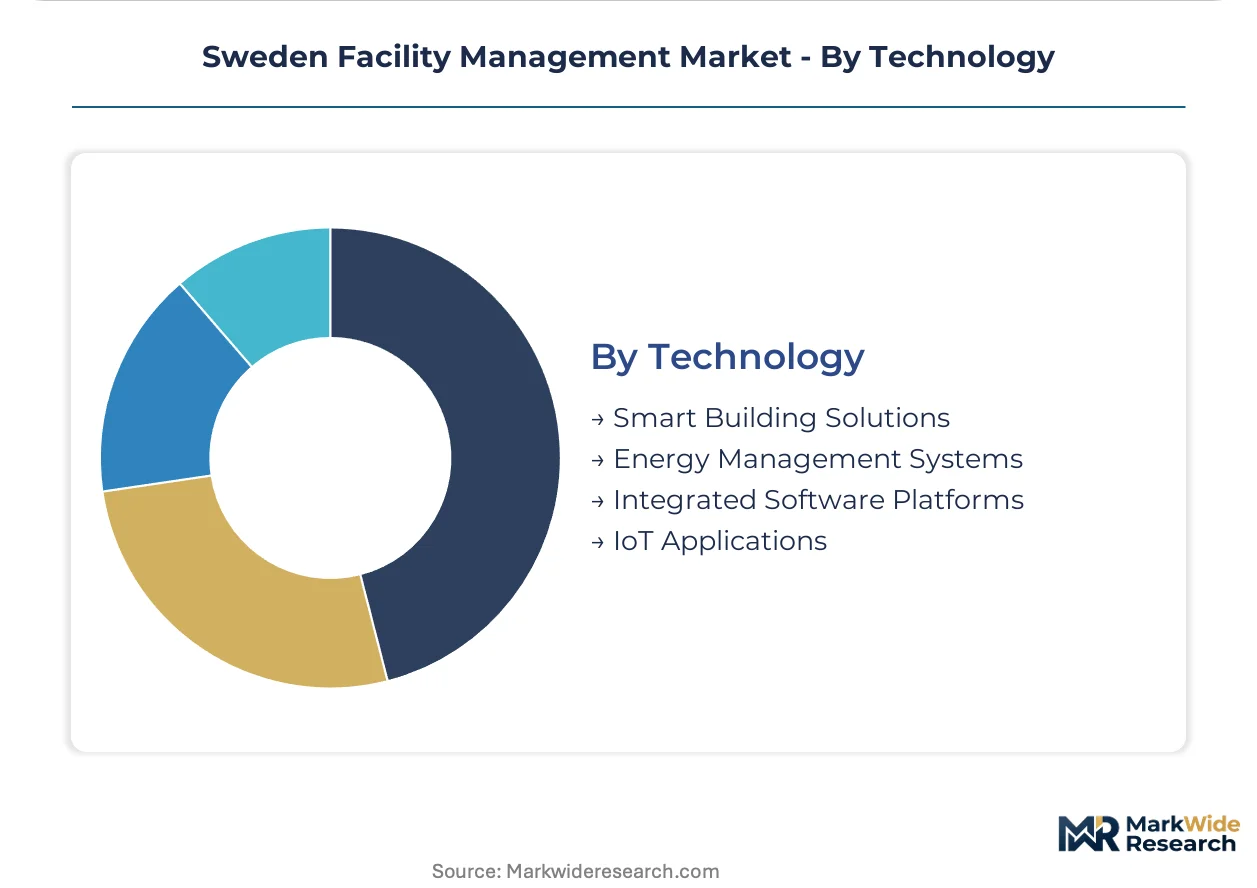
Technology:
Data infrastructure maturity and interoperability capabilities determine competitive positioning.
- Smart Building Solutions:Digital twin platforms and automated control systems for HVAC, lighting, and access. Stockholm commercial property owners deploy these fastest to meet EU Energy Performance of Buildings Directive audit requirements.
- IoT Applications:Sensor networks enabling predictive intervention and real-time performance monitoring. These systems compress traditional reactive maintenance cycles across Swedish building portfolios.
- Energy Management Systems:Software platforms for district heating optimization and electricity load balancing.
- Integrated Software Platforms:Unified dashboards spanning security, cleaning, and technical services for multi-site corporate accounts.
IoT Applications leads on investment velocity; Integrated Software Platforms leads on procurement priority for large accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's commercial density anchors facility management demand concentration across Swedish sub-regions. County council healthcare infrastructure and university research campuses drive divergent procurement patterns between metropolitan cores and secondary cities.
Stockholm County
Premium office stock in the capital's financial district sustains integrated service contract volumes. The EU Energy Performance of Buildings Directive mandates systematic energy auditing for public buildings. Kista Science City and Solna's hospital cluster concentrate multi-site corporate and healthcare facility management demand.
Västra Götaland
Gothenburg's logistics corridor and automotive manufacturing base generate industrial facility services requirements. Boverket building regulations enforce energy retrofit planning across municipal property portfolios. The Port of Gothenburg and surrounding distribution centers prioritize single-accountability service models over fragmented subcontractor networks.
Skåne
Lund's research campus and Malmö's commercial expansion outpace local technical service capacity. Sweden's Environmental Code imposes waste sorting obligations that facility managers operationalize on-site. The Øresund region's cross-border property investments demand unified Nordic service standards.
Uppsala
University campus energy optimization mandates exceed available smart building expertise. The Swedish Work Environment Authority enforces occupational health standards shaping cleaning protocols. Biotech and life science clusters concentrate specialized facility requirements.
Norrland
District heating infrastructure and remote healthcare facilities create maintenance access challenges. EU Green Deal retrofit timelines compress building energy performance targets for aging public stock. Mining and forestry industry towns sustain industrial facility services demand.
Sweden Facility Management Market Competitive Landscape
Consolidation dominates the current landscape as integrated service platforms absorb specialized regional operators. The market presents a tiered structure with national scale providers, Nordic-focused specialists, and technology-augmented security integrators. Three archetypes define competitive positioning: bundled infrastructure operators, pure-play facility specialists, and security-led converged service providers. M&A activity and IoT platform development represent the dominant competitive vectors reshaping vendor relationships.
Among Nordic-anchored service providers, Coor Service Management and ISS Facility Services AB exemplify the integrated infrastructure archetype through their multi-site public sector presence. Securitas occupies a distinct position bundling security operations with broader facility accountability. Kiona represents the technology-native segment deploying building automation platforms. These three anchors illustrate how scale, convergence, and digital capability stratify competitive positioning across Swedish procurement channels.
| Leading Market Players |
|---|
| Lassila & Tikanoja |
| Nordic Facility Management |
| ISS Facility Services AB |
| Kiona |
| Vallmo |
| Coor Service Management |
| Newsec Property Asset Management |
| Bentley Systems Incorporated |
| Securitas |
| Others |
Value Network & Pricing Analysis
District heating tariff indices cascade through Swedish facility management pricing tiers, compressing margins for fixed-price contracts while elevating cost-plus arrangements in municipal portfolios. Energy input volatility feeds directly into service rate negotiations across Stockholm's commercial core and county council healthcare networks.
Pricing Analysis
Input-cost pass-through from electricity and heating tariffs dominates contract renegotiation cycles between facility managers and public sector clients. Three-tier pricing structure across integrated platform, bundled service, and single-service levels differentiates vendors by technical capability depth and geographic coverage density. Pricing pressure stems from district heating rate volatility and certified technician wage inflation, particularly acute in fixed-margin cleaning and maintenance agreements. County council healthcare facilities exhibit highest price sensitivity due to budget caps, while corporate premium office clients prioritize outcome accountability over unit cost.
Supply Chain Analysis
ISO 41001 certification and Swedish Work Environment Authority compliance credentials gate vendor participation in public sector procurement frameworks. Equipment and technology sourcing concentrates in Germany, Denmark, and Finland for building automation systems and IoT sensor hardware. Supply chains draw from specialized component manufacturers for HVAC controls, security integration modules, and predictive analytics software platforms. Single-source vulnerability exists for proprietary building management system protocols from 1990s-era installations that obstruct seamless IoT integration. Distribution runs through direct vendor-client relationships for large accounts and regional subcontractor networks for geographic coverage extension.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sweden Facility Management Market functions as a regulatory compounder where EU Green Deal retrofit mandates and Boverket energy auditing requirements continuously generate compliance-driven service demand.
For Market Incumbents: Acquire predictive analytics platforms and IoT-enabled building automation capabilities to defend against technology-native entrants. Consolidate regional subcontractor networks in university cities like Uppsala and Lund where energy optimization mandates outpace local technical capacity. ISO 41001 certification investment remains essential for public sector contract retention as accreditation bodies extend audit cycles for integrated service scope expansions. For New Entrants and Emerging Players: The premium-to-economy price-point gap in smart building solutions presents entry opportunity for specialized IoT platform vendors targeting mid-market commercial property owners. Underpenetrated university research campuses in Lund and Uppsala offer white-space expansion with less entrenched incumbent relationships. Go-to-market positioning should emphasize EU AI Act compliance advisory bundled with automated building system deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-augmented facility specialists possessing proprietary data analytics capabilities and established county council relationships. Long-term viability favors vendors with demonstrated predictive maintenance platform deployment and cross-border Nordic service standardization. Monitor EU Energy Performance of Buildings Directive enforcement intensity as inflection indicator for technical facility services demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Enables predictive maintenance deployment meeting EU Green Deal retrofit timelines for Stockholm commercial properties. |
| County Council Contract Consolidation | Captures healthcare facility outsourcing expansion driven by aging infrastructure and staffing constraints. |
| EU AI Act Compliance Advisory | Creates differentiated revenue stream from automated building system classification and human oversight protocol documentation. |
| University City Geographic Expansion | Addresses energy optimization mandate gaps in Lund and Uppsala research campuses with limited local technical capacity. |
| Backward Integration into Energy Auditing | Secures Boverket-mandated compliance service revenue and deepens client relationship stickiness. |
Research Methodology
Coverage spans Stockholm County, Västra Götaland, Skåne, Uppsala, and Norrland, with primary inputs from each sub-region informing demand pattern calibration. Primary interviews with facility management executives, county council procurement officers, commercial property portfolio managers, and building automation engineers combined with secondary validation from Boverket regulatory filings, Swedish Work Environment Authority enforcement data, EU Energy Performance of Buildings Directive implementation reports, and county council outsourcing tender databases. Bottom-up contract value aggregation and top-down market sizing triangulation cross-validated segment-level estimates.
Rate-of-change decomposition across service type, end user vertical, contract structure, and technology integration level shaped the analytical framework over the projection horizon. CAGRs derived from historical contract renewal velocity, public sector outsourcing penetration trends, and smart building investment intensity across Swedish commercial real estate. Segmentation modeling incorporated energy retrofit mandate compliance timelines, healthcare infrastructure aging curves, and IoT platform adoption rates by property owner category.
Caveats apply where EU AI Act implementation guidance, district heating tariff regulatory reform, or Swedish labor market policy shifts could materially shift the outlook. Forecasts reflect assumptions regarding sustained public sector outsourcing appetite and continued EU Green Deal enforcement intensity. A model refresh is warranted upon material change in Boverket building regulation amendment schedules or county council capital budget allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Global Facility Management Software Market
Facility Management
Warehouse Management Service Market
Facility Management
Switzerland Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Facility Management Services Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Bahrain Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
China Facility Management Market