
 Europe Self Storage Market | 2026-2036
Europe Self Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Self Storage Market Intelligence
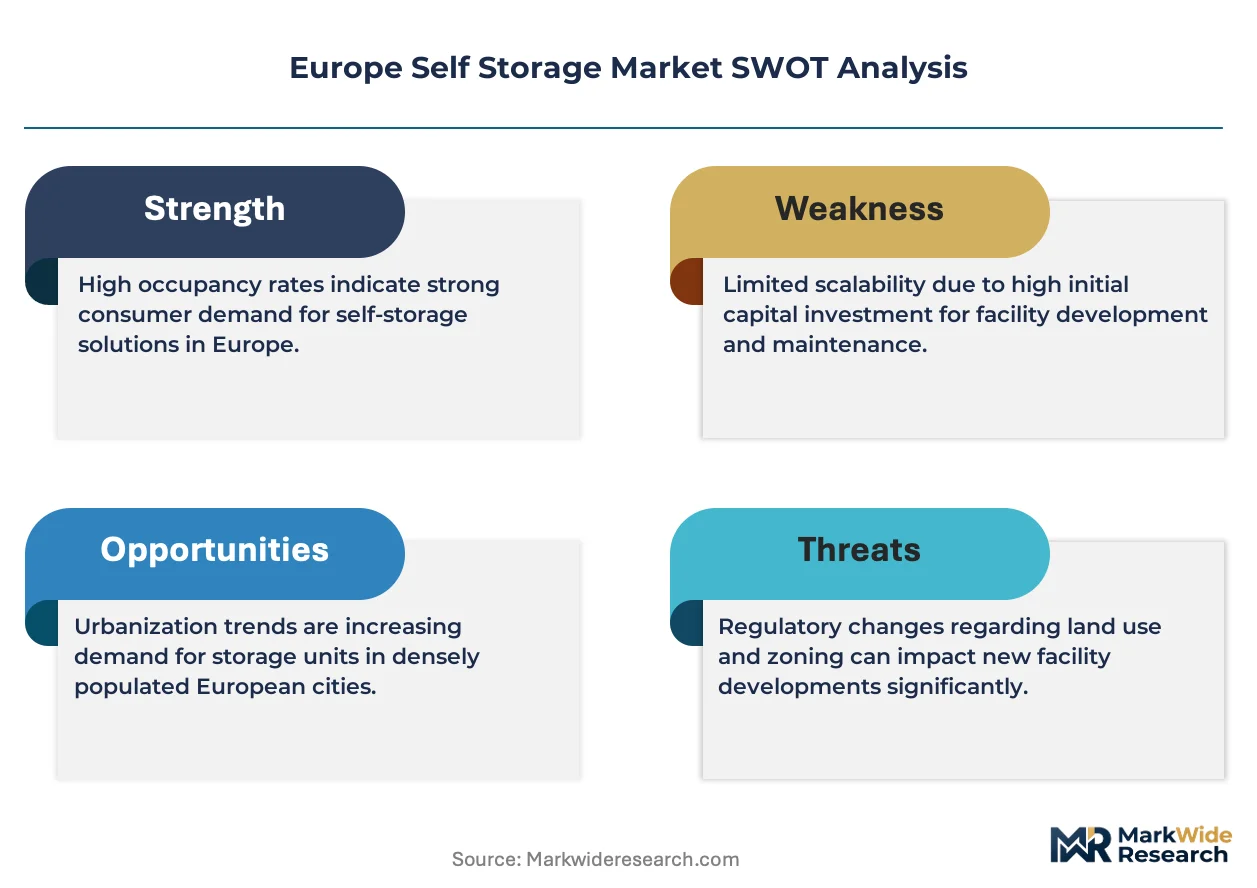
Smart access control and IoT-enabled unit monitoring is narrowing the operational gap between premium and standard storage offerings across Europe. Shurgard Self Storage SA leverages its REIT structure to sustain portfolio expansion in dense metropolitan zones. Safestore Holdings PLC anchors its position through backward integration into property development and facility management. Big Yellow Group PLC dominates the UK landscape with purpose-built assets in Greater London and commuter corridors.
Europe self storage refers to the commercial provision of rentable, secured space for personal or business goods, typically housed in steel-reinforced concrete or prefabricated metal structures with climate regulation capabilities between 15°C and 25°C and humidity controls below 60%. The primary purpose is to absorb spatial constraints from urbanization, housing transitions, and inventory overflow for households and enterprises. Indoor storage leads the product type mix in Northern Europe where weather exposure risks are pronounced, while mobile storage is expanding fastest among business customers seeking just-in-time logistics flexibility. Rental services command the largest revenue pool, though insurance services carry superior per-unit margins as operators bundle coverage into standard contracts.
REACH and the EU Green Deal shape facility construction standards by mandating low-emission materials and energy performance disclosures across member states, while GDPR governs digital tenant data collected through automated access systems. National regulators including Germany's KBA for transportable mobile units and France's CNIL for biometric access data add compliance layers that operators must navigate. Stakeholders should monitor how upcoming EU building efficiency directives will alter retrofit economics for aging facilities in city centers.
Market Dynamics
Urban densification across Northern Europe is compressing residential square footage per capita, pushing household overflow into commercial storage facilities while EU building efficiency mandates force operators to retrofit aging assets.
Growth Catalysts
- EU Green Deal retrofit mandates:Facility operators in Germany, France, and the Netherlands are upgrading insulation and installing solar arrays to meet energy performance disclosures, creating demand for climate-controlled units that command rental premiums.
- Small business inventory overflow:E-commerce merchants in Greater London and Paris are leasing flexible warehousing to manage just-in-time logistics without committing to long-term industrial leases.
- Biometric access systems:IoT-enabled smart locks and mobile app entry are reducing staffing costs while improving tenant security perceptions across metropolitan facilities.
Market Restraints
- Construction cost volatility:Steel and concrete input prices fluctuate with energy markets, squeezing margins on new purpose-built facilities in dense urban cores where land scarcity already elevates project costs.
- GDPR compliance friction:Biometric data collection for automated access systems triggers France's CNIL oversight requirements, adding legal review cycles and technical safeguards that delay deployment.
- Self-storage substitution:On-demand logistics platforms and micro-fulfillment centers are capturing inventory overflow from small retailers who previously leased traditional units.
Strategic Opportunities
- Eastern European underpenetration:Poland, Czech Republic, and Romania exhibit storage square footage per capita at one-third of UK levels, presenting first-mover expansion potential in Warsaw and Prague logistics corridors.
- Mobile storage convergence:Portable container solutions paired with last-mile delivery partnerships are capturing business customers seeking inventory flexibility without fixed facility commitments.
- CSRD disclosure requirements:Large facility operators can leverage energy efficiency investments to satisfy corporate sustainability reporting mandates and attract institutional capital.
Industry Challenges
- Retrofit capex intensity:Aging concrete structures in central London and Paris require multimillion-euro upgrades to meet EU building efficiency directives, straining REIT distribution requirements.
- Biometric system integration:Legacy access control infrastructure in 1990s-era facilities demands complete replacement rather than incremental upgrade, complicating tenant transition management.
- Climate engineering talent scarcity:HVAC specialists capable of maintaining 15°C-25°C temperature bands with sub-60% humidity controls command premium wages in tight Northern European labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Self Storage Market |
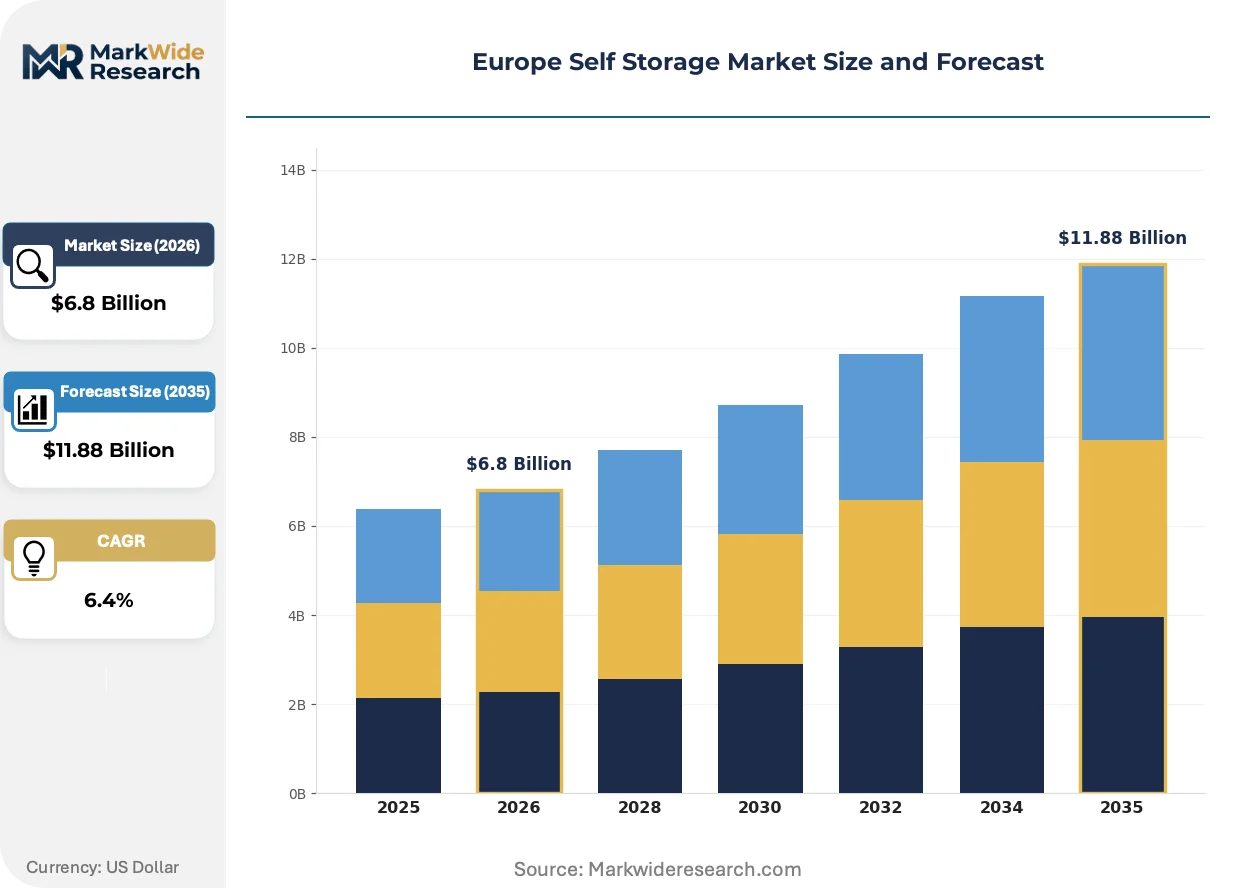
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Storage, Outdoor Storage, Climate-Controlled Units, Mobile Storage Customer Type: Individuals, Businesses, Students, Military Personnel Service Type: Rental Services, Management Services, Packing Supply Services, Insurance Services Access Mode: 24/7 Access, Limited Access, By Appointment Only, Drive-Up Access |
| Companies Covered | Self Storage Group ASA, MyPlace SelfStorage GmbH, Shurgard Self Storage SA, Nettolager, Pelican Self Storage, Safestore Holdings PLC, SureStore Ltd, W Wiedmer AG, Big Yellow Group PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Self Storage Market Strategic Shifts & Innovations
Facility operators are deploying sensor networks and automation to compress operational costs while regulatory pressure accelerates building performance upgrades. These shifts are narrowing the service gap between premium and standard offerings.
IoT-enabled environmental monitoring is digitizing unit-level climate control across Northern European facilities. Shurgard and Safestore are deploying wireless sensors that track temperature, humidity, and door access in real time. This infrastructure is digitizing the operational boundary between climate-controlled premium units and standard storage, allowing dynamic pricing adjustments based on actual conditions rather than fixed tier assignments.
REACH chemical safety regulations and the EU Green Deal are mandating low-emission materials in new construction and major renovations. Facility developers must now source formaldehyde-free insulation and low-VOC coatings for interior finishes. German operators face additional KBA transport certification for mobile storage units, compressing deployment timelines for container-based services.
Households are unbundling storage from residential square footage as urban housing costs consume larger income shares. Young professionals in Amsterdam, Berlin, and Manchester are treating storage as a subscription utility rather than a transitional solution. This behavioral shift is most visible in London, where commuters lease units near transit hubs to decouple living space from possession storage.
Europe Self Storage Market Segmentation
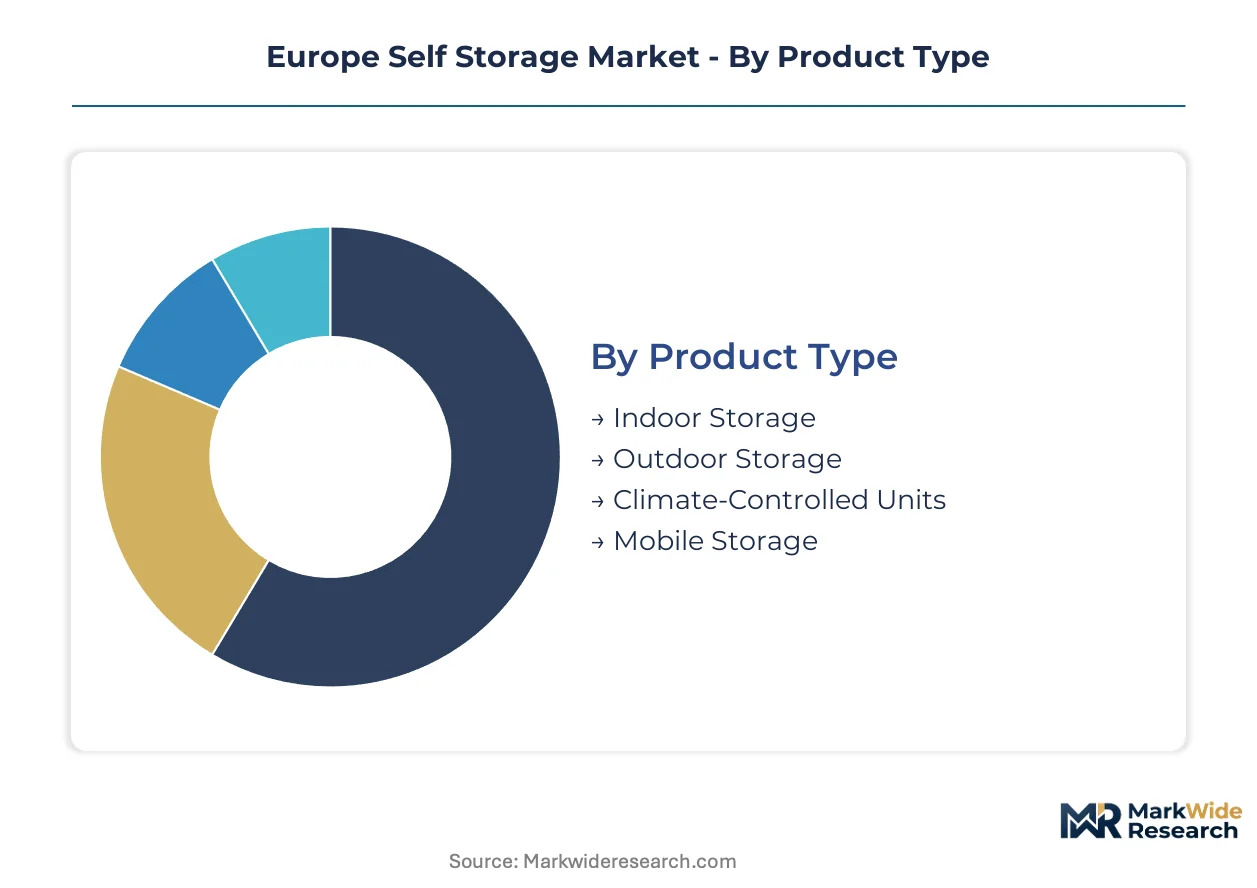
Segmentation in the Europe self storage market reveals how facility operators allocate capital across physical configurations, customer cohorts, and service tiers. Understanding these splits illuminates where pricing power concentrates and where operational complexity escalates.
Product Type:
Cost tier differentiation across physical storage configurations determines facility design economics and rental rate structures throughout Northern and Western Europe.
- Indoor Storage:Steel-reinforced concrete or prefabricated metal structures shield contents from weather exposure. Demand concentrates in the United Kingdom, Germany, and the Netherlands where precipitation risks and urban density push households toward enclosed units.
- Climate-Controlled Units:HVAC systems maintain 15°C-25°C temperature bands with sub-60% humidity controls for sensitive inventory. E-commerce merchants in Greater London and Paris command premium rates for pharmaceutical and electronics storage compliant with EU Green Deal energy disclosures.
- Outdoor Storage:Open-air or canopy-covered spaces for vehicles, construction equipment, and bulk materials. German KBA transport regulations govern mobile unit certification in this category.
- Mobile Storage:Portable containers delivered to customer locations. Warsaw and Prague logistics corridors show fastest adoption among small businesses seeking just-in-time flexibility without fixed facility commitments.
Indoor storage holds installed capacity. Mobile storage is rotating up the share rankings.
Customer Type:
Application focus varies sharply across end-use segments, with business customers demanding service-level agreements that residential users rarely negotiate.
- Businesses:Inventory overflow from e-commerce and just-in-time logistics drives contract terms spanning 12-36 months. French small retailers face substitution pressure from micro-fulfillment centers in dense urban cores.
- Individuals:Household overflow from housing transitions and downsizing. Young professionals in Amsterdam, Berlin, and Manchester treat storage as a subscription utility rather than transitional solution.
- Students:Seasonal demand spikes during academic term breaks. University towns in the United Kingdom and Germany exhibit pronounced summer vacancy cycles.
- Military Personnel:Deployment-driven storage needs with standardized insurance requirements. British and German base corridors sustain dedicated facility clusters.
Individual accounts generate volume throughput. Business contracts are climbing the margin contribution ladder fastest.
Service Type:
Margin structure diverges dramatically between commoditized rental streams and value-added services that operators bundle for retention.
- Rental Services:Core lease revenue from unit square meterage. Purpose-built assets in Greater London and commuter corridors command rate premiums through Shurgard and Big Yellow Group portfolios.
- Insurance Services:Per-unit coverage bundled into standard contracts. Superior margin profile compared to base rental, with GDPR-compliant data handling required for biometric-linked policy administration.
- Management Services:Third-party facility operation for institutional landlords. Safestore Holdings PLC anchors this segment through backward integration into property development and facility management.
- Packing Supply Services:Ancillary retail of boxes, tape, and protective materials. Low-margin attachment sale with high frequency in household move-in cohorts.
Rental services dominate revenue tonnage. Insurance services are expanding the profit pool most aggressively.
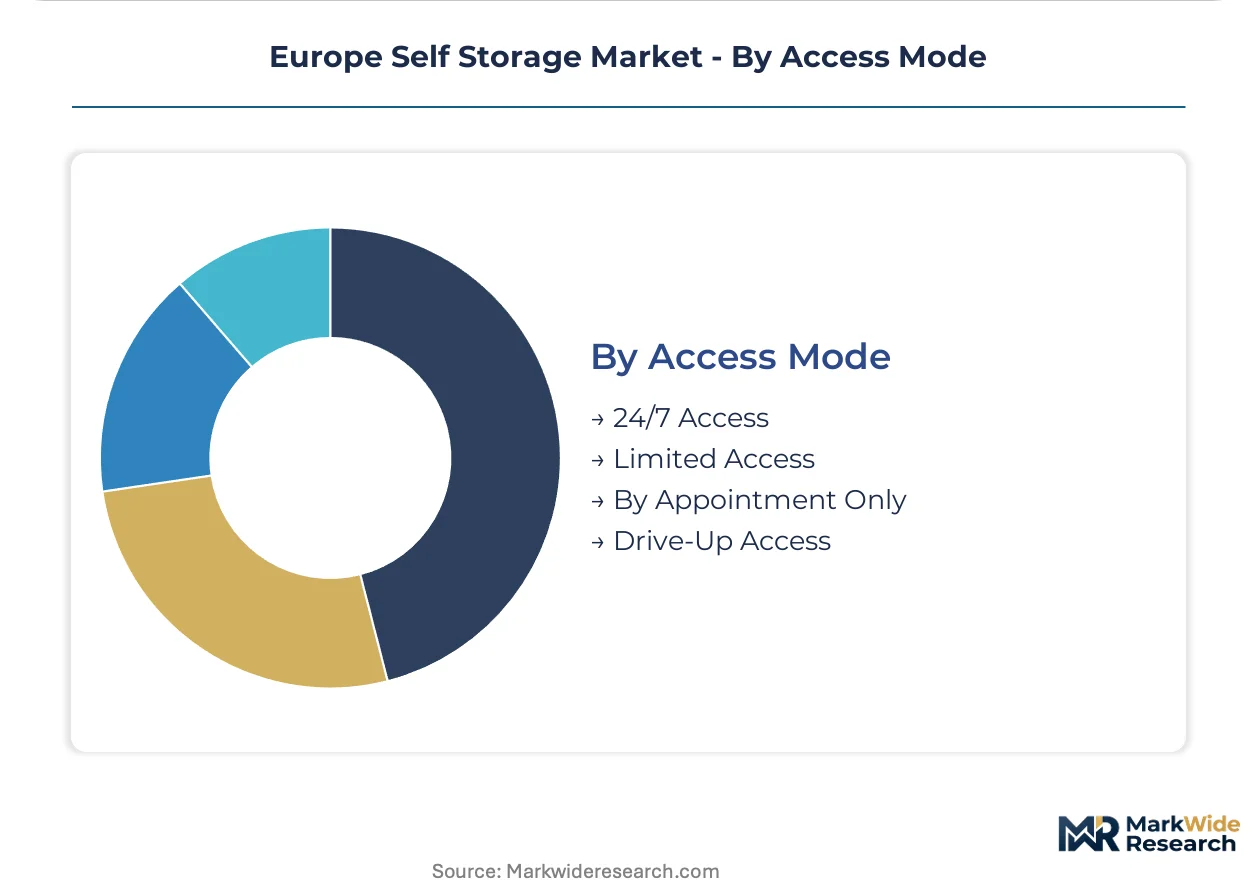
Access Mode:
Customer type and facility vintage shape access infrastructure investment, with newer builds embedding IoT capabilities that legacy assets struggle to retrofit.
- 24/7 Access:Biometric smart locks and mobile app entry reduce staffing costs. France's CNIL oversight requirements add legal review cycles for biometric data collection.
- Drive-Up Access:Ground-level units for vehicle loading. Preferred by business customers with palletized inventory in German industrial zones.
- Limited Access:Staffed hours with supervised entry. Older central London and Paris facilities maintain this model due to retrofit capex constraints.
- By Appointment Only:White-glove service for high-value collections. Niche positioning in Swiss and Luxembourg markets with wealth concentration.
24/7 access commands technology investment. Drive-up access is gaining preference among logistics-intensive users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German operators export mobile storage solutions to Polish and Czech logistics corridors, while UK facility managers license operational platforms to Dutch and Belgian developers seeking rapid market entry.
United Kingdom
Young professionals in Manchester and Bristol treat storage as a subscription utility rather than transitional solution. GDPR governs biometric data collection through automated access systems deployed across Greater London facilities. Purpose-built assets in commuter corridors command rental premiums through climate-controlled unit differentiation.
Germany
E-commerce merchants in Berlin and Hamburg lease flexible warehousing for just-in-time inventory management. KBA transport certification governs mobile storage unit deployment, compressing timelines for container-based services. Industrial zones in North Rhine-Westphalia exhibit strongest demand for drive-up access configurations among palletized inventory users.
France
Small retailers in Paris face substitution pressure from micro-fulfillment centers capturing traditional overflow demand. CNIL oversight requirements add legal review cycles for biometric access data collection. Île-de-France facilities retrofit aging concrete structures to meet EU building efficiency disclosure mandates.
Netherlands
Amsterdam households unbundle storage from residential square footage as urban housing costs consume larger income shares. REACH chemical safety regulations mandate low-emission materials in facility renovations. Rotterdam logistics corridors attract mobile storage adoption among businesses seeking port-proximate inventory flexibility.
Poland
Warsaw exhibits storage square footage per capita at one-third of UK levels, presenting first-mover expansion potential. EU Green Deal energy performance disclosures shape new facility construction standards. Prague logistics corridors show fastest mobile storage adoption among small businesses seeking just-in-time flexibility.
Europe Self Storage Market Key Industry Players
On the supply side, the industry is consolidating around REIT-structured operators with captive development capabilities and independent regional specialists with localized site control. Three archetypes dominate: vertically integrated REITs with backward integration into property development, mid-scale national chains with standardized operational platforms, and independent owner-operators with single-market density. Competitive intensity centers on portfolio expansion through brownfield acquisition and technology-enabled operational differentiation.
Among UK-listed REITs, Big Yellow Group PLC and Safestore Holdings PLC exemplify the integrated development archetype, while Shurgard Self Storage SA anchors the continental European expansion vector with its Brussels-based corporate structure. MyPlace SelfStorage GmbH represents the German-speaking market specialist tier with localized operational expertise.
| Leading Market Players |
|---|
| Self Storage Group ASA |
| MyPlace SelfStorage GmbH |
| Shurgard Self Storage SA |
| Nettolager |
| Pelican Self Storage |
| Safestore Holdings PLC |
| SureStore Ltd |
| W Wiedmer AG |
| Big Yellow Group PLC |
| Others |
Cost & Logistics Intelligence
Steel and concrete input volatility determines both facility construction cost spreads and the geographic shape of new supply across Northern Europe. Energy market fluctuations compress margins on purpose-built assets in dense urban cores while pushing developers toward brownfield acquisitions with lower embedded material exposure.
Pricing Analysis
The legacy-to-smart facility pricing gap separates 1990s-era concrete structures from IoT-enabled new builds across the United Kingdom and Germany. Three-tier pricing structure across premium climate-controlled, standard enclosed, and economy outdoor levels stratifies by EU Green Deal compliance grade and biometric access certification. Cost compression in standard units is intensifying because on-demand logistics platforms capture inventory overflow from French small retailers. E-commerce merchants in Greater London show least price sensitivity due to just-in-time logistics requirements, while students in university towns exhibit highest sensitivity during seasonal demand cycles.
Supply Chain Analysis
Upstream feedstock for steel-reinforced concrete and prefabricated metal structures draws from German, Polish, and Turkish manufacturing clusters. HVAC components for climate control systems rest on specialized suppliers in the Netherlands and Denmark with limited alternative sourcing. Single-source vulnerability concentrates in biometric access hardware where French CNIL compliance requirements restrict vendor pools. Distribution runs through REIT-structured operators with captive development capabilities and independent regional specialists with localized site control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against micro-fulfillment centers and on-demand logistics platforms capturing traditional inventory overflow demand from small retailers.
For Market Incumbents: Harden facility portfolios against substitution by retrofitting aging assets with IoT-enabled environmental monitoring and biometric smart locks. Backward integration into property development secures brownfield acquisition pipelines in dense metropolitan zones. Climate engineering talent scarcity in Northern European labor markets demands premium wage structures or training partnerships. For New Entrants and Emerging Players: Eastern European underpenetration offers white-space expansion in Warsaw and Prague logistics corridors where storage square footage per capita trails UK levels by two-thirds. Mobile storage convergence with last-mile delivery partnerships captures business customers seeking inventory flexibility without fixed facility commitments. First-mover positioning in Polish industrial zones leverages German operator export relationships for operational platform licensing. For Investors and Strategic Acquirers: CSRD disclosure requirements reshape the acquisition landscape by privileging operators with energy efficiency investments that satisfy corporate sustainability reporting mandates. Long-term viability centers on REIT-structured operators with captive development capabilities and established metropolitan density. The signal to watch is EU building efficiency directive implementation timelines altering retrofit economics for aging central London and Paris facilities.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Infrastructure Deployment | Biometric smart locks and sensor networks reduce staffing costs across Greater London facilities. |
| EU Green Deal Retrofit Program | Solar array and insulation upgrades command rental premiums in climate-controlled unit tiers. |
| Mobile Storage Partnership | Portable container solutions with last-mile delivery capture Warsaw business customers. |
| Eastern European Expansion | First-mover positioning in Prague logistics corridors exploits underpenetrated storage markets. |
| CSRD Compliance Investment | Energy performance disclosures attract institutional capital to REIT-structured operators. |
Research Approach
Desk research of facility operator annual reports, EU regulatory filings, and construction cost indices preceded structured interviews with REIT portfolio managers, facility development executives, climate engineering specialists, and biometric access system vendors. Primary fieldwork across the United Kingdom, Germany, France, and the Netherlands validated secondary data on square footage per capita and rental rate structures. Bottom-up unit economics triangulated against top-down market sizing from REIT disclosures and national property registries.
Fixed assumptions across the analysis window held EU Green Deal implementation timelines and GDPR enforcement patterns constant while varying steel price volatility and interest rate environments. Segmentation modeling spanned product type, customer cohort, service tier, and facility vintage dimensions. CAGRs derived from facility expansion pipelines, brownfield acquisition activity, and household unbundling behavior projections. Climate control penetration rates and mobile storage adoption curves served as industry-specific forecast inputs.
Practitioners should monitor EU building efficiency directive enforcement intensity and on-demand logistics platform market share gains for early signals requiring forecast revision. Cross-checking against national property registry data and REIT distribution coverage ratios is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
Real Estate (Property) Management Market
Property Management
Residential Property Management Market
Property Management
United States Property Management Market
Property Management
Property Management Service Market
Property Management
Spain Warehousing Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Real Estate Management Software Market
Property Management
Qatar Flexible Office Space Market
Property Management
Property Management Software Market
Property Management
Hungary Warehousing Sector Market
Property Management
US Property Management Software Market
Property Management
South Korea Self-Storage Market