
 GCC Luxury Market | 2026-2036
GCC Luxury Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Luxury Market Intelligence
The gap between heritage craftsmanship and mass-premium diffusion is consolidating around exclusivity thresholds. LVMH Moët Hennessy Louis Vuitton leverages its vertical control over leather goods supply chains to sustain scarcity-driven pricing. Chalhoub Group anchors regional distribution through long-standing boutique networks across Dubai and Abu Dhabi. Kering SA differentiates via selective wholesale partnerships that limit brand dilution in secondary GCC cities.
GCC Luxury encompasses high-value goods and experiential services defined by artisanal production, limited distribution, and price inelasticity among wealth cohorts; authentication protocols and provenance documentation function as technical specifications that preserve resale value and brand equity. Jewelry and accessories capture concentrated margin pools due to material transparency and heirloom positioning. The customer-type dimension tilts toward high net worth individuals and affluent consumers, where personal shopping and concierge service types deepen retention through relationship-based selling rather than transactional convenience.
Saudi Vision 2030 and UAE consumer protection frameworks shape market access through localization mandates and import documentation requirements that affect boutique licensing. The country's national standards body and tourism authorities in Dubai and Riyadh enforce retail quality benchmarks that filter counterfeit penetration. Stakeholders must monitor how regulatory tightening on commercial agency laws redistributes channel control between international maisons and domestic operators.
Market Dynamics
Ultra-high-net-worth concentration in Riyadh and Dubai is compressing distribution timelines and forcing real estate-heavy experiential formats that merge retail with hospitality and cultural programming.
Growth Catalysts
- Saudi Vision 2030:Cultural and tourism investments in Riyadh and AlUla are creating new consumer access corridors that extend luxury reach beyond traditional Dubai-centric flows.
- Experiential retail formats:Boutique concepts integrating hospitality, private dining, and art curation deepen engagement with HNW individuals seeking relationship-based purchasing environments.
- Leather goods scarcity engineering:Controlled supply releases and waitlist management sustain price inelasticity across handbags and small leather accessories.
Market Restraints
- Commercial agency law tightening:Saudi Arabia's evolving regulatory framework redistributes channel control and creates licensing friction for international maisons operating through domestic partners.
- Skilled artisan scarcity:Limited regional pipeline for heritage craftsmanship training constrains expansion of bespoke and made-to-order service tiers.
- Import documentation complexity:UAE consumer protection frameworks and national standards body requirements extend time-to-market for new boutique openings.
Strategic Opportunities
- AlUla and secondary Saudi cities:Underpenetrated geographies outside Riyadh and Jeddah offer first-mover positioning as domestic tourism infrastructure matures.
- Digital authentication convergence:Blockchain provenance tracking and NFC-enabled product passports create resale value preservation tools that deepen primary market commitment.
- Concierge service unbundling:Subscription-based personal shopping models extend relationship-based selling to affluent consumers below UHNW thresholds.
Industry Challenges
- Counterfeit penetration:Authentication protocol standardization gaps complicate consumer trust building in secondary market channels.
- Boutique capex intensity:Flagship real estate requirements in Dubai Mall and Riyadh Boulevard districts demand eight-figure capital commitments with extended payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Luxury Market |
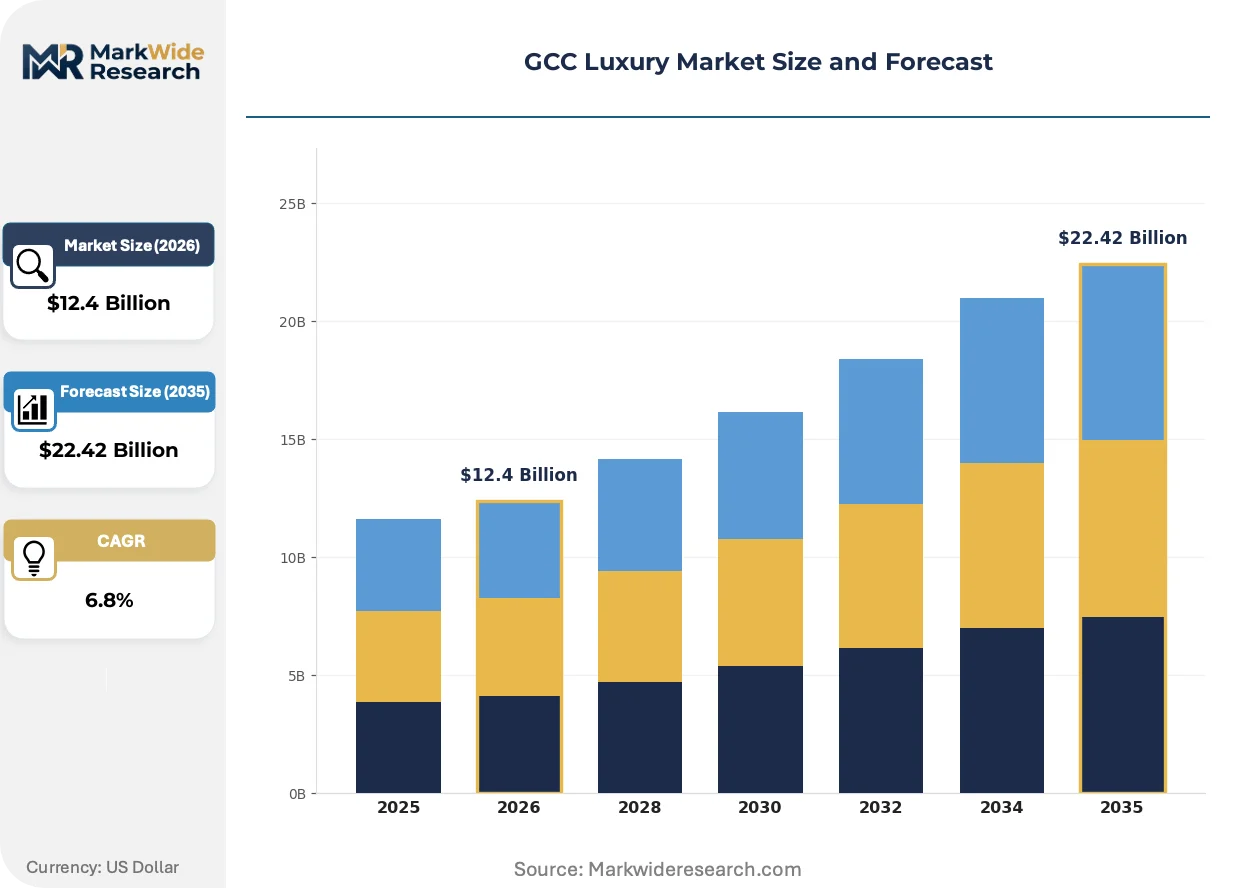
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Accessories, Footwear, Jewelry Customer Type: High Net Worth Individuals, Affluent Consumers, Tourists, Corporates Channel: Online, Department Stores, Boutiques, Luxury Malls Service Type: Personal Shopping, Customization, Concierge, After-Sales |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering SA, Compagnie Financière Richemont SA, Chanel SA, Chalhoub Group, Hermès International, Prada S.p.A., Majid Al Futtaim Group, Al Tayer Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Luxury Market Strategic Shifts & Innovations
Technology integration is compressing the distance between digital discovery and physical acquisition, while regulatory localization and experiential service unbundling reshape competitive positioning across the Gulf.
Blockchain-based provenance documentation is unifying authentication, resale tracking, and warranty transfer into single-platform ecosystems. Maisons including LVMH and Richemont are deploying these systems across high-value jewelry and watch categories. This convergence is enabling secondary market transparency that protects brand equity while capturing margin from circular economy participation.
SFDA and MOHAP cosmetic and fragrance registration pathways are tightening ingredient disclosure and stability testing requirements for products entering Saudi and UAE markets. These frameworks extend product development timelines by six to twelve months for new launches. Fragrance houses are responding by pre-positioning regulatory dossiers and establishing regional formulation labs in Dubai Science Park.
Personal shopping and concierge services are fragmenting from bundled boutique relationships into standalone subscription offerings accessible through mobile platforms. Chalhoub Group and regional independents are deploying these models to capture affluent consumers seeking curated access without flagship proximity. This shift is most visible in Dubai, where digital-native HNW individuals under forty prioritize convenience and exclusivity over traditional loyalty programs.
GCC Luxury Market Segmentation
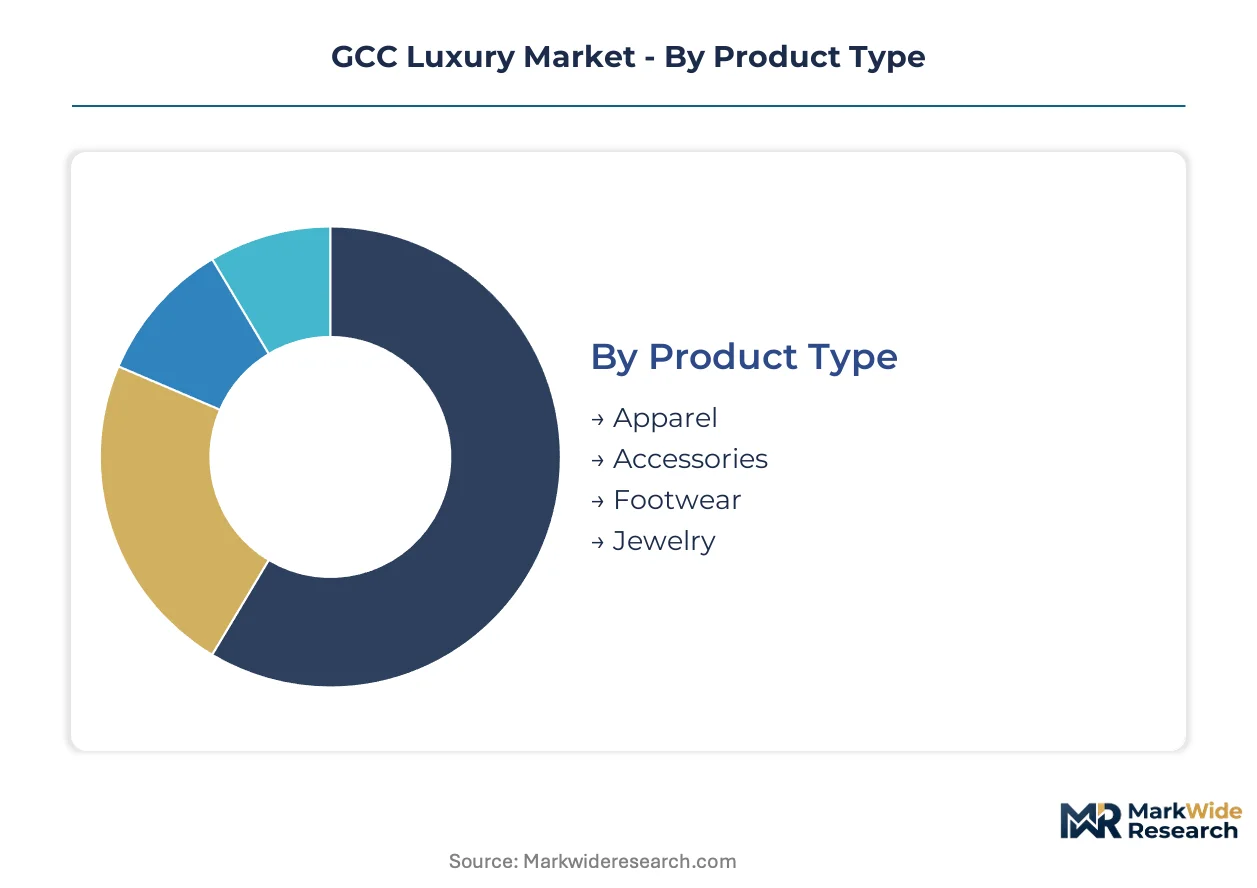
GCC luxury segmentation maps purchasing power gradients against distribution density and service intensity. Category boundaries blur where experiential retail merges product acquisition with hospitality programming.
Product Type:
Customization depth varies sharply across this category, from made-to-measure apparel requiring multiple fittings to ready-to-wear accessories with minimal alteration.
- Jewelry:High-value pieces incorporate certified gemstones and precious metals with blockchain-tracked provenance documentation. Demand clusters in Dubai's Gold Souk district and Riyadh's King Abdullah Financial District, driven by gift-giving customs and wealth preservation needs.
- Accessories:Handbags and small leather goods leverage controlled scarcity through waitlist management and limited regional releases. Leather goods scarcity engineering sustains price inelasticity across Dubai Mall and Riyadh Boulevard flagship locations.
- Apparel:Seasonal collections balance runway visibility with climate-appropriate fabrics for Gulf heat conditions.
- Footwear:Artisanal construction methods from Italian and Spanish ateliers dominate premium positioning.
Leading the category by volume: Accessories. Growing fastest: Jewelry.
Customer Type:
Spending concentration tracks residency status and purchasing frequency, with local UHNW cohorts driving recurring revenue versus transient tourist flows.
- High Net Worth Individuals:Ultra-wealthy residents in Riyadh and Dubai sustain relationship-based selling through dedicated client advisors and private salon access. Personal shopping and concierge service types deepen retention through bespoke appointment scheduling rather than transactional convenience.
- Affluent Consumers:Upper-middle-tier buyers seek entry-point luxury through diffusion lines and seasonal promotions. This segment responds to digital authentication convergence tools that preserve resale value and reduce perceived purchase risk.
- Tourists:Visitors from South Asia, Russia, and sub-Saharan Africa concentrate purchases in Dubai's duty-free zones and mall clusters.
- Corporates:Business procurement channels service executive gifting and hospitality uniform programs.
Volume concentration: High Net Worth Individuals. Steepest expansion trajectory: Affluent Consumers.
Channel:
Real estate intensity separates experiential formats from transactional efficiency, with capital deployment varying tenfold across the spectrum.
- Boutiques:Maison-controlled flagship locations in Dubai Mall and Riyadh Boulevard merge retail with private dining and art curation. Eight-figure capital commitments with extended payback horizons filter operator entry.
- Luxury Malls:Mall of the Emirates and The Galleria in Abu Dhabi aggregate multiple maisons under single rooflines with valet and concierge infrastructure.
- Department Stores:Chalhoub Group's Paris Gallery and Harvey Nichols Riyadh operate as multi-brand concessions with shared back-of-house services.
- Online:Digital platforms capture discovery and replenishment purchases, though high-value acquisitions remain showroom-dependent.
Revenue leadership: Boutiques. Gaining share fastest: Online.
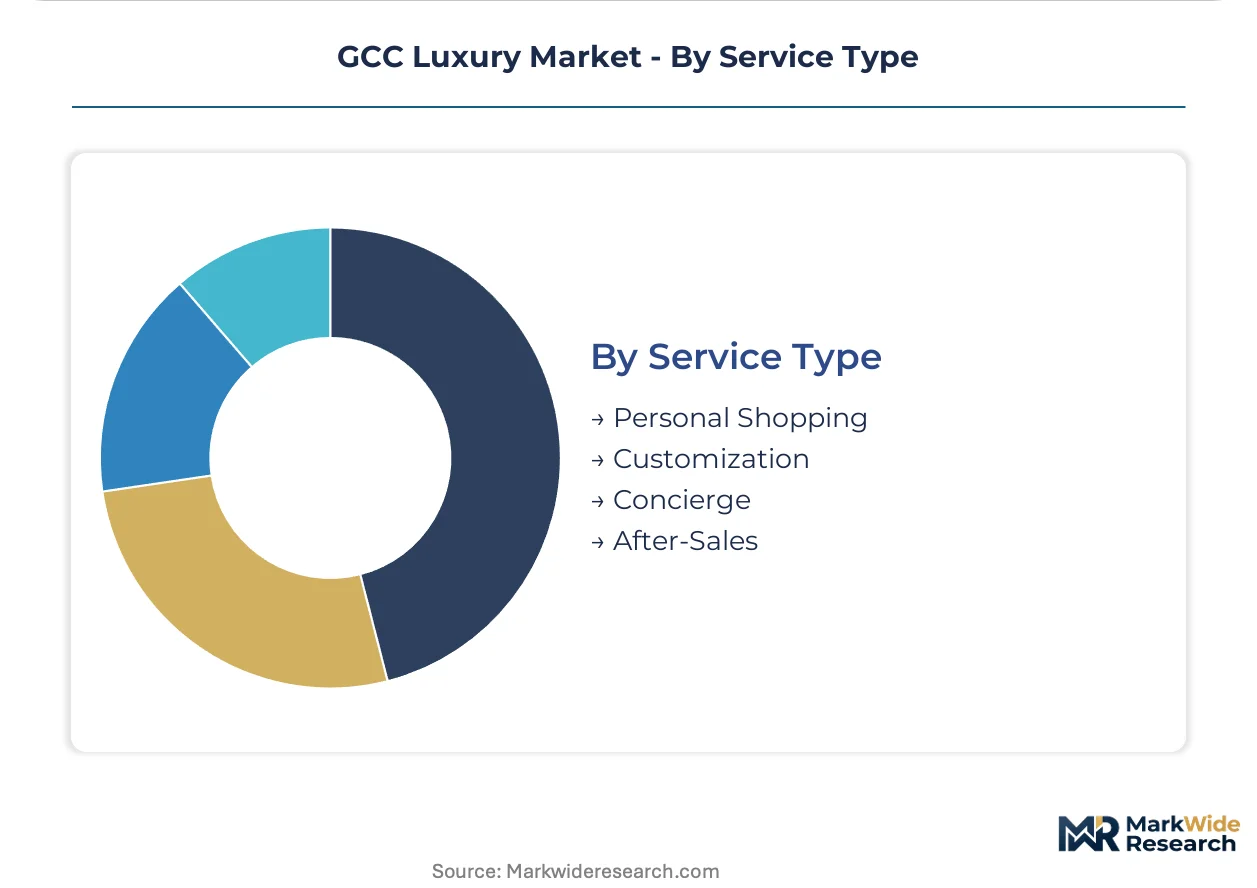
Service Type:
Relationship intensity scales from transactional after-sales to embedded lifestyle management with annual retainer structures.
- Personal Shopping:Dedicated advisors curate collections across multiple maisons, pre-empting client preferences through purchase history analysis. Subscription-based models extend this service to affluent consumers below UHNW thresholds through mobile platforms.
- Concierge:Lifestyle management spans travel coordination, event access, and household procurement beyond fashion categories.
- Customization:Bespoke and made-to-order tiers face constraints from skilled artisan scarcity limiting regional pipeline expansion.
- After-Sales:Repair, resizing, and refurbishment services protect resale value and sustain brand equity in secondary markets.
Margin concentration: Personal Shopping. Expanding most quickly: Concierge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Mall and Riyadh Boulevard anchor luxury consumption corridors across the Gulf Cooperation Council, compressing distribution timelines through experiential retail formats that merge hospitality with cultural programming.
United Arab Emirates
Dubai's Gold Souk and Mall of the Emirates concentrate jewelry demand from South Asian and Russian tourists. MOHAP enforces cosmetic and fragrance registration pathways that extend product development timelines. Abu Dhabi's The Galleria aggregates multiple maisons under single rooflines with valet infrastructure.
Saudi Arabia
Riyadh's King Abdullah Financial District and AlUla's emerging tourism infrastructure create new consumer access corridors. SFDA tightens commercial agency laws that redistribute channel control between international maisons and domestic operators. Jeddah's Red Sea coastline hosts secondary city expansion as domestic tourism matures.
Qatar
Doha's Pearl-Qatar and Lusail Marina cluster high-net-worth residents seeking bespoke services. The Qatar Financial Centre Authority streamlines licensing for luxury retail operators. Msheireb Downtown Doha integrates heritage architecture with contemporary boutique concepts.
Kuwait
Kuwait City's Avenues Mall and Salhiya district sustain relationship-based selling through dedicated client advisors. The Kuwait Direct Investment Promotion Authority facilitates foreign boutique licensing under commercial agency frameworks. The Grand Avenue precinct targets affluent consumers below ultra-high-net-worth thresholds.
GCC Luxury Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the GCC luxury landscape, where vertical control over supply chains separates heritage maisons from regional distributors. The market structure consolidates around a handful of French and Swiss conglomerates controlling leather goods and jewelry categories. Three archetypes dominate: vertically integrated European maisons, regional distribution specialists with long-standing boutique networks, and diversified Gulf-based retail operators managing multi-brand concessions. Competitive moves concentrate on selective wholesale partnerships that limit brand dilution and experiential format investments requiring eight-figure capital commitments.
Within the vertically integrated tier, LVMH Moët Hennessy Louis Vuitton and Kering SA exemplify scarcity-driven positioning through controlled supply releases and waitlist management. Chalhoub Group anchors regional distribution across Dubai and Abu Dhabi through multi-brand concessions and shared back-of-house services. These three entities occupy distinct competitive positions: the European conglomerates leverage in-house production and heritage craftsmanship, while the regional specialist compresses time-to-market through established licensing relationships and localized regulatory navigation.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering SA |
| Compagnie Financière Richemont SA |
| Chanel SA |
| Chalhoub Group |
| Hermès International |
| Prada S.p.A. |
| Majid Al Futtaim Group |
| Al Tayer Group |
| Others |
Cost & Logistics Intelligence
Captive control over European leather goods ateliers and Italian jewelry workshops anchors both scarcity positioning and margin preservation across GCC distribution. This backward integration into heritage craftsmanship insulates LVMH and Richemont from wholesale price volatility while sustaining waitlist-driven premiums in Dubai Mall and Riyadh Boulevard flagships.
Pricing Analysis
Value-based pricing anchored to provenance documentation and resale value preservation dominates high-value jewelry and watch categories. Three-tier pricing structure across bespoke, made-to-measure, and ready-to-wear levels segments accessibility while protecting exclusivity thresholds. Cost compression in entry-tier leather accessories is intensifying because Gulf-based affluent consumers below UHNW thresholds demand authentication-enabled purchase confidence. Tourist segments exhibit highest price sensitivity; ultra-high-net-worth residents demonstrate near-zero elasticity.
Supply Chain Analysis
Air freight and specialized handling costs from Paris, Milan, and Geneva constitute significant landed cost components for time-sensitive seasonal collections. Geographic supply concentration centers on France, Italy, and Switzerland for finished goods; UAE and Saudi Arabia function as regional distribution hubs with limited domestic manufacturing. Raw material dependencies include certified gemstones from Antwerp, precious metals from Swiss refiners, and exotic leathers from controlled European tanneries. Single-source vulnerability in skilled artisan capacity constrains bespoke service expansion. Distribution runs through maison-controlled boutiques and Chalhoub Group's multi-brand concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as eight-figure flagship capex requirements and regulatory licensing friction force smaller regional operators toward acquisition or exit. Boutique real estate intensity and commercial agency law tightening in Saudi Arabia compress viable competitive positions to vertically integrated conglomerates and established distribution specialists.
For Market Incumbents: Cement scarcity-driven positioning through controlled regional release calendars and blockchain-enabled provenance systems that deepen primary market commitment. Invest in captive training pipelines for heritage craftsmanship to address artisan scarcity constraining bespoke expansion. Defend against digital-native subscription competitors by unbundling concierge services into standalone mobile-accessible offerings.
For New Entrants and Emerging Players: Affluent consumers below ultra-high-net-worth thresholds represent the most accessible entry point, particularly through digital authentication convergence tools that reduce perceived purchase risk. AlUla and secondary Saudi cities offer white-space positioning ahead of domestic tourism infrastructure maturation. Deploy subscription-based personal shopping models to bypass capital-intensive flagship requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in regional distribution specialists with established licensing relationships and localized regulatory navigation capabilities. Long-term viability favors asset-light platforms with digital authentication infrastructure over real estate-heavy boutique operators. Monitor commercial agency law implementation in Saudi Arabia as inflection indicator for channel control redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Implementation | Unifies authentication, resale tracking, and warranty transfer for LVMH and Richemont jewelry categories. |
| Regional Formulation Lab Establishment | Fragrance houses pre-position SFDA and MOHAP regulatory dossiers in Dubai Science Park. |
| Concierge Service Unbundling | Chalhoub Group extends relationship-based selling to affluent consumers through mobile subscription platforms. |
| AlUla Boutique Pre-Positioning | First-mover operators capture emerging tourism infrastructure before competitor flagship saturation. |
| Captive Artisan Training Pipeline | Addresses skilled craftsmanship scarcity constraining made-to-order service tier expansion. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this GCC luxury market assessment. Primary interviews with brand country managers, retail operations directors, luxury mall leasing executives, and regional distribution partners combined with secondary validation from SFDA cosmetic registration databases, Dubai Department of Economic Development licensing records, and Chalhoub Group public disclosures. Bottom-up boutique revenue modeling and top-down wealth cohort spending analysis provided triangulation across product type, customer segment, channel, and service type dimensions.
Granularity-level modeling deployed country-specific projections for UAE, Saudi Arabia, Qatar, and Kuwait alongside city-level disaggregation for Dubai, Riyadh, Abu Dhabi, and Jeddah. Segmentation dimensions included product type, customer wealth tier, channel format, and service intensity. CAGRs derived from wealth formation trajectories, tourism flow projections, and regulatory implementation timelines. Industry-specific forecast inputs incorporated Saudi Vision 2030 cultural investment schedules and MOHAP cosmetic registration pathway processing durations.
Revisions become necessary when commercial agency law implementation accelerates, blockchain authentication protocol standardization gaps persist, or flagship real estate capex requirements escalate beyond eight-figure thresholds. Forecasts reflect assumptions about ultra-high-net-worth concentration stability and experiential retail format adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market