
 Europe Luxury Residential Real Estate Market | 2026-2036
Europe Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Residential Real Estate Market Foresight
Brokerage consortiums and exclusive listing networks is reshaping how trophy assets reach qualified buyers across European borders. Sotheby's International Realty leverages its art-world client overlap to sustain high-touch transaction pipelines. Engel & Völkers anchors its position through proprietary agent certification and controlled territory allocation. Christie's International Real Estate differentiates via auction-floor provenance ties that validate property narratives.
Europe luxury residential real estate comprises freehold and leasehold dwellings trading above localized price thresholds, typically exceeding five million euros in prime markets, with construction spanning timber-frame Alpine chalets, Haussmannian stone elevations, and contemporary glass-and-steel penthouses; these assets function as stores of value, lifestyle amenities, and cross-border wealth allocation instruments. Villas and penthouses within the property-type dimension command the deepest liquidity pools, while chalets in the French and Swiss Alps extract seasonal premiums. Family offices and sovereign wealth entities among customer-type segments are concentrating capital in estate diversification strategies that prioritize generational holding structures over yield extraction.
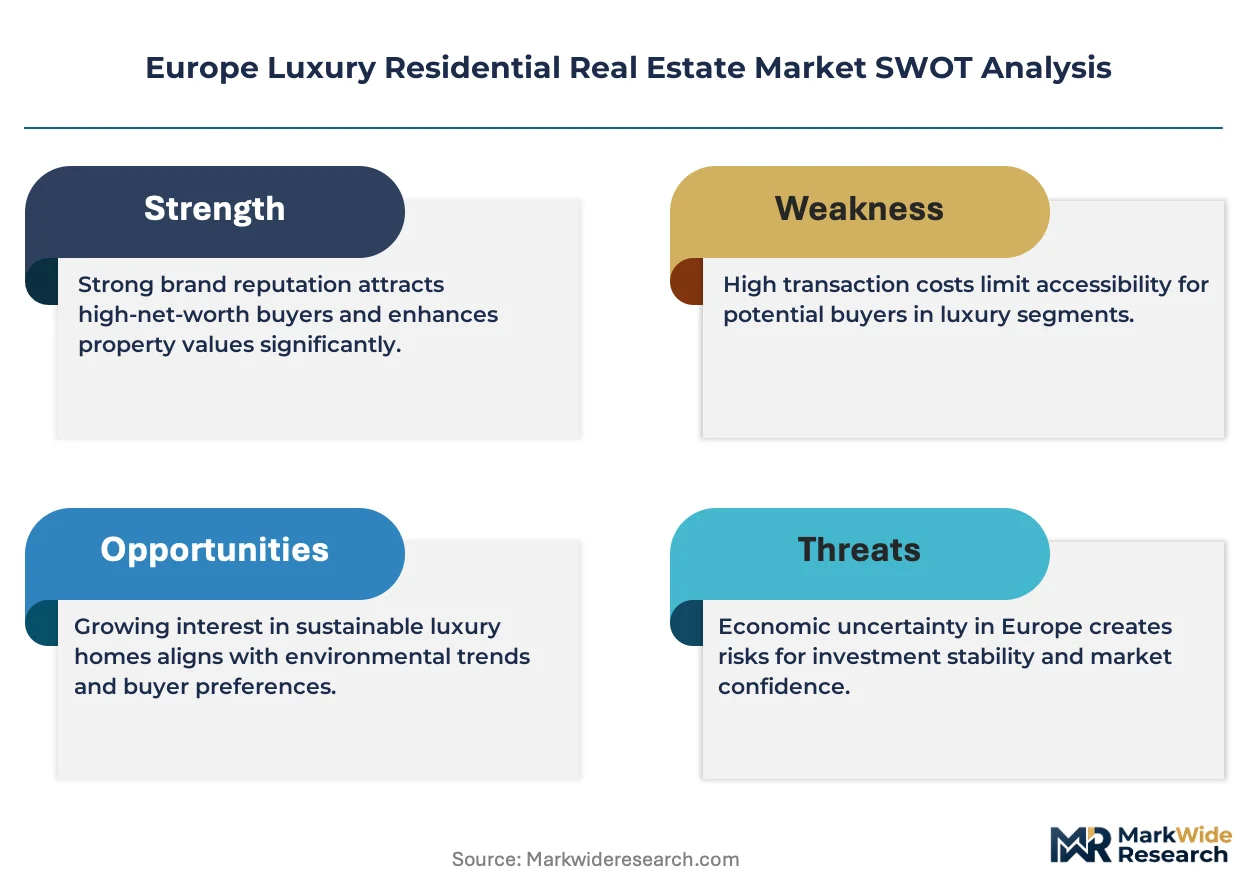
EU Green Deal building performance standards and national heritage conservation codes in France and Italy are mandating energy-efficiency upgrades that alter renovation economics for pre-war stock. ESG disclosure requirements under CSRD are filtering into lending criteria for trophy assets held through corporate vehicles. Stakeholders must monitor how carbon-performance gaps between compliant and non-compliant stock reshape relative pricing and financing access.
Market Dynamics
Wealth migration from emerging economies into European gateway cities is compressing transaction timelines and intensifying bidding competition for trophy assets. EU Green Deal building performance standards are simultaneously mandating capital-intensive retrofits across pre-war heritage stock, bifurcating liquidity between compliant and non-compliant properties.
Growth Catalysts
- EU Green Deal retrofit mandates:Building performance standards are accelerating capital deployment into energy-efficiency upgrades across France and Italy's heritage inventory. Family offices view compliant assets as premium collateral for green-linked financing structures.
- Wealth migration flows:Ultra-high-net-worth buyers from Middle Eastern and Asian source markets are concentrating acquisition activity in London's prime central postcodes and Paris arrondissements. This inbound demand expands the qualified buyer pool for assets above five million euros.
- Cross-border listing networks:Brokerage consortiums are collapsing information asymmetries between domestic and international buyers through exclusive territory allocation and certified agent pipelines. Trophy assets now reach qualified purchasers across multiple jurisdictions within compressed marketing windows.
Market Restraints
- Heritage conservation codes:France's ABF and Italy's Soprintendenze impose material and design restrictions that extend renovation timelines and inflate professional fees. Pre-approval processes for facade modifications routinely exceed eighteen months in protected zones.
- Construction input volatility:Specialized limestone, terrazzo, and ornamental metalwork face supply concentration among artisan producers in Tuscany and Provence. Lead times for custom Haussmannian stone elevations have extended substantially.
- Interest rate sensitivity:Trophy asset financing through corporate vehicles faces tightened lending criteria as central bank policy rates compress leverage capacity. Lenders are stress-testing debt service coverage against sustained higher-rate environments.
Strategic Opportunities
- Portuguese Golden Visa pathway:Lisbon and Algarve markets retain residency-linked investment routes that channel non-EU capital into rehabilitation projects. Heritage building conversions qualify for reduced stay requirements and accelerated citizenship timelines.
- Alpine seasonal rental optimization:Swiss and French chalet inventory is capturing premium yields through fractional ownership structures and concierge-managed short-term leasing. Technology platforms are collapsing owner-operator friction in yield extraction.
- CSRD-aligned ESG disclosure:Corporate sustainability reporting requirements are filtering into due diligence protocols for assets held through Luxembourg and Netherlands holding structures. Early compliance creates differentiation in institutional buyer targeting.
Industry Challenges
- Specialized conservation craftsmanship scarcity:Master artisans capable of authentic stone carving, fresco restoration, and ornamental plasterwork are aging out of the workforce without sufficient apprenticeship pipelines. Recruitment for heritage-grade renovation projects extends project schedules.
- Integrated building systems complexity:Concealing geothermal, photovoltaic, and smart home infrastructure within protected elevations requires coordination between conservation architects and MEP engineers. Design iterations multiply when aesthetic constraints conflict with performance targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Residential Real Estate Market |
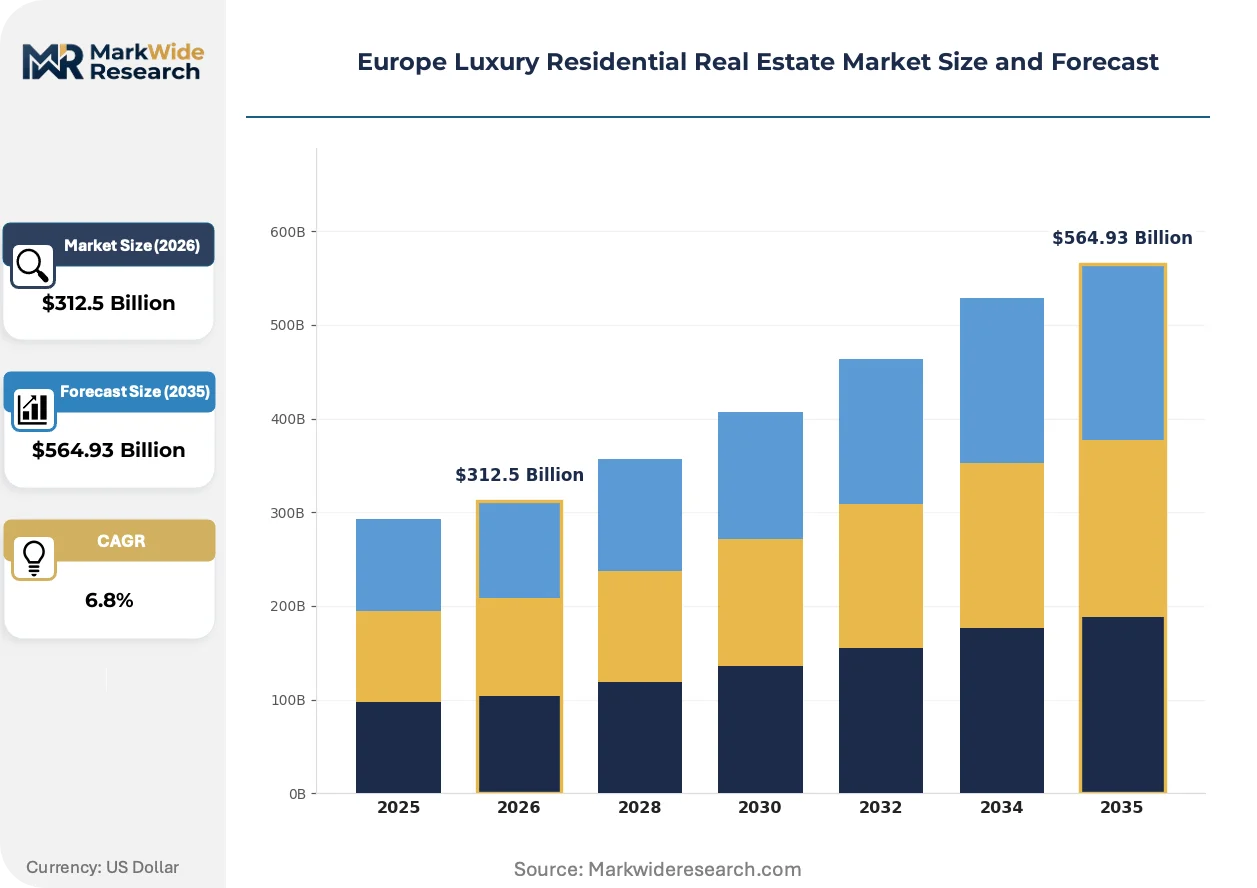
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $564.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Penthouses, Mansions, Chalets, Townhouses, Lofts Customer Type: High Net Worth Individuals, Family Offices, Private Investors, Real Estate Funds, Sovereign Wealth Entities, Boutique Buyers Sales Channel: Brokerage Firms, Online Platforms, Auctions, Direct Sales, Real Estate Exhibitions, Concierge Services Investment Strategy: Buy-to-Let, Capital Appreciation, Holiday Homes, Second Residences, Estate Diversification, Asset Preservation |
| Companies Covered | Sotheby's International Realty, Christie's International Real Estate, Engel & Völkers, John Taylor, Proprietes Le Figaro, Mansion Global, Luxury Places SA, Knight Frank, Savills, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Residential Real Estate Market Shifts & Advancements
Digital twin technology and blockchain-based provenance verification are collapsing transaction friction in cross-border trophy asset sales. These tools compress due diligence timelines while satisfying institutional buyer requirements for transparent ownership history.
Digital twin modeling is collapsing the information gap between remote international buyers and on-site property assessment. Family offices in Singapore and Dubai now commission virtual walkthroughs with embedded thermal imaging and structural sensor data before committing to physical inspections. This technology is collapsing the traditional site-visit bottleneck that previously gated cross-border transactions.
CSRD disclosure requirements are mandating granular energy-performance documentation for assets held through corporate vehicles. Lenders in Frankfurt and Amsterdam are integrating carbon-intensity metrics into loan covenant structures for trophy portfolios. Prime central London assets with verified net-zero retrofit pathways command preferential leverage terms from institutional credit committees.
Buyer concentration among single-family offices is displacing traditional high-net-worth individual purchasers in the ultra-prime segment. These entities deploy dedicated real estate acquisition teams with mandate-specific return thresholds and generational holding horizons. Paris and Monaco markets exhibit the most pronounced shift toward institutionalized family capital deployment.
Europe Luxury Residential Real Estate Market Segmentation
Segmentation in Europe luxury residential real estate reveals how capital deployment patterns, buyer sophistication levels, and transaction mechanisms fragment across distinct commercial channels. Understanding these divisions illuminates where liquidity concentrates and where regulatory or operational friction reshapes competitive positioning.
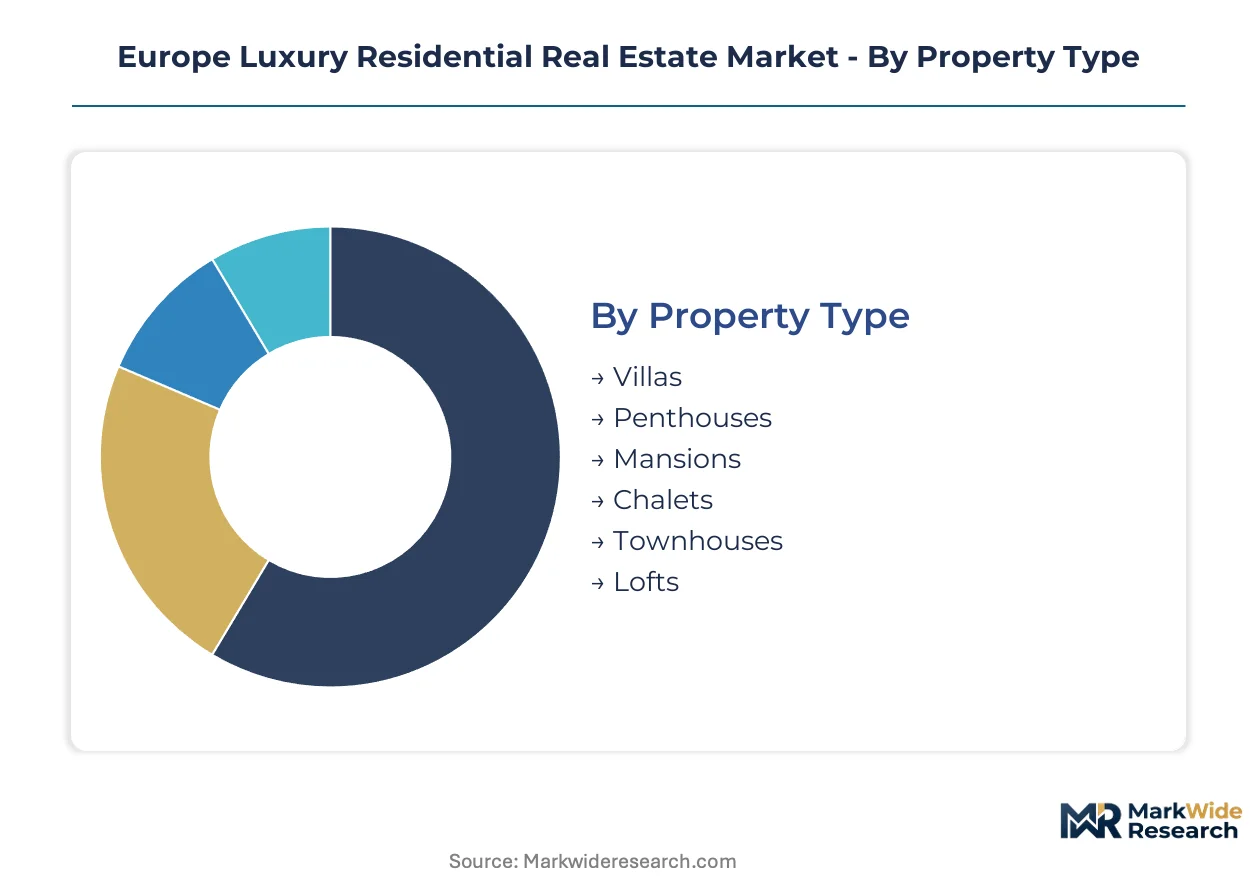
Property Type:
Mature inventory categories dominate transaction volumes while emerging formats capture yield optimization demand.
- Villas:Freehold structures with land parcels exceeding 2,000 square meters, typically featuring landscaped gardens and perimeter security. Demand concentrates in France's Côte d'Azur and Tuscany's wine-country corridors, where Middle Eastern and Asian buyers seek generational holding structures with privacy buffers.
- Penthouses:Top-floor units in prime central London and Paris arrondissements with private terrace access and 360-degree sightlines. Institutional capital from Singapore and Dubai targets these assets for trophy portfolio allocation, compressing due diligence timelines through digital twin pre-assessment.
- Mansions:Heritage-grade urban residences exceeding 1,000 square meters of interior volume, often requiring EU Green Deal retrofit compliance.
- Chalets:Timber-frame Alpine structures in French and Swiss ski domains with seasonal rental optimization potential.
- Townhouses:Multi-story urban dwellings in protected conservation zones with facade modification restrictions.
- Lofts:Converted industrial or commercial spaces with open-plan configurations and raw architectural elements.
Villas handle the majority of throughput; penthouses are the fastest mover on share.
Customer Type:
Buyer composition shifts from individual wealth holders toward institutionalized capital pools with dedicated acquisition mandates.
- High Net Worth Individuals:Private purchasers with liquid assets exceeding thirty million euros, typically deploying personal capital without external governance structures. Concentration in Monaco and Geneva markets reflects proximity to private banking infrastructure and favorable fiscal treatment.
- Family Offices:Dedicated investment vehicles managing single-family wealth across generational horizons, deploying teams with mandate-specific return thresholds. These entities are displacing individual purchasers in Paris ultra-prime segments, prioritizing estate diversification over yield extraction.
- Private Investors:Non-institutional capital pools with discretionary deployment capacity and shorter holding horizons.
- Real Estate Funds:Pooled vehicles with LP-GP structures targeting trophy assets above fifty million euro entry thresholds.
- Sovereign Wealth Entities:State-backed capital with strategic rather than purely financial objectives, active in London's Belgravia and Kensington corridors.
- Boutique Buyers:Collectors and lifestyle purchasers acquiring for personal use with minimal resale intent.
Family offices command the deepest capital reserves; boutique buyers show the steepest expansion trajectory in Portuguese Golden Visa corridors.
Sales Channel:
Channel selection correlates with asset price tier and buyer geography, with high-touch mechanisms dominating ultra-prime transactions.
- Brokerage Firms:Established networks with certified agent pipelines and exclusive territory allocation, collapsing information asymmetries between domestic and international buyers. Sotheby's International Realty and Engel & Völkers sustain competitive position through art-world client overlap and proprietary certification standards.
- Online Platforms:Technology-enabled marketplaces with virtual staging and AI-powered matching algorithms. These channels are gaining traction among remote Asian buyers assessing Alpine and Mediterranean inventory before committing to physical inspection travel.
- Auctions:Christie's International Real Estate leverages auction-floor provenance ties to validate property narratives and compress price discovery timelines.
- Direct Sales:Off-market transactions between principals, bypassing intermediary fees but requiring established trust networks.
- Real Estate Exhibitions:Periodic showcase events in London, Paris, and Monaco concentrating qualified buyers and inventory in compressed marketing windows.
- Concierge Services:White-glove acquisition teams managing end-to-end relocation, renovation, and household staffing integration.
Brokerage firms transact the highest absolute value; online platforms are climbing the fastest in buyer adoption curves.
Investment Strategy:
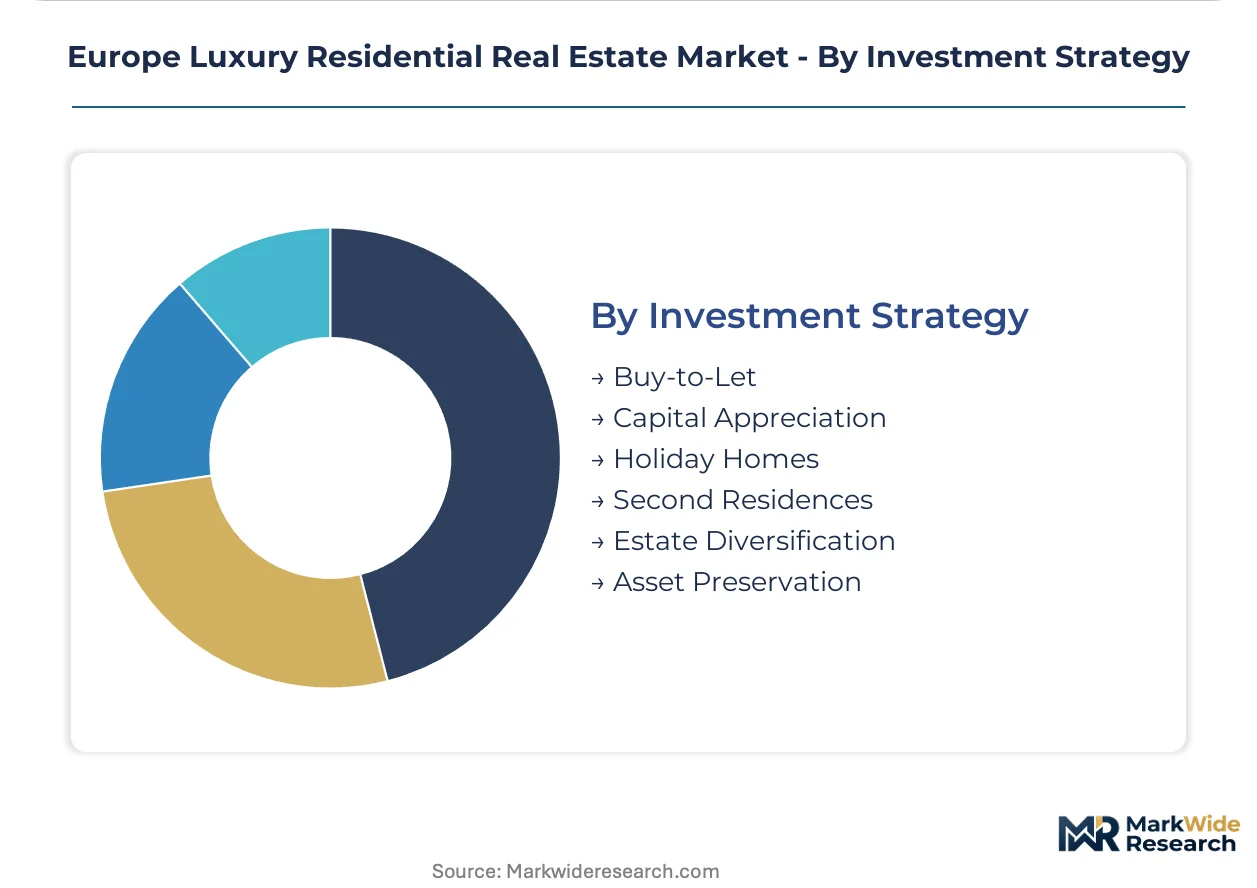
Strategy selection reflects holding horizon preferences and regulatory exposure to EU Green Deal compliance costs.
- Buy-to-Let:Income-oriented deployment targeting seasonal or long-term rental yields, prevalent in Lisbon and Algarve rehabilitation projects qualifying for Golden Visa reduced-stay requirements.
- Capital Appreciation:Price-gain-focused holding with minimal yield extraction, dominant in London prime central postcodes where supply constraints outpace demand growth.
- Holiday Homes:Personal-use assets with intermittent rental optimization through fractional ownership structures.
- Second Residences:Supplementary dwellings for seasonal occupation, concentrated in French Riviera and Swiss Alpine markets.
- Estate Diversification:Multi-asset allocation across geographies and property types to reduce concentration risk.
- Asset Preservation:Wealth storage in tangible, non-correlated instruments with minimal leverage and generational transfer planning.
Capital appreciation strategies absorb the majority of institutional capital; buy-to-let approaches are expanding most quickly in Portuguese and Spanish coastal markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal building performance standards are redirecting capital flows toward compliant inventory across member states. National heritage conservation codes layer additional retrofit requirements onto pre-war stock. Wealth migration from Middle Eastern and Asian source markets is compressing transaction timelines in gateway cities.
United Kingdom
London's prime central postcodes anchor institutional capital deployment from Singapore and Dubai family offices. The Financial Conduct Authority's mortgage lending guidelines stress-test debt service coverage against sustained higher-rate environments. Knightsbridge and Belgravia corridors exhibit the most pronounced bidding competition for trophy assets above five million pounds.
France
Paris arrondissements and Côte d'Azur villas attract generational holding structures from Middle Eastern buyers seeking privacy buffers. The Architectes des Bâtiments de France impose material and design restrictions that extend renovation timelines in protected zones. Cannes and Saint-Tropez sub-markets command seasonal premiums for waterfront inventory with landscaped grounds.
Switzerland
French and Swiss Alpine chalets capture yield optimization demand through fractional ownership structures. Cantonal regulations restrict foreign acquisition of secondary residences, preserving price stability for domestic and permitted international buyers. Verbier and Gstaad clusters concentrate timber-frame inventory with concierge-managed short-term leasing potential.
Italy
Tuscany's wine-country corridors and Lake Como waterfront draw estate diversification strategies from family offices. The Soprintendenze Archeologia Belle Arti e Paesaggio mandates pre-approval processes for facade modifications that routinely exceed eighteen months. Florence and Milan heritage-grade mansions face bifurcated liquidity between EU Green Deal compliant and non-compliant stock.
Portugal
Lisbon and Algarve markets channel non-EU capital through residency-linked investment routes. Golden Visa regulations qualify heritage building conversions for reduced stay requirements and accelerated citizenship timelines. Porto and Cascais rehabilitation projects attract boutique buyers with minimal resale intent and lifestyle-oriented holding horizons.
Europe Luxury Residential Real Estate Market Competitive Landscape
On the supply side, the industry is structured around brokerage consortiums with exclusive territory allocation and certified agent pipelines. Established networks collapse information asymmetries between domestic and international buyers through controlled marketing windows. Two strategic archetypes dominate: art-world client overlap specialists and auction-floor provenance validators. Competitive moves concentrate on cross-border listing network expansion and proprietary certification standard deployment.
Within the heritage-grade transaction tier, Sotheby's International Realty and Christie's International Real Estate exemplify auction-house-affiliated positioning that validates property narratives through provenance ties. Engel & Völkers anchors the certified-agent archetype with controlled territory allocation. Knight Frank and Savills occupy positions within the institutional advisory segment serving family office capital deployment.
| Leading Market Players |
|---|
| Sotheby's International Realty |
| Christie's International Real Estate |
| Engel & Völkers |
| John Taylor |
| Proprietes Le Figaro |
| Mansion Global |
| Luxury Places SA |
| Knight Frank |
| Savills |
| Others |
Supply & Pricing Matrix
Artisan labor scarcity in Tuscany and Provence simultaneously compresses renovation margins and bifurcates pricing tiers between heritage-authentic and standard-finish inventory. EU Green Deal compliance costs feed directly into buyer qualification thresholds, reshaping how capital deploys across compliant and non-compliant stock.
Pricing Analysis
Certification level creates the primary spread between EU Green Deal-compliant heritage assets and standard inventory. Three-tier pricing structure across premium, standard, and economy levels reflects energy-performance documentation, conservation-grade craftsmanship, and provenance validation. Pricing pressure stems from interest rate sensitivity compressing leverage capacity for corporate-vehicle acquisitions. Family offices exhibit lowest price sensitivity due to generational holding horizons, while private investors face acute pressure from tightened lending criteria.
Supply Chain Analysis
Export-control regimes on specialized conservation technologies limit cross-border equipment flows for heritage-grade retrofit projects. Supply concentrates in France, Italy, and Switzerland for limestone, terrazzo, and ornamental metalwork. Raw material dependencies include Haussmannian stone from Burgundy quarries, Alpine timber from Swiss cantonal forests, and fresco pigments from Venetian traditional producers. Single-source vulnerability runs through aging master artisans without apprenticeship pipelines. Distribution runs through exclusive brokerage networks with certified agent pipelines and controlled territory allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master artisans capable of authentic stone carving and ornamental plasterwork are aging out of the workforce faster than training programs replenish them, constraining heritage-grade renovation capacity and compressing timelines for trophy asset readiness.
For Market Incumbents: Pre-empt competitive erosion by securing exclusive contracts with conservation-grade craftsmen in Provence and Tuscany before rival brokerages lock in capacity. Anchor position through proprietary certification standards for agents handling EU Green Deal compliance documentation. Vertical integration into concierge-managed short-term leasing platforms captures yield optimization demand from fractional ownership structures. For New Entrants and Emerging Players: Portuguese Golden Visa rehabilitation projects in Porto and Cascais represent the most penetrable entry point for non-EU capital channeling. Alpine seasonal rental optimization technology platforms in French and Swiss ski domains offer white-space positioning with collapsing owner-operator friction. Launch through digital twin-enabled remote assessment tools targeting Singapore and Dubai family offices. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors early EU Green Deal compliance positioning. Long-term viability across the next decade hinges on acquiring assets with verified net-zero retrofit pathways and established provenance documentation. Watch for inflection in carbon-intensity metrics integration into Frankfurt and Amsterdam lending covenant structures.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Craftsmanship Pipeline Development | Apprenticeship partnerships with French ABF-accredited ateliers secure conservation-grade capacity. |
| EU Green Deal Compliance Certification | Early energy-performance documentation creates differentiation in institutional buyer targeting. |
| Digital Twin Platform Deployment | Virtual walkthroughs with embedded sensor data collapse cross-border transaction friction. |
| Fractional Ownership Structure Launch | Concierge-managed short-term leasing captures premium yields from Alpine chalet inventory. |
| Cross-Border Listing Network Expansion | Exclusive territory allocation compresses marketing windows for trophy assets above five million euros. |
Research Methodology
A spread of perspectives from luxury brokerage principals, heritage conservation architects, family office real estate directors, and institutional lending officers converged on the working assumptions. Primary interviews combined with secondary validation from EU Green Deal regulatory filings, French ABF pre-approval databases, and Swiss cantonal foreign acquisition records. Bottom-up transaction analysis triangulated against top-down capital flow estimates across the analysis window.
Demand-supply balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include property type, customer archetype, sales channel, and investment strategy alongside regional regulatory cluster differentiation. CAGRs derived from historical transaction velocity patterns and forward-looking wealth migration flow projections. Forecast inputs incorporated EU Green Deal retrofit mandate timelines and CSRD disclosure requirement phase-ins.
Macroeconomic conditions sit as an overlay; deviation in central bank policy rates and cross-border capital control regimes would shift the trajectory. Forecasts reflect documented assumptions regarding wealth migration persistence and conservation craftsmanship availability. Material shifts in EU Green Deal enforcement intensity or heritage code pre-approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market