
 Heat Transfer Paper Market | 2026-2036
Heat Transfer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Transfer Paper Market Outlook
Custom apparel decorators and small-batch textile printers is bifurcating the Heat Transfer Paper Market away from bulk promotional buyers. Neenah Coldenhove leverages its European coating expertise to supply high-release papers for sublimation transfer. Sappi anchors supply for large-format digital transfer rolls through its coated specialty paper infrastructure. Jiangyin Wellye Paper Industry Co., Ltd. competes on cost-efficient thermal transfer substrates serving Asia-Pacific garment decorators.
Heat transfer paper comprises coated or uncoated specialty substrates engineered to receive inkjet, laser, or sublimation inks and release them cleanly onto textiles, ceramics, or polymer surfaces under heat and pressure, typically with coatings containing silica, clay, or proprietary polymer layers at basis weights of 80–140 gsm. Its primary commercial purpose is enabling on-demand, short-run decoration of fabrics and promotional goods without screen-printing setup costs. Digital transfer paper leads product type value generation due to compatibility with desktop and wide-format inkjet systems, while sublimation technology captures the fastest growth trajectory driven by polyester sportswear expansion. Small businesses dominate end-user volume, though large enterprises command superior margins through centralized procurement of coated rolls.
EPA oversight of volatile organic compound emissions from coating operations shapes U.S. manufacturing compliance costs for domestic producers. REACH registration requirements in Europe restrict certain fluorinated chemistries formerly common in release coatings, redirecting R&D toward silicone and plant-derived alternatives. China's GB standards for paper product safety, administered by SAMR, govern import acceptance of coated transfer substrates. Stakeholders must monitor evolving chemical restriction lists across these jurisdictions to anticipate reformulation cycles and qualify new coating chemistries before supply disruptions materialize.
Market Dynamics
Digital-ready transfer substrates are bifurcating procurement patterns as custom apparel decorators abandon bulk promotional contracts in favor of short-run, on-demand production workflows anchored by desktop and wide-format inkjet systems.
Growth Catalysts
- Polyester sportswear expansion:Sublimation-compatible heat transfer paper demand accelerates as athletic apparel brands specify polyester-rich fabric blends for moisture-wicking performance garments.
- REACH chemical disclosure tightening:European coating reformulation mandates are redirecting R&D investment toward silicone-release and plant-derived alternatives, qualifying new substrate chemistries for EU market access.
- Guangdong cluster density:China's textile decorator concentration in Guangdong province generates concentrated demand for cost-efficient thermal transfer substrates serving promotional goods exporters.
Market Restraints
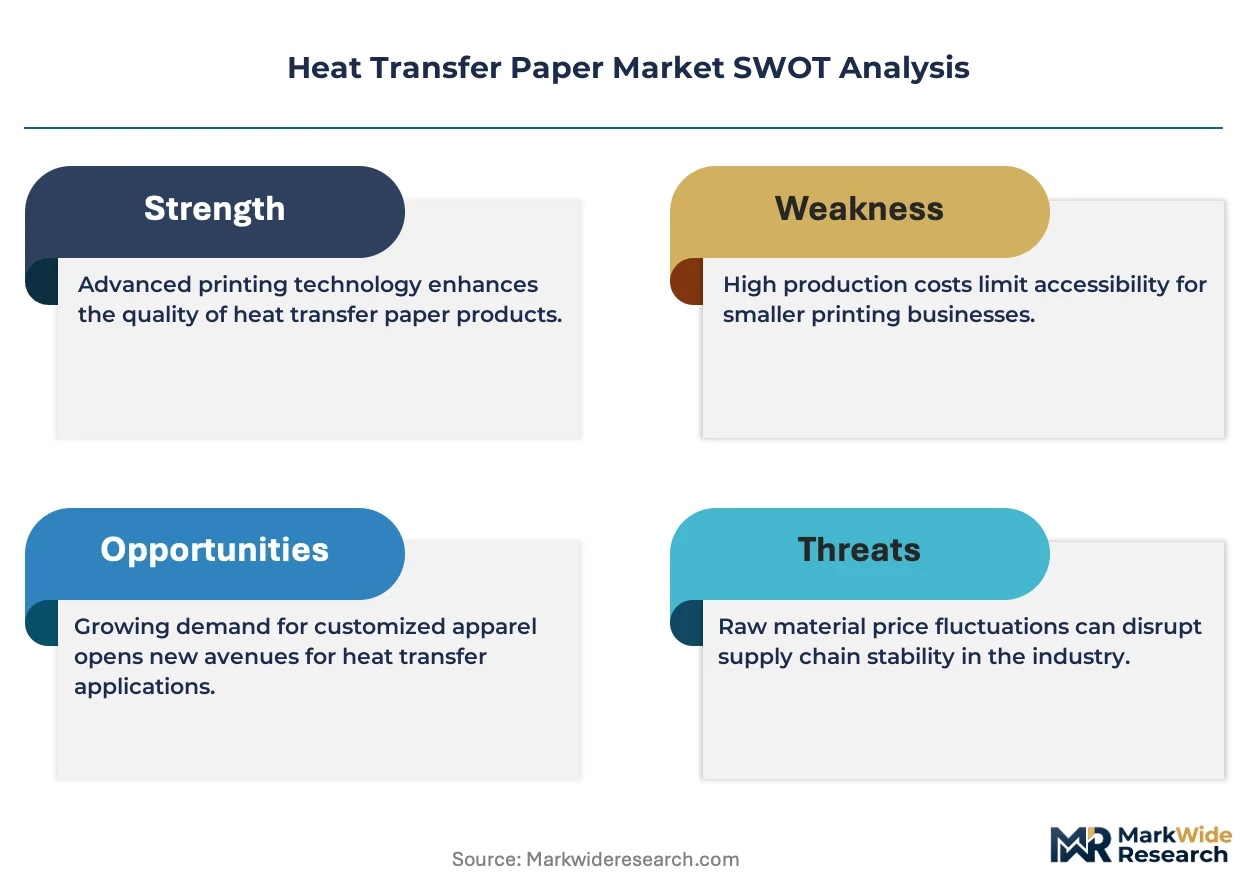
- Fluorinated chemistry phase-out:Formerly standard release coatings face restriction under REACH and EPA oversight, forcing coating line reconfiguration and qualification delays.
- Specialty pulp input volatility:Coated substrate production depends on alpha-cellulose pulp grades subject to packaging industry demand competition and freight cost swings.
- Screen-printing setup cost compression:Automated screen systems with rapid changeover capabilities are eroding the cost advantage that drove digital transfer adoption in mid-volume runs.
Strategic Opportunities
- India garment export corridor:Tiruppur and Surat textile hubs remain underpenetrated by digital transfer substrate suppliers, presenting first-mover positioning for coating-optimized papers.
- Ceramic and polymer decoration:Sublimation transfer protocols are extending beyond textiles into customized drinkware and phone case applications with higher margin profiles.
- EU Green Deal procurement criteria:Public sector promotional goods tenders are embedding sustainability scoring that favors bio-based coating formulations and certified substrate sourcing.
Industry Challenges
- Coating technician scarcity:Formulation chemistry expertise for silica-clay-polymer layer optimization is concentrated among aging specialists in European and Japanese paper mills.
- GB standard certification timelines:China's SAMR-administered paper product safety assessments for import acceptance create 6-12 month qualification gaps for new substrate introductions.
- Legacy screen-printing integration:Hybrid production facilities face workflow friction combining digital transfer stations with existing screen-drying infrastructure and color-matching protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Transfer Paper Market |
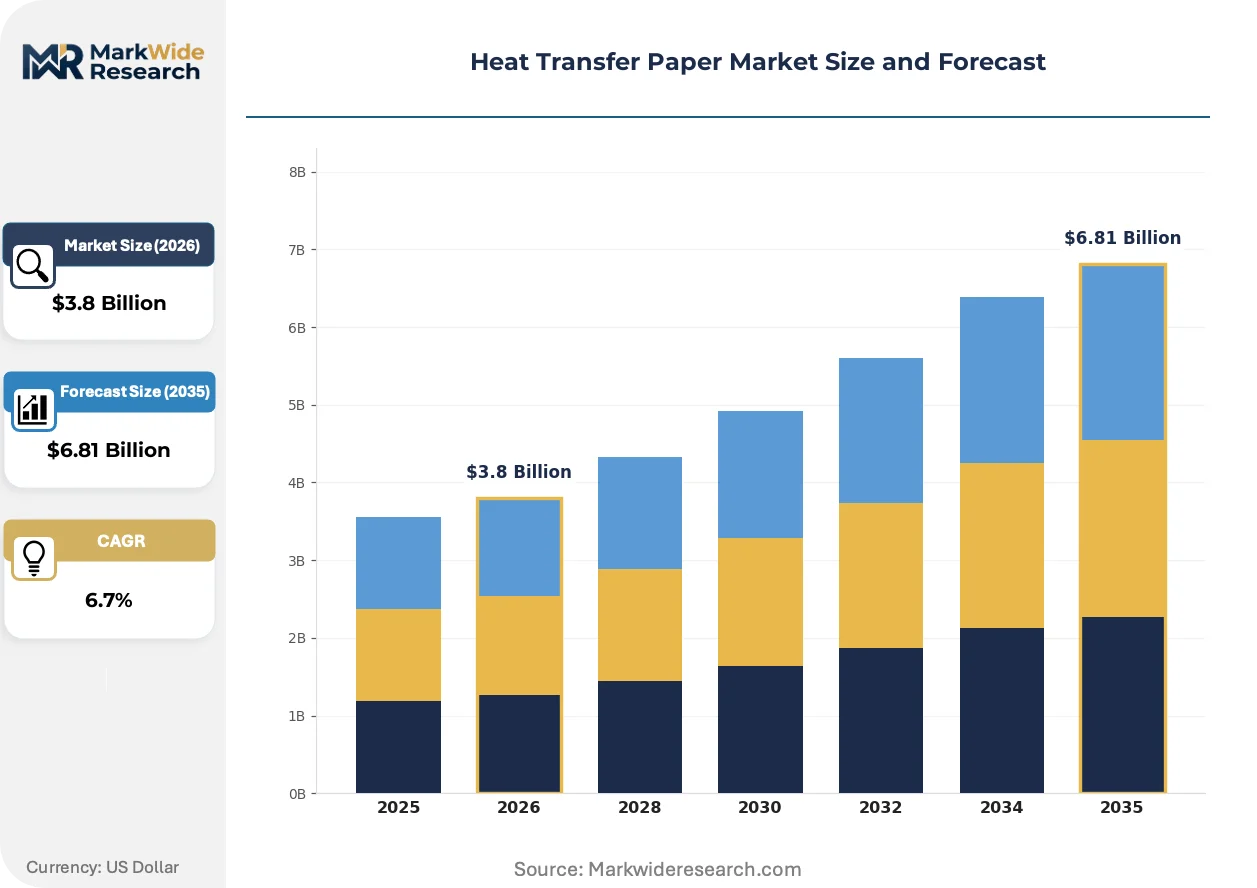
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Transfer Paper, Clear Transfer Paper, Digital Transfer Paper, Eco-Solvent Transfer Paper Application: Textile Printing, Promotional Products, Home Decor, Custom Apparel Technology: Inkjet Printing, Laser Printing, Sublimation, Thermal Transfer End User: Small Businesses, Large Enterprises, Educational Institutions, Hobbyists |
| Companies Covered | Sappi, Surya Coats Private Limited, Neenah Coldenhove, Jiangyin Wellye Paper Industry Co., Ltd., MINSEO CO., LTD., Felix Schoeller Group, CANAPA Inc., Sino Coat Inc., Stahls' Transfer Paper Experts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Transfer Paper Market Strategic Shifts
Water-based ink compatibility requirements and plant-derived coating chemistries are simultaneously reshaping substrate formulation priorities across European and North American supply chains.
Silicone-release coating technology is displacing fluorinated alternatives in high-performance transfer papers. Custom apparel producers in Germany and the Netherlands are specifying these substrates for polyester sportswear decoration to preempt REACH compliance disruptions. The shift is compressing coating line reconfiguration cycles and accelerating qualification partnerships between paper mills and inkjet ink formulators.
ECHA's restriction roadmap for per- and polyfluoroalkyl substances is forcing coating operation overhauls across European transfer paper manufacturing. Industrial consequence includes capital allocation toward plasma-treatment and UV-cured silicone systems that maintain release performance without restricted chemistries. Small-batch textile printers in Italy and Portugal are experiencing substrate supply interruptions as mills stagger reformulation rollouts.
Direct-to-film transfer protocols are disrupting traditional heat transfer paper procurement among small business decorators. Web-to-print platforms and aggregated micro-order fulfillment are replacing distributor-based roll purchasing in North American custom apparel channels. This behavioral pivot is most visible in the United States, where Etsy-integrated production workflows are compressing order minimums and fragmenting substrate specification authority away from centralized print shop buyers.
Heat Transfer Paper Market Segmentation
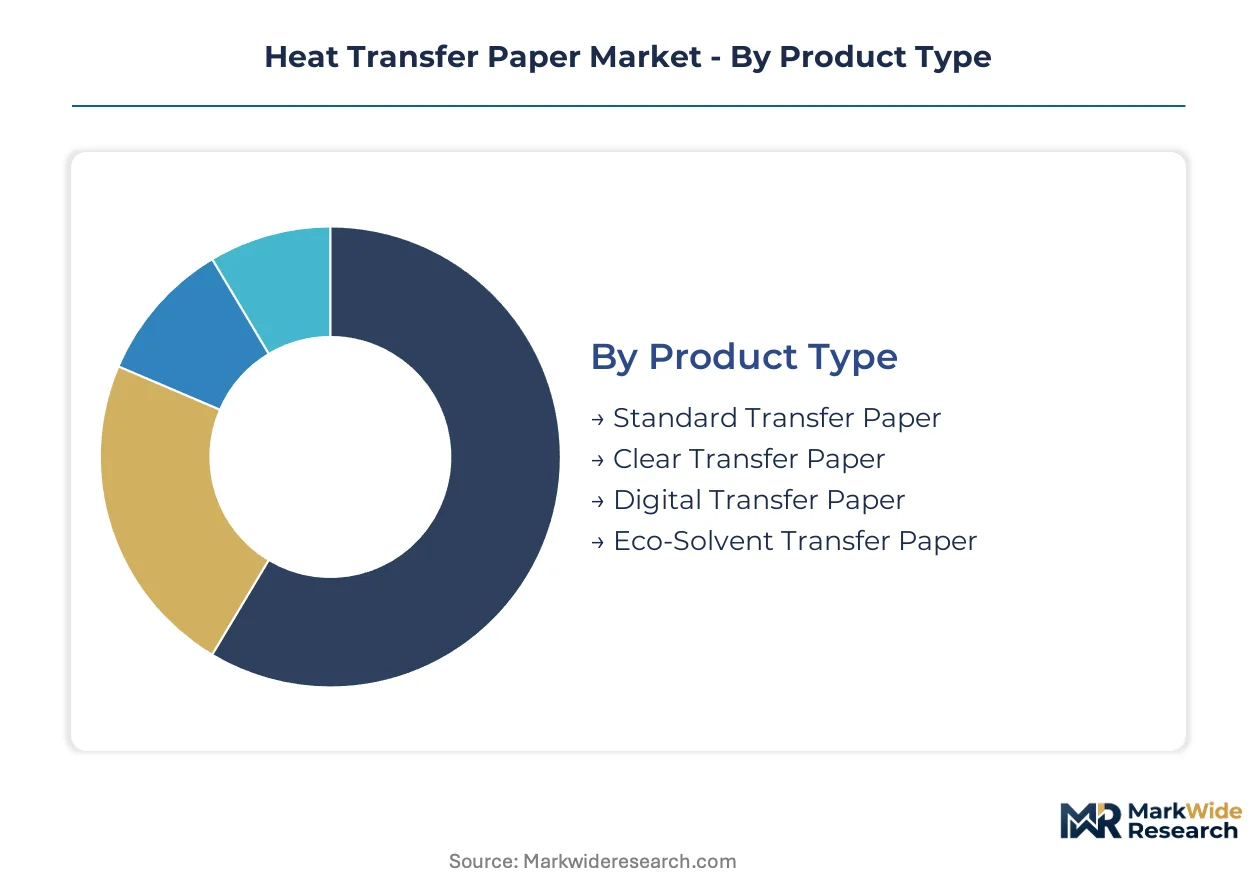
Channel-mix dynamics in heat transfer paper procurement vary sharply across segment boundaries. Desktop decorators favor narrow-format digital substrates purchased through web-to-print platforms, while large-format operations source coated rolls through mill-direct contracts.
Product Type:
Distribution channels bifurcate sharply between commodity substrates and specialty formulations, with digital-ready papers commanding premium placement through equipment OEM bundling.
- Digital Transfer Paper:Engineered with silica-clay-polymer coatings optimized for aqueous and pigment inkjet systems at 90–120 gsm basis weights. Demand concentrates among custom apparel producers in Guangdong province and North American web-to-print decorators migrating from screen-printing workflows. Compatibility certification with Epson, Roland, and Mimaki ink systems drives specification authority.
- Eco-Solvent Transfer Paper:Manufactured with solvent-resistant polymer release layers that withstand aggressive ink chemistries without coating degradation. European sign and display printers under ECHA chemical disclosure mandates favor these substrates for outdoor-durable textile graphics. REACH-compliant coating reformulations are compressing supplier qualification timelines.
- Standard Transfer Paper:Uncoated or minimally coated cellulose substrates serving cost-sensitive promotional goods producers.
- Clear Transfer Paper:Transparent PET-film or cast-coated papers enabling no-background transfers onto dark fabrics.
By volume, Standard Transfer Paper leads. By growth pace, Digital Transfer Paper is climbing the fastest.
Application:
Margin structures diverge across application segments, with textile decoration capturing value through substrate-ink-fabric compatibility premiums while promotional goods compete on throughput efficiency.
- Custom Apparel:Short-run, on-demand decoration of t-shirts, activewear, and fashion accessories using heat press release papers. Small business decorators in the United States and Germany dominate procurement volume through aggregator platforms. Direct-to-film protocol adoption is fragmenting traditional paper specification authority.
- Textile Printing:Industrial-scale sublimation transfer onto polyester sportswear and home textiles requiring high-release coatings and precise dimensional stability. Athletic apparel brands in Italy and Portugal specify sublimation-compatible substrates for moisture-wicking performance garments. ECHA fluorinated chemistry restrictions are forcing coating reformulation cycles.
- Promotional Products:Bulk decoration of bags, caps, and corporate merchandise through conventional thermal transfer methods.
- Home Decor:Cushion covers, curtains, and wall textiles with lower volume but higher margin per square meter.
Promotional Products moves the most tonnage. Custom Apparel shows the steepest expansion trajectory.
Technology:
Equipment installed base and ink chemistry compatibility lock substrate specifications into multi-year procurement cycles.
- Sublimation:Dye-sublimation transfer papers with specialized coatings that release disperse dyes onto polyester under heat and pressure. Demand accelerates in China's Zhejiang and Jiangsu textile clusters serving export-oriented sportswear manufacturers. SAMR GB standard certification requirements create 6–12 month qualification gaps for new substrate introductions.
- Inkjet Printing:Aqueous and UV-curable inkjet-compatible papers for desktop and wide-format systems. Small-batch textile printers in the Netherlands and United Kingdom specify these for rapid prototyping and sample production. Water-based ink compatibility requirements are reshaping coating formulation priorities.
- Laser Printing:Heat-resistant papers formulated for toner adhesion and clean release in laser transfer workflows.
- Thermal Transfer:Wax-resin and resin-compatible ribbons for barcode and industrial labeling applications.
Thermal Transfer holds the largest installed base. Sublimation is gaining share fastest among decoration technologies.
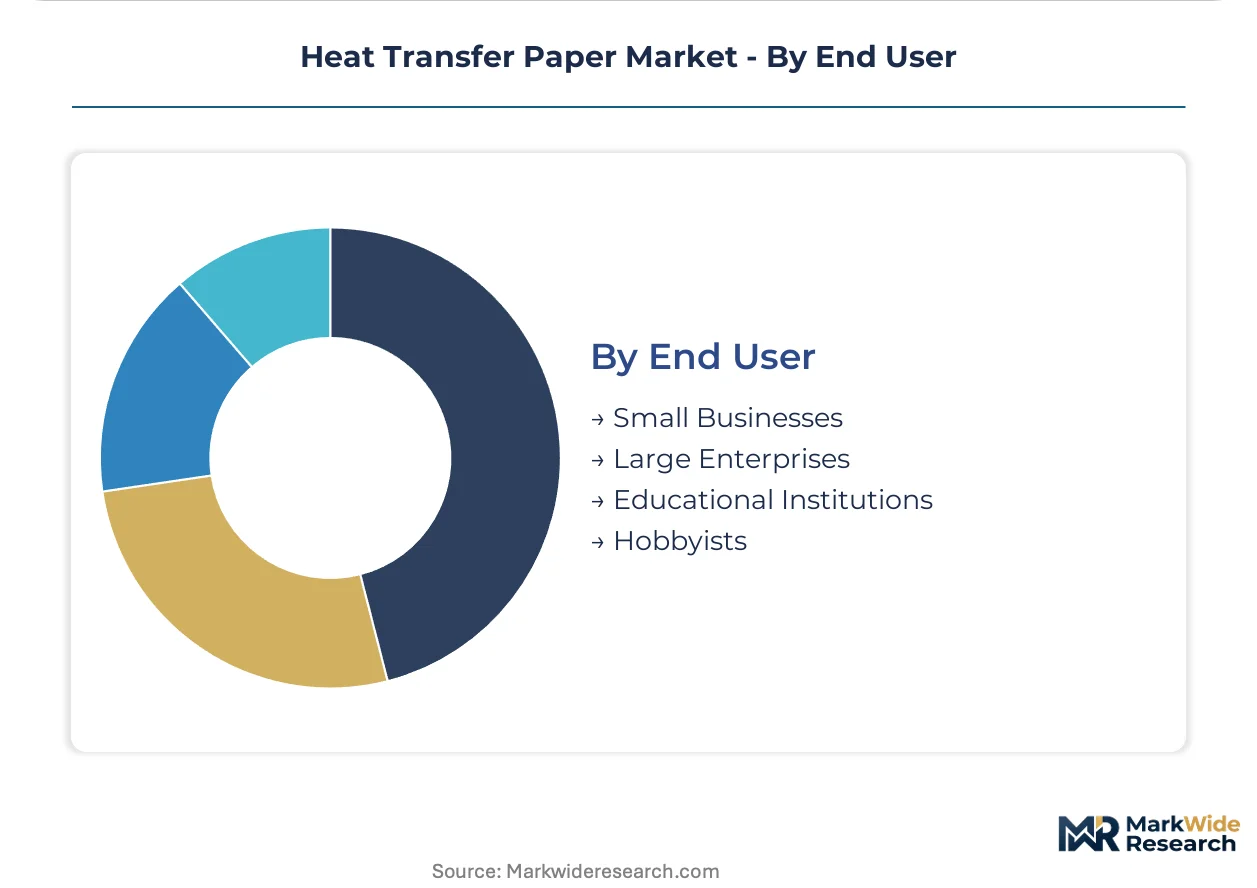
End User:
Procurement scale and technical sophistication create distinct customer tiers with diverging service requirements.
- Small Businesses:Independent custom apparel decorators and Etsy-integrated producers purchasing cut-sheet and narrow-roll formats. These operators in the United States and United Kingdom drive demand for desktop-compatible digital transfer papers with minimal setup waste. Web-to-print platform integration is compressing order minimums and fragmenting distributor relationships.
- Large Enterprises:Centralized print shops and promotional goods manufacturers with mill-direct coated roll contracts. These buyers in Germany and Japan command superior margins through volume commitments and specification influence over coating development. REACH and EPA compliance documentation requirements dominate procurement criteria.
- Educational Institutions:Vocational programs and university maker spaces with intermittent, price-sensitive purchasing patterns.
- Hobbyists:Consumer-grade crafters sourcing through retail channels and online marketplaces.
Large Enterprises dominate value capture. Small Businesses show the most rapid procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating formulation expertise clusters in Western Europe and East Asia, while downstream consumption concentrates in textile manufacturing belts across China, South Asia, and North America. Regional regulatory divergence on fluorinated chemistry restrictions is fragmenting substrate qualification timelines and redirecting trade flows.
United States
Custom apparel decorators in the Southeast and Pacific Northwest drive digital transfer substrate demand through web-to-print aggregator platforms. EPA oversight of volatile organic compound emissions from coating operations shapes domestic manufacturing compliance costs. Los Angeles and Atlanta host dense concentrations of small-batch textile printers migrating from screen-printing workflows.
Germany
Industrial-scale sublimation transfer for polyester sportswear anchors substrate demand among athletic apparel brands specifying moisture-wicking performance garments. ECHA's restriction roadmap for per- and polyfluoroalkyl substances forces coating operation overhauls toward plasma-treatment and UV-cured silicone systems. The Ruhr industrial corridor and Bavaria host paper mills accelerating reformulation partnerships with inkjet ink formulators.
China
Guangdong province generates concentrated demand for cost-efficient thermal transfer substrates serving promotional goods exporters and textile decorators. SAMR-administered GB standards for paper product safety create six-to-twelve month qualification gaps for new coated substrate introductions. Zhejiang and Jiangsu textile clusters export sublimation-compatible sportswear requiring high-release coating specifications.
India
Tiruppur and Surat textile hubs remain underpenetrated by digital transfer substrate suppliers despite expanding garment export volumes. BIS certification requirements for coated paper imports extend procurement timelines for small-batch decorators. Maharashtra and Gujarat industrial belts are attracting first-mover positioning from coating-optimized paper suppliers seeking regional manufacturing partnerships.
Japan
Precision coating expertise for thermal transfer ribbons concentrates among specialty paper mills serving barcode and industrial labeling applications. METI guidance on chemical substance management influences reformulation priorities for release coating alternatives. The Kanto region around Tokyo anchors demand from electronics and automotive component decorators requiring dimensional stability specifications.
Heat Transfer Paper Market Competitive Environment
Concentration sits with integrated specialty paper manufacturers possessing captive coating lines and pulp supply arrangements. The vendor base spans three tiers: multinational coated paper conglomerates with mill-direct distribution, regional converters serving price-sensitive decorators, and niche formulators targeting sublimation-specific release performance. Strategic moves center on silicone-release coating qualification partnerships and backward integration into alpha-cellulose pulp sourcing to offset packaging industry demand competition.
Within the European coating expertise tier, Neenah Coldenhove and Felix Schoeller Group exemplify formulation-driven positioning anchored by release chemistry specialization. Sappi occupies a scale-driven position among coated specialty paper infrastructure owners supplying large-format digital transfer rolls. Jiangyin Wellye Paper Industry Co., Ltd. represents cost-efficient thermal transfer substrate production serving Asia-Pacific garment decorators. These three archetypes—European formulators, integrated paper conglomerates, and Asia-Pacific cost optimizers—capture distinct procurement segments based on technical specification authority and volume scale.
| Leading Market Players |
|---|
| Sappi |
| Surya Coats Private Limited |
| Neenah Coldenhove |
| Jiangyin Wellye Paper Industry Co., Ltd. |
| MINSEO CO., LTD. |
| Felix Schoeller Group |
| CANAPA Inc. |
| Sino Coat Inc. |
| Stahls' Transfer Paper Experts |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day coating reformulation qualification timelines in European mills compress pricing power for REACH-compliant silicone-release substrates while amplifying cost premiums for qualified supply. This lead-time band concentrates procurement leverage among incumbents with pre-qualified coating lines, forcing price-sensitive decorators toward standard-grade alternatives or Asian-sourced thermal transfer papers.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across European and export markets, separating premium silicone-release formulations from standard clay-polymer coatings and economy-grade uncoated cellulose. Price differentiation hinges on ECHA compliance certification and volume-scale procurement commitments from large enterprise buyers. Pricing pressure stems from fluorinated chemistry phase-out costs accelerating coating line reconfiguration expenses. Small business decorators exhibit highest price sensitivity through web-to-print aggregator platforms, while German athletic apparel brands command specification authority with lowest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for alpha-cellulose pulp shipments to coating facilities in Germany and the Netherlands. Supply concentrates in China, Germany, and Japan, with Guangdong province hosting dense downstream decorator clusters and the Ruhr corridor anchoring European coating expertise. Raw material dependencies center on specialty pulp grades, silica and clay coating inputs, and silicone release agents. Single-source vulnerability sits with aging coating technician expertise concentrated in European and Japanese paper mills. Distribution runs through mill-direct contracts for large-format rolls and web-to-print platforms for narrow-format desktop supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where REACH qualification timelines and ECHA compliance documentation create switching costs that lock buyers into pre-qualified supplier relationships.
For Market Incumbents: Secure coating formulation partnerships with inkjet ink formulators to preempt compatibility certification disruptions from direct-to-film protocol substitution. Lock in backward integration into alpha-cellulose pulp sourcing to offset packaging industry demand competition. Prioritize capacity qualification under China's SAMR GB standards to capture six-to-twelve month first-mover windows in Zhejiang and Jiangsu textile clusters.
For New Entrants and Emerging Players: Differentiate on plant-derived coating chemistries aligned with EU Green Deal procurement criteria embedding sustainability scoring in public sector tenders. Target India's Tiruppur and Surat garment export corridors as underpenetrated white-space with BIS certification barriers delaying incumbent entry. Pursue ceramic and polymer decoration applications beyond textiles for higher margin profiles with less established specification authority.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational paper conglomerates divesting non-core specialty coating divisions amid fluorinated chemistry transition costs. Long-term viability favors assets with captive silicone-release expertise and SAMR pre-qualification status. Watch direct-to-film transfer protocol adoption rates among Etsy-integrated decorators as inflection signal for traditional heat transfer paper demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Release Coating Qualification Partnership | ECHA fluorinated restrictions force mill-ink formulator collaboration to maintain EU market access. |
| Backward Integration into Alpha-Cellulose Pulp | Packaging demand competition for specialty pulp grades threatens coating substrate input security. |
| SAMR GB Standard Pre-Certification Investment | Six-to-twelve month qualification gaps create first-mower positioning in China's textile clusters. |
| Plant-Derived Coating R&D Program | EU Green Deal procurement criteria embed sustainability scoring favoring bio-based formulations. |
| Ceramic Decoration Application Expansion | Sublimation protocols extend beyond textiles into customized drinkware with superior margin profiles. |
Study Parameters
Operator-level perspectives from coating line technicians, custom apparel decorators, inkjet ink formulators, and SAMR certification consultants anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, specialty paper trade association filings, and ECHA restriction roadmap documentation. Bottom-up demand modeling from decorator procurement patterns triangulated with top-down coating capacity assessments across European and Asia-Pacific mill networks.
Sensitivity analysis tested volume and value outputs across coating reformulation scenarios, fluorinated chemistry restriction timelines, and direct-to-film substitution rates over the projection horizon. Segmentation dimensions modeled include product type, application, technology, end-user scale tier, and regional regulatory cluster. CAGRs derived from coating capacity expansion announcements, textile export volume trajectories, and equipment installed base growth in desktop and wide-format inkjet systems.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement trajectory and stable alpha-cellulose pulp supply; material deviation in regulatory stringency or raw material availability would warrant model refresh. Specific risk factors include accelerated ECHA restriction expansion, SAMR certification timeline extensions, and rapid direct-to-film protocol adoption among small-batch decorators. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
White Top Testliner Market
Paper Products
Decor Paper Market
Paper Products
Printing and Writing Papers Market
Paper Products
Greaseproof Paper Market
Paper Products
Thin Printing Paper Market
Paper Products
Global Kraft Paper Market
Paper Products
Paper Machine Systems Market
Paper Products
Softwood Pulp Market
Paper Products
Paper and Board Technologies Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Recovered Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Aramid Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Thermal Paper Market
Paper Products
Sawn Wood Market