
 Unbleached Hardwood Kraft Pulp Market | 2026-2036
Unbleached Hardwood Kraft Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Unbleached Hardwood Kraft Pulp Market Analytics
Buyer consolidation among tissue producers is restructuring contract negotiations across the Unbleached Hardwood Kraft Pulp value chain. Suzano leverages its integrated eucalyptus fiber platform to secure long-term supply agreements. International Paper anchors North American production through extensive mill infrastructure in the southeastern United States. Mercer International competes on cost-efficient kraft processing at its European and Canadian facilities.
Unbleached hardwood kraft pulp consists of cellulose fibers extracted from deciduous tree species via the sulfate process, typically retaining lignin content above three percent to preserve structural strength and yield a brown, unbleached finish for packaging-grade applications. Sulfate pulp dominates industrial procurement due to superior tear resistance and yield efficiency relative to soda or chemithermomechanical alternatives. Folding cartons command the largest application share as food-contact packaging specifications tighten globally. Specialty papers represent the fastest-expanding segment, driven by barrier-coated grades for grease-resistant and moisture-resistant end uses.
EPA effluent guidelines in the United States, EU Ecolabel criteria under the EU Green Deal, and Brazil's IBAMA forestry licensing collectively shape fiber certification requirements and mill emissions thresholds. These frameworks push producers toward chain-of-custody documentation and reduced elemental chlorine-free processing standards. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate compliance costs and secure preferred supplier status with multinational packaging converters.
Market Dynamics
EU Green Deal mandates and the F-Gas Regulation are forcing pulp producers to reconfigure fiber sourcing documentation and mill emissions compliance, while buyer consolidation among tissue and packaging converters compresses contract negotiation cycles across the value chain.
Growth Catalysts
- E-commerce packaging volumes:Corrugated box demand from Brazil's e-commerce sector pulls unbleached hardwood kraft pulp into linerboard and medium applications at double-digit annual tonnage increments.
- REACH chemical compliance:EU Ecolabel criteria for reduced elemental chlorine-free processing create procurement preference for certified sulfate pulp in food-contact folding cartons.
- Barrier coating integration:Grease-resistant and moisture-resistant specialty grades are displacing plastic films in quick-service restaurant packaging, opening new end-use specifications for brown kraft substrates.
Market Restraints
- Eucalyptus fiber concentration:Brazil's Aracruz-Bahia corridor controls a disproportionate share of global hardwood pulp supply, creating geographic vulnerability to port congestion and currency volatility.
- Natural gas cost exposure:Kraft pulping's thermal energy intensity ties mill operating margins to European and North American natural gas price swings, compressing returns during winter demand spikes.
- Recycled fiber substitution:Containerboard mills in the US Southeast are increasing recycled-content ratios in linerboard, capping virgin pulp penetration in corrugated packaging segments.
Strategic Opportunities
- Indian packaging modernization:Food-grade folding carton specifications under FSSAI are tightening, creating first-mover advantage for certified unbleached kraft suppliers establishing local agent relationships.
- Digital print compatibility:Barrier-coated unbleached grades that accept water-based inkjet formulations are opening short-run, customized packaging contracts with craft food brands.
- EU Taxonomy alignment:CSRD disclosure requirements for Scope 3 emissions are pushing multinational converters toward chain-of-custody-certified fiber, favoring suppliers with FSC-PEFC dual certification.
Industry Challenges
- Process control engineering shortage:Kraft recovery boiler optimization and digester Kappa number automation require specialized chemical engineering talent that pulp mills in Canada and the Nordic region struggle to recruit.
- Multijurisdictional certification lag:Simultaneous pursuit of EPA effluent guidelines, EU Ecolabel, and IBAMA licensing creates documentation bottlenecks that delay new product qualification with multinational buyers by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unbleached Hardwood Kraft Pulp Market |
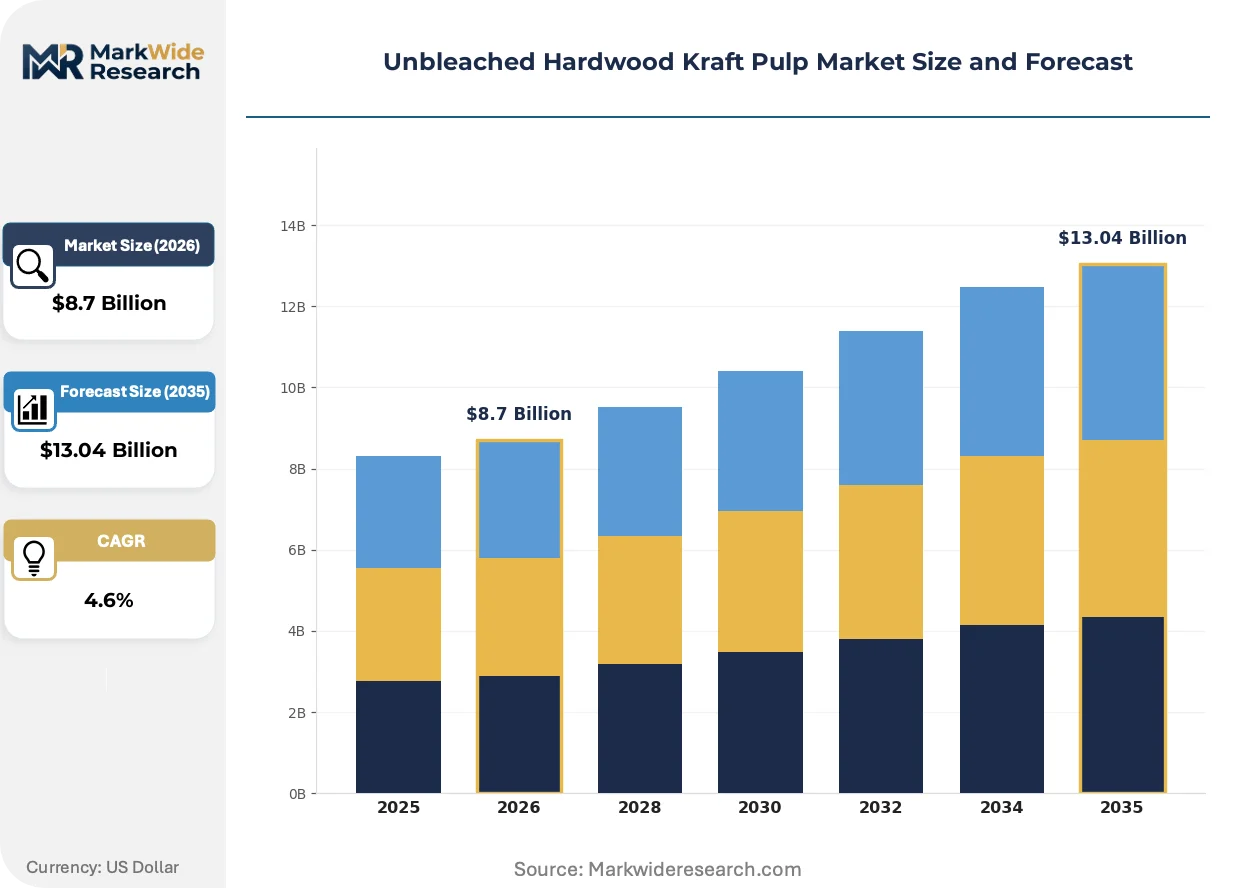
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfate Pulp, Soda Pulp, Chemithermomechanical Pulp, Bleach Kraft Pulp End User: Packaging Industry, Paper Manufacturers, Tissue Producers, Printing Sector Application: Folding Cartons, Bags, Paperboard, Specialty Papers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | International Paper, Mercer International Inc., WestRock Company, Mondi Group, Georgia-Pacific LLC, Stora Enso Oyj, Suzano, UPM-Kymmene Corporation, Canfor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unbleached Hardwood Kraft Pulp Market Evolving Landscape
Digitization of fiber tracking and process control systems is compressing quality variance and enabling mass-customization of pulp properties, while regulatory disclosure mandates restructure competitive differentiation around verified sustainability metrics rather than commodity pricing.
Advanced process control platforms integrating real-time Kappa number sensors with automated digester chemistry adjustments are modularizing how mills manage hardwood species variability. Packaging converters in the US Southeast and Northern Europe are piloting these systems to reduce rejected batches and tighten moisture-content tolerances for barrier-coating applications. The technology is modularizing quality assurance from a batch-sampling function into a continuous, specification-tunable production parameter.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents is redirecting investment toward water-based barrier coatings that rely on unbleached kraft substrates for structural integrity. Mill operators in Finland and Sweden are retrofitting coating lines to handle these formulations, anticipating specification lock-in from frozen food and ready-meal packaging brands. Folding carton converters serving EU supermarket private labels face the tightest compliance deadlines and are qualifying suppliers eighteen months ahead of mandate effective dates.
Brand-owner sustainability scorecards are restructuring how tissue and packaging buyers evaluate pulp suppliers, replacing spot-price benchmarking with multi-criteria assessments spanning carbon intensity, water stewardship, and social compliance. Multinational consumer goods companies in Germany and the Netherlands are consolidating supplier panels to those providing granular, SKU-level chain-of-custody documentation. This pattern is most visible in Northern European procurement offices where CSRD reporting obligations cascade supplier disclosure requirements through tier-one packaging contracts.
Unbleached Hardwood Kraft Pulp Market Segmentation
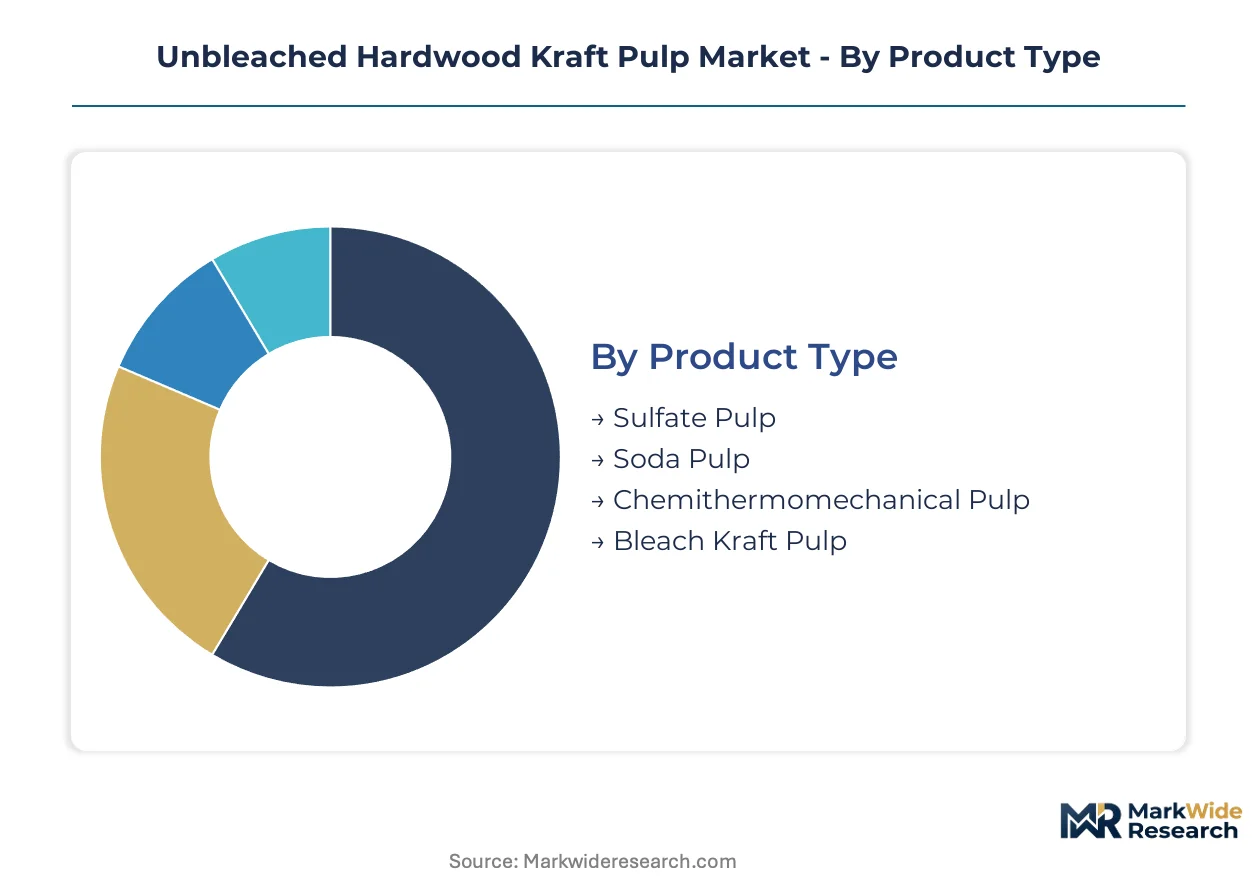
Segmentation reveals how procurement patterns diverge across pulp grades and end-use specifications. Buyers prioritize tear resistance, lignin retention, and barrier-coating compatibility when selecting unbleached hardwood kraft pulp for packaging applications.
Product Type:
Volume production concentrates on sulfate chemistry, while premium positioning accrues to specialty process variants with enhanced yield efficiency.
- Sulfate Pulp:The dominant kraft process employs sodium sulfate to extract cellulose from deciduous hardwoods, preserving lignin content above three percent for structural integrity. Brazilian eucalyptus processors and US Southeast mills anchor global tonnage output for corrugated linerboard and folding carton substrates. This segment commands the largest production share due to superior tear resistance and chemical recovery efficiency.
- Soda Pulp:Sodium hydroxide-based cooking yields higher cellulose purity with lower lignin retention than sulfate alternatives. Nordic mills in Finland and Sweden deploy this chemistry for specialty paper grades requiring enhanced brightness without full bleaching. Demand concentrates in grease-resistant packaging where modified fiber surfaces improve barrier coating adhesion.
- Chemithermomechanical Pulp:Combined chemical pretreatment and mechanical refining achieves high yield from hardwood chips with minimal lignin removal. Energy intensity limits adoption to regions with low-cost biomass power.
- Bleach Kraft Pulp:Extended processing reduces lignin below one percent for whitened finishes, sacrificing the unbleached designation. Premium tissue applications absorb limited volumes outside core packaging markets.
Today's leader: Sulfate Pulp. Tomorrow's challenger: Soda Pulp.
End User:
Customer type determines specification stringency, with food-contact packaging converters imposing the tightest chain-of-custody requirements.
- Packaging Industry:Folding carton and corrugated box converters represent the dominant demand pool, specifying unbleached kraft for structural layers and printable surfaces. E-commerce fulfillment networks in Brazil and quick-service restaurant chains in the United States drive double-digit tonnage growth for moisture-resistant grades. EU Green Deal disclosure mandates are restructuring supplier qualification around verified carbon intensity metrics.
- Paper Manufacturers:Containerboard mills integrate unbleached hardwood pulp into linerboard and medium for box construction. US Southeast mills balance virgin fiber with rising recycled content ratios to manage input costs.
- Tissue Producers:Premium towel and napkin applications require controlled lignin content for absorbency without excessive yellowing. Consolidation among tissue buyers compresses contract negotiation cycles.
- Printing Sector:Specialty publishing and industrial documentation absorb limited volumes, with digital print compatibility emerging as a specification differentiator for short-run packaging prototypes.
Packaging Industry holds current volume dominance. Specialty paper grades for food service represent the steepest expansion trajectory.
Application:
End-use functionality separates commodity tonnage from value-added specifications requiring barrier coating integration.
- Folding Cartons:Food-grade boxboard for frozen meals, dry goods, and retail packaging constitutes the largest application segment. EU Ecolabel criteria and FSSAI standards in India tighten fiber sourcing documentation for direct food contact.
- Bags:Multiwall sacks and retail carry bags exploit unbleached kraft's high tear resistance and printability. Cement and agricultural product packaging anchor demand in Brazil's industrial corridor.
- Paperboard:Solid bleached and unbleached board grades for rigid packaging and book covers require precise caliper control. Mills serving Northern European converters invest in automated thickness monitoring.
- Specialty Papers:Grease-resistant and moisture-barrier grades are displacing plastic films in quick-service packaging. Finnish and Swedish mills retrofit coating lines to capture specification lock-in from frozen food brands.
Folding Cartons maintains installed base leadership. Specialty Papers climbs fastest on barrier coating substitution.
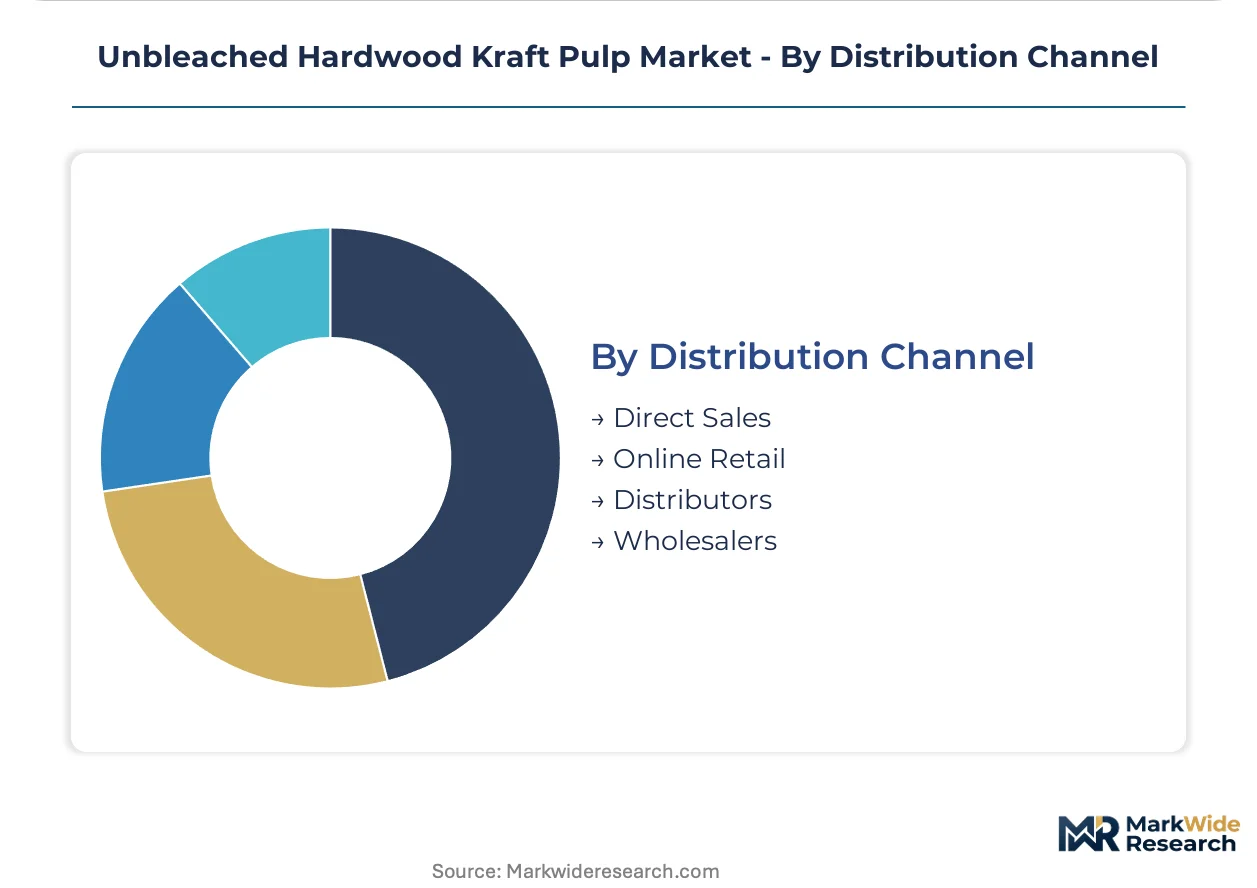
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with multinational converters bypassing intermediaries for direct mill relationships.
- Direct Sales:Long-term supply agreements dominate procurement for tissue and packaging converters with predictable volume requirements. Suzano and International Paper anchor relationships through integrated fiber platforms.
- Online Retail:Digital procurement platforms emerge for standardized grades and spot purchases, though quality verification limits adoption.
- Distributors:Regional stocking locations serve mid-sized converters requiring just-in-time delivery and technical support. Inventory carrying costs compress margins during natural gas price spikes.
- Wholesalers:Bulk aggregation of residual grades and off-specification lots serves secondary processors with flexible quality tolerances.
Direct Sales commands premium contract value. Distributors face margin pressure from buyer consolidation and digital alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands larger export volumes than the United States, yet American mills retain pricing leverage through integrated containerboard networks. Geographic concentration in the southeastern US and Brazil's eucalyptus belt defines supply-side configuration.
Brazil
E-commerce fulfillment networks and agricultural packaging drive double-digit tonnage growth for linerboard applications. IBAMA forestry licensing tightens chain-of-custody documentation for export-bound pulp. The Aracruz-Bahia corridor anchors global hardwood pulp supply, with mills retrofitting coating lines for barrier-grade specifications.
United States
Corrugated box demand from quick-service restaurant chains and frozen food brands sustains folding carton consumption. EPA effluent guidelines push southeastern mills toward reduced elemental chlorine-free processing standards. The US Southeast pine-hardwood transition zones concentrate mill infrastructure, where International Paper and Georgia-Pacific operate integrated fiber-to-boxboard platforms.
Finland
EU F-Gas Regulation deadlines accelerate water-based barrier coating qualification for frozen food packaging. EU Ecolabel criteria under the EU Green Deal mandate verified carbon intensity disclosure for supermarket private-label suppliers. Mill clusters in the Lakeland region retrofit coating lines to capture specification lock-in from Nordic frozen meal brands.
Sweden
CSRD reporting obligations cascade supplier disclosure requirements through German and Dutch converter procurement offices. REACH chemical compliance creates preference for certified sulfate pulp in food-contact applications. Stora Enso Oyj and UPM-Kymmene Corporation anchor production in the Norrland timber belt, where automated digester systems reduce quality variance.
India
FSSAI food-grade folding carton specifications tighten fiber sourcing documentation for direct food contact. The country's national packaging regulator is aligning import standards with EU Ecolabel benchmarks. Maharashtra and Gujarat industrial corridors attract first-mover suppliers establishing local agent relationships for barrier-coated kraft grades.
Unbleached Hardwood Kraft Pulp Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Unbleached Hardwood Kraft Pulp value chain. The vendor base organizes around three strategic archetypes: integrated fiber-to-paperboard conglomerates with captive pulp capacity, standalone market pulp exporters serving global converters, and regional specialty producers targeting barrier-coated grades. Competitive differentiation hinges on backward integration into plantation forestry and certification stacking for EU Taxonomy alignment.
Within the integrated conglomerate tier, International Paper and Georgia-Pacific exemplify the North American model of captive pulp feeding containerboard networks. Suzano anchors the pure-play export archetype through its Brazilian eucalyptus platform. Mercer International occupies a position bridging both models with cost-efficient kraft processing across European and Canadian facilities.
| Leading Market Players |
|---|
| International Paper |
| Mercer International Inc. |
| WestRock Company |
| Mondi Group |
| Georgia-Pacific LLC |
| Stora Enso Oyj |
| Suzano |
| UPM-Kymmene Corporation |
| Canfor Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FSC-PEFC dual-certified sulfate pulp and uncertified commodity tonnage manifests in both contract premiums and mill sourcing configurations. Buyers under CSRD disclosure obligations pay elevated rates for chain-of-custody documentation while Brazilian eucalyptus processors capture margin through integrated plantation control.
Pricing Analysis
Capacity additions in Brazil's Aracruz-Bahia corridor are reshaping price floors for standard-grade sulfate pulp. Contract-based long-term offtake dominates procurement for multinational packaging converters, with price differentiation hinging on certification tier and volume scale. Pricing pressure stems from recycled fiber substitution in US Southeast containerboard mills, where buyers blend rising post-consumer content ratios. Mid-sized converters lacking direct mill relationships exhibit highest price sensitivity, while integrated tissue producers with captive pulp demand show lowest.
Supply Chain Analysis
EU Ecolabel domestic-content mandates are reshaping sourcing patterns for supermarket private-label suppliers. Geographic concentration centers on Brazil, the United States, and Finland, with hardwood chip supply drawing from eucalyptus plantations, southeastern pine-hardwood transition zones, and Nordic timber belts. Kraft pulping's thermal energy intensity creates single-source vulnerability to natural gas price volatility. Distribution runs through direct mill relationships for volume buyers and regional distributors for mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EU F-Gas Regulation phase-down deadlines forcing packaging converters to qualify barrier-coated kraft suppliers eighteen months ahead of mandate effective dates.
For Market Incumbents: Hedge against recycled fiber substitution by deepening backward integration into eucalyptus plantation forestry and accelerating FSC-PEFC dual-certification stacking. Capture specification lock-in from frozen food brands retrofitting coating lines for water-based barrier formulations. For New Entrants and Emerging Players: Digital procurement platforms for spot-grade sulfate pulp offer the lowest-friction entry path. Target India's Maharashtra and Gujarat industrial corridors where FSSAI food-grade specifications tighten without established local supplier relationships. Lead with barrier-coated grades compatible with water-based inkjet formulations for craft food brand short-run contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play Brazilian eucalyptus exporters with uncontracted expansion capacity. Five-to-ten-year viability favors integrated fiber-to-pulp platforms over standalone mechanical mills. Watch for EU Taxonomy alignment completion rates among Northern European converters as inflection signal for certified fiber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Forestry | Suzano's captive eucalyptus supply secures margin insulation against hardwood chip spot volatility. |
| Dual Certification Stacking | FSC-PEFC documentation unlocks EU Taxonomy-aligned contracts with German supermarket private labels. |
| Barrier Coating Line Retrofit | Finnish mills capturing specification lock-in from Nordic frozen meal brands ahead of F-Gas deadlines. |
| Digital Procurement Platform Launch | Spot-grade sulfate pulp marketplaces reduce friction for mid-sized converters lacking direct mill access. |
| Long-term Supply Agreement Extension | International Paper anchors southeastern US containerboard networks through integrated fiber commitments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged pulp mill operations directors, packaging converter procurement leads, tissue manufacturer supply planners, and forestry certification auditors. Secondary validation drew from EPA effluent guideline filings, EU Ecolabel registry databases, IBAMA licensing records, and customs trade data for hardwood pulp shipments. Bottom-up capacity modeling and top-down demand estimation were cross-checked for convergence.
Segment-weighting applied differential growth coefficients across sulfate chemistry, soda process variants, and chemithermomechanical grades. End-use dimensions spanned folding cartons, corrugated linerboard, specialty barrier papers, and tissue applications. Regional production hubs, fiber certification tiers, and natural gas cost exposure fed into margin compression modeling. CAGRs were derived from trend extrapolation adjusted for regulatory mandate timing.
The model assumes a particular technology adoption path; alternative pathways for digester automation and Kappa number real-time sensing would alter the outlook. Forecasts embed assumptions around EU Green Deal implementation pace, IBAMA enforcement intensity, and eucalyptus plantation expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Medium Density Fiberboard Market
Paper Products
Household Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Paper Making Machine Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Organic Tissue Paper Market
Paper Products
Inlay Paper Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Paper Machine Systems Market
Paper Products
Printing Paper Market
Paper Products
Chemical Cellulose Market
Paper Products
Paper Machinery Market
Paper Products
Sawn Wood Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Global Pulp and Paper Machinery Market