
 Blackcurrant Concentrate Market | 2026-2036
Blackcurrant Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Blackcurrant Concentrate Market Outlook
Buyer concentration among beverage manufacturers is rebalancing as mid-sized functional drink brands fragment procurement across specialized concentrate suppliers rather than consolidating around commodity processors. DOEHLER Group leverages its integrated fruit processing platform to sustain long-term supply contracts with multinational beverage clients. Kiril Mischeff Ltd anchors its position through deep relationships with UK and European juice compounders. SVZ International competes on scale, operating multiple processing facilities that control regional blackcurrant sourcing corridors.
Blackcurrant concentrate is a viscous or powdered extract derived from Ribes nigrum berries, typically standardized to 65°Brix for liquid forms or spray-dried to below 5% moisture for powder variants, used primarily as a coloring agent, acidulant, and polyphenol source in formulated foods and beverages. Liquid concentrates retain dominant volume share among product types due to their compatibility with existing beverage manufacturing infrastructure and lower reconstitution costs for industrial users. Nutraceuticals represents the fastest-expanding end-user segment as anthocyanin standardization enables health-positioned supplement formulations with measurable polyphenol content claims.
EFSA maintains strict maximum residue limits under EU Regulation 396/2005 for blackcurrant imports, while the FDA enforces FSVP rules that require U.S. importers to verify foreign supplier compliance with preventive controls. The EU Green Deal's pesticide reduction targets are forcing concentrate processors to document integrated pest management practices across their contracted orchards. Stakeholders must monitor evolving bilateral trade agreements between New Zealand and Asian markets, as tariff shifts could redirect Pacific-origin concentrate flows and alter competitive access for European processors.
Market Dynamics
Poland and New Zealand now control the majority of global blackcurrant processing capacity, creating a dual-polar supply structure that forces beverage manufacturers to navigate concentrated sourcing corridors and EFSA pesticide residue documentation requirements.
Growth Catalysts
- Anthocyanin standardization:Nutraceutical formulators now demand measurable polyphenol content claims, pulling concentrate procurement toward certified high-anthocyanin suppliers. This specification tier commands sustained volume commitments from supplement manufacturers.
- EU Green Deal pesticide reduction targets:The Farm to Fork Strategy mandates integrated pest management documentation across contracted orchards, favoring processors with established compliance infrastructure over commodity traders.
- Functional beverage proliferation:Mid-sized drink brands fragment procurement across specialized concentrate suppliers rather than consolidating around commodity processors, opening contract opportunities for regional specialists.
Market Restraints
- Input cost volatility:Energy-intensive concentration processes expose margins to natural gas price swings in European processing facilities, particularly affecting spray-dried powder variants.
- Supply concentration risk:Dual-polar processing dominance in Poland and New Zealand creates vulnerability to regional weather events or bilateral trade disruptions affecting Pacific-origin concentrate flows.
- Regulatory friction:FDA FSVP rules require U.S. importers to verify foreign supplier compliance with preventive controls, adding documentation overhead and inspection liability for cross-Atlantic shipments.
Strategic Opportunities
- Asian market tariff restructuring:Evolving bilateral agreements between New Zealand and Asian markets could redirect Pacific-origin concentrate flows, creating first-mover access for processors establishing direct Asian distribution.
- Clean-label acidulant substitution:Synthetic colorant and acidulant replacement mandates in formulated foods position blackcurrant concentrate as a dual-function ingredient in bakery and confectionery applications.
- Carbon accounting convergence:EU CSRD reporting requirements and corporate Scope 3 emissions tracking create premium positioning for processors with documented orchard-to-concentrate carbon footprints.
Industry Challenges
- Analytical chemistry skill scarcity:Anthocyanin quantification and pesticide residue testing require specialized chromatography expertise that concentrate processors struggle to staff at scale.
- Legacy equipment retrofit costs:Existing 65°Brix liquid concentrate lines require capital-intensive modification to produce low-moisture spray-dried powders demanded by nutraceutical customers.
- Certification timeline compression:Organic and regenerative agriculture certifications now require multi-year orchard transition periods that outpace customer contract cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackcurrant Concentrate Market |
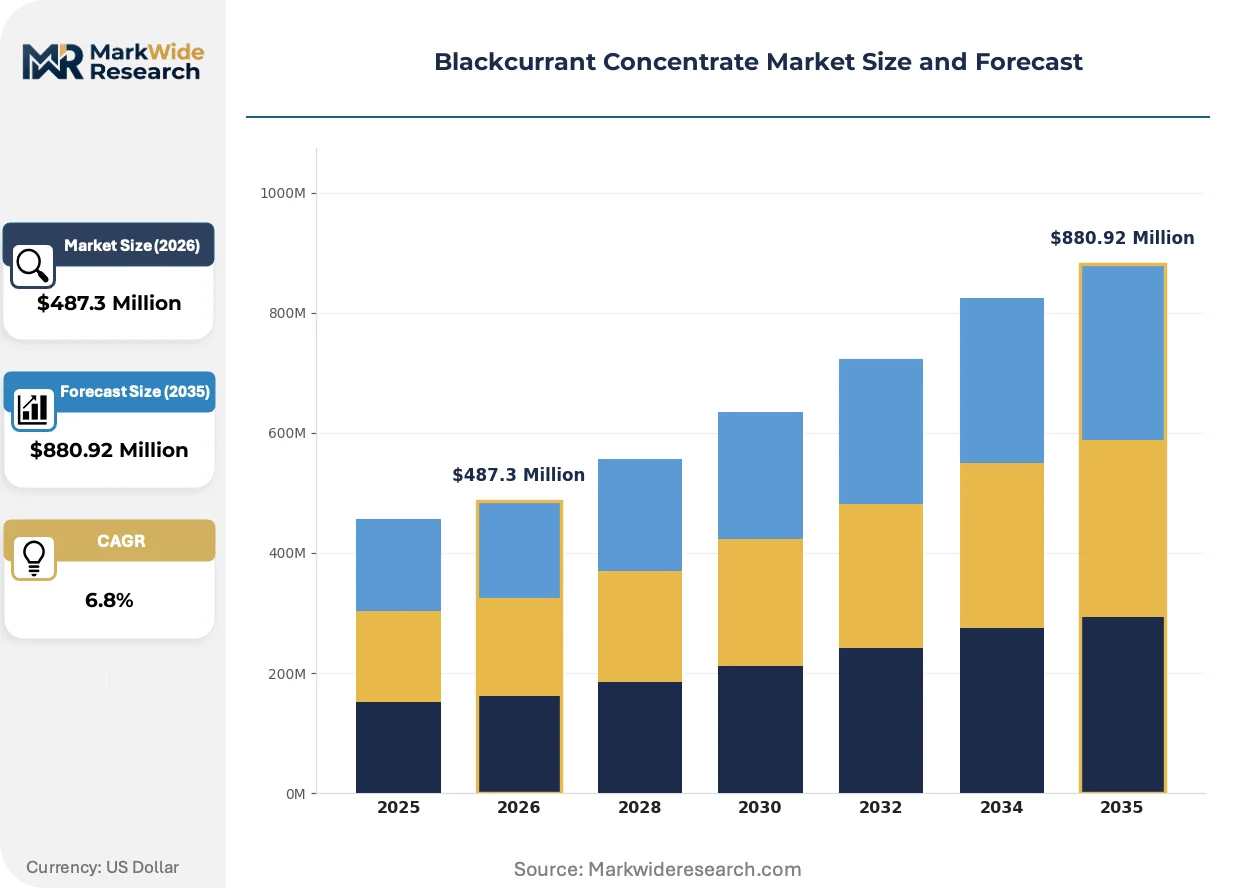
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrates, Powdered Extracts, Freeze-Dried, Puree End User: Food Industry, Beverage Manufacturers, Nutraceuticals, Cosmetics Distribution Channel: Online Sales, Supermarkets, Wholesale Distributors, Specialty Stores Geographical Demand: North America, Europe, Asia Pacific, Latin America |
| Companies Covered | DOEHLER Group, Archer Daniels Midland Company, Sums Fruits, Hortex Holding, Kiril Mischeff Ltd, Ariza, SVZ International, Cobell Ltd, Blackcurrant New Zealand Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackcurrant Concentrate Market Strategic Shifts
Processing technology and procurement specifications are converging to reshape how blackcurrant concentrate moves from orchard to formulated product, with regulatory compliance emerging as a competitive differentiator rather than a baseline requirement.
Low-temperature vacuum concentration is expanding into premium nutraceutical supply chains as processors preserve heat-sensitive anthocyanin compounds for standardized polyphenol claims. Supplement manufacturers in Germany and Switzerland now specify vacuum-processed concentrate in procurement tenders, compressing margins for traditional thermal processors while enabling contract premiums for certified low-temperature suppliers.
EFSA's tightening maximum residue limits under EU Regulation 396/2005 now require batch-level pesticide documentation for all imported blackcurrant concentrates entering European compounders. This regulatory burden favors vertically integrated processors with captive orchard networks over traders sourcing from spot markets, pushing mid-sized beverage brands toward long-term supply agreements with documented provenance.
Mid-sized functional drink brands now disaggregate concentrate procurement across multiple specialized suppliers rather than consolidating volume with single commodity processors. This fragmentation pattern is most visible in UK and Nordic markets, where smaller batch sizes and customized Brix specifications are displacing standardized bulk contracts that dominated procurement through the 2010s.
Blackcurrant Concentrate Market Segmentation
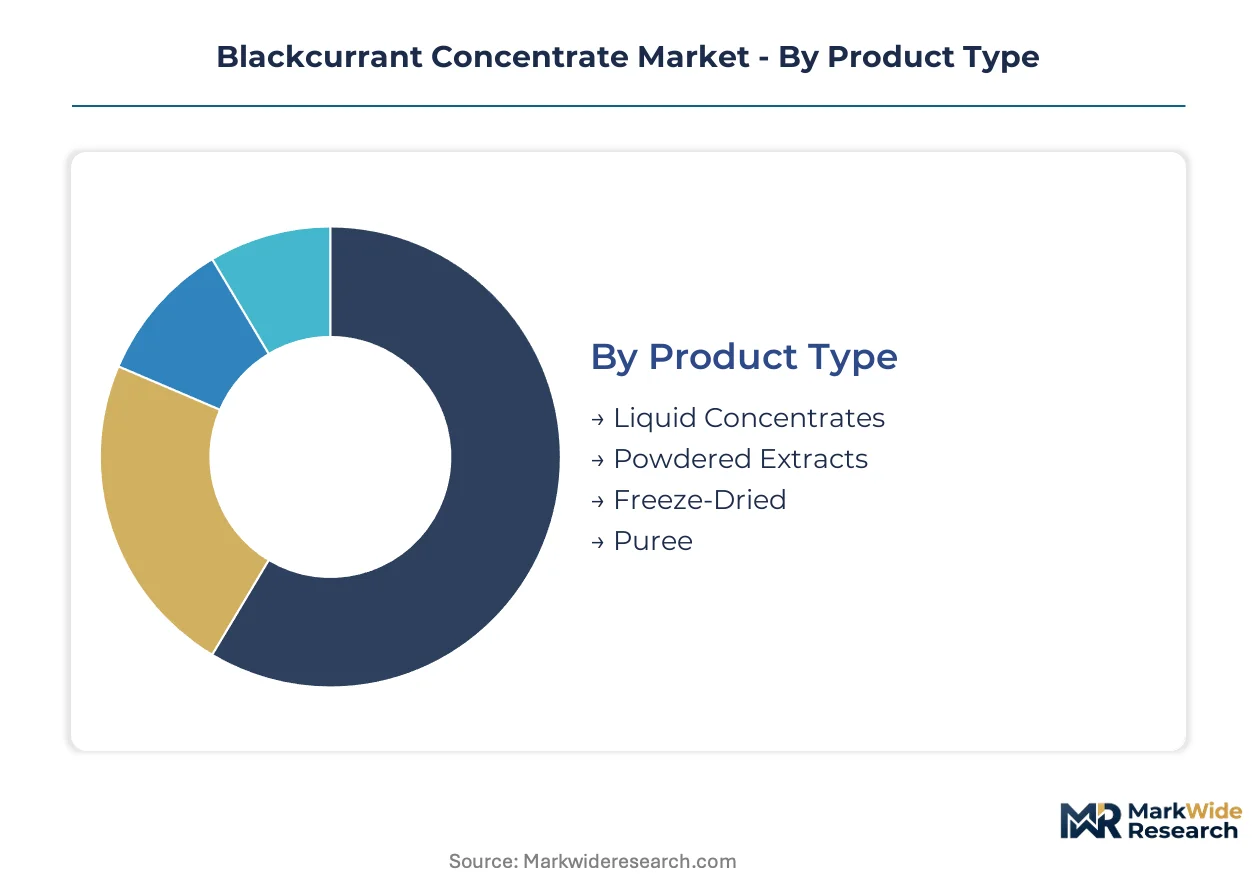
Blackcurrant concentrate procurement patterns diverge sharply across formulation requirements and regulatory exposure. Manufacturers select product formats and supply channels based on heat sensitivity needs, anthocyanin standardization demands, and end-use certification burdens.
Product Type:
Beverage compounders and nutraceutical formulators prioritize thermal stability and reconstitution economics when selecting concentrate formats.
- Liquid Concentrates:Standardized to 65°Brix, these viscous extracts dominate beverage manufacturing due to compatibility with existing pasteurization lines and lower reconstitution energy costs. Polish and New Zealand processors control bulk liquid supply corridors into European and Asian markets.
- Powdered Extracts:Spray-dried to below 5% moisture, these variants enable precise dosing in supplement capsules and dry beverage mixes. German and Swiss nutraceutical manufacturers now specify low-temperature vacuum processing to preserve heat-sensitive anthocyanin compounds for standardized polyphenol claims.
- Freeze-Dried:Premium tier retains volatile aromatic compounds for high-end confectionery and artisanal applications.
- Puree:Unconcentrated format serves bakery and dairy applications requiring intact fruit texture rather than colorant functionality.
Liquid concentrates lead on scale; powdered extracts lead on momentum.
End User:
Regulatory documentation intensity and anthocyanin specification tiers separate procurement patterns across consuming industries.
- Beverage Manufacturers:Functional drink brands fragment procurement across specialized suppliers for customized Brix specifications and clean-label positioning. EFSA pesticide residue documentation under EU Regulation 396/2005 now mandates batch-level verification for all imports.
- Nutraceuticals:Supplement formulators demand measurable polyphenol content claims, pulling procurement toward certified high-anthocyanin suppliers with chromatography-verified standardization. This segment is expanding most quickly as health-positioned products capture shelf space.
- Food Industry:Bakery and confectionery applications utilize blackcurrant concentrate for dual-function acidulant and natural colorant replacement.
- Cosmetics:Anthocyanin-rich extracts target antioxidant claims in skincare formulations with lower volume requirements but premium pricing tolerance.
Beverage manufacturers anchor volume demand; nutraceuticals command specification premiums.
Distribution Channel:
Order scale and certification complexity determine whether buyers engage direct processors or intermediated supply tiers.
- Wholesale Distributors:Bulk liquid concentrate moves through established fruit ingredient distributors serving mid-sized compounders without direct processor relationships. DOEHLER Group and SVZ International leverage long-term contracts with these intermediaries.
- Online Sales:E-commerce platforms enable small-batch procurement for artisanal producers and regional supplement manufacturers seeking specialized specifications without minimum order constraints.
- Supermarkets:Retail-packaged concentrates for home beverage preparation represent marginal volume.
- Specialty Stores:Health food channels distribute premium organic and regenerative-certified variants to consumer markets.
Wholesale distributors retain volume dominance; online sales are gaining share fastest among emerging formulators.
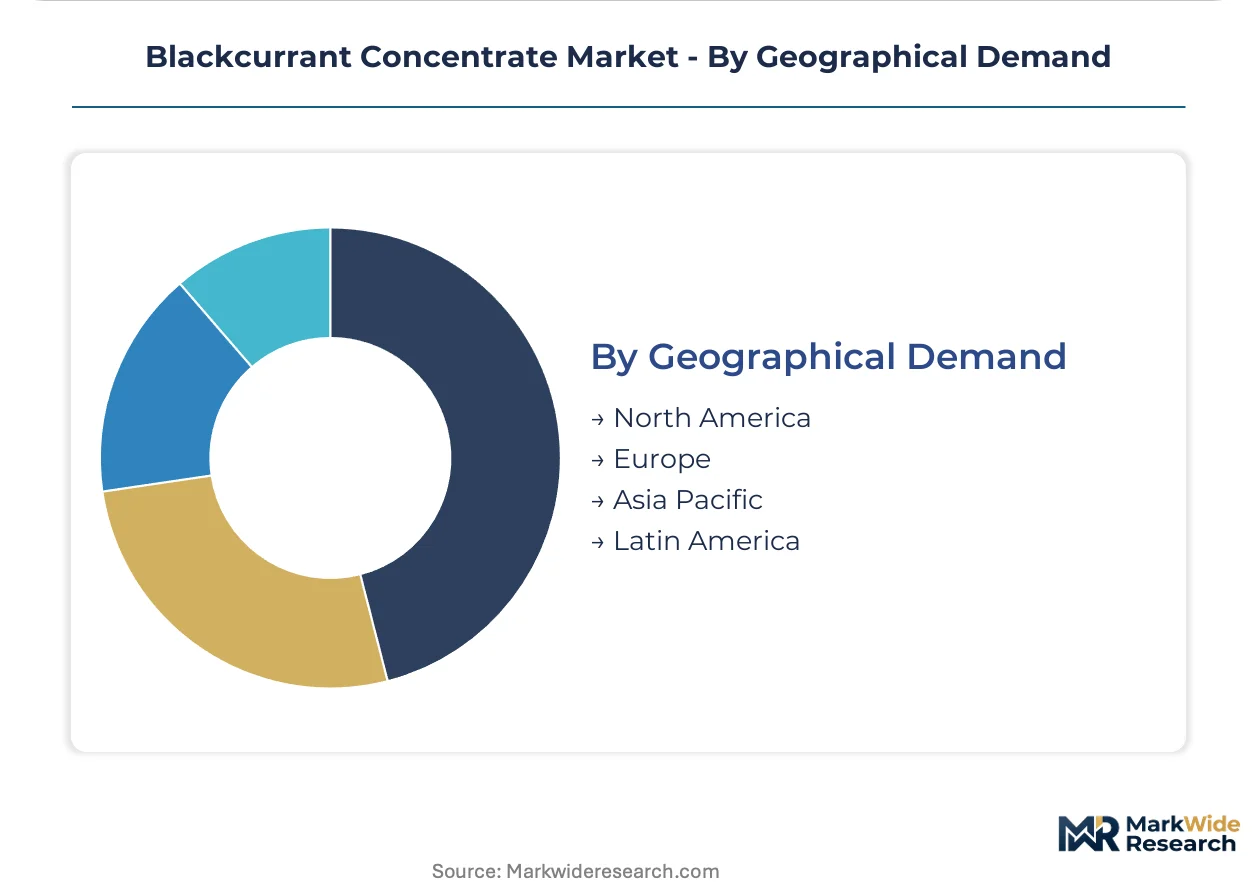
Geographical Demand:
Regulatory stringency and functional beverage penetration create divergent growth trajectories across consuming regions.
- Europe:EU Green Deal pesticide reduction targets and EFSA maximum residue limits force concentrate processors to document integrated pest management practices. German, UK, and Nordic markets show highest functional beverage formulation activity.
- North America:FDA FSVP rules require U.S. importers to verify foreign supplier compliance with preventive controls, adding documentation overhead for cross-Atlantic shipments from Polish and New Zealand origins.
- Asia Pacific:Evolving bilateral agreements between New Zealand and Asian markets could redirect Pacific-origin concentrate flows, altering competitive access for European processors.
- Latin America:Emerging demand centers on natural colorant substitution in processed foods with lower regulatory documentation requirements.
Europe leads on specification intensity; Asia Pacific presents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland processes more blackcurrant concentrate than New Zealand, yet both nations now dominate separate supply corridors into European and Asian markets respectively. This dual-polar structure forces beverage manufacturers to navigate concentrated sourcing geography and divergent regulatory documentation requirements.
Germany
Functional beverage compounders in Bavaria and North Rhine-Westphalia drive premium concentrate procurement for anthocyanin-standardized formulations. EFSA maximum residue limits under EU Regulation 396/2005 mandate batch-level pesticide documentation for all imports. Cologne and Hamburg host major juice compounding clusters where mid-sized brands fragment procurement across specialized suppliers.
United Kingdom
Mid-sized functional drink manufacturers in London and the Midlands disaggregate concentrate sourcing for customized Brix specifications and clean-label positioning. The UK Food Standards Agency enforces retained EU pesticide residue standards post-Brexit. Kiril Mischeff Ltd anchors supply relationships with regional compounders through deep procurement partnerships.
Poland
Domestic processors control bulk liquid concentrate supply corridors into European markets, leveraging captive orchard networks across Mazovia and Podlasie regions. EU Green Deal Farm to Fork Strategy mandates integrated pest management documentation across contracted growing areas. Warsaw and Łódź concentrate blackcurrant processing infrastructure that supplies multinational beverage clients.
New Zealand
Pacific-origin concentrate flows serve Asian markets through evolving bilateral trade agreements that could redirect regional competitive access. The Ministry for Primary Industries enforces export certification aligned with destination market pesticide standards. Canterbury and Nelson growing regions supply Blackcurrant New Zealand Inc members with processing scale for international shipment.
United States
Cross-Atlantic concentrate imports face FDA Foreign Supplier Verification Program rules requiring importers to verify foreign supplier compliance with preventive controls. Beverage manufacturers in California and the Northeast source primarily from Polish and New Zealand origins. New York and Los Angeles metropolitan areas concentrate nutraceutical formulators demanding high-anthocyanin standardized extracts.
Blackcurrant Concentrate Market Competitive Environment
Polish producers anchor one tier; New Zealand specialists hold Pacific supply corridors. The vendor base concentrates around vertically integrated processors with captive orchard networks rather than commodity traders. Three archetypes dominate: integrated fruit processing platforms, regional specialists with deep compounding relationships, and scale-driven operators controlling sourcing corridors. Competitive moves center on long-term supply contract capture and low-temperature vacuum processing capacity expansion for nutraceutical-grade certification.
Within the integrated processing tier, DOEHLER Group exemplifies the platform model through sustained multinational beverage client relationships. Among UK-based specialists, Kiril Mischeff Ltd occupies a position anchored by regional juice compounder partnerships. At the scale-driven end, SVZ International represents operators with multiple facilities controlling regional sourcing corridors. These three companies illustrate how geographic origin and customer relationship depth separate competitive positioning in concentrate supply.
| Leading Market Players |
|---|
| DOEHLER Group |
| Archer Daniels Midland Company |
| Sums Fruits |
| Hortex Holding |
| Kiril Mischeff Ltd |
| Ariza |
| SVZ International |
| Cobell Ltd |
| Blackcurrant New Zealand Inc |
| Others |
Value Chain & Pricing Dynamics
Natural gas costs for spray-drying operations in European processing facilities feed directly into three-tier pricing stratification across premium nutraceutical-grade, standard beverage-grade, and economy industrial-grade concentrate tiers.
Pricing Analysis
Capacity additions in New Zealand are reshaping price floors for Pacific-origin concentrate entering Asian markets. Pricing stratifies across premium vacuum-processed anthocyanin-standardized extracts, standard 65°Brix liquid concentrates, and economy bulk commodity grades. Cost compression in spray-dried powder variants is intensifying because energy-intensive thermal processing exposes margins to natural gas volatility. Beverage manufacturers show highest price sensitivity due to fragmented procurement across multiple suppliers, while nutraceutical formulators tolerate premium positioning for certified polyphenol content.
Supply Chain Analysis
Freight costs for refrigerated liquid concentrate shipments from Poland to German compounding clusters run through established overland corridors with documented pesticide residue certification at each border checkpoint. Supply concentrates in Poland and New Zealand with captive orchard networks across Mazovia and Canterbury regions. Raw material flows draw from contracted blackcurrant cultivars, natural gas for thermal processing, and chromatography reagents for anthocyanin quantification. Single-source vulnerability persists where bilateral trade disruptions between New Zealand and Asian markets could redirect Pacific-origin concentrate flows. Distribution runs through wholesale fruit ingredient distributors serving mid-sized compounders without direct processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through low-temperature vacuum processing certification that commands premium positioning from nutraceutical formulators seeking standardized polyphenol claims.
For Market Incumbents: Cement long-term supply contracts with multinational beverage clients by documenting integrated pest management practices across captive orchard networks. Expand low-temperature vacuum concentration capacity to capture nutraceutical-grade certification premiums before thermal processors retrofit legacy 65°Brix lines. Threat substitution from synthetic colorants and acidulants accelerates as clean-label mandates spread through bakery and confectionery applications. For New Entrants and Emerging Players: Capture white-space in online sales channels serving artisanal producers and regional supplement manufacturers seeking specialized Brix specifications without minimum order constraints. Target nutraceutical formulators in Germany and Switzerland demanding chromatography-verified anthocyanin standardization with vacuum-processed concentrate offerings. Go-to-market leverage rests on direct Asian distribution partnerships as New Zealand bilateral trade agreements evolve. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemistry skill scarcity constrains anthocyanin quantification and pesticide residue testing capabilities at scale. Long-term viability favors vertically integrated processors with captive orchard networks and established EFSA compliance infrastructure over commodity traders. Acquisition target archetype: regional specialists with deep juice compounder relationships and existing low-temperature processing capacity. Signal to watch: carbon accounting convergence under EU CSRD reporting requirements creating premium positioning for documented orchard-to-concentrate footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Vacuum Processing Capacity Expansion | Preserves heat-sensitive anthocyanins for nutraceutical-grade certification demanded by German supplement manufacturers. |
| Integrated Pest Management Documentation Investment | Meets EU Green Deal Farm to Fork Strategy mandates for contracted orchard network compliance. |
| Direct Asian Distribution Partnership Development | Captures first-mover access as New Zealand bilateral trade agreements redirect Pacific-origin concentrate flows. |
| Carbon Footprint Certification Program | Aligns with EU CSRD Scope 3 emissions tracking requirements for premium processor positioning. |
| Analytical Chemistry Capability Buildout | Addresses skill scarcity in chromatography-verified anthocyanin quantification for standardized polyphenol claims. |
Study Parameters
Direct dialogue with concentrate processors, beverage compounder procurement directors, nutraceutical formulator R&D leads, and fruit ingredient distributors grounded this analysis in operational realities. Secondary validation drew from EFSA pesticide residue databases, EU Farm to Fork Strategy implementation reports, customs trade flow records, and SEC filings of publicly traded fruit processing platforms. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand segmentation by end-use industry.
Market size outputs across the analysis window reflect disaggregated modeling by product type, end-user segment, and distribution channel with geographic demand clusters. CAGRs were derived from segment-level growth trajectories weighted by procurement pattern shifts toward nutraceutical applications. Forecast inputs incorporated energy cost pass-through assumptions for spray-dried powder variants and regulatory compliance timeline compression for organic certification transitions.
Underlying measurement precision varies by segment; liquid concentrate volumes carry tighter precision than emerging freeze-dried premium tiers with limited processor participation. Forecasts reflect documented assumptions about bilateral trade agreement evolution and EFSA maximum residue limit enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Sesame Oil Market
Ingredients
Modified Soya Flour Market
Ingredients
Chickpea Flour Market
Ingredients
Lipids Market
Ingredients
Self-Rising Flour Market
Ingredients
Vegetable Glycerin Market
Ingredients
Vegetable Extract Market
Ingredients
Encapsulated Salt Market
Ingredients
Clean Label Starch Market
Ingredients
South America Fats and Oil Market
Ingredients
Pea Flour Market
Ingredients
Glucomannan Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Bean Pasta Market