
 Sesame Oil Market | 2026-2036
Sesame Oil Market Size, Share, and Industry Trends Forecast 2026-2036
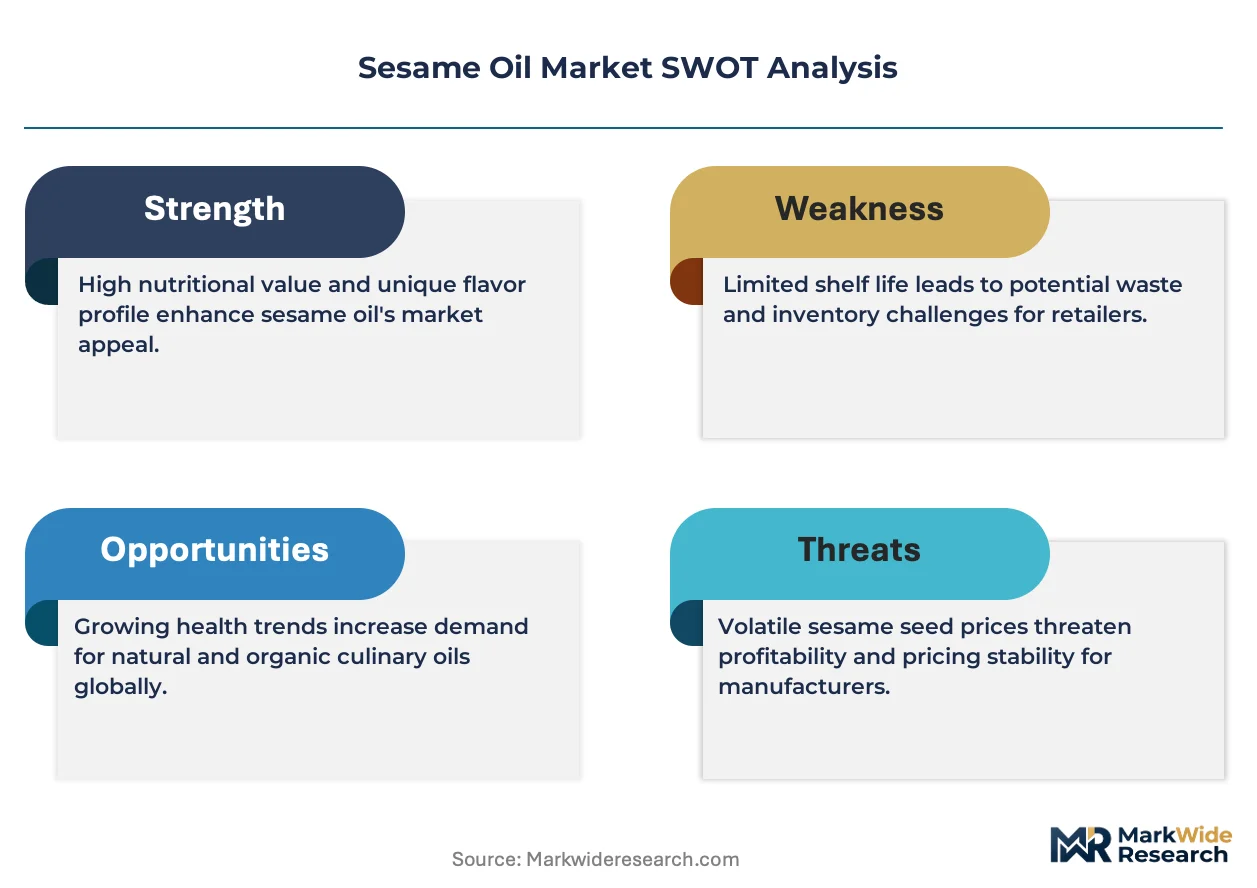
Sesame Oil Market Analysis
The premium-to-commodity split in sesame oil is rebalancing around extraction method and geographic origin rather than price alone. Cold-pressed variants command shelf space in North American and European specialty retail, while refined grades dominate Southeast Asian food manufacturing. Kadoya Sesame Mills Incorporated anchors Japanese domestic quality benchmarks through vertically controlled roasting protocols. Dipasa Group leverages its Mexican seed sourcing network to supply North American processors with consistent oleic profiles. Wilmar International competes across Asian mass-market channels with integrated crushing and refining capacity.
Sesame oil is a fixed oil expressed from Sesamum indicum seeds, typically containing 80-85% unsaturated fatty acids with lignan antioxidants including sesamin and sesamolin that confer oxidative stability exceeding most vegetable oils. Its primary commercial purpose spans culinary frying and dressing applications, cosmetic emollient formulations, and pharmaceutical excipient use where high smoke points and biocompatible lipid profiles matter. Cold pressed variants capture margin pools in organic and wellness-oriented retail, while refined grades occupy institutional food service and processed food manufacturing. The pharmaceutical segment sustains specialized demand for ultra-pure grades meeting pharmacopeial standards, though food and beverage applications retain dominant volume share across all distribution channels.
FDA food labeling requirements and EFSA novel food evaluations shape export market access for sesame oil processors seeking cross-border placement. BIS quality certification in India and JIS standards in Japan create divergent compliance burdens that filter supplier participation by technical capability. Stakeholders must monitor evolving allergen disclosure mandates and carbon intensity reporting rules that threaten to segment supply chains by regulatory sophistication rather than production cost alone.
Market Dynamics
Extraction method certification now splits the sesame oil trade into parallel supply chains with incompatible cost structures and customer bases. Cold-pressed organic grades command dedicated logistics and retail placement, while refined bulk grades compete on oleic stability metrics for food manufacturing procurement.
Growth Catalysts
- EFSA Novel Food Pathway:European Union clearance protocols for traditional oil processing methods are opening shelf access for heritage extraction techniques previously excluded from formal retail channels.
- Ayurvedic Export Demand:India's FSSAI quality benchmarks for therapeutic-grade oils are creating certified supply pools that pharmaceutical formulators in Germany and Switzerland now specify in raw material procurement.
- Supercritical CO2 Extraction:This solvent-free processing technology is capturing antioxidant fractions at commercial scale, enabling premium cosmetic applications that roasted-seed pressing cannot replicate.
Market Restraints
- Sesame Seed Price Volatility:Sudanese and Ethiopian supply disruptions transmit directly to crusher margins, as these origins supply over sixty percent of internationally traded seed.
- REACH Registration Burden:European Chemicals Agency compliance costs for imported oil batches filter out small-scale Asian exporters lacking dedicated regulatory affairs capacity.
- High-Oleic Sunflower Substitution:Seed oil blenders in North American snack manufacturing are reformulating away from sesame where oxidative stability is the sole performance requirement.
Strategic Opportunities
- Vietnamese Cold-Pressed Segment:Underdeveloped domestic branding in this origin creates white space for traceable single-estate oils targeting Japanese and South Korean premium retail.
- Pharmacopeial Grade Expansion:United States Pharmacopeia and European Pharmacopoeia compliance investments unlock excipient contracts with contract development and manufacturing organizations.
- Direct-to-Consumer Subscription:Fresh-pressed oil clubs bypassing traditional wholesale distribution are capturing lifetime value in wellness-oriented North American households.
Industry Challenges
- Roasting Technician Scarcity:Traditional Japanese and Korean roasting mastery requires multi-year apprenticeship, constraining capacity expansion for authentic toasted oil production.
- Organic Certification Timeline:Three-year conversion periods for conventional sesame farms block supply response to sudden spikes in certified organic demand.
- Legacy Refinery Retooling:Southeast Asian mass-market processors face capital requirements to meet tightening FDA traceability rules for allergen cross-contamination prevention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sesame Oil Market |
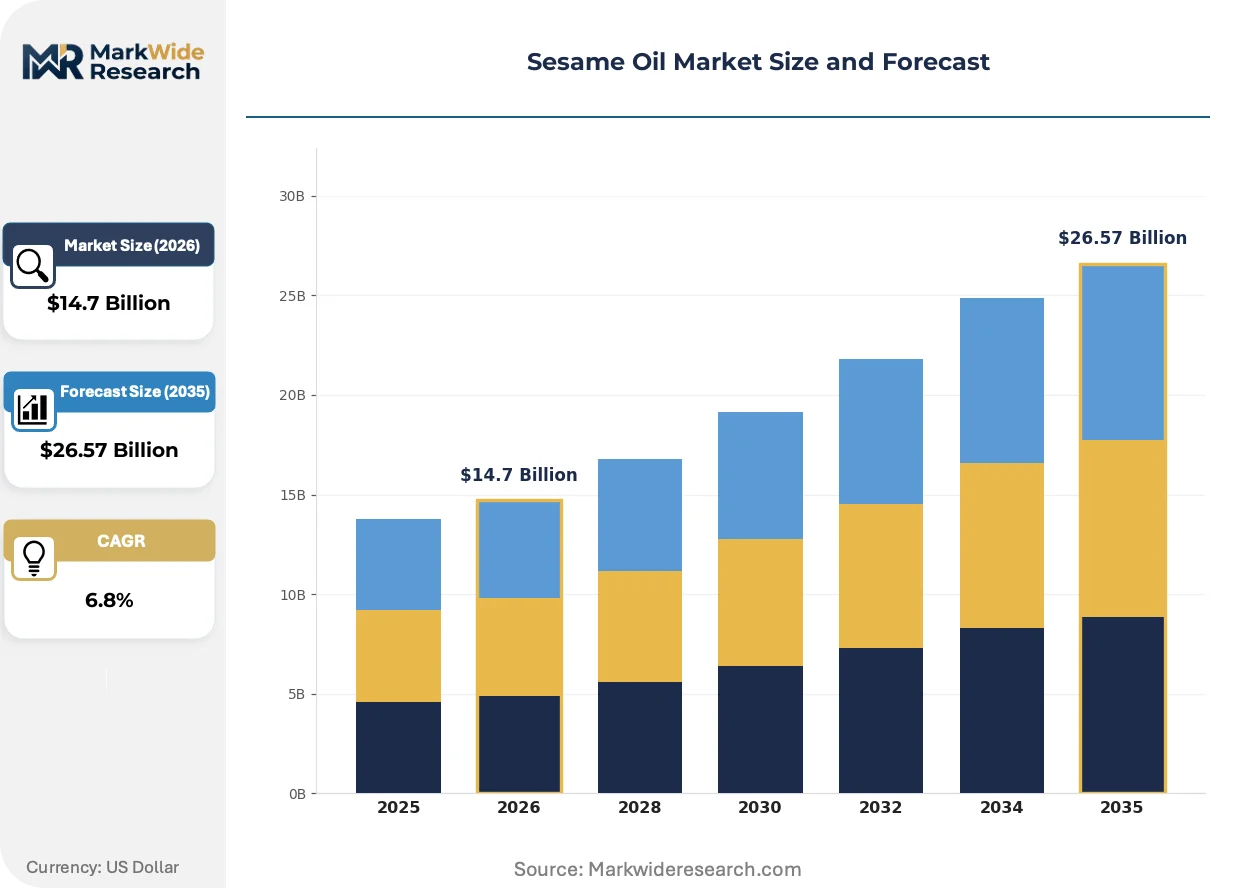
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Roasted, Blended End Use Industry: Food & Beverage, Cosmetic, Pharmaceutical, Biofuel Packaging Type: Glass Bottles, Plastic Containers, Metal Cans, Pouches Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Dipasa Group, Anhui Yanzhuang, Kadoya Sesame Mills Incorporated, Lee Kum Kee, Shandong Ruifu, Chee Seng Oil Factory Pte Ltd., Wilmar International, Manishankar Oil Pvt. Ltd., La Tourangelle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sesame Oil Market Emerging Trajectories
Processing transparency and origin verification are becoming primary competitive variables as buyers separate aesthetic claims from measurable quality attributes. Technology deployment and regulatory adaptation now determine market access more than raw production volume.
Blockchain-enabled seed-to-bottle traceability is decentralizing quality assurance away from centralized laboratory testing toward distributed ledger verification. Organic retailers in California and Nordic markets are adopting this infrastructure fastest, with pilot programs operational across Ethiopian and Indian supply chains. The structural consequence is compressing the premium that undifferentiated organic certification previously commanded.
United States FDA Food Safety Modernization Act traceability rules are forcing exporters to retrofit batch coding and allergen segregation protocols. Crushing facilities in Gujarat and Tamil Nadu are investing in dedicated sesame-only production lines to satisfy these requirements. North American import distributors now specify FSMA-compliant documentation as a condition of purchase order acceptance.
Specialty food buyers are rotating procurement toward single-origin oils with named village or cooperative provenance, displacing blended origin products in premium retail. Japanese department store food halls and European delicatessen chains are driving this specification change. The shift is most visible in South Korean and Taiwanese markets where traceability storytelling commands measurable price premiums over generic organic labeling.
Sesame Oil Market Segmentation
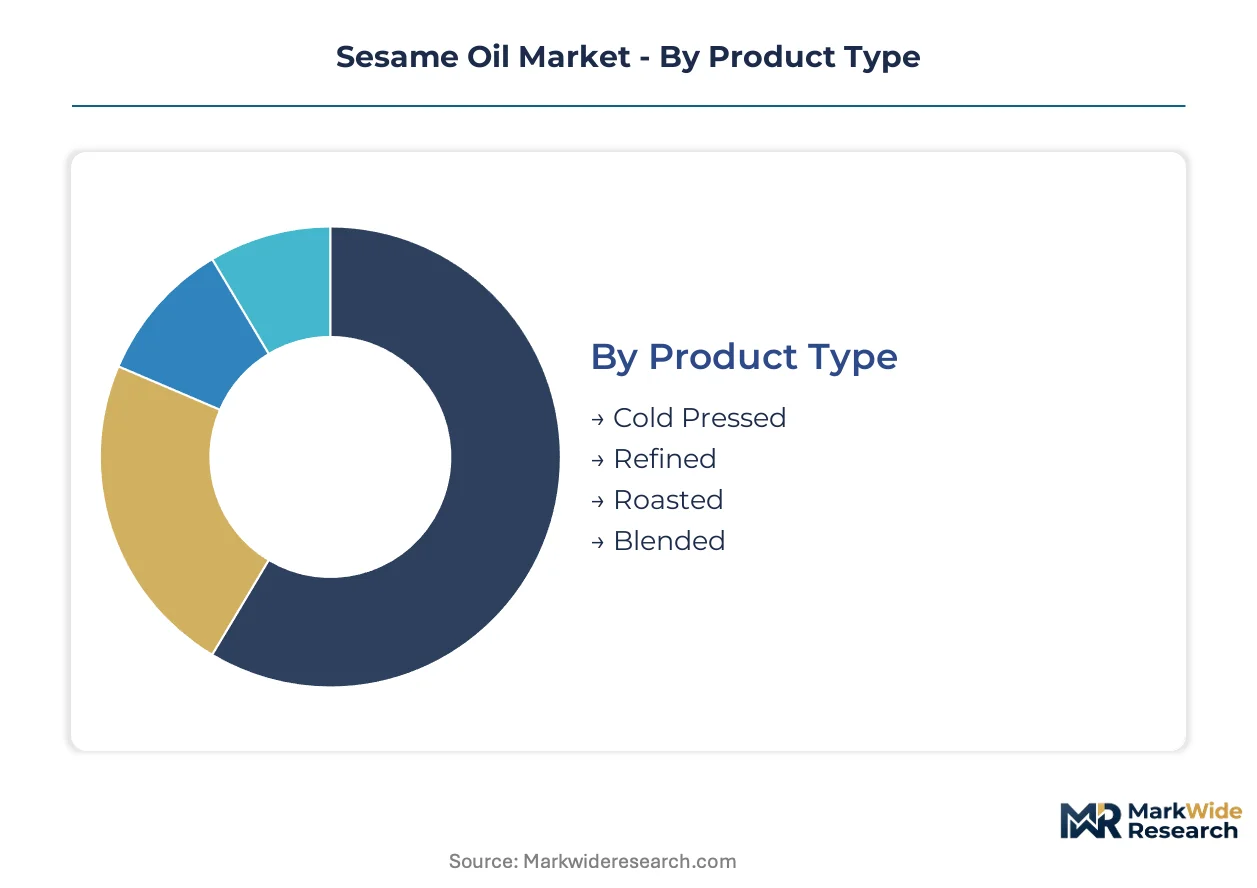
Sesame oil processors navigate four intersecting segmentation dimensions that determine margin capture and regulatory exposure. Product type and end-use specifications drive technical compliance requirements, while packaging and channel choices shape working capital intensity and brand positioning.
Product Type:
Supply concentration among Ethiopian and Sudanese seed origins forces processors to align extraction methods with destination market regulatory thresholds.
- Cold Pressed:Mechanical extraction below 40°C preserves lignan antioxidant complexes including sesamin and sesamolin. European organic retailers and North American wellness distributors specify this grade for premium shelf placement, with EFSA novel food evaluations creating formal market access pathways.
- Refined:Degummed and deodorized through chemical or physical processes to achieve neutral flavor profiles and extended fryer life. Southeast Asian food manufacturers in Vietnam and Thailand absorb volume here for instant noodle seasoning and cooking oil blends.
- Roasted:Traditional Japanese and Korean roasting protocols develop characteristic amber color and nutty aromatic compounds through controlled Maillard reactions. Apprentice-trained technicians in Gifu prefecture and Jeolla province constrain scalable supply.
- Blended:Formulated combinations with sunflower, peanut, or rice bran oils optimize cost-performance ratios for institutional food service procurement in India and Bangladesh.
Refined grades absorb the bulk of installed capacity; cold pressed is expanding most quickly.
End Use Industry:
Application-driven purity standards split manufacturing investment between food-grade infrastructure and pharmacopeial-capable cleanroom facilities.
- Food & Beverage:Dominant volume channel spanning premium dressing applications in Japanese department store food halls to mass-market frying in Indonesian street food supply chains. FDA Food Safety Modernization Act traceability rules now govern import documentation.
- Cosmetic:Emollient formulations leverage sesame oil's biocompatible lipid profile and oxidative stability for Korean skincare and French pharmacy channels. Supercritical CO2 extraction enables antioxidant fraction capture for active ingredient concentrates.
- Pharmaceutical:United States Pharmacopeia and European Pharmacopoeia compliance unlocks excipient contracts with Swiss and German contract manufacturing organizations. Ultra-low peroxide specifications require nitrogen-blanketed handling infrastructure.
- Biofuel:Emerging feedstock for biodiesel transesterification where high unsaturated fatty acid content meets cetane number requirements. Indian policy support through the National Biofuel Policy anchors pilot deployment.
Food and beverage commands absolute volume leadership; pharmaceutical applications are climbing the fastest on margin per liter.
Packaging Type:
Material selection trades shelf appeal against logistics economics and regulatory migration limits.
- Glass Bottles:Premium positioning in Japanese and South Korean gift markets with UV protection for lignan preservation. Weight and fragility elevate landed costs for export markets.
- Plastic Containers:HDPE and PET formats dominate North American mass retail with tamper-evident closures. California and EU single-use plastic directives are forcing rPET transition investments.
- Metal Cans:Tinplate and aluminum formats serve institutional food service and industrial bulk segments across Indian and Bangladeshi processing clusters. Corrosion resistance specifications vary by humidity exposure.
- Pouches:Stand-up flexible packaging gains traction in Southeast Asian convenience retail and airline catering channels. Oxygen barrier multilayer films extend shelf life without refrigeration.
Plastic containers hold the largest installed filling capacity; pouches are gaining share fastest in emerging market convenience formats.
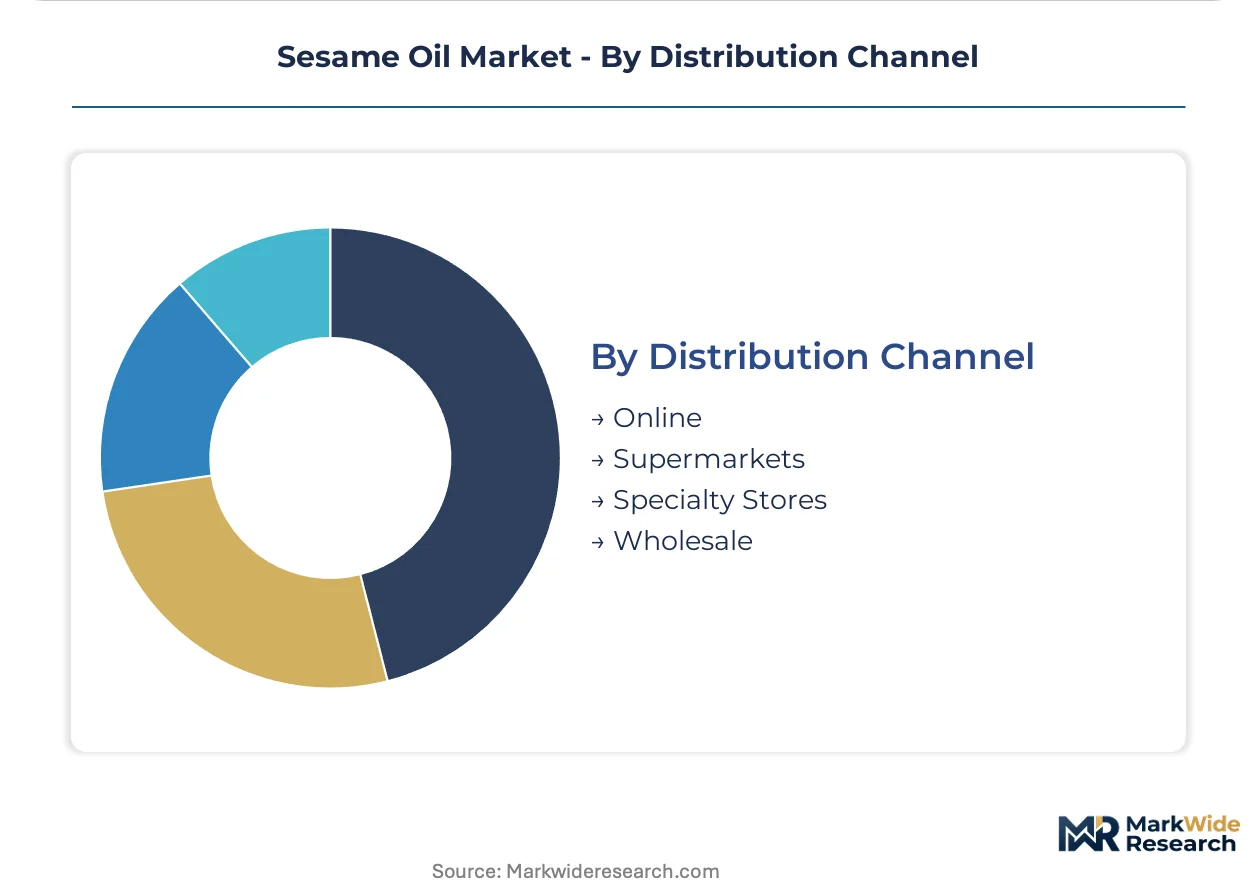
Distribution Channel:
Channel economics determine whether processors capture brand margin or surrender value to intermediaries.
- Online:Direct-to-consumer subscription models in California and New York wellness segments bypass wholesale markups. Fresh-pressed clubs emphasize harvest dating and origin storytelling.
- Supermarkets:Mass retail placement in Kroger, Tesco, and Aeon networks requires slotting fee investments and promotional calendar compliance. Private label penetration compresses branded margin pools.
- Specialty Stores:Organic grocers and Asian food halls in London, Paris, and Vancouver command premium positioning for single-origin and cold-pressed grades. Blockchain traceability verification increasingly conditions shelf access.
- Wholesale:Food service distributors and industrial ingredient suppliers in Gujarat and Tamil Nadu move volume to restaurant chains and processed food manufacturers. FSMA-compliant documentation now gates purchase order acceptance.
Wholesale channels handle the greatest volume throughput; online direct-to-consumer is expanding most quickly on customer lifetime value metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's crushing corridor around Rajkot and Jamnagar anchors sesame oil processing capacity, with integrated refineries serving both domestic Ayurvedic formulators and export markets bound for Europe and North America.
India
Ayurvedic therapeutic-grade demand from Kerala and Maharashtra drives FSSAI-certified supply pools for pharmaceutical formulators in Germany. BIS quality certification creates compliance filters that advantage established processors in Gujarat and Tamil Nadu. Rajkot's crushing clusters are retrofitting dedicated sesame-only production lines to satisfy FDA Food Safety Modernization Act traceability documentation.
China
Cold-pressed organic grades from Shandong and Anhui provinces supply Japanese and South Korean premium retail channels. SAMR food safety standards and GB quality benchmarks shape export readiness for cross-border placement. Zhengzhou's processing hubs are expanding supercritical CO2 extraction capacity for antioxidant fraction capture in cosmetic applications.
Japan
Traditional roasted oil demand from Tokyo and Osaka department store food halls sustains apprentice-trained technician scarcity in Gifu prefecture. JIS standards and METI quality protocols create domestic benchmarks that resist price-based import competition. Kadoya's vertically controlled roasting protocols in Aichi prefecture set quality reference points for the regional trade.
United States
Wellness-oriented subscription models in California and New York bypass wholesale markups through direct-to-consumer fresh-pressed clubs. FDA Food Safety Modernization Act traceability rules and evolving allergen disclosure mandates filter supplier participation by regulatory sophistication. Los Angeles and San Francisco specialty retailers are adopting blockchain-enabled seed-to-bottle verification fastest.
Germany
Pharmaceutical excipient demand from Swiss and German contract manufacturing organizations specifies United States Pharmacopeia and European Pharmacopeia compliance. EFSA novel food evaluations and REACH registration requirements filter small-scale exporters lacking dedicated regulatory affairs capacity. Hamburg's import distributors now specify FSMA-compliant documentation as a condition of purchase order acceptance.
Sesame Oil Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across parallel supply chains with incompatible cost structures. Integrated seed crushers with captive roasting and refining capacity face specialty retailers who outsource production to certified toll processors. Three archetypes dominate: vertically controlled heritage brands, scale-driven mass-market refiners, and agile organic specialists. Competitive moves concentrate on origin verification infrastructure and pharmacopeial compliance investments rather than price compression alone.
Within the heritage-tier segment, Kadoya Sesame Mills Incorporated exemplifies vertically controlled quality protocols, while Dipasa Group represents North American supply chain anchoring through Mexican seed sourcing networks. Wilmar International occupies the scale-driven mass-market position across Asian food manufacturing channels. These three entities illustrate how extraction method certification and geographic origin control now determine competitive positioning more than raw crushing volume.
| Leading Market Players |
|---|
| Dipasa Group |
| Anhui Yanzhuang |
| Kadoya Sesame Mills Incorporated |
| Lee Kum Kee |
| Shandong Ruifu |
| Chee Seng Oil Factory Pte Ltd. |
| Wilmar International |
| Manishankar Oil Pvt. Ltd. |
| La Tourangelle |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps across Gujarat and Tamil Nadu anchor crushing capacity through generational capital structures that resist short-term margin compression, enabling pricing discipline even when Sudanese seed volatility transmits downstream. Their patient financing contrasts with private-equity-rolled-up specialists in North American distribution, who face quarterly yield pressure that accelerates spot-market purchasing and erodes contract-based price stability.
Pricing Analysis
Value-based pricing anchored to lignan antioxidant retention separates cold-pressed organic grades from commodity refined volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by extraction certification, with EFSA novel food clearance and USDA organic status commanding measurable premiums over undifferentiated bulk. Pricing pressure stems from high-oleic sunflower substitution in North American snack manufacturing, where oxidative stability alone drives procurement decisions. Mass-market food manufacturers exhibit highest price sensitivity, while Japanese department store buyers and German pharmaceutical formulators accept premiums for traceable provenance and pharmacopeial compliance.
Supply Chain Analysis
Refurbishment and reconditioning flows for crushing equipment extend asset life across Indian processing clusters where capital replacement cycles lag Western benchmarks. Geographic supply concentrates in Sudan, Ethiopia, and India, with over sixty percent of internationally traded seed originating from the first two. Raw material dependencies rest on monsoon-dependent acreage expansion, port logistics at Mombasa and Djibouti, and jute bagging specifications for moisture control. Single-source vulnerability runs through Red Sea shipping lanes, where geopolitical disruption threatens seed delivery windows. Distribution runs through integrated crushers with captive roasting capacity in Rajkot, toll processors in Zhengzhou, and import distributors in Hamburg specifying FSMA-compliant documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sesame oil processing stands at an extraction-method transition, with supercritical CO2 technology displacing traditional roasted-seed pressing for antioxidant fraction capture in cosmetic and pharmaceutical applications.
For Market Incumbents: Acquire nitrogen-blanketed handling infrastructure and USP-compliant cleanroom capacity to defend pharmacopeial grade positioning against emerging CO2 extraction specialists. Secure backward integration into Ethiopian and Sudanese seed sourcing through long-term offtake agreements that lock in oleic profile consistency, insulating margins from spot-market volatility that threatens refined grade profitability. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for Vietnamese single-estate oils targeting South Korean and Japanese premium retail, bypassing slotting fee barriers that gate supermarket placement. White space concentrates in blockchain-verified organic segments where heritage extraction storytelling commands price premiums over undifferentiated certification, with fresh-pressed clubs capturing lifetime value through harvest dating and cooperative provenance narratives. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmacopeial-capable processors in India and China facing temporary FDA documentation compliance costs, where regulatory sophistication gaps filter weaker competitors. Long-term viability centers on excipient contract durability with Swiss and German CDMOs, as pharmaceutical applications climb fastest on margin per liter. Watch for EFSA novel food pathway acceleration as inflection indicator signaling premium retail access expansion for heritage extraction methods.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Grade Certification | Unlocks excipient contracts with German and Swiss CDMOs requiring USP and EP compliance. |
| Blockchain Traceability Deployment | Enables shelf access at California organic retailers and Nordic markets adopting distributed ledger verification. |
| Supercritical CO2 Extraction Scale-Up | Captures antioxidant fractions for Korean skincare and French pharmacy active ingredient concentrates. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale markups through fresh-pressed clubs emphasizing harvest dating in wellness segments. |
| Backward Integration into Seed Origins | Secures consistent oleic profiles from Ethiopian and Sudanese supply zones against price volatility. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across crushing plant managers in Gujarat, procurement leads at Japanese food manufacturers, organic certification auditors, and pharmaceutical excipient buyers in Basel and Frankfurt. FDA FSMA documentation, EFSA novel food registers, FSSAI quality benchmarks, and Indian customs export declarations supplied quantitative foundations. Bottom-up volume modeling from installed crushing capacity triangulated against top-down demand estimates from end-use industry consumption patterns.
Data-stream reconciliation across extraction method certification databases, seed origin trade flows, and retail scanner data enabled segmentation-level projections across the analysis window. The analytical framework modeled product type, end-use industry, packaging format, and distribution channel dimensions, with CAGRs derived from trend extrapolation of lignan antioxidant demand in wellness retail and pharmacopeial specification tightening in European markets. Forecast inputs incorporated organic conversion timeline constraints and roasting technician apprenticeship scarcity as supply-side ceiling factors.
The model holds under stable Red Sea logistics and monsoon-dependent seed crop yields; deviation in Sudanese supply disruptions or REACH registration cost escalation would shift volume and margin projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Flaxseed Derivatives Market
Ingredients
North America Agar Market
Ingredients
Hexane-Free Protein Market
Ingredients
Durian Powder Market
Ingredients
Honey Powder Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Valerian Root Oil Market
Ingredients
Heart Health Ingredients Market
Ingredients
Bean Flour Market
Ingredients
Hydrogenated Starch Market
Ingredients
Global Tomato Powder Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Omega 6 Market
Ingredients
Global Dry Yeast Market
Ingredients
Pomace Olive Oil Market
Ingredients
Modified Maize Starch Market