
 Leprosy Treatment Market | 2026-2036
Leprosy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Leprosy Treatment Market Outlook
Subscription-based drug replenishment programs for multidrug therapy is repositioning how national leprosy programs procure treatment supplies. Johnson & Johnson anchors global supply through its sustained donation of rifampicin to WHO elimination campaigns. Novartis leverages its clofazimine manufacturing network to serve endemic markets across South Asia and sub-Saharan Africa. Lupin Limited competes on cost-optimized dapsone production for public health procurement channels.
Leprosy treatment encompasses pharmacological intervention against Mycobacterium leprae infection using rifampicin, clofazimine, and dapsone in standardized multidrug regimens lasting 6-12 months depending on classification. The primary purpose is bacteriological cure, prevention of disability, and interruption of transmission chains in endemic populations. Antibiotics dominate value flows due to WHO-mandated multidrug therapy protocols, while immunomodulators represent a faster-growing segment addressing leprosy reactions and neuritis complications. Hospitals capture the largest patient volume for initial diagnosis and complex case management, though homecare settings are expanding for stable continuation-phase therapy.
WHO elimination strategies, FDA oversight of rifampicin quality standards, and national pharmaceutical regulators in endemic countries collectively shape product specifications and market access conditions. India's CDSCO enforces bioequivalence requirements for generic dapsone that filter suppliers eligible for government tenders. Stakeholders must monitor shifts in WHO drug donation commitments and domestic manufacturing incentives as determinants of supply security and pricing trajectories.
Market Dynamics
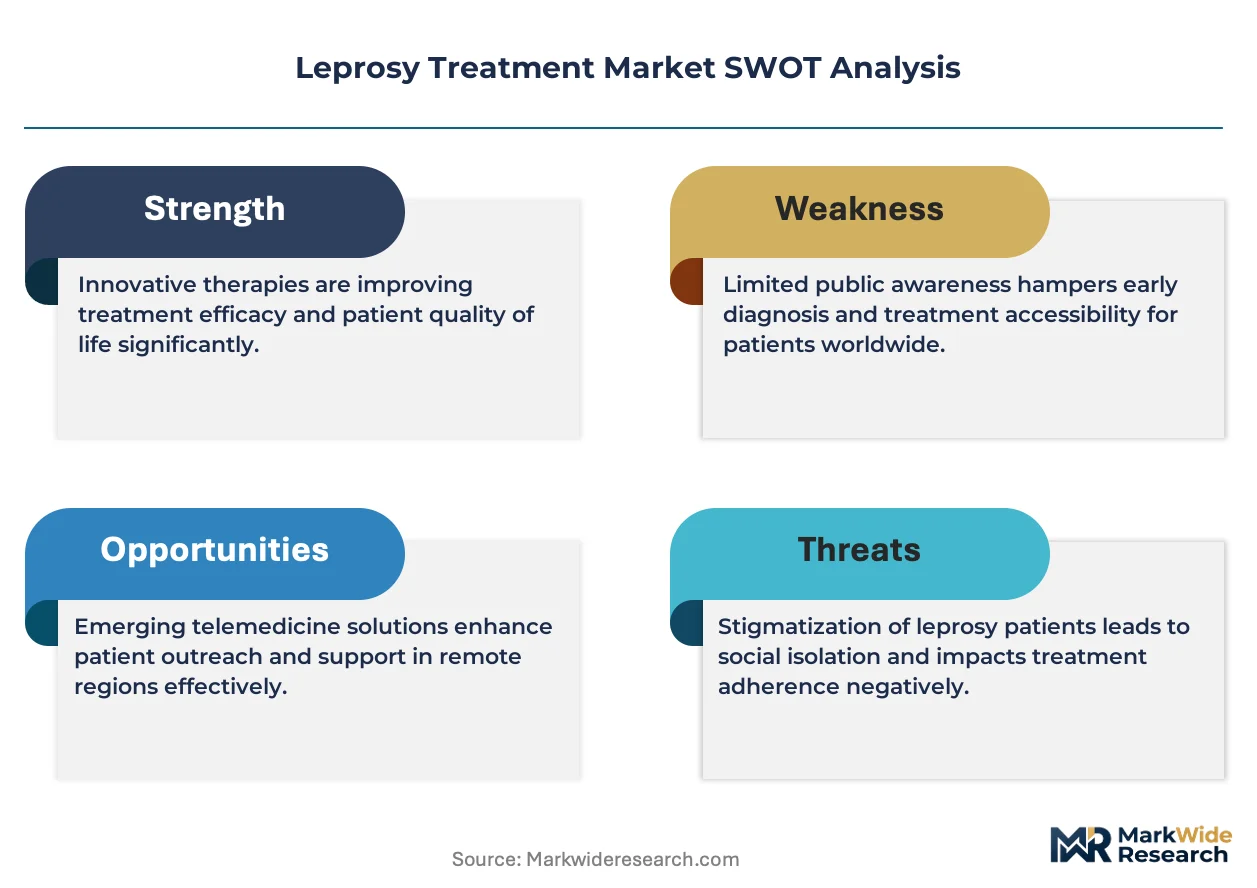
WHO's sustained multidrug therapy donation programs are compressing commercial pricing power while expanding treatment access across endemic corridors. This external supply intervention is restructuring how national programs procure antibiotics and manage inventory cycles.
Growth Catalysts
- India's CDSCO bioequivalence mandates:Generic dapsone manufacturers meeting these standards gain eligibility for government tenders, expanding supplier pools for national elimination programs.
- Subscription replenishment models:Automated drug resupply systems reduce stockout risk in remote health facilities across Brazil's Amazon basin.
- Diagnostic polymerase chain reaction tools:Molecular confirmation of Mycobacterium leprae infection shortens treatment initiation timelines in Indonesian district hospitals.
Market Restraints
- Rifampicin supply concentration:Single-source donation dependency creates vulnerability if WHO commitments fluctuate or manufacturing disruptions occur.
- Clofazimine production bottlenecks:Limited active pharmaceutical ingredient manufacturers outside India constrain rapid scale-up during outbreak responses.
- Reaction management complexity:Erythema nodosum leprosum and reversal reactions require corticosteroid co-therapy, complicating standardized procurement protocols.
Strategic Opportunities
- Homecare continuation therapy:Stable paucibacillary cases managed through community health workers reduce hospital bed occupancy in Indonesia's archipelago regions.
- Post-exposure prophylaxis protocols:Single-dose rifampicin for household contacts creates incremental demand beyond active case treatment.
- Digital adherence technologies:Medication event reminder systems using basic mobile infrastructure address treatment completion gaps in rural India.
Industry Challenges
- Leprosy reaction prediction:No reliable biomarker exists to anticipate neuritis episodes, forcing reactive rather than preventive clinical management.
- Disability prevention integration:Self-care group formation requires sustained community health worker deployment that strains peripheral health system capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leprosy Treatment Market |
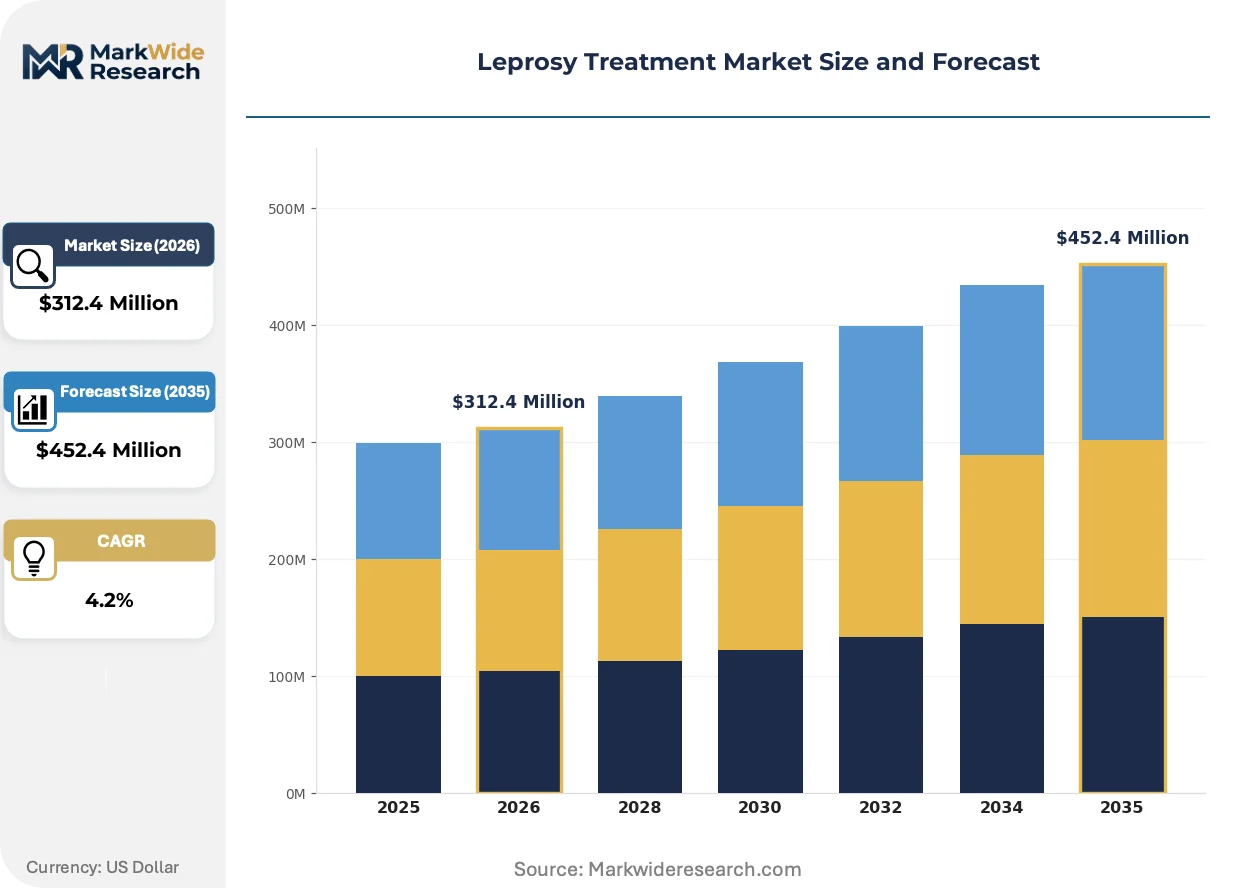
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $452.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Immunomodulators, Vaccines, Corticosteroids End User: Hospitals, Clinics, Long-term Care Facilities, Homecare Settings Delivery Mode: Oral, Intravenous, Topical, Combination Therapy Stage of Disease: Early Stage, Moderate Stage, Advanced Stage, Relapsed Cases |
| Companies Covered | Johnson & Johnson, Lupin Limited, Novartis AG, Pfizer Inc., Cipla Limited, Sanofi, Bayer AG, Cadila Pharmaceuticals, Glaxo Smithcline Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leprosy Treatment Market Strategic Shifts
Leprosy care delivery is fragmenting across institutional and community settings as national programs pursue elimination targets. Technology and policy shifts are compressing diagnostic timelines while reshaping procurement relationships.
Loop-mediated isothermal amplification (LAMP) diagnostics is overtaking slit-skin smear microscopy in district-level confirmation workflows. Brazilian municipal health secretariats in Minas Gerais and Pará states are deploying these point-of-care platforms to reduce referral delays. The technology is overtaking centralized laboratory dependency by enabling same-day treatment initiation in peripheral clinics.
WHO's 2021-2030 Global Leprosy Strategy is tightening reporting requirements for disability grade and treatment completion metrics. National programs must now disaggregate data by gender and disability status, forcing health information system upgrades. India's NLEP and Brazil's SINAN registry are absorbing these compliance costs through dedicated federal transfers.
Consolidated tendering by state procurement agencies is displacing fragmented district-level purchasing in India's endemic states. Bihar and Uttar Pradesh have shifted to centralized rate-contracting for multidrug therapy kits, compressing supplier margins but improving supply security. This concentration is most visible where disease burden justifies volume-based negotiation leverage.
Leprosy Treatment Market Segmentation
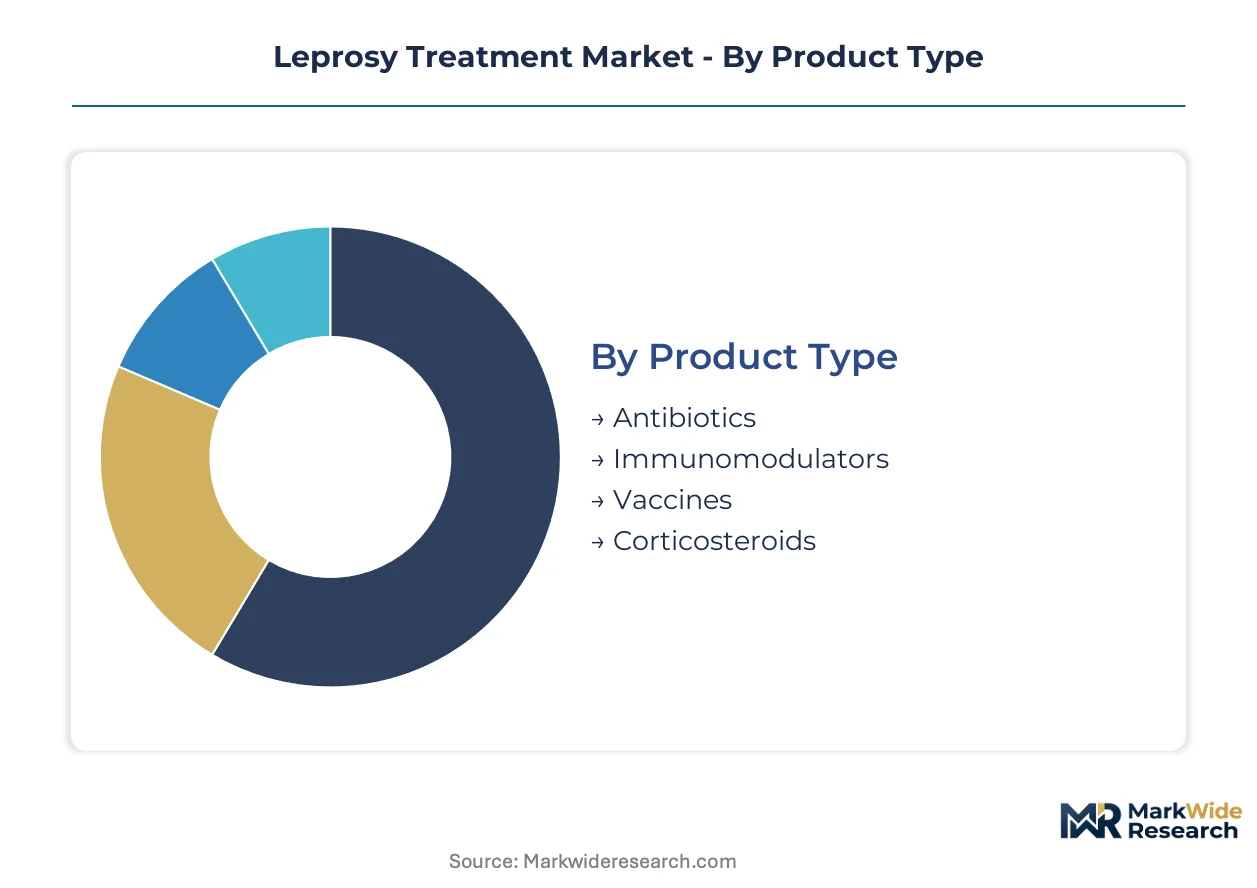
Leprosy treatment procurement varies sharply by product integration depth. Standalone antibiotic regimens dominate government tenders, while embedded immunomodulator combinations command premium positioning in reaction management protocols.
Product Type:
Standalone antibiotics anchor first-line protocols, whereas embedded immunomodulator systems address complication cascades requiring corticosteroid co-administration.
- Antibiotics:Rifampicin, clofazimine, and dapsone constitute WHO-mandated multidrug therapy with standardized dosing schedules. India's NLEP procures these through centralized rate-contracting in Bihar and Uttar Pradesh, compressing supplier margins while securing volume commitments.
- Immunomodulators:Thalidomide and pentoxifylline modulate cytokine storms in erythema nodosum leprosum reactions. Brazilian municipal health secretariats in Pará state deploy these in district hospitals where neuritis complications exceed antibiotic-only management capacity.
- Vaccines:Bacillus Calmette-Guérin and leprosy-specific candidates remain investigational with limited commercial procurement channels.
- Corticosteroids:Prednisolone bridges acute reaction episodes in WHO protocols.
Volume placements concentrate in Antibiotics; the faster expansion belongs to Immunomodulators.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from lean community-based delivery models.
- Hospitals:Tertiary facilities manage initial diagnosis, disability grading, and complex reaction episodes requiring specialist intervention. Indonesian district hospitals absorb polymerase chain reaction confirmation tools to shorten treatment initiation timelines.
- Clinics:Peripheral health posts handle stable case detection and referral triage. Brazil's Amazon basin clinics deploy automated drug resupply systems to reduce stockout risk in remote corridors.
- Long-term Care Facilities:Rehabilitation centers address disability prevention through self-care group formation.
- Homecare Settings:Community health workers supervise continuation-phase therapy in Indonesia's archipelago regions.
Patient volume concentrates in Hospitals; the steepest expansion trajectory belongs to Homecare Settings.
Delivery Mode:
Application context dictates route selection, with oral dominance in field settings and intravenous reserve for severe complications.
- Oral:Fixed-dose combination tablets simplify adherence in community-based programs. India's CDSCO bioequivalence mandates filter generic suppliers eligible for government tenders.
- Intravenous:Reserved for hospital-managed severe reactions requiring rapid corticosteroid loading.
- Topical:Limited to wound care adjuncts in disability management protocols.
- Combination Therapy:Sequential oral-intravenous protocols address reaction flare-ups.
Procurement volume concentrates in Oral; the fastest uptake belongs to Combination Therapy.
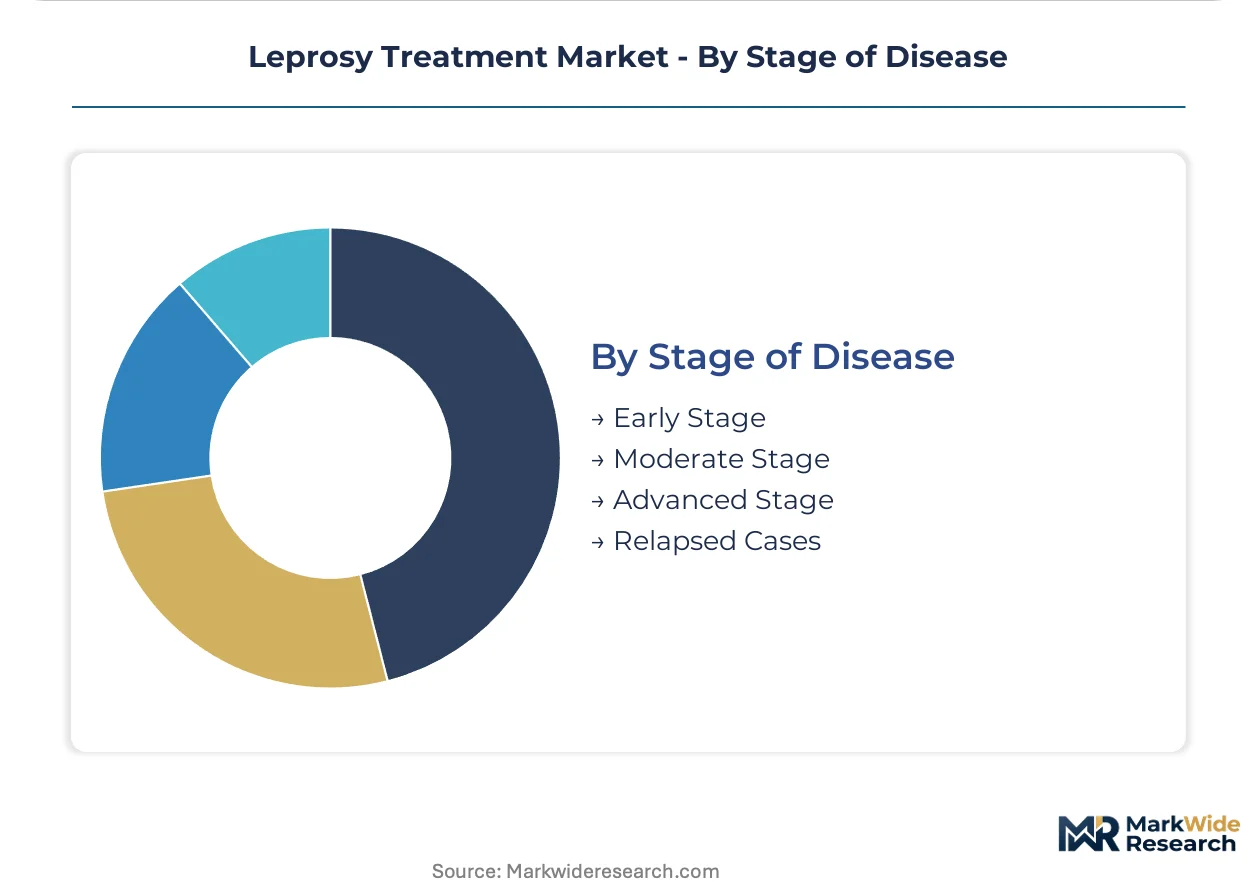
Stage of Disease:
Maturity gradients separate established paucibacillary protocols from emerging relapse management requirements.
- Early Stage:Six-month paucibacillary regimens achieve highest completion rates. Digital adherence technologies using basic mobile infrastructure address treatment gaps in rural India.
- Moderate Stage:Multibacillary protocols extend to twelve months with intensified monitoring.
- Advanced Stage:Disability-grade cases require integrated antibiotic-rehabilitation approaches.
- Relapsed Cases:Second-line regimens and resistance testing strain laboratory capacity.
Treatment initiations concentrate in Early Stage; the most pressing capacity expansion belongs to Relapsed Cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors pharmaceutical manufacturing for leprosy multidrug therapy, with Bihar and Uttar Pradesh absorbing the highest case detection volumes through India's National Leprosy Eradication Program infrastructure.
India
Bihar and Uttar Pradesh states concentrate over half of India's annual new case detections, driving centralized rate-contracting for antibiotic kits. CDSCO bioequivalence mandates filter generic dapsone suppliers eligible for government tenders, compressing margins while securing volume commitments. Mumbai-Pune industrial corridor hosts active pharmaceutical ingredient manufacturers supplying rifampicin and clofazimine to national programs.
Brazil
Pará and Minas Gerais states register the highest leprosy notification rates in the Amazon basin and southeastern regions. ANVISA oversees quality standards for imported clofazimine while municipal health secretariats deploy point-of-care LAMP diagnostics in peripheral clinics. São Paulo-based distributors manage replenishment logistics for multidrug therapy kits across remote Amazon corridors.
Indonesia
East Java and Central Java provinces bear the archipelago's heaviest disease burden, with district hospitals adopting polymerase chain reaction confirmation tools. The national health ministry coordinates with WHO for rifampicin donations while local manufacturers supply dapsone for domestic multidrug regimens. Community health workers supervise continuation-phase therapy across dispersed island communities.
Nigeria
Kano and Borno states in the northern region report persistent endemic transmission amid security challenges affecting health system access. The national pharmaceutical regulator enforces quality standards for donated rifampicin while state primary healthcare boards manage limited clofazimine stocks. Lagos-based procurement agents coordinate import logistics for multidrug therapy components.
Bangladesh
Rajshahi and Rangpur divisions along the Indian border maintain active case-finding through NGO partnerships. The Directorate General of Drug Administration monitors generic antibiotic quality for national elimination targets. Dhaka-based manufacturers produce dapsone for regional supply while relying on WHO donations for rifampicin coverage.
Leprosy Treatment Market Competitive Environment
Capital-heavy producers compete with asset-light procurement specialists across the leprosy treatment supply chain. The market structure concentrates around three archetypes: originator pharmaceutical companies donating essential antibiotics, generic manufacturers competing on cost-optimized production, and regional distributors managing last-mile logistics. Strategic moves center on securing WHO donation partnerships and qualifying for government tender eligibility through regulatory compliance investments.
Among originator-donor archetypes, Johnson & Johnson anchors global rifampicin supply through sustained WHO commitments, while Novartis occupies a parallel position in clofazimine manufacturing networks. Lupin Limited exemplifies the generic-cost tier, competing on dapsone production scale for public health procurement channels across South Asian endemic markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Lupin Limited |
| Novartis AG |
| Pfizer Inc. |
| Cipla Limited |
| Sanofi |
| Bayer AG |
| Cadila Pharmaceuticals |
| Glaxo Smithcline Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Donation-dependent supply architectures reshape pricing discipline across endemic markets, compressing commercial margins while securing treatment access. WHO-sourced rifampicin flows through national procurement channels at zero acquisition cost, forcing generic manufacturers to compete on operational efficiency rather than therapeutic differentiation.
Pricing Analysis
Value-based pricing anchors on treatment completion rates and disability prevention outcomes rather than unit dose economics. India's centralized rate-contracting for multidrug therapy kits stratifies procurement across bioequivalence-certified tiers, with CDSCO-compliant dapsone suppliers commanding modest premiums over uncertified alternatives. Pricing pressure intensifies as consolidated state tenders displace fragmented district purchasing, squeezing supplier margins in Bihar and Uttar Pradesh. National leprosy programs exhibit acute price sensitivity, while hospital systems managing complex reaction episodes demonstrate greater tolerance for immunomodulator premiums.
Supply Chain Analysis
Direct-to-government channels handle bulk antibiotic procurement for national elimination programs, bypassing wholesale distribution layers. Active pharmaceutical ingredient manufacturing concentrates in India, China, and selected European facilities, with Mumbai-Pune corridor suppliers dominating clofazimine and dapsone feedstock production. Raw material dependencies span rifamycin fermentation stocks, specialty chemical intermediates, and corticosteroid precursors. Single-source donation vulnerability for rifampicin creates structural risk if WHO commitments fluctuate or Johnson & Johnson manufacturing disruptions occur. Distribution runs through state medical supply corporations in endemic countries, with last-mile logistics managed by municipal health secretariats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leprosy treatment procurement operates as a cost-of-compliance market where India's CDSCO bioequivalence mandates erect regulatory moats favoring certified generic manufacturers over opportunistic entrants.
For Market Incumbents: Deepen backward integration into active pharmaceutical ingredient production to insulate margin structures from raw material volatility and qualify for concentrated government tenders. Secure long-term WHO donation partnership extensions before contract renewal windows compress competitive positioning. Expand manufacturing footprint beyond Maharashtra to hedge against regional regulatory disruption. For New Entrants and Emerging Players: Municipal health secretariats in Brazil's Amazon basin represent the most penetrable channel archetype, with automated replenishment systems creating white-space demand beyond incumbent logistics coverage. Target district hospital networks in Indonesian provinces where polymerase chain reaction adoption strains existing supplier technical service capacity. Position on diagnostic-therapeutic bundling rather than commodity antibiotic substitution. For Investors and Strategic Acquirers: Shifts in WHO drug donation commitment language are the leading indicator that supply security premiums will reprice across endemic markets. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Acquisition targets should display CDSCO or ANVISA certification portfolios with established national tender track records. Monitor clofazimine API manufacturer consolidation in India as a supply constraint signal.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Donation Partnership Extension | Secures rifampicin supply anchorage for national elimination program eligibility. |
| CDSCO Bioequivalence Certification | Unlocks centralized tender access in India's highest-burden endemic states. |
| Point-of-Care Diagnostic Integration | Brazilian municipal secretariats value LAMP-platform bundling with therapy supply. |
| Homecare Logistics Network Buildout | Indonesia's archipelago geography rewards community health worker channel control. |
| Immunomodulator Portfolio Expansion | Thalidomide and corticosteroid combinations address reaction management premium tiers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving national leprosy program directors, pharmaceutical regulatory affairs specialists, hospital procurement managers, and WHO supply chain coordinators. Bottom-up modeling of treatment initiation volumes by disease stage and region triangulated against top-down expenditure flows reported in national health accounts. FDA quality standards documentation, CDSCO bioequivalence determinations, and ANVISA import registrations provided product-level validation.
Segmentation granularity extended to product type, end user setting, delivery mode, and disease stage across the projection horizon, with regional clusters modeled at country-level resolution for India, Brazil, Indonesia, Nigeria, and Bangladesh. CAGRs derived from epidemiological trend extrapolation, procurement volume trajectories, and policy commitment durability assessments. Forecast inputs incorporated WHO elimination target revisions, domestic manufacturing incentive schemes, and diagnostic technology adoption curves.
Several conditions sit outside the modeled scope, including novel vaccine commercialization timelines, antimicrobial resistance surveillance disruptions, and security-conflict impacts on health system access in Borno and Kano states. Forecasts reflect documented assumptions regarding sustained donor commitment levels and regulatory harmonization progress. Periodic stress-testing of base assumptions is recommended against leprosy reaction biomarker breakthroughs and clofazimine API supply shocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market