
 North America Digital X-Ray Market | 2026-2036
North America Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital X-Ray Market Analytics
Outpatient clinic demand is shifting toward compact, mobile-capable digital x-ray platforms that enable point-of-care diagnostics without dedicated radiology suites. GE Healthcare leverages its installed base of imaging equipment to sustain recurring revenue through detector upgrades and software subscriptions. Siemens Healthineers anchors its North American position with R&D intensity focused on photon-counting detector development. Fujifilm Medical Systems differentiates through specialized veterinary and orthopedic imaging portfolios that occupy niche clinical segments.
North America Digital X-Ray refers to electronic image capture systems that replace analog film with solid-state detectors, typically employing cesium iodide or gadolinium oxysulfide scintillators coupled to thin-film transistor arrays that convert x-ray photons into digital signals at spatial resolutions exceeding 2.5 line pairs per millimeter. These systems serve primary diagnostic purposes across human and veterinary medicine, enabling immediate image review, DICOM-compliant storage, and integration with hospital information systems. Portable systems lead unit shipments due to emergency department and bedside imaging requirements, while flat panel detectors represent the fastest-growing product category as facilities retrofit existing analog rooms. Direct radiography technology commands premium positioning over computed radiography alternatives, though hybrid systems retain relevance in budget-constrained imaging centers transitioning incrementally.
FDA 510(k) premarket notification requirements govern device clearance, while the EPA regulates x-ray tube emissions under federal radiation protection standards; state-level health departments in California, Texas, and New York impose additional facility certification and operator training mandates that shape procurement timelines. The FDA's evolving guidance on artificial intelligence and machine learning in medical imaging is creating new compliance pathways for algorithm-enabled diagnostic tools. Stakeholders must monitor reimbursement rate adjustments from CMS and private payers, as these directly influence hospital capital expenditure cycles and replacement demand for aging radiography infrastructure.
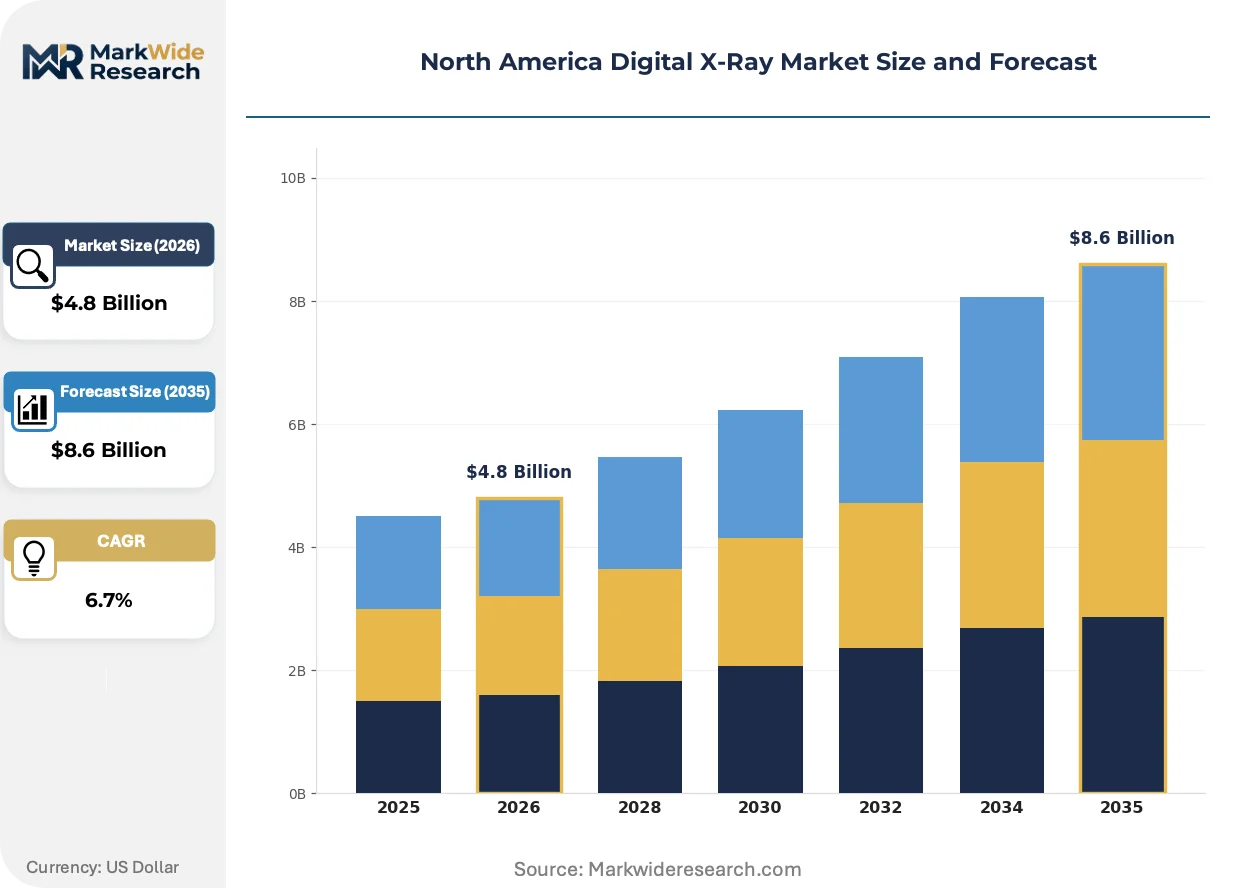
Market Dynamics
Hospital networks across Texas and California are consolidating radiography procurement around direct radiography systems, compressing replacement cycles and forcing equipment vendors to bundle software subscriptions with hardware sales.
Growth Catalysts
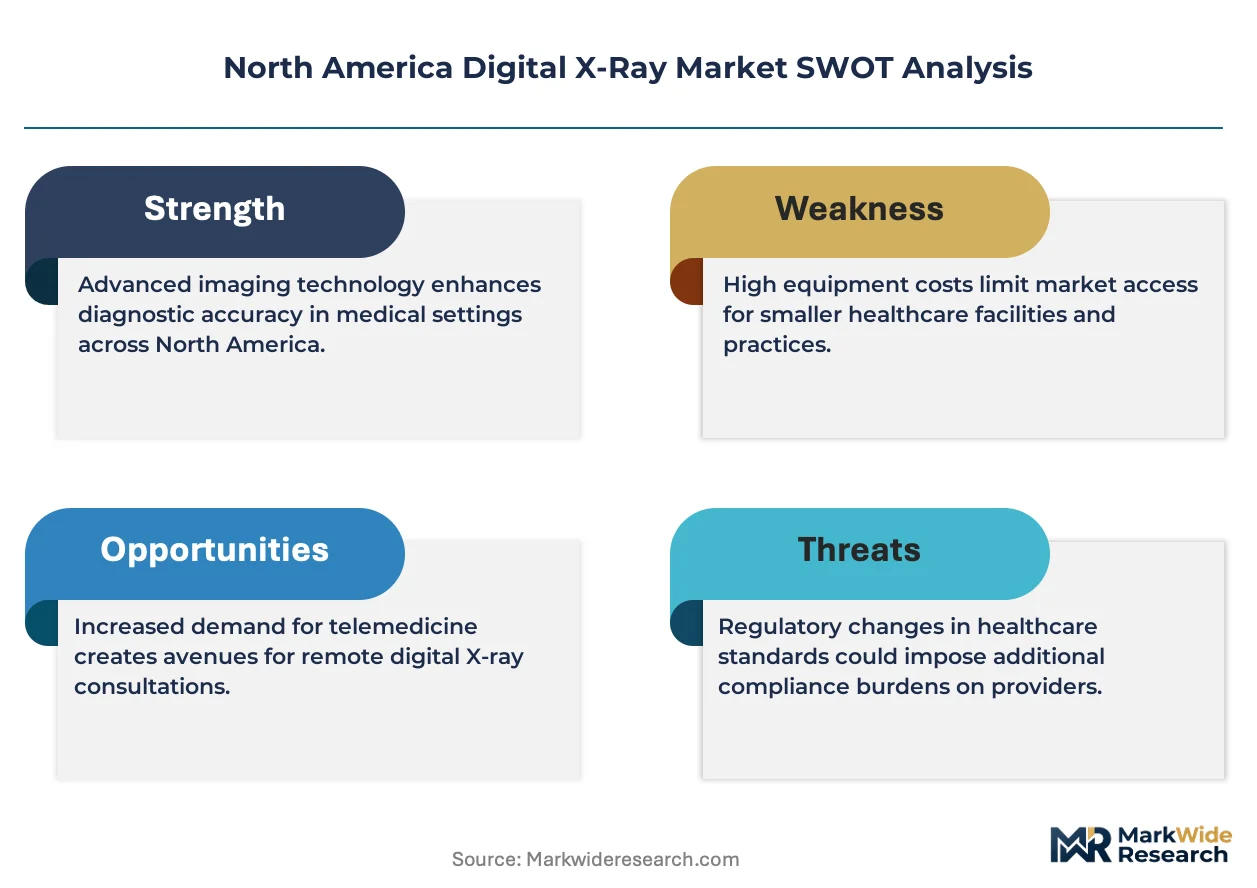
- CMS reimbursement alignment:Medicare payment structures now favor digital imaging workflows over analog alternatives, accelerating capital allocation toward detector upgrades in outpatient settings.
- Photon-counting detector maturation:Solid-state sensor technology is reducing radiation dose requirements while improving tissue contrast resolution in cardiac and thoracic applications.
- Bedside imaging demand:Emergency departments in the United States are prioritizing portable digital x-ray units to reduce patient transport risks and accelerate triage decisions.
Market Restraints
- Cesium iodide supply concentration:Scintillator material production clusters in East Asian manufacturing hubs, exposing detector assembly lines to single-source vulnerability.
- FDA 510(k) pathway friction:Premarket notification timelines for AI-enabled diagnostic software are extending as the agency develops algorithm validation frameworks.
- Computed radiography persistence:Budget-constrained imaging centers in rural Canada continue deploying cassette-based systems, delaying full digital conversion.
Strategic Opportunities
- Veterinary imaging expansion:Specialty animal hospitals in Ontario and Quebec are adopting dedicated orthopedic digital radiography suites for equine and companion animal diagnostics.
- AI-ML diagnostic convergence:Machine learning algorithms paired with digital detectors are automating fracture detection and pneumothorax flagging in emergency workflows.
- Mobile imaging services:Independent service operators are deploying truck-mounted digital x-ray units to serve long-term care facilities lacking on-site radiology infrastructure.
Industry Challenges
- Qualified technologist scarcity:Radiologic technologist training programs in the United States are not producing sufficient graduates to staff expanded outpatient imaging networks.
- Legacy PACS integration complexity:New digital detector installations must interface with decade-old picture archiving systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital X-Ray Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Retrofit Solutions, Flat Panel Detectors End User: Hospitals, Outpatient Clinics, Imaging Centers, Research Labs Technology: Computed Radiography, Direct Radiography, Hybrid Systems, Analog Systems Application: Dental Imaging, Orthopedic Imaging, Cardiovascular Imaging, Veterinary Diagnostics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Fujifilm Medical Systems, Canon Medical Systems Corporation, Koninklijke Philips N.V., Carestream Health, Shimadzu Corporation, Hologic Corporation, Varex Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital X-Ray Market Evolving Landscape
Artificial intelligence integration is compressing diagnostic turnaround times while regulatory frameworks for algorithm-enabled devices mature, reshaping how hospitals evaluate equipment procurement.
Photon-counting CT detectors adapted for general radiography are automating exposure optimization across variable patient body types. Academic medical centers in Massachusetts and Pennsylvania are piloting these systems for pediatric and bariatric imaging protocols. The technology is automating dose reduction while maintaining diagnostic image quality, forcing incumbent flat-panel manufacturers to accelerate R&D timelines.
The FDA's evolving guidance on machine learning in medical imaging is creating compliance uncertainty for algorithm developers. Device manufacturers must now submit clinical validation data demonstrating diagnostic equivalence to human readers. Software-enabled digital x-ray systems face extended review periods, particularly for chest and musculoskeletal applications where AI flagging is most advanced.
Hospital purchasing cooperatives are consolidating equipment procurement decisions across multi-facility networks. Group purchasing organizations in Texas and Florida are negotiating enterprise-wide digital radiography contracts that bundle detectors, software licenses, and maintenance services. This concentration is squeezing independent imaging centers that lack volume leverage, pushing them toward refurbished equipment markets or third-party service agreements.
North America Digital X-Ray Market Segmentation
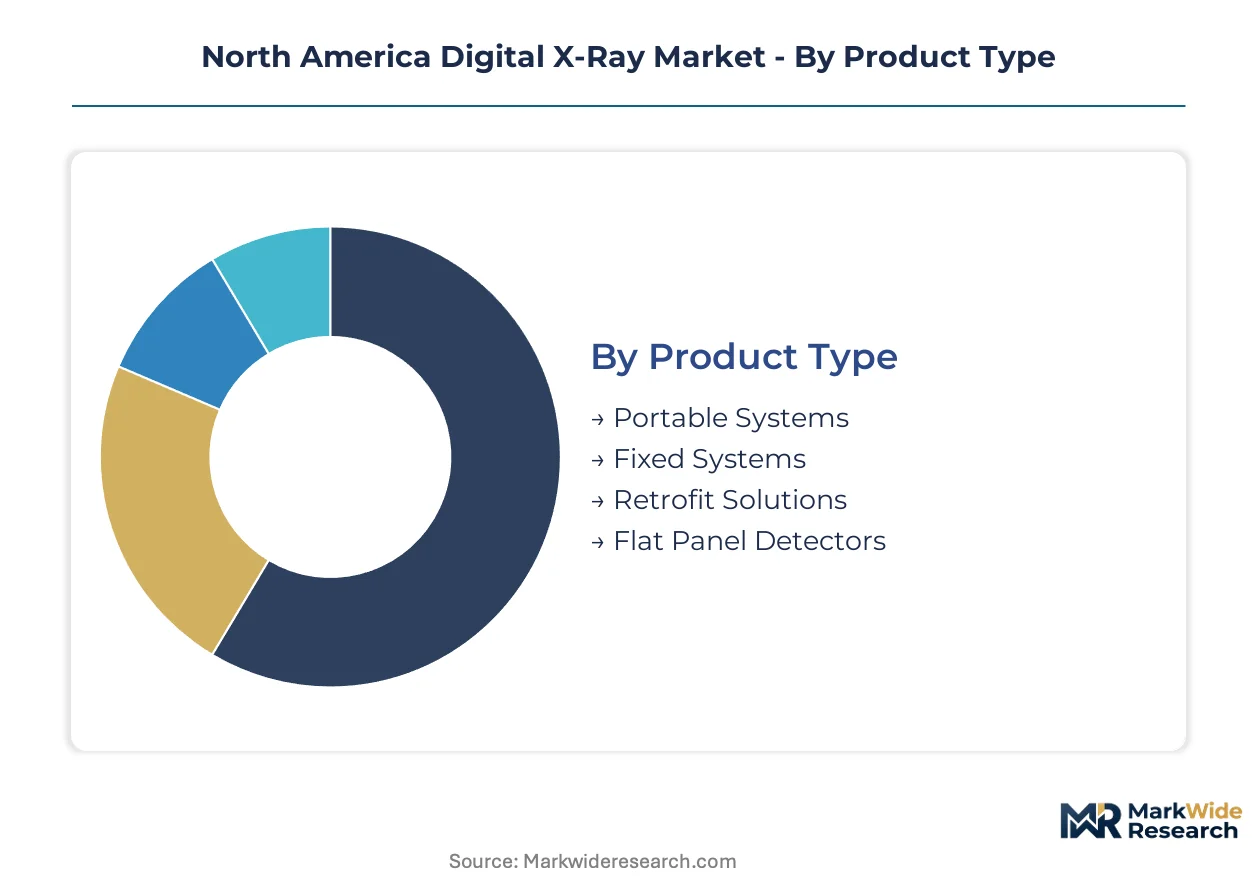
Equipment replacement cycles and detector upgrade pathways fragment procurement decisions across North American healthcare networks. Facility budget tiers and clinical throughput requirements create distinct purchasing segments that vendors must address with differentiated hardware and service bundles.
Product Type:
Upgrade urgency varies sharply by installation footprint, with emergency departments demanding mobility while imaging centers prioritize detector resolution specifications.
- Portable Systems:Battery-powered mobile units with wireless detector connectivity enable bedside imaging in ICU and emergency settings. Texas hospital networks are standardizing on portable fleets to reduce patient transport risks and accelerate triage throughput.
- Flat Panel Detectors:Thin-film transistor arrays with cesium iodide scintillation layers convert x-ray photons to digital signals at diagnostic resolutions. California outpatient clinics are retrofitting existing analog rooms with these detectors to avoid full room construction costs while achieving direct radiography workflow benefits.
- Fixed Systems:Ceiling-suspended or floor-mounted tube stands with integrated detector tables serve high-volume radiology departments.
- Retrofit Solutions:Detector upgrade kits for legacy analog rooms preserve existing mechanical infrastructure while enabling digital capture.
Portable systems sit at the top of the volume ranking, with flat panel detectors climbing the fastest.
End User:
Capital allocation authority concentrates differently across customer types, with hospital networks wielding enterprise purchasing power against independent clinic budget constraints.
- Hospitals:Multi-department imaging departments with dedicated radiology staff and 24/7 operational requirements. Texas and California hospital systems are consolidating procurement through group purchasing organizations, compressing vendor margins while demanding bundled software subscriptions.
- Outpatient Clinics:Limited-space facilities requiring compact systems without dedicated radiology suites. United States urgent care chains are deploying point-of-care digital x-ray to reduce referral leakage and capture diagnostic revenue in-house.
- Imaging Centers:Specialized facilities competing on throughput and turnaround time metrics.
- Research Labs:Academic and pharmaceutical imaging units with protocol customization requirements.
Hospitals command the largest equipment budgets, while outpatient clinics are expanding most quickly.
Technology:
Technology migration paths reflect capital availability and workflow disruption tolerance, with direct radiography commanding premium positioning against transitional hybrid alternatives.
- Direct Radiography:Solid-state detectors capturing x-ray photons without intermediate conversion steps, enabling immediate image display and lowest radiation dose profiles. United States hospital networks are prioritizing DR for new construction and full replacement projects to maximize throughput and minimize retake rates.
- Computed Radiography:Cassette-based phosphor plate systems requiring mechanical scanning and erasure cycles. Rural Canadian imaging centers continue deploying CR technology where budget constraints delay full digital conversion.
- Hybrid Systems:Configurations supporting both cassette and direct detector workflows during transition periods.
- Analog Systems:Film-based radiography with chemical processing, now limited to obsolete infrastructure and extreme budget constraints.
Direct radiography leads replacement demand, with hybrid systems retaining relevance in budget-constrained transitions.
Application:
Clinical specialization requirements drive detector specification differentiation, with orthopedic and dental applications demanding distinct resolution and software capabilities.
- Orthopedic Imaging:High-resolution protocols for fracture visualization and joint alignment assessment, requiring specialized detector positioning and weight-bearing capabilities. United States sports medicine clinics are investing in dedicated orthopedic suites to capture trauma and post-operative monitoring volume.
- Veterinary Diagnostics:Adapted systems for equine and companion animal imaging with modified table configurations and exposure parameters. Ontario and Quebec specialty animal hospitals are adopting dedicated veterinary digital radiography for orthopedic and dental applications in high-value equine and small animal cases.
- Dental Imaging:Intraoral and panoramic systems with specialized sensor formats and reduced radiation protocols.
- Cardiovascular Imaging:High-frame-rate capabilities for angiographic and interventional procedures.
Orthopedic imaging dominates procedure volume, with veterinary diagnostics gaining share fastest in specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in digital x-ray manufacturing concentrate detector assembly in jurisdictions with streamlined medical device pathways, while procurement decisions cluster where CMS reimbursement alignment and state-level facility certification create demand pull. Production cost differentials across North American borders are reshaping vendor facility placement and service network configuration.
United States
Texas and California hospital networks are consolidating radiography procurement through group purchasing organizations, compressing replacement cycles for direct radiography systems. FDA 510(k) premarket notification requirements govern device clearance, while state health departments in California, Texas, and New York impose additional facility certification mandates. Massachusetts academic medical centers are piloting photon-counting detector systems for pediatric and bariatric imaging protocols.
Canada
Rural imaging centers in Prairie Provinces continue deploying computed radiography cassette-based systems where budget constraints delay full digital conversion. Health Canada regulates medical device licensing through the Medical Devices Directorate, with provincial health authorities in Ontario and Quebec controlling capital equipment allocation. Ontario specialty animal hospitals are adopting dedicated veterinary digital radiography suites for equine orthopedic diagnostics.
Mexico
Cross-border service operators are deploying mobile digital x-ray units to serve maquiladora industrial corridors and northern border cities lacking fixed radiology infrastructure. COFEPRIS regulates medical device registration, with accelerated pathways for FDA-cleared equipment enabling faster market entry. Nuevo León manufacturing clusters are attracting detector component assembly operations serving North American aftermarket demand.
North America Digital X-Ray Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system vendors commanding premium positioning in hospital networks while component suppliers capture recurring revenue from detector upgrades and replacement cycles. Market structure tilts toward consolidated enterprise procurement, as group purchasing organizations in Texas and Florida negotiate bundled hardware-software-service contracts that squeeze independent imaging center margins. Three archetypes dominate: diversified imaging conglomerates with installed base leverage, specialized detector technology developers, and independent service operators deploying mobile fleets. Competitive intensity is concentrating around M&A activity targeting AI-enabled diagnostic software capabilities and strategic partnerships bundling equipment with radiology workflow platforms.
Within the diversified imaging tier, GE Healthcare and Siemens Healthineers exemplify archetypes leveraging global installed bases to sustain recurring revenue through detector upgrades and software subscriptions. Fujifilm Medical Systems occupies a specialist position, differentiated through niche clinical segment focus. These three represent the competitive spectrum from full-platform conglomerates to targeted portfolio specialists, with each archetype responding differently to procurement consolidation pressures and AI-ML diagnostic convergence requirements.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Medical Systems |
| Canon Medical Systems Corporation |
| Koninklijke Philips N.V. |
| Carestream Health |
| Shimadzu Corporation |
| Hologic Corporation |
| Varex Imaging |
| Others |
Value Network & Pricing Analysis
Cesium iodide scintillator crystals from East Asian manufacturing hubs feed through detector assembly lines to pricing tiers downstream, with procurement concentration in Texas and California hospital networks compressing channel margins while single-source material dependencies elevate supply risk premiums.
Pricing Analysis
Distributor markups on flat-panel detectors vary by certification tier, with FDA 510(k)-cleared units commanding premium positioning against Health Canada-licensed equivalents. Pricing stratifies across premium DR systems, standard hybrid configurations, and economy CR retrofits based on detector resolution and software bundling. Cost compression in the outpatient clinic tier is intensifying because GPO-negotiated enterprise contracts squeeze independent imaging center margins. Rural Canadian facilities exhibit highest price sensitivity, while Massachusetts academic medical centers prioritize photon-counting performance over acquisition cost.
Supply Chain Analysis
Freight costs on cesium iodide crystals and thin-film transistor arrays from Japan, South Korea, and Taiwan elevate landed costs for North American detector assembly operations. Raw material dependencies center on rare-earth phosphors, semiconductor-grade silicon substrates, and precision analog-to-digital converters. Single-source vulnerability in scintillator material production exposes assembly lines to tariff exposure and logistics chokepoints. Distribution runs through OEM direct sales to hospital networks, with third-party service operators capturing mobile unit deployment in long-term care and veterinary segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) review timelines in the United States run 40-60% longer than Health Canada Medical Devices Directorate pathways, creating regulatory-arbitrage opportunities for manufacturers prioritizing Canadian market entry before southbound expansion.
For Market Incumbents: Hedge against photon-counting detector displacement by accelerating R&D partnerships with Massachusetts and Pennsylvania academic medical centers piloting next-generation sensor protocols. Lock in multi-year detector upgrade subscriptions with Texas and California GPOs before refurbished equipment channels capture budget-constrained independent imaging centers. Channel control through captive service networks represents the critical defensive lever. For New Entrants and Emerging Players: Direct-to-veterinary-clinic digital sales platforms bypass entrenched hospital-GPO procurement blockades, opening immediate revenue paths in Ontario and Quebec equine orthopedic segments. Target mobile imaging services for long-term care facilities in underserved Prairie Provinces and northern Mexico border cities where fixed radiology infrastructure gaps persist. White-space capture depends on truck-mounted unit leasing models with per-scan revenue sharing rather than capital equipment sales. For Investors and Strategic Acquirers: Roll-up economics work for independent service operators with mobile fleets because reimbursement rate compression is forcing hospital networks to outsource non-core imaging capacity to variable-cost providers. Five-to-ten-year viability hinges on AI-enabled diagnostic software capabilities that automate fracture detection and pneumothorax flagging. Watch FDA guidance finalization on machine learning validation frameworks as the inflection signal for algorithm-enabled device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shorter clearance timelines capture CMS reimbursement alignment windows before competitor products reach market. |
| Photon-Counting Detector Partnership | Massachusetts academic medical center collaborations validate pediatric dose-reduction protocols for premium positioning. |
| GPO Contract Consolidation | Texas and Florida enterprise-wide bundles compress competitor access to high-volume replacement cycles. |
| AI-ML Diagnostic Software Development | FDA algorithm validation frameworks favor early movers with chest and musculoskeletal flagging capabilities. |
| Veterinary Imaging Portfolio Expansion | Ontario and Quebec specialty animal hospital adoption creates defensible niche against human-medicine price wars. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and veterinary clinic operators grounded qualitative findings, cross-referenced against FDA 510(k) premarket notification databases, Health Canada Medical Devices Directorate licensing records, CMS Medicare reimbursement schedules, and hospital procurement databases. Secondary validation drew from SEC filings of listed imaging equipment manufacturers and trade customs data on detector component imports. Bottom-up unit shipment estimates and top-down revenue triangulation converged on market sizing across the analysis window.
Top-down macroeconomic modeling anchored demand projections to hospital capital expenditure cycles and outpatient clinic expansion rates, while bottom-up segmentation tracked portable systems, flat-panel detectors, fixed installations, and retrofit kits by technology migration path. Direct radiography, computed radiography, hybrid, and analog technology tiers were modeled against end-user budget constraints and workflow disruption tolerance. CAGRs derived from logistic adoption curves fitted to historical replacement cycle data and reimbursement rate trajectory assumptions.
Regulatory timeline delays, cesium iodide supply disruptions, and radiologic technologist training program output shortfalls are the dominant revision risks to installed base and upgrade forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Digital Mammography Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Digital Pathology Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
United States Mammography Market
Medical Imaging
South America Digital X-Ray Devices Market