
 Starch-Based Plastics Market | 2026-2036
Starch-Based Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Based Plastics Market Outlook
Food packaging is broadening its share of starch-based plastics consumption as major retailers phase out conventional petroleum-derived films. Novamont S.p.A. anchors European production of certified compostable starch compounds for flexible packaging applications. Corbion N.V. leverages its fermentation expertise to supply high-purity polylactic acid precursors blended with thermoplastic starch. Kuraray Co. Ltd dominates Asian supply of barrier-enhanced starch films for moisture-sensitive food products.
Starch-based plastics comprise thermoplastic starch and starch blends formulated with plasticizers to achieve melt processability in conventional extrusion and injection molding equipment. These materials typically contain 30-70% starch content by weight, with glycerol or sorbitol serving as primary plasticizers to reduce brittleness and lower processing temperatures. Their primary industrial purpose centers on replacing polyethylene and polypropylene in single-use applications where biodegradation or compostability delivers regulatory compliance and waste reduction. Thermoplastic starch currently leads volume consumption due to its cost position and compatibility with existing blown film lines. Starch blends represent the fastest-expanding category as compounders optimize mechanical properties through polyhydroxyalkanoate and polylactic acid co-formulations. Molded products command premium positioning where dimensional stability and heat resistance justify formulation complexity.
The EU Green Deal and REACH compliance protocols are tightening material certification requirements across European supply chains, compelling converters to source only EN 13432-certified compounds. FDA food contact regulations in the United States govern migration limits for plasticizers and residual processing aids in starch-based food packaging. China's GB standards and dual carbon goals are accelerating domestic substitution mandates for petroleum-based disposables in major municipal markets. Stakeholders must monitor evolving compostability certification reciprocity between jurisdictions to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
Industrial composting infrastructure deployment is concentrating converter capacity around certified facilities, creating geographic lock-in effects that favor compounders with established logistics corridors to high-volume offtake points.
Growth Catalysts
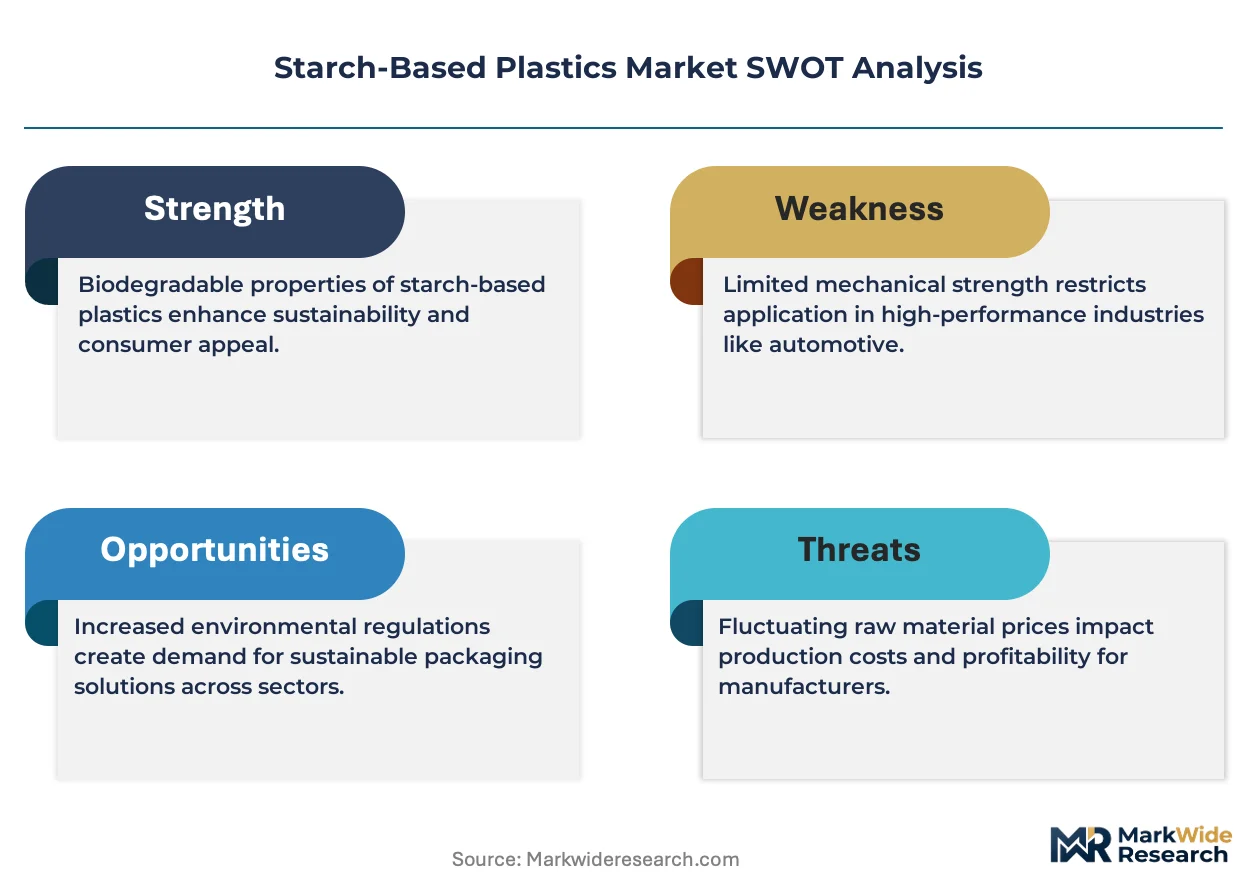
- EU Green Deal packaging mandates:EN 13432 certification requirements are pulling flexible film converters toward certified starch compounds to maintain supermarket shelf access across German and French retail networks.
- Foodservice disposables:Quick-service restaurant chains are specifying thermoplastic starch cutlery and clamshells to meet corporate plastic reduction commitments without sacrificing compostability claims.
- Glycerol plasticizer availability:Biodiesel co-product streams are stabilizing input costs for TPS formulations, improving cost parity against conventional polyethylene in blown film applications.
Market Restraints
- Moisture sensitivity:Unmodified thermoplastic starch absorbs ambient humidity, degrading mechanical properties during storage and limiting applications to short-shelf-life packaging.
- Composting infrastructure gaps:Industrial composting facilities remain concentrated in Germany, Italy, and the Netherlands, leaving converters in Eastern Europe without viable end-of-life pathways for certified products.
- Polyethylene price volatility:Naphtha-derived conventional films periodically undercut starch-based alternatives on unit economics during crude oil price troughs.
Strategic Opportunities
- Agricultural mulch films:Soil-biodegradable starch formulations are displacing polyethylene in specialty crop applications where retrieval costs exceed material premiums.
- India PLI scheme for bioplastics:Production-linked incentives are attracting compounders to establish thermoplastic starch capacity serving domestic food packaging and agricultural film demand.
- Barrier coating convergence:Atomic layer deposition of aluminum oxide onto starch substrates is creating compostable high-barrier structures for oxygen-sensitive foods.
Industry Challenges
- Compostability certification timelines:EN 13432 and ASTM D6400 testing protocols require 180-day industrial composting validation, delaying product launches and freezing working capital in pre-certified inventory.
- Extrusion equipment retrofit costs:Conventional polyethylene lines require screw and die modifications to process thermoplastic starch without thermal degradation, demanding capital commitments from mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Based Plastics Market |
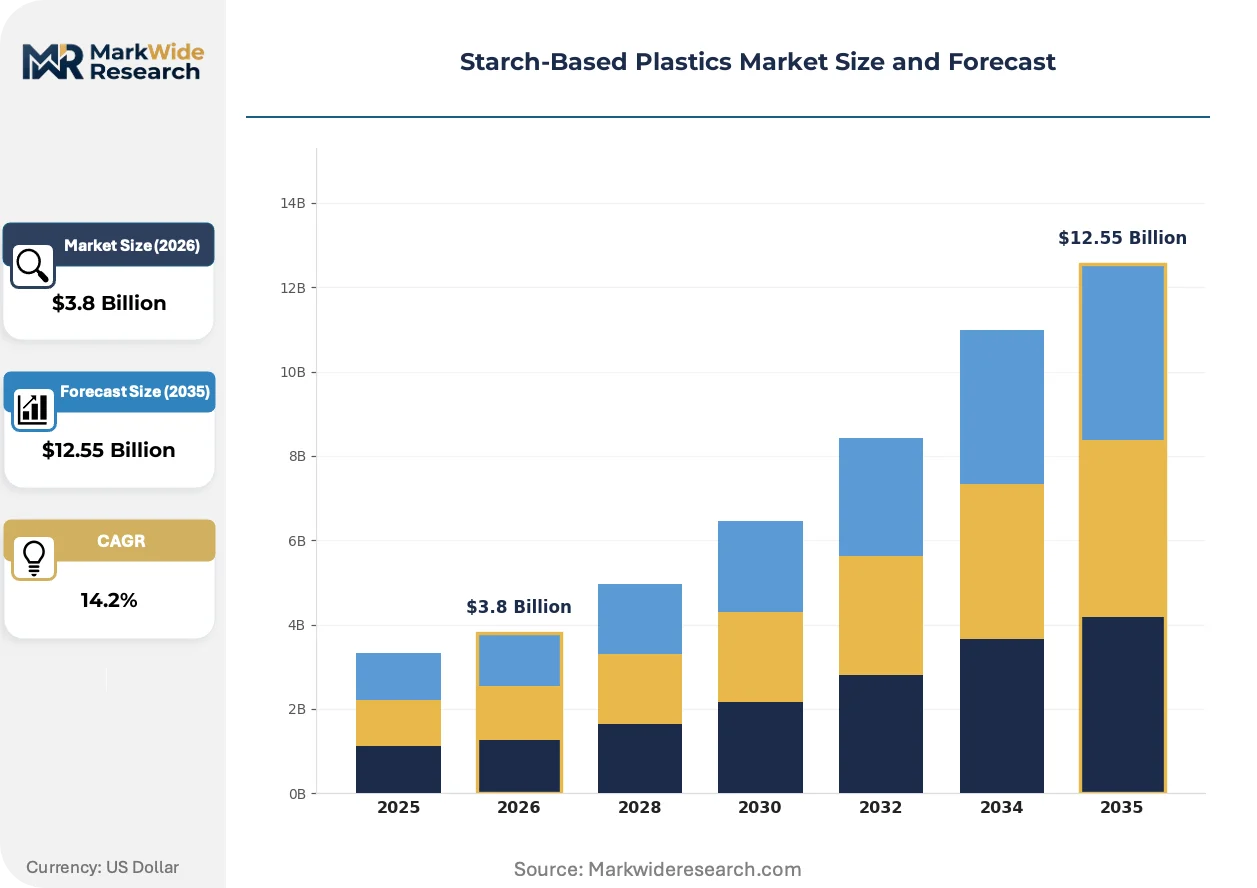
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Starch, Starch Blends, Biodegradable Compounds, Expanded Starch End User: Packaging, Agriculture, Consumer Goods, Automotive Application: Film, Coating, Molded Products, Fiber Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Kuraray Co. Ltd, Rodenburg Biopolymers, Biome Bioplastics Limited, Wittenburg Group, Nihon Cornstarch Corporation, Toray Industries Inc, Novamont S.p.A, BIOTEC GmbH & Co, Corbion N.V, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Based Plastics Market Strategic Shifts
Active modification of starch crystallinity and plasticizer systems is expanding the process window for these materials, enabling deployment on standard thermoplastic equipment without dedicated capital investment.
Thermoplastic starch nanocomposites incorporating cellulose nanocrystals are electrifying mechanical property profiles in injection-molded applications. Houseware brands serving Nordic retail channels are adopting these compounds for rigid containers and cutlery. The technology is electrifying substitution economics against polypropylene in durable disposables by closing the heat-resistance gap that previously limited starch to cold-fill applications.
REACH authorization requirements for persistent organic pollutants are tightening residual solvent limits in starch-plasticizer compounding operations. Compounders serving EU food contact applications are investing in supercritical CO2 extraction systems to eliminate toluene and xylene traces. Small-batch specialty producers without capital access are exiting the certified compound segment, consolidating formulation expertise among integrated starch processors with in-house purification assets.
Retail procurement teams are consolidating supplier panels around vertically integrated compounders capable of certifying full chain-of-custody documentation. German supermarket private-label managers now require batch-level compostability certificates uploaded to blockchain-verified portals. This behavior concentrates contract awards among three to four compounders with dedicated regulatory affairs functions, marginalizing trading houses and distributor intermediaries in high-volume flexible packaging categories.
Starch-Based Plastics Market Segmentation
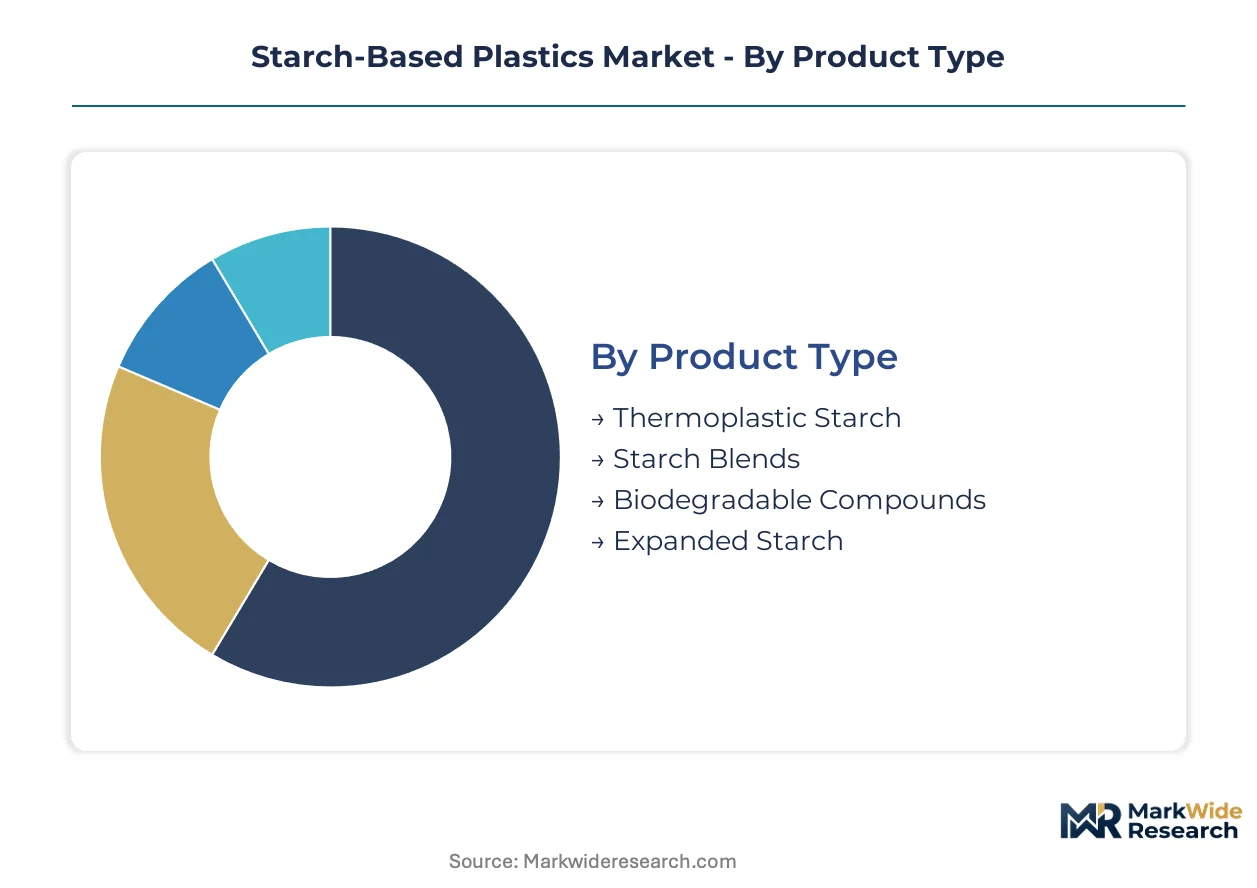
Starch-based plastics demand fragments across formulation chemistries, end-use specifications, and supply chain configurations. Each segmentation axis reveals distinct margin structures and certification requirements that compounders must navigate to secure shelf placement in regulated retail environments.
Product Type:
Formulation complexity determines processing equipment compatibility and compostability certification pathways.
- Thermoplastic Starch:Native starch plasticized with glycerol or sorbitol achieves melt processability in conventional blown film extruders. German flexible packaging converters favor this grade for cost-sensitive supermarket produce bags where EN 13432 compliance suffices.
- Starch Blends:Co-formulations with polylactic acid or polyhydroxyalkanoates expand mechanical property envelopes for injection-molded cutlery. Quick-service restaurant procurement teams specify these compounds to meet corporate plastic reduction commitments without sacrificing heat resistance.
- Biodegradable Compounds:Pre-compounded masterbatches incorporate pro-degradant additives for soil-biodegradable agricultural films. Italian specialty crop growers deploy these in tomato and strawberry cultivation where retrieval costs exceed material premiums.
- Expanded Starch:Foamed structures replace expanded polystyrene in protective packaging applications. Electronics fulfillment centers in the Netherlands utilize molded trays for device shipping.
Mature deployment sits with thermoplastic starch in blown film lines. Newer deployment is concentrated in starch blends gaining share in rigid foodservice disposables.
End User:
Customer procurement sophistication varies sharply across sectors, with certification documentation requirements scaling from batch-level to chain-of-custody verification.
- Packaging:Flexible film converters serving German and French retail networks dominate volume offtake. Private-label managers now mandate blockchain-verified compostability certificates uploaded to supplier portals.
- Agriculture:Soil-biodegradable mulch films displace polyethylene in specialty crop applications. Tomato and strawberry growers in Italy and Spain calculate total cost of ownership including retrieval labor.
- Consumer Goods:Houseware brands serving Nordic retail channels adopt thermoplastic starch nanocomposites for rigid containers. Cellulose nanocrystal reinforcement closes heat-resistance gaps against polypropylene.
- Automotive:Interior trim applications specify starch-based foams for noise-dampening components. OEM sustainability scorecards drive material substitution in door panels and seat cushioning.
Volume concentrates in packaging procurement teams consolidating supplier panels. Margin expansion is steepest in agriculture where retrieval economics justify formulation premiums.
Application:
Processing technology constraints segment the market by equipment retrofit requirements and thermal stability demands.
- Film:Blown and cast film extrusion consumes the majority of thermoplastic starch tonnage. German converters leverage existing polyethylene lines with screw and die modifications.
- Coating:Barrier-enhanced starch substrates receive atomic layer deposition of aluminum oxide for oxygen-sensitive foods. High-barrier structures target premium snack packaging applications.
- Molded Products:Injection molding of cutlery and clamshells requires starch-PLA blends for dimensional stability. Quick-service chains specify these for compostability claims in captive waste streams.
- Fiber:Melt-spun starch fibers enter nonwoven applications for disposable wipes and agricultural textiles. Processing windows remain narrow due to moisture sensitivity during extrusion.
Equipment utilization is highest in film extrusion. Capital investment intensity is greatest in coating lines integrating vacuum deposition chambers.
Distribution Channel:
Supply chain configuration reflects customer scale and certification documentation requirements.
- Direct Sales:Vertically integrated compounders serve high-volume converters with dedicated technical service. German supermarket private-label supply chains require batch-level traceability.
- Distributors:Regional stocking points serve mid-tier converters lacking capital for direct procurement relationships. Inventory risk concentrates in pre-certified compound awaiting EN 13432 validation.
- Online Retail:Specialty compounders reach small-batch processors through digital channels. Minimum order quantities limit adoption to formulation development and pilot-scale trials.
- Wholesalers:Trading houses aggregate spot demand from converters in Eastern European markets lacking industrial composting infrastructure. Marginalized by blockchain-verified certificate requirements in premium segments.
Contract concentration favors direct sales to certified compounders. Channel expansion is occurring in distributor networks serving secondary geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial composting infrastructure and regulatory mandates are concentrating starch-based plastics demand in specific tax-incentive zones and special-economic-areas where certified facilities anchor converter supply chains.
Germany
Industrial composting facilities in Bavaria and Baden-Württemberg process high volumes of certified starch packaging from converters serving Aldi and Lidl private-label networks. The EU Green Deal packaging mandates under EN 13432 certification pull flexible film producers toward thermoplastic starch formulations. The Düsseldorf-Cologne corridor hosts compounders supplying blown film lines for Central European retail distribution.
Italy
Specialty crop growers in Emilia-Romagna and Sicily deploy soil-biodegradable starch mulch films for tomato and strawberry cultivation where retrieval costs exceed material premiums. Novamont S.p.A. anchors domestic production of certified compostable compounds from its Novara facility. The Po Valley agricultural belt drives formulation demand for biodegradable agricultural applications.
United States
Quick-service restaurant chains specify thermoplastic starch cutlery and clamshells to meet corporate plastic reduction commitments across California and New York municipal markets. FDA food contact regulations govern migration limits for plasticizers in starch-based food packaging. The Midwest corn belt supplies feedstock to compounders serving foodservice disposables procurement teams.
China
GB standards and dual carbon goals accelerate domestic substitution mandates for petroleum-based disposables in Shanghai and Beijing municipal markets. Kuraray Co. Ltd dominates Asian supply of barrier-enhanced starch films for moisture-sensitive food products. The Yangtze River Delta concentrates blown film converter capacity serving domestic snack packaging demand.
India
Production-linked incentives under the PLI scheme for bioplastics attract compounders to establish thermoplastic starch capacity serving domestic food packaging demand in Maharashtra and Gujarat. The FSSAI regulates food contact applications while state-level plastic bans in Delhi and Karnataka drive substitution. The Pune-Ahmedabad industrial corridor hosts emerging converter operations for agricultural films.
Starch-Based Plastics Market Competitive Environment
Top-tier vendors anchor certified compound supply, while mid-scale blenders and regional distributors occupy lower tiers with pre-certified inventory awaiting validation. The market structure concentrates around vertically integrated starch processors with in-house purification assets and dedicated regulatory affairs functions. Three archetypes dominate: fermentation-technology specialists leveraging biochemical expertise, agricultural-commodity processors with captive starch supply, and polymer-compounding houses with existing thermoplastic equipment. Competitive moves center on backward integration into glycerol plasticizer supply and geographic expansion toward industrial composting clusters.
Within the fermentation-technology tier, Corbion N.V. and Novamont S.p.A. exemplify integrated compounders capable of certifying full chain-of-custody documentation for EU retail procurement portals. Kuraray Co. Ltd occupies a position among Asian barrier-film specialists serving moisture-sensitive food applications. These named entities represent the archetype concentration where regulatory compliance capabilities and composting infrastructure access determine contract awards.
| Leading Market Players |
|---|
| Kuraray Co. Ltd |
| Rodenburg Biopolymers |
| Biome Bioplastics Limited |
| Wittenburg Group |
| Nihon Cornstarch Corporation |
| Toray Industries Inc |
| Novamont S.p.A |
| BIOTEC GmbH & Co |
| Corbion N.V |
| Others |
Value Chain & Pricing Dynamics
Compounders with EN 13432 certification expertise cluster in Germany's Düsseldorf-Cologne corridor, where regulatory affairs specialists command wage premiums that propagate through three-tier pricing structures separating premium certified compounds from standard grades and spot-market uncertified resin.
Pricing Analysis
Short lead-time premiums distinguish contract pricing from spot inventory discounts in thermoplastic starch procurement. Three-tier pricing structure across premium, standard, and economy levels reflects EN 13432 certification status and batch-level traceability documentation. Cost compression in economy-grade uncertified compounds is intensifying because biodiesel-derived glycerol plasticizer supply fluctuations destabilize input costs. Quick-service restaurant chains exhibit highest price sensitivity in cutlery procurement, while German supermarket private-label managers prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Aldi and Lidl procurement teams mandate multi-supplier qualification across at least two certified compounders per SKU. Supply concentrates in Germany, Italy, and the Netherlands where industrial composting infrastructure anchors converter operations. Raw material dependencies include native corn and potato starch feedstocks, glycerol plasticizers from biodiesel co-product streams, and polylactic acid precursors from fermentation operations. Single-source vulnerability persists in barrier-enhanced starch films where atomic layer deposition equipment constrains coating capacity. Distribution runs through vertically integrated compounders with dedicated logistics corridors to certified composting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH authorization timelines for persistent organic pollutants force capital-constrained specialty producers to exit certified compound segments.
For Market Incumbents: Deploy backward integration into glycerol plasticizer supply to secure input cost stability against biodiesel market volatility. Novamont S.p.A. and Corbion N.V. exemplify this model through captive fermentation assets. Incumbents should simultaneously expand thermoplastic starch nanocomposite capacity serving Nordic houseware brands, where cellulose nanocrystal reinforcement commands formulation premiums against polypropylene substitution.
For New Entrants and Emerging Players: Trading houses with regional stocking points in Eastern European markets represent the most penetrable channel archetype, as blockchain-verified certificate requirements marginalize these intermediaries in premium German retail supply chains. New entrants should target soil-biodegradable agricultural film demand in India's Maharashtra and Gujarat, where PLI scheme incentives reduce capital barriers to thermoplastic starch capacity establishment. A specialty compounder go-to-market angle through FSSAI-compliant food contact formulations serves domestic snack packaging converters in the Pune-Ahmedabad corridor.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated starch processors with in-house purification assets given REACH solvent-limit enforcement. Long-term viability across the analysis window favors compounders with dedicated regulatory affairs functions capable of certifying full chain-of-custody documentation. Acquisition targets include mid-scale blenders in Italy's Po Valley agricultural belt with established biodegradable mulch film formulations. The signal to watch is EN 13432 certification reciprocity agreements between EU and Asian jurisdictions, which would unlock cross-border inventory mobility and consolidate contract awards among multi-regional compounders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Supply | Biodiesel co-product streams stabilize TPS formulation costs against polyethylene price troughs. |
| EN 13432 Certification Investment | German supermarket private-label managers mandate blockchain-verified compostability certificates. |
| Thermoplastic Starch Nanocomposite Capacity | Cellulose nanocrystal reinforcement closes heat-resistance gaps against polypropylene in Nordic retail. |
| Soil-Biodegradable Agricultural Film Formulation | Italian tomato and strawberry growers calculate retrieval cost savings exceeding material premiums. |
| Atomic Layer Deposition Barrier Coating | Aluminum oxide deposition creates compostable high-barrier structures for oxygen-sensitive snack packaging. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this starch-based plastics market assessment. Primary interviews with blown film converters, compounder regulatory affairs directors, quick-service restaurant procurement managers, and industrial composting facility operators combined with secondary validation from ECHA REACH authorization databases, EU Green Deal implementation reports, and German packaging waste compliance records. Bottom-up and top-down triangulation cross-checked volume estimates across formulation chemistries and end-use specifications.
Granularity-level modeling deployed separate projections for thermoplastic starch, starch blends, biodegradable compounds, and expanded starch product categories. Segmentation dimensions included formulation chemistry, processing technology constraint, compostability certification tier, and regional industrial composting infrastructure density. CAGRs were derived from demand elasticity analysis against polyethylene price differentials and regulatory mandate implementation schedules. Forecast inputs incorporated glycerol plasticizer supply curves from biodiesel production forecasts and EN 13432 certification timeline distributions.
Caveats apply where industrial composting infrastructure deployment lags or REACH solvent-limit enforcement accelerates could materially shift the outlook. Deviation in EU-Asia certification reciprocity agreements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Compostable Phone Cases Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Global Bioplastic Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
China Bioplastics Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
North America Bioplastics Market