
 Asia-Pacific Bio Plasticizers Market | 2026-2036
Asia-Pacific Bio Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bio Plasticizers Market Analytics
GB/T 33372 VOC emission standards for adhesives and sealants is redrawing supplier eligibility across the Asia-Pacific Bio Plasticizers Market. LG Chem leverages captive epoxidized soybean oil capacity to anchor premium positioning in South Korean wire insulation. Zhejiangjiaao Enprotech Stock Co., Ltd. sustains cost leadership through integrated vegetable oil refining in Zhejiang province. DIC Corporation differentiates via specialty adipate esters targeting Japanese automotive OEMs.
Bio plasticizers are renewable-derived additives that impart flexibility to rigid polymer matrices, typically exhibiting plasticizing efficiencies between 0.8 and 1.2 relative to di-octyl phthalate benchmarks and functioning through intermolecular spacing of polyvinyl chloride chains. Their primary purpose is to replace petroleum-based orthophthalates in sensitive applications such as food-contact films, medical tubing, and children's toys where leachate migration must meet sub-ppm thresholds. Packaging applications dominate volume offtake due to Asia's processed food sector expansion, while flooring segments command margin premiums through low-VOC certification requirements in commercial builds. Liquid formulations lead form-level demand given ease of compounding into existing calendering and extrusion lines, though gel variants are gaining traction in precision coating applications requiring controlled viscosity profiles.
China's MEE enforces GB standards limiting phthalate content in consumer goods, while South Korea's MFDS regulates food-contact material migration limits, and India's BIS mandates certification for toys and childcare articles. These frameworks collectively shift procurement specifications toward bio-based alternatives with traceable feedstock chains and third-party compostability verification. Stakeholders must monitor regulatory divergence between national standards bodies to anticipate reformulation timelines and avoid stranded inventory in cross-border supply chains.
Market Dynamics
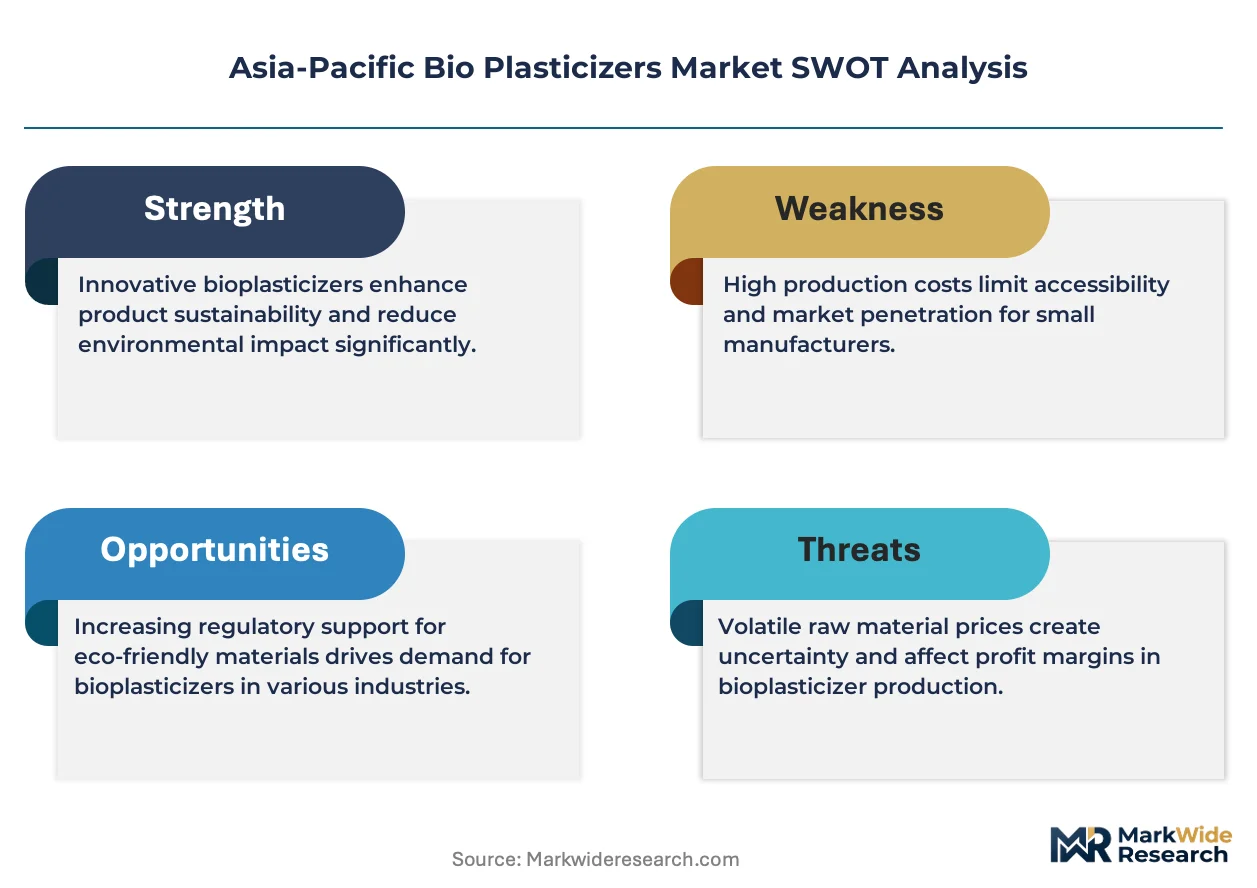
GB/T 33372 VOC emission standards for adhesives and sealants are redrawing supplier eligibility across the Asia-Pacific Bio Plasticizers Market, forcing reformulation timelines that compress procurement cycles and strand non-compliant inventory in cross-border supply chains.
Growth Catalysts
- India's BIS certification mandates:Phthalate-free requirements for children's products are tightening compliance thresholds and redirecting procurement toward bio-based alternatives with traceable feedstock chains.
- Wire and cable sector expansion:Southeast Asian manufacturers are expanding purchases of bio-based alternatives as regional electrical infrastructure buildouts accelerate.
- China's eastern manufacturing corridor:Concentrated demand from Shanghai to Ningbo creates scale economies that reduce unit costs for bio plasticizer formulations.
Market Restraints
- Epoxidized soybean oil price volatility:Agricultural commodity swings transmit directly into raw material costs, compressing margins for formulators lacking captive refining capacity.
- South Korean supply concentration:LG Chem's captive ESO capacity anchors premium positioning, creating barriers for new entrants seeking wire insulation market share.
- Plasticizing efficiency gaps:Bio-based alternatives exhibit 0.8-1.2 efficiency ratios versus di-octyl phthalate benchmarks, requiring higher loadings that increase formulation costs.
Strategic Opportunities
- Japanese automotive OEMs:Specialty adipate esters targeting vehicle interior applications command margin premiums through low-VOC certification requirements.
- Gel variant formulations:Precision coating applications requiring controlled viscosity profiles are gaining traction as a differentiated product line beyond liquid standards.
- Third-party compostability verification:Procurement specifications increasingly demand traceable feedstock chains, creating first-mover advantages for certified suppliers.
Industry Challenges
- Regulatory divergence monitoring:Stakeholders must track national standards bodies across China MEE, South Korea MFDS, and India BIS to anticipate reformulation timelines.
- Cross-border inventory stranding:Divergent compliance thresholds between GB standards, food-contact migration limits, and toy certification requirements create working capital traps.
- Legacy calendering line integration:Existing extrusion infrastructure requires viscosity-profile matching that extends qualification cycles for new bio-based formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bio Plasticizers Market |
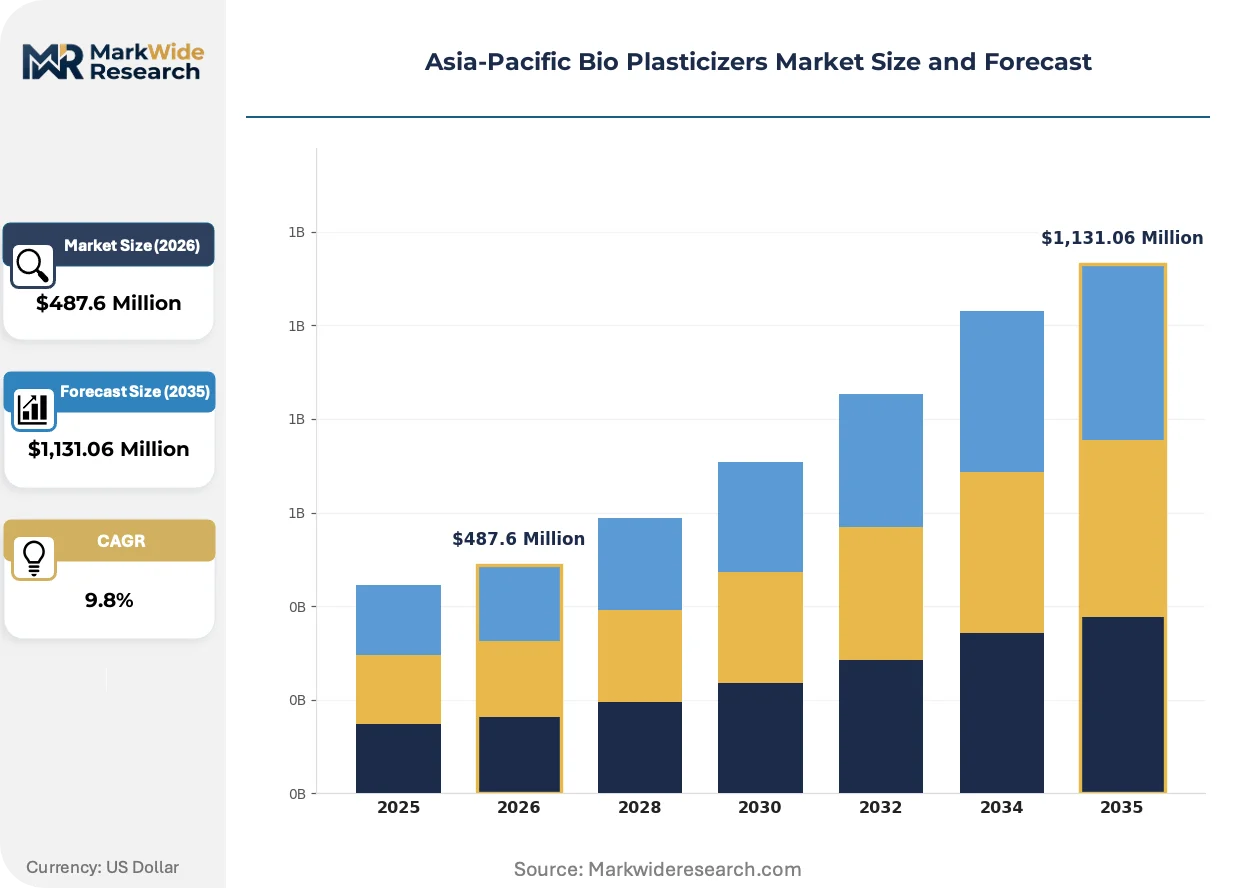
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Di-ethyl Phthalate, Butyl Benzyl Phthalate, Dioctyl Phthalate, Adipates Application: Packaging, Flooring, Toys, Coatings End User: Automotive, Construction, Consumer Goods, Electronics Form: Liquid, Solid, Gel, Paste |
| Companies Covered | DIC Corporation, Zhejiangjiaao Enprotech Stock Co., Ltd., Aekyung Chemical, JiangXi East Huge Dragon Chemical co.,ltd, Hebei Jingu Plasticizer Co. Ltd., UPC Technology Corp., KLJ Group, Hanwha Chemical, LG Chem, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bio Plasticizers Market Evolving Landscape
Formulation chemistry advances and procurement specification tightening are converging to reshape competitive positioning in Asia-Pacific bio plasticizer supply, with certification-driven segmentation overtaking commodity pricing as the primary value lever.
Epoxidized soybean oil derivatives are displacing petroleum-based orthophthalates in food-contact film applications across China's processed food sector expansion. Major packaging converters in the Shanghai-Ningbo corridor are qualifying these alternatives at accelerated pace to meet GB/T migration limits. This displacement is compressing the addressable market for conventional plasticizers while expanding premium-tier pricing for verified bio-based supply.
China's MEE enforcement of GB standards limiting phthalate content in consumer goods is tightening industrial compliance windows. Manufacturers must now document feedstock provenance through third-party verification chains to maintain supplier status. Wire and cable segments in South Korea and flooring applications in commercial builds across Southeast Asia are most affected, with procurement teams extending qualification timelines to capture certification documentation.
Buyer concentration among Southeast Asian wire and cable manufacturers is consolidating procurement volumes toward preferred suppliers with integrated vegetable oil refining. Direct mill relationships are replacing distributor intermediaries for large-scale offtake agreements. This channel compression is most visible in Vietnam and Thailand, where electrical infrastructure investment is concentrating demand among three to four major cable producers.
Asia-Pacific Bio Plasticizers Market Segmentation
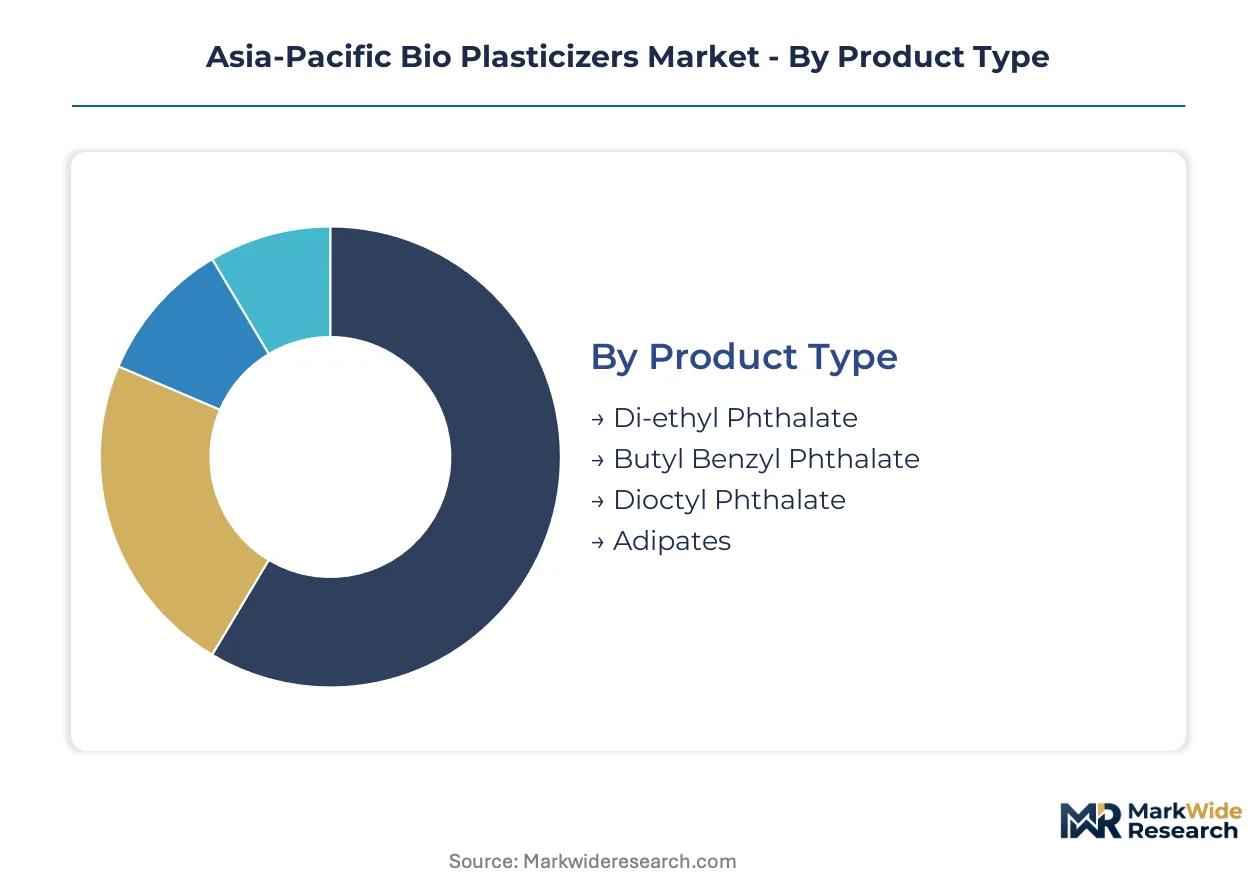
Segmentation reveals how bio plasticizer procurement splits between export-facing specifications and domestic compliance tiers. Each dimension carries distinct margin profiles and qualification barriers that reshape supplier positioning across the Asia-Pacific corridor.
Product Type:
Di-ethyl phthalate and butyl benzyl phthalate formulations serve predominantly export-oriented wire and cable manufacturers seeking REACH-equivalent compliance. Dioctyl phthalate and adipate variants anchor domestic consumption within China's GB-standard industrial base.
- Di-ethyl Phthalate:Lower molecular weight ester delivering rapid plasticizing action in flexible PVC compounds. Demand concentrates in Southeast Asian wire insulation exports to European automotive harness suppliers, where REACH registration costs filter out smaller compounders. Agricultural commodity volatility in soybean oil feedstocks compresses margins for non-integrated producers.
- Butyl Benzyl Phthalate:Aromatic-ring structure provides superior stain resistance in flooring applications. Japanese commercial build specifications drive premium offtake, with MFDS migration limits forcing reformulation away from conventional orthophthalates. Certification documentation extends qualification cycles by four to six months.
- Dioctyl Phthalate:Workhorse plasticizer for domestic Chinese packaging films meeting GB/T 33372 VOC thresholds. Cost-sensitive converters in the Zhejiang corridor favor this grade for calendering line compatibility.
- Adipates:Linear diester chemistry targeting low-temperature flexibility in automotive interior applications. South Korean OEMs specify adipate esters for dashboard skins requiring minus forty-degree performance.
Dioctyl phthalate commands the established base. The steepest expansion runs through adipates.
Application:
Packaging and flooring applications split between high-volume commodity supply and certified premium tiers. Toys and coatings occupy specialized niches with divergent technical requirements and regulatory exposure.
- Packaging:Food-contact films dominate volume offtake across China's processed food sector expansion. Shanghai-Ningbo converters qualify bio-based alternatives at accelerated pace to meet GB/T migration limits. Direct mill relationships are replacing distributor intermediaries for large-scale agreements.
- Flooring:Commercial build specifications command margin premiums through low-VOC certification requirements. Southeast Asian hospitality projects specify bio plasticizer content for LEED-equivalent green building credits. Documentation burdens extend procurement timelines.
- Toys:India's BIS phthalate-free mandates tighten compliance thresholds for childcare articles. Traceable feedstock chains with third-party verification separate qualified suppliers from commodity traders.
- Coatings:Precision viscosity control requirements favor gel-variant formulations in automotive refinishing and industrial maintenance applications.
Packaging captures volume leadership. Coatings is climbing the fastest.
End User:
Automotive and electronics procurement teams specify certified bio-based grades with full documentation chains. Construction and consumer goods buyers prioritize cost position and calendering line compatibility.
- Automotive:Japanese OEM interior specifications drive specialty adipate ester demand with sub-ppm migration thresholds. Tier-one suppliers must document epoxidized soybean oil provenance through third-party verification to maintain approved vendor status.
- Construction:Wire and cable infrastructure buildouts across Vietnam and Thailand concentrate demand among three to four major cable producers. Integrated vegetable oil refining capabilities determine supplier selection.
- Consumer Goods:Toys and childcare articles face India's BIS certification mandates with escalating testing requirements. Smaller molders struggle with qualification costs.
- Electronics:Cable jacketing for data centers and telecommunications requires flame-retardant compatibility with bio plasticizer loadings. South Korean wire manufacturers specify LG Chem captive ESO capacity for premium positioning.
Construction anchors the volume base. Automotive is gaining share fastest.
Form:
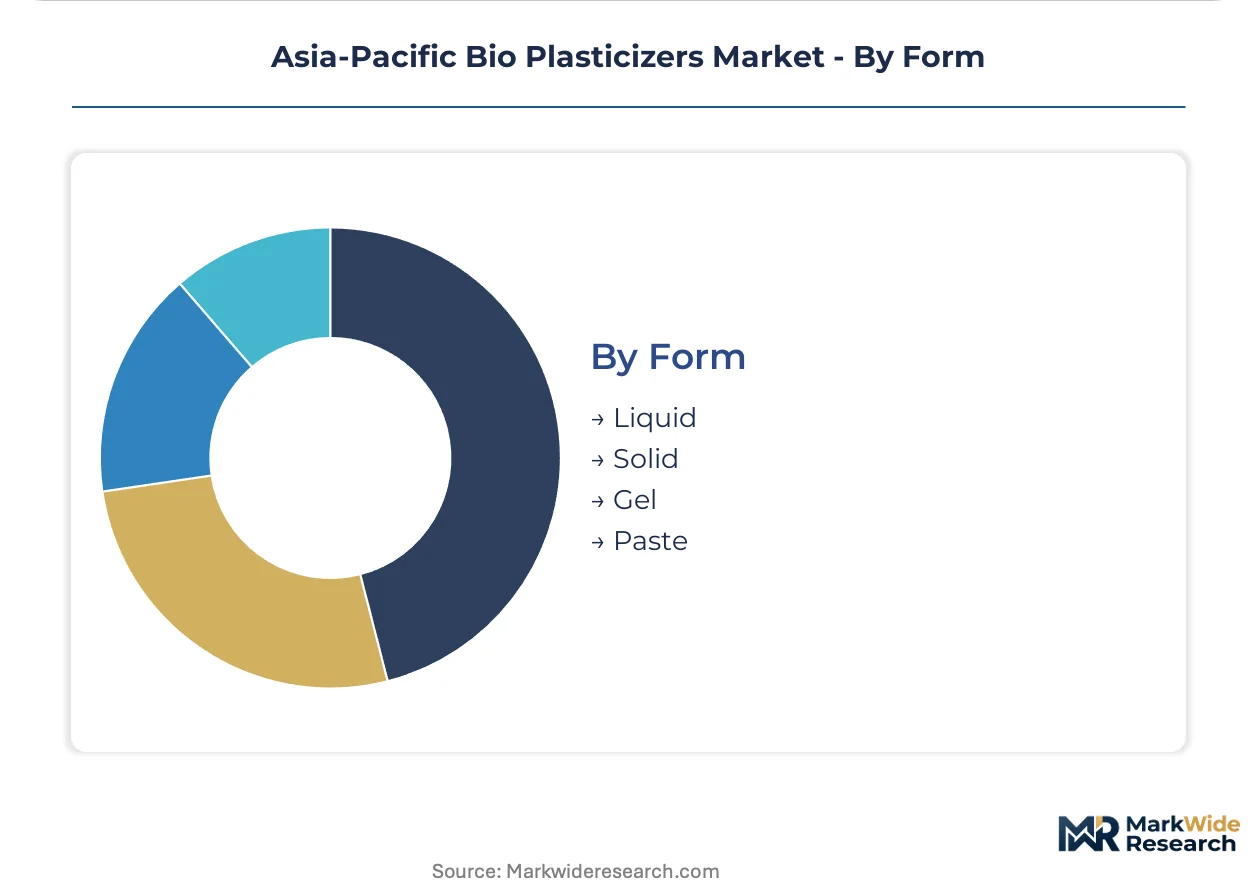
Liquid formulations integrate seamlessly into existing extrusion infrastructure. Solid, gel, and paste variants require specialized compounding equipment and extended qualification protocols.
- Liquid:Standard viscosity profiles enable direct drop-in replacement for petroleum-based plasticizers in calendering and extrusion lines. China's eastern manufacturing corridor from Shanghai to Ningbo drives scale economies.
- Solid:Pelletized concentrates suit remote compounders lacking liquid handling infrastructure. Southeast Asian wire manufacturers favor solid forms for inventory stability in tropical climates.
- Gel:Controlled rheology targets precision coating applications in automotive refinishing and electronics conformal coatings. Viscosity-profile matching extends qualification cycles.
- Paste:High-viscosity formulations for plastisol applications in flooring and wall covering segments. Limited supplier base creates sourcing concentration.
Liquid holds the established base. Gel is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wire and cable manufacturers, packaging converters, and automotive OEMs concentrate procurement across four distinct national markets, each with divergent regulatory timelines and feedstock access shaping supplier selection.
China
Packaging converters in the Shanghai-Ningbo corridor drive volume demand as processed food sector expansion accelerates. MEE enforcement of GB/T 33372 VOC standards for adhesives and sealants compresses reformulation timelines for local suppliers. Eastern manufacturing clusters from Jiangsu to Zhejiang province are qualifying bio-based alternatives at accelerated pace to maintain supplier status.
India
Toy manufacturers and childcare article molders face tightening compliance thresholds under BIS phthalate-free mandates. The national standards body escalates testing requirements for traceable feedstock chains. Industrial concentrations in Maharashtra and Gujarat struggle with qualification costs that filter out smaller compounders from approved vendor lists.
Japan
Automotive OEM interior specifications command premium pricing for specialty adipate esters with sub-ppm migration thresholds. METI-aligned technical standards shape procurement documentation requirements. Tier-one suppliers in the Nagoya corridor must verify epoxidized soybean oil provenance through third-party chains to maintain approved status.
South Korea
Wire insulation manufacturers specify captive epoxidized soybean oil capacity for premium cable jacketing positions. MFDS food-contact migration limits regulate material qualification protocols. Seoul-based electronics cable producers concentrate demand among preferred suppliers with integrated vegetable oil refining capabilities.
Vietnam
Electrical infrastructure buildouts concentrate wire and cable procurement among three to four major cable producers. Direct mill relationships replace distributor intermediaries for large-scale offtake agreements. Ho Chi Minh City industrial zones are absorbing regional supply chain reconfiguration as manufacturers relocate from China.
Asia-Pacific Bio Plasticizers Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive vegetable oil refining capacity, supplemented by mid-scale specialists in epoxidized soybean oil derivatives and regional distributors serving cost-sensitive packaging converters. Strategic archetypes split between feedstock-integrated majors, formulation specialists, and import-dependent traders. Capacity expansion and backward integration into vegetable oil refining represent dominant competitive moves as margin pressure from agricultural commodity volatility intensifies.
Among Japan-based chemical conglomerates, DIC Corporation occupies a position exemplifying specialty ester differentiation for automotive OEM requirements. Korean industrial groups including LG Chem and Hanwha Chemical represent the feedstock-integrated archetype with captive epoxidized soybean oil positions. Chinese specialists such as Zhejiangjiaao Enprotech Stock Co., Ltd. anchor cost-leadership positioning through integrated vegetable oil refining in coastal manufacturing clusters.
| Leading Market Players |
|---|
| DIC Corporation |
| Zhejiangjiaao Enprotech Stock Co., Ltd. |
| Aekyung Chemical |
| JiangXi East Huge Dragon Chemical co.,ltd |
| Hebei Jingu Plasticizer Co. Ltd. |
| UPC Technology Corp. |
| KLJ Group |
| Hanwha Chemical |
| LG Chem |
| Others |
Value Network & Pricing Analysis
Epoxidized soybean oil displacement of petroleum-based orthophthalates simultaneously redistributes supply geography toward coastal China and South Korea while compressing pricing premiums for verified bio-based grades. Agricultural commodity indexation in raw material contracts transmits soybean price volatility directly into formulation costs, forcing buyers to choose between captive-integrated suppliers and exposed traders.
Pricing Analysis
Cost-plus contracts indexed to CBOT soybean oil futures dominate procurement agreements across the Asia-Pacific corridor. Pricing stratifies across premium certified grades for Japanese automotive OEMs, standard GB-compliant tiers for Chinese packaging converters, and economy spot positions for Southeast Asian wire manufacturers. Cost compression in standard tiers is intensifying because Zhejiang-based integrated refiners expand capacity. Small compounders lacking backward integration face the steepest price sensitivity, while tier-one automotive suppliers accept premium positioning for documented feedstock chains.
Supply Chain Analysis
Inventory strategy splits between just-in-time liquid delivery for Shanghai-Ningbo calendering lines and strategic stockpiling of solid concentrates by Vietnamese wire manufacturers in tropical storage. Supply concentrates in China, South Korea, and Japan, with epoxidized soybean oil, specialty adipate esters, and vegetable oil feedstocks anchoring raw material dependencies. Single-source vulnerability runs through LG Chem's captive ESO capacity for premium Korean cable jacketing. Distribution runs through direct mill relationships replacing distributor intermediaries for large-scale offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as regulatory divergence between China MEE, South Korea MFDS, and India BIS creates compliance-tier niches that favor specialized formulators over commodity traders.
For Market Incumbents: Shield market position by deepening backward integration into vegetable oil refining in Zhejiang and Jiangsu provinces to offset agricultural commodity volatility. Accelerate third-party compostability certification investments to capture procurement specifications demanding traceable feedstock chains before smaller competitors qualify. For New Entrants and Emerging Players: Technical documentation services for BIS certification compliance represent a service-layer gap where incumbents under-serve Indian toy manufacturers struggling with qualification costs. Target Maharashtra and Gujarat molding clusters with bundled testing and feedstock verification offerings. Pursue gel-variant formulation partnerships with automotive refinishing specialists as the most penetrable premium tier. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors feedstock-integrated specialists with captive refining capacity and established OEM qualification relationships. Long-term viability hinges on regulatory enforcement durability across the Asia-Pacific corridor. Watch India BIS testing requirement escalation as the signal indicating sustained pricing power for certified suppliers versus commodity traders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Refining | Zhejiangjiaao's integrated coastal operations demonstrate margin protection against soybean price swings. |
| Third-Party Compostability Certification | GB/T compliance documentation separates approved automotive suppliers from stranded inventory traders. |
| Specialty Adipate Ester Capacity Addition | DIC Corporation's Japanese automotive positioning commands premium through sub-ppm migration thresholds. |
| Direct Mill Relationship Development | Vietnamese cable producers consolidate procurement among three to four preferred suppliers with refining control. |
| Gel-Variant Formulation R&D Investment | Precision coating applications in automotive refinishing create differentiated viscosity-profile offerings. |
Research Methodology
A spread of perspectives from plant managers at epoxidized soybean oil refineries, procurement leads at Japanese automotive OEMs, technical R&D directors at Chinese packaging converters, and distribution channel partners across Southeast Asia converged on the working assumptions shaping this analysis. Primary interview insights triangulated against customs and trade data, SEC 10-K chemical segment disclosures, China MEE regulatory filings, and South Korea MFDS migration limit documentation. Bottom-up volume estimates from individual facility capacities reconciled with top-down demand projections derived from end-use industry consumption patterns.
Segmentation dimensions modeled include product chemistry tier, end-use application vertical, form specification, and regional regulatory compliance cluster across the projection horizon. CAGRs emerged from slope analysis of historical trajectory adjusted for enforcement intensity of GB standards, BIS certification mandates, and MFDS food-contact regulations. Industry-specific forecast inputs incorporated electrical infrastructure investment pipelines in Vietnam and Thailand plus processed food sector expansion rates in China's eastern manufacturing corridor.
Forecasts assume regulatory continuity in China MEE enforcement, India BIS escalation, and South Korea MFDS migration protocols; material policy shifts would require re-modeling. Agricultural commodity price volatility, cross-border inventory stranding from divergent compliance thresholds, and qualification timeline extensions for legacy calendering line integration represent specific risk factors. Revision becomes warranted when BIS testing requirement intensity crosses thresholds filtering more than half of incumbent suppliers from approved vendor lists.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biocomposite Materials Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Starch Blended Biodegradable Polymer Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biopolymer Films Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-PET Market
Bioplastics
Compostable Phone Cases Market