
 Polyglycerol Market | 2026-2036
Polyglycerol Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglycerol Market Intelligence
Green chemistry advances in enzymatic glycerol polymerization is reshaping how polyglycerol derivatives achieve higher oligomer purity with lower energy input. Cargill Incorporated leverages its agricultural feedstock base to secure cost-advantaged glycerol supply chains. BASF SE anchors European production through integrated oleochemical complexes in Ludwigshafen. Evonik Industries specializes in high-purity grades for pharmaceutical and personal care applications.
Polyglycerol comprises oligomers of glycerol linked through ether bonds, typically containing two to ten glycerol units with hydroxyl values ranging from 1000 to 1800 mg KOH/g, serving primarily as hydrophilic building blocks for food-grade emulsifiers, cosmetic humectants, and pharmaceutical excipients. Polyglycerol esters dominate volume due to their extensive use in margarine, confectionery, and whipped toppings where they replace synthetic emulsifiers. Personal care applications expand fastest as formulators substitute polyglycerol oleates for ethoxylated surfactants under clean-label pressures. Polyglycerol phosphate retains niche positioning in corrosion inhibition for water-based coatings.
EMA guidelines on excipient quality and the EU Green Deal's bio-based content thresholds shape product standards and market access across European pharmaceutical and cosmetic supply chains. FDA food additive regulations and FSSAI standards for polyglycerol esters in bakery and dairy applications create compliance layers that favor established producers with documented supply chain traceability. Stakeholders must monitor how tightening purity specifications and renewable content mandates redistribute margin pools between commodity-grade and specialty-grade polyglycerol manufacturers.
Market Dynamics
Enzymatic glycerol polymerization is compressing energy requirements and elevating oligomer purity thresholds, forcing capital reallocation across oleochemical value chains.
Growth Catalysts
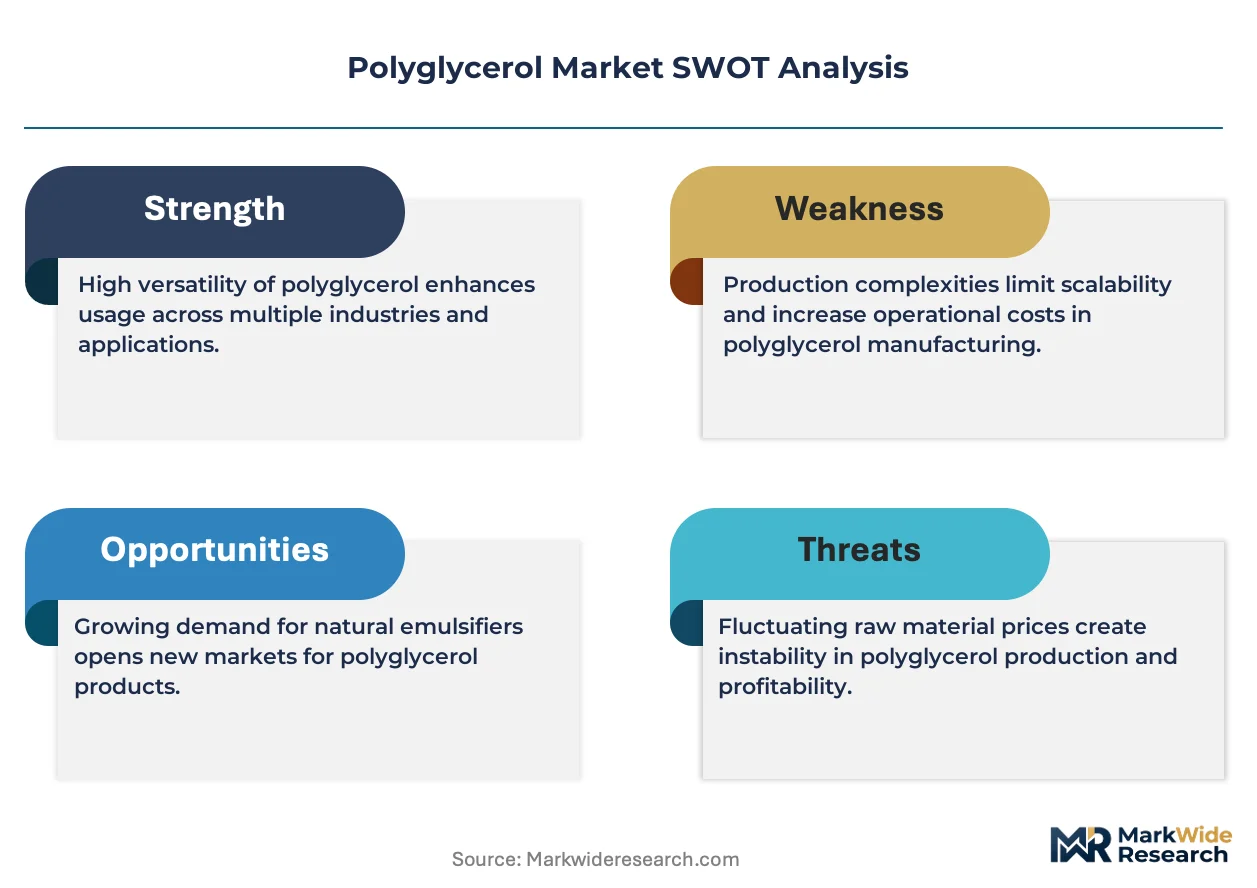
- EU Green Deal bio-based mandates:Cosmetic formulators in Germany replace petrochemical polyols with plant-derived polyglycerol to meet renewable content thresholds.
- Clean-label confectionery reformulation:Food manufacturers adopt polyglycerol esters as emulsifier alternatives to synthetic additives under tightening consumer scrutiny.
- Pharmaceutical excipient upgrading:EMA quality guidelines push drug developers toward high-purity polyglycerol grades for oral and topical delivery systems.
Market Restraints
- Crude glycerol price volatility:Biodiesel output fluctuations create feedstock cost instability for polymerization facilities.
- Specialty-grade supply concentration:Ludwigshafen and Hamburg clusters control European high-purity production, creating geographic bottleneck risk.
- Ethoxylated surfactant lock-in:Established personal care formulations resist reformulation due to performance validation costs.
Strategic Opportunities
- India FSSAI compliance pathway:Bakery and dairy processors seek approved polyglycerol ester suppliers for domestic market expansion.
- Corrosion inhibition coatings:Polyglycerol phosphate gains traction in water-based industrial paint systems.
- Enzyme-process technology licensing:Biocatalysis platforms enable regional producers to bypass capital-intensive thermal polymerization.
Industry Challenges
- Cross-functional formulation expertise:Cosmetic chemists with combined emulsifier and bio-based material knowledge command scarcity premiums.
- Multi-jurisdiction traceability systems:FDA, EMA, and FSSAI documentation requirements strain supplier quality infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglycerol Market |
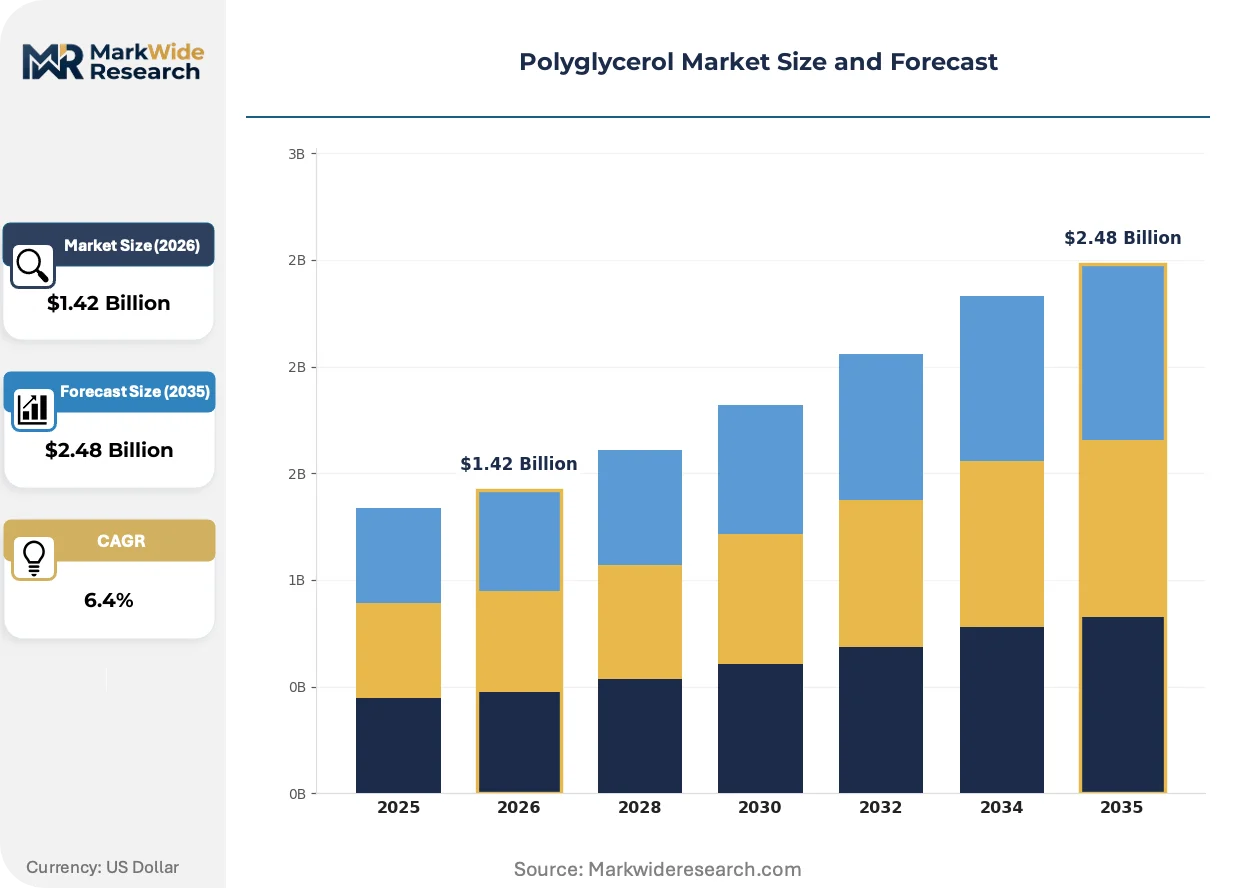
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyglycerol Esters, Polyglycerol Phosphate, Polyglycerol Succinates, Polyglycerol Oleates Applications: Food Industry, Personal Care, Pharmaceuticals, Paints End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Coating Producers Distribution Channel: Online Retailers, Direct Sales, Distributors, B2B Supply |
| Companies Covered | Cargill Incorporated, Palsgaard A/S, BASF SE, Stepan Company, Taiyo Kagaku, Evonik Industries, Lonza Group, Sakamoto Yakuhin Kogyo Co., Ltd., Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglycerol Market Strategic Shifts & Innovations
Process intensification and regulatory harmonization are compressing development cycles while fragmenting competitive advantage sources across the value chain.
Continuous-flow enzymatic reactors are virtualizing batch polymerization economics. Specialty chemical producers in the Netherlands and Belgium retrofit existing glycerol infrastructure with immobilized lipase systems. This technology is virtualizing capital deployment models by enabling modular scale-up without dedicated greenfield construction.
REACH substance evaluation expansions are tightening oligomer distribution specifications for cosmetic-grade polyglycerol. ECHA scrutiny of residual glycerol and diglycerol content forces reformulators to invest in chromatographic purification. Personal care ingredient distributors in Düsseldorf and Hamburg accelerate third-party testing partnerships to preempt compliance gaps.
Direct-procurement platforms are disintermediating traditional oleochemical distributors. Mid-sized cosmetic brands in France and Spain source polyglycerol esters through certified supplier portals with embedded chain-of-custody documentation. This channel shift concentrates volume with producers possessing integrated quality management systems.
Polyglycerol Market Segmentation
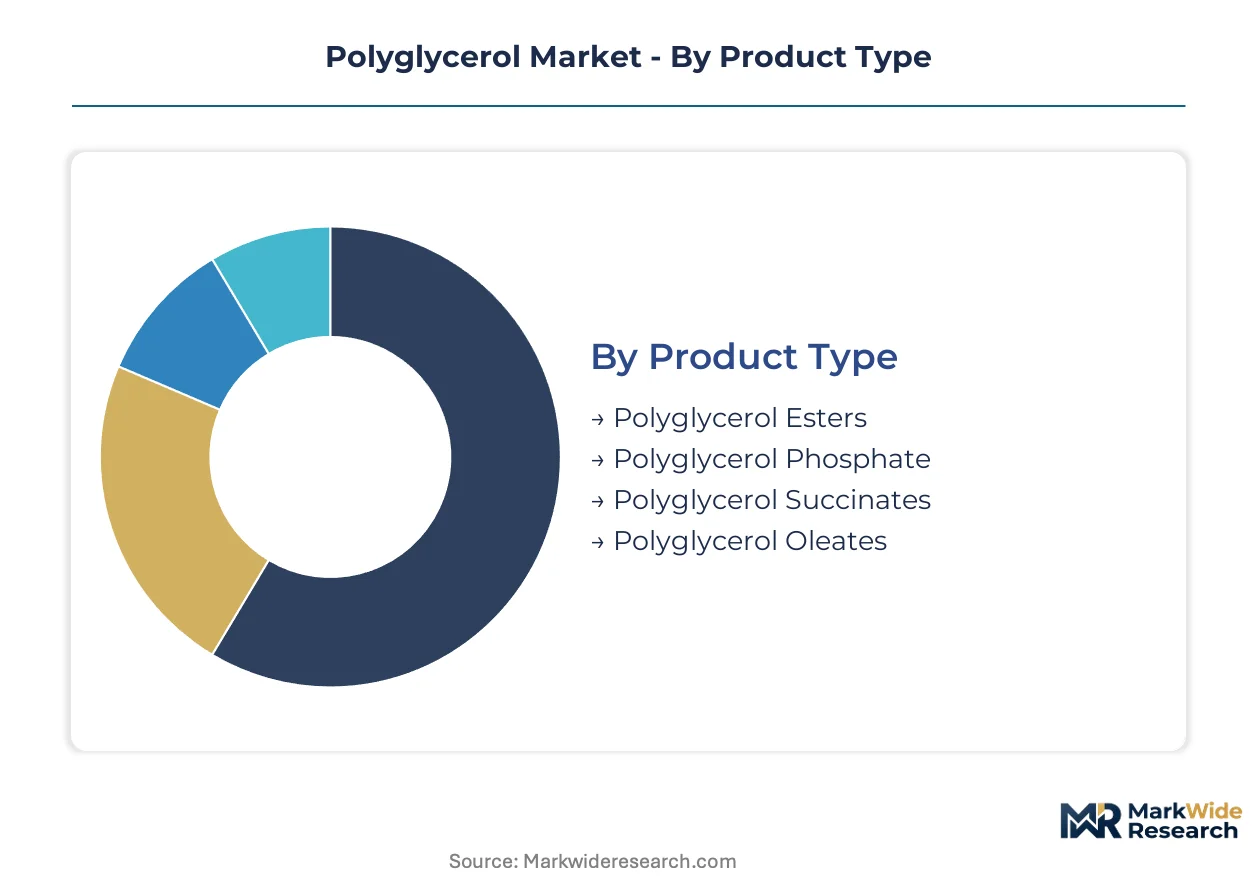
Polyglycerol derivatives serve distinct functional roles across food emulsification, cosmetic formulation, and pharmaceutical delivery. Segmentation reveals how oligomer purity and esterification degree determine pricing tiers and regulatory pathways.
Product Type:
Derivatives span from commodity emulsifiers to high-purity excipients, with oligomer distribution and ester chain length defining application boundaries.
- Polyglycerol Esters:These comprise glycerol oligomers esterified with fatty acids, typically C16-C18 chains, delivering HLB values from 3 to 15 for water-in-oil and oil-in-water systems. Food manufacturers in Germany substitute these for synthetic emulsifiers under clean-label mandates from the EU Green Deal. Crude glycerol price swings from biodiesel production compress margins for commodity-grade suppliers.
- Polyglycerol Oleates:Unsaturated C18:1 esters of polyglycerol-3 through polyglycerol-10 provide skin-feel modulation and solubilization for lipid-active ingredients. Cosmetic formulators in Hamburg and Düsseldorf clusters deploy these to replace ethoxylated surfactants under REACH oligomer scrutiny. ECHA evaluation of residual diglycerol content forces chromatographic purification investments.
- Polyglycerol Phosphate:Phosphate esters deliver corrosion inhibition through metal surface chelation in water-based coating systems. Coating producers leverage these for low-VOC industrial paint formulations.
- Polyglycerol Succinates:Succinic acid esters provide pH-responsive emulsification for pharmaceutical microemulsion systems. Drug developers value these for oral bioavailability enhancement of poorly soluble actives.
The dominant share belongs to Polyglycerol Esters, while Polyglycerol Oleates is closing the gap fastest.
Applications:
End-use concentration tracks regulatory intensity, with food and personal care absorbing volume and pharmaceutical commanding premium pricing.
- Food Industry:Margarine, confectionery, and whipped topping applications exploit polyglycerol ester functionality for aeration and crystallization control. FSSAI standards in India and FDA food additive regulations create multi-jurisdiction compliance layers favoring documented supply chains.
- Personal Care:Moisturizers, cleansers, and sun care products incorporate polyglycerol derivatives as humectants and emulsifiers. EMA excipient quality guidelines and EU Green Deal bio-based thresholds reshape procurement specifications.
- Pharmaceuticals:Oral and topical delivery systems demand high-purity grades with defined oligomer distributions. Ludwigshafen production clusters anchor European supply for these stringent applications.
- Paints:Water-based industrial coatings utilize polyglycerol phosphate for corrosion protection. Formulators substitute these for traditional phosphate esters under environmental pressure.
Food Industry holds the volume lead, though Personal Care generates steepest expansion trajectory as clean-label pressures intensify.
End User:
Customer sophistication varies from commodity procurement in food manufacturing to specification-driven purchasing in pharmaceuticals.
- Food Manufacturers:Bakery and dairy processors specify polyglycerol esters for emulsification and shelf-life extension. FSSAI compliance requirements in India drive supplier qualification protocols.
- Cosmetic Companies:Formulators seek bio-based emulsifiers with documented renewable content for EU Green Deal alignment. Hamburg and Düsseldorf ingredient clusters concentrate purchasing power.
- Pharmaceutical Firms:Drug developers require excipient grades meeting EMA quality guidelines with full supply chain traceability. Ludwigshafen integrated oleochemical complexes serve these stringent demands.
- Coating Producers:Industrial paint manufacturers specify polyglycerol phosphate for water-based corrosion inhibition systems. REACH substance evaluation influences substitution patterns.
Food Manufacturers account for the largest procurement volume, yet Cosmetic Companies are gaining share fastest through bio-based reformulation mandates.
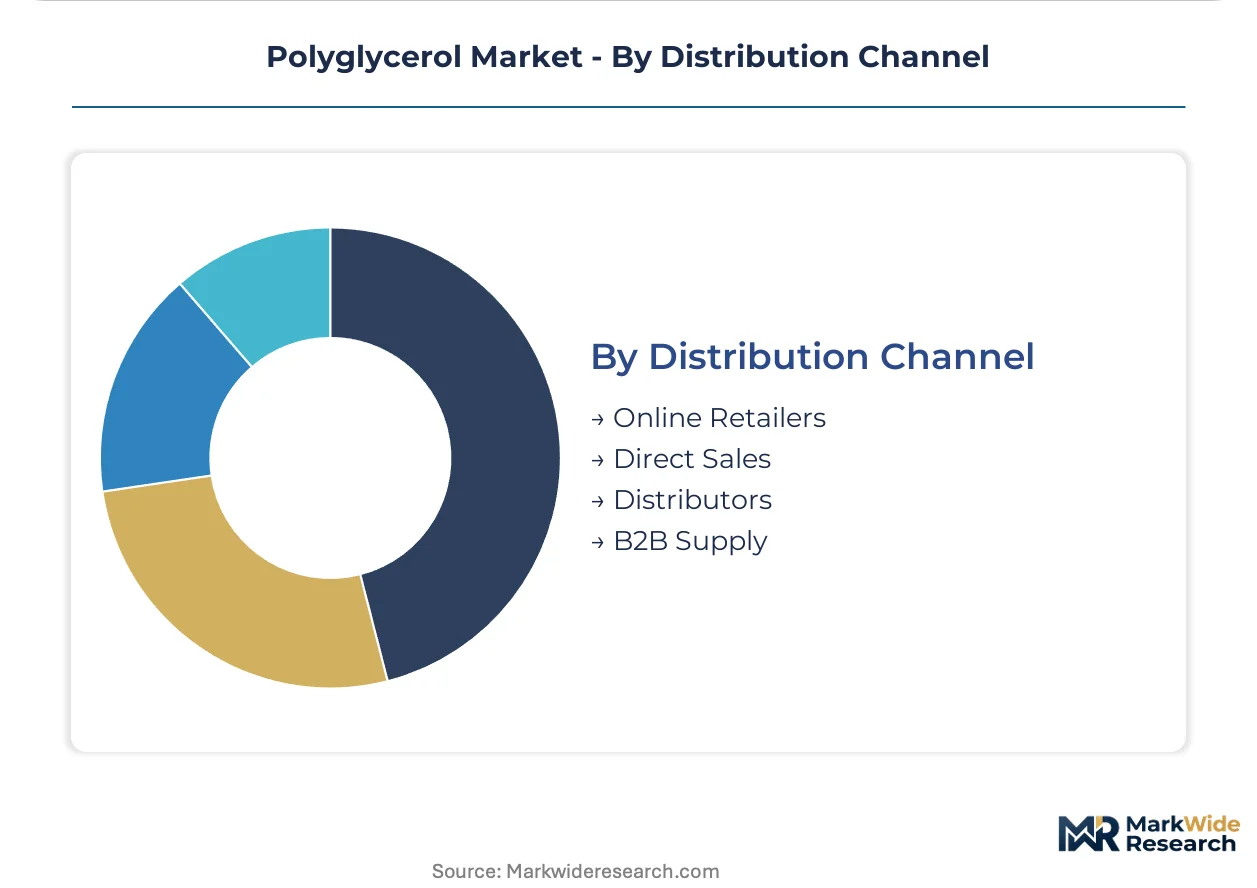
Distribution Channel:
Channel selection reflects customer scale and documentation requirements, with direct procurement displacing traditional intermediaries.
- Direct Sales:Large food and cosmetic manufacturers negotiate long-term contracts with integrated producers for supply security and chain-of-custody documentation. BASF SE and Cargill Incorporated leverage agricultural feedstock positions for direct relationships.
- Distributors:Regional chemical distributors serve mid-sized formulators with technical support and inventory management. Düsseldorf and Hamburg clusters host specialized oleochemical distributors.
- B2B Supply:Contract manufacturing arrangements link polyglycerol producers to finished goods manufacturers. Embedded quality management systems satisfy multi-jurisdiction traceability demands.
- Online Retailers:Small-scale cosmetic brands and independent formulators source through certified supplier portals with compliance documentation. These platforms disintermediate traditional distribution for sub-tonnage orders.
Direct Sales commands the dominant channel position, while Online Retailers are expanding most quickly among emerging cosmetic brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-purity polyglycerol grades to pharmaceutical formulators across France and Switzerland, while China ships commodity polyglycerol esters to Southeast Asian food processors.
United States
Food manufacturers in the Midwest and California drive polyglycerol ester consumption for clean-label bakery applications. FDA food additive regulations mandate documented supply chain traceability for emulsifier approvals. Houston and Chicago host oleochemical processing clusters where producers retrofit glycerol infrastructure for higher oligomer purity.
Germany
Cosmetic formulators in Hamburg and Düsseldorf source plant-derived polyglycerol to meet EU Green Deal bio-based thresholds. REACH substance evaluations force investments in chromatographic purification for residual diglycerol control. Ludwigshafen anchors European high-purity production through integrated oleochemical complexes serving pharmaceutical and personal care sectors.
China
Biodiesel expansion in Jiangsu and Shandong provinces generates crude glycerol feedstock for domestic polymerization facilities. GB standards for food additives create compliance frameworks for polyglycerol ester manufacturers. The Yangtze River Delta concentrates esterification capacity serving both domestic food processors and export markets across Southeast Asia.
India
Bakery and dairy processors in Maharashtra and Gujarat seek FSSAI-approved polyglycerol ester suppliers for domestic market expansion. The national food regulator mandates additive safety documentation that favors established producers with quality management systems. Mumbai and Ahmedabad ingredient distributors build technical support capabilities for mid-sized regional food manufacturers.
Japan
Cosmetic brands in Tokyo and Osaka prefectures demand high-purity polyglycerol oleates for premium skincare formulations. METI guidelines on chemical substance safety influence procurement specifications for bio-based emulsifiers. The Kanto region hosts specialty chemical distributors linking domestic formulators to regional glycerol derivative suppliers.
Polyglycerol Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base spans agricultural conglomerates with captive glycerol supply, integrated oleochemical majors with multi-plant networks, and regional esterification specialists serving single-application niches. Three archetypes dominate: feedstock-integrated agricultural processors, diversified chemical conglomerates with pharmaceutical-grade capabilities, and focused emulsifier specialists with formulation technical service. Competitive moves concentrate on enzymatic process licensing partnerships and direct-procurement platform development to capture mid-sized cosmetic brand volume.
Among feedstock-integrated players, Cargill Incorporated exemplifies the agricultural-processor archetype with glycerol supply chain control. BASF SE and Evonik Industries occupy positions within the diversified-chemical tier, anchoring European high-purity production through Ludwigshafen-based manufacturing infrastructure. These three entities represent distinct competitive vectors: upstream feedstock security, integrated multi-grade production scale, and pharmaceutical-specialist purity capabilities.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Palsgaard A/S |
| BASF SE |
| Stepan Company |
| Taiyo Kagaku |
| Evonik Industries |
| Lonza Group |
| Sakamoto Yakuhin Kogyo Co., Ltd. |
| Croda International Plc |
| Others |
Cost & Logistics Intelligence
Crude glycerol price volatility from biodiesel output fluctuations compresses margin pools across polymerization tiers while simultaneously forcing geographic consolidation of high-purity production capacity. This feedstock instability widens spreads between commodity-grade polyglycerol esters and pharmaceutical-grade oligomers, concentrating supply chain control with Ludwigshafen-integrated producers who possess captive glycerol refining and chromatographic purification infrastructure.
Pricing Analysis
Thermal polymerization legacy systems command economy-tier positioning against enzymatic next-generation platforms capturing premium pricing for elevated oligomer purity. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and food-grade levels reflects certification intensity from EMA guidelines and FSSAI standards. Pricing pressure stems from biodiesel-driven crude glycerol cost swings that squeeze commodity ester margins. Food manufacturers exhibit highest price sensitivity due to bulk procurement volumes, while pharmaceutical firms accept premium tiers for documented traceability.
Supply Chain Analysis
Contract manufacturing concentration rests with Ludwigshafen oleochemical complexes, Hamburg cosmetic ingredient clusters, and Jiangsu biodiesel-integrated polymerization facilities. Geographic supply concentration centers on Germany, China, and India as primary production nodes. Raw material dependencies draw from crude glycerol feedstock, immobilized lipase biocatalysts, and C16-C18 fatty acid streams. Single-source vulnerability concentrates in European high-purity grades where REACH oligomer specifications limit qualified suppliers. Distribution runs through direct-procurement platforms disintermediating traditional oleochemical distributors for mid-sized cosmetic brand volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery phase anchored to biodiesel output expansion normalizing crude glycerol feedstock economics. Recovery timing hinges on enzymatic process licensing adoption compressing capital barriers for regional capacity additions.
For Market Incumbents: Insulate margin position through backward integration into agricultural glycerol supply and chromatographic purification capacity for EMA-compliant oligomer grades. Threat substitution from ethoxylated surfactant reformulation resistance demands technical service investment in clean-label emulsifier validation. Priority lever: Ludwigshafen production cluster expansion with embedded quality management systems satisfying multi-jurisdiction traceability. For New Entrants and Emerging Players: Maharashtra and Gujarat bakery-dairy processor clusters represent underpenetrated FSSAI compliance pathways where established supplier qualification gaps create procurement vulnerability. White-space targets concentrate on mid-tier food manufacturers seeking documented supply chains and regional cosmetic brands requiring bio-based emulsifier technical support. Go-to-market angle: enzyme-process technology licensing partnerships bypassing capital-intensive thermal polymerization infrastructure. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors feedstock-integrated agricultural processors with glycerol supply chain control. Long-term viability across the projection horizon rests on enzymatic platform adoption curves and regulatory harmonization on oligomer purity specifications. Acquisition target archetype: regional esterification specialists possessing FSSAI-approved status and cosmetic-grade purification capabilities. Signal to watch: ECHA substance evaluation expansions tightening residual diglycerol thresholds as compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Biocatalysis platforms enable modular scale-up without dedicated greenfield construction in regional markets. |
| Backward Integration into Glycerol Supply | Agricultural feedstock control secures cost-advantaged raw material positions against biodiesel volatility. |
| Chromatographic Purification Investment | REACH oligomer specifications force residual diglycerol control for cosmetic-grade market access. |
| Direct-Procurement Platform Development | Certified supplier portals with embedded chain-of-custody documentation capture mid-sized cosmetic brand volume. |
| FSSAI Compliance Pathway Establishment | Documented quality management systems unlock Maharashtra and Gujarat bakery-dairy processor procurement. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, Cefic sector reports, and ECHA substance evaluation databases. Primary interviews engaged plant managers at polymerization facilities, procurement leads at downstream food and cosmetic manufacturers, distribution channel partners in Düsseldorf and Hamburg clusters, and technical R&D directors specializing in enzymatic glycerol chemistry. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis and production capacity assessments across Germany, China, and India.
Forecast inputs span grade tier segmentation, end-use industry concentration, regional production hub distribution, and enzymatic technology adoption curves. Analytical framework projects volume and value trajectories across the analysis window through demand-side modeling of food emulsification, personal care reformulation, and pharmaceutical excipient upgrading. CAGRs derive from segment-level growth rate reconciliation against macro oleochemical demand indicators and regulatory compliance cost evolution.
Practitioners should monitor crude glycerol price volatility, ECHA oligomer specification expansions, and enzymatic licensing partnership announcements for early signals of forecast revision. Forecasts reflect assumptions on biodiesel output normalization, REACH implementation timelines, and FSSAI enforcement intensity. Quarterly review of feedstock cost indices, regulatory consultation outcomes, and clean-label formulation patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market