
 Malaysia Plastics Market | 2026-2036
Malaysia Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Plastics Market Outlook
Packaging demand from food and beverage processors is hardening across Peninsular Malaysia. Scientex Berhad leverages its blown film extrusion capacity to dominate flexible packaging substrates for regional FMCG brands. LOTTE Chemical Titan Holding Berhad anchors its position through integrated polyolefin production at its Pasir Gudang complex. Behn Meyer Polymers Sdn Bhd specializes in engineering polymer distribution, controlling technical resin flows to automotive tier suppliers.
Plastics comprise synthetic or semi-synthetic organic polymers formulated from petrochemical feedstocks, typically processed via injection molding, extrusion, or blow molding at temperatures between 150°C and 350°C depending on resin grade. These materials serve as lightweight, corrosion-resistant substitutes for metal, glass, and wood across industrial and consumer applications. Polyethylene film and sheet formulations lead volume consumption due to their dominance in food packaging and agricultural mulching, while polypropylene granules represent the fastest-growing form segment driven by automotive interior parts and appliance housings. Polyvinyl chloride maintains mature demand in construction piping and electrical insulation, though margin pools are shifting toward medical-grade formulations for tubing and blood bags.
BIS-equivalent standards through the Department of Standards Malaysia and the Environmental Quality Act administered by the Department of Environment govern product safety and polymer waste management protocols. The Roadmap Towards Zero Single-Use Plastics imposes phased bans on straws and carrier bags, forcing converters to certify compostable alternatives or absorb compliance penalties. Stakeholders must monitor feedstock cost volatility from naphtha cracking economics and decide between importing specialty resins or building local compounding capability.
Market Dynamics
Malaysia's plastics sector faces structural compression from the Roadmap Towards Zero Single-Use Plastics, forcing converters to pivot feedstock choices and extrusion lines toward biodegradable alternatives while maintaining throughput for existing food packaging contracts.
Growth Catalysts
- Food packaging demand:Beverage processors across Peninsular Malaysia are hardening order volumes for flexible film substrates, particularly in the Klang Valley corridor spanning Selangor and Kuala Lumpur.
- Automotive polymer consumption:Polypropylene granules are penetrating interior parts and appliance housings as lightweighting mandates intensify across ASEAN vehicle assembly plants.
- Department of Standards Malaysia certification pathways:BIS-equivalent standards for compostable alternatives are creating compliant product categories that command premium positioning against conventional polyethylene.
Market Restraints
- Naphtha cracking economics:Feedstock cost volatility from regional petrochemical complexes compresses margin pools for independent converters lacking backward integration into monomer production.
- Polyolefin supply concentration:Integrated producers at Pasir Gudang anchor domestic resin availability, creating dependency risk for distributors without multi-source procurement frameworks.
- Technical resin import dependency:Engineering polymers for automotive tier suppliers flow through specialized distributors, exposing converters to currency fluctuation and lead-time extension.
Strategic Opportunities
- Biodegradable formulation white space:The Environmental Quality Act administered by the Department of Environment is redirecting investment toward compostable polymer development for straws and carrier bags.
- Medical-grade PVC pivot:Blood bag and tubing applications offer margin expansion beyond mature construction piping segments, with certification requirements filtering out commodity converters.
- Agricultural mulching film:Polyethylene sheet formulations for Peninsular Malaysia's plantation sector represent underpenetrated volume against food packaging saturation.
Industry Challenges
- Compostable certification timelines:Converters must navigate extended validation periods under Department of Environment protocols while maintaining legacy polyethylene production lines.
- Extrusion line reconfiguration:Temperature control systems require capital deployment to process biodegradable resins at modified thermal profiles distinct from conventional polyolefin ranges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Plastics Market |
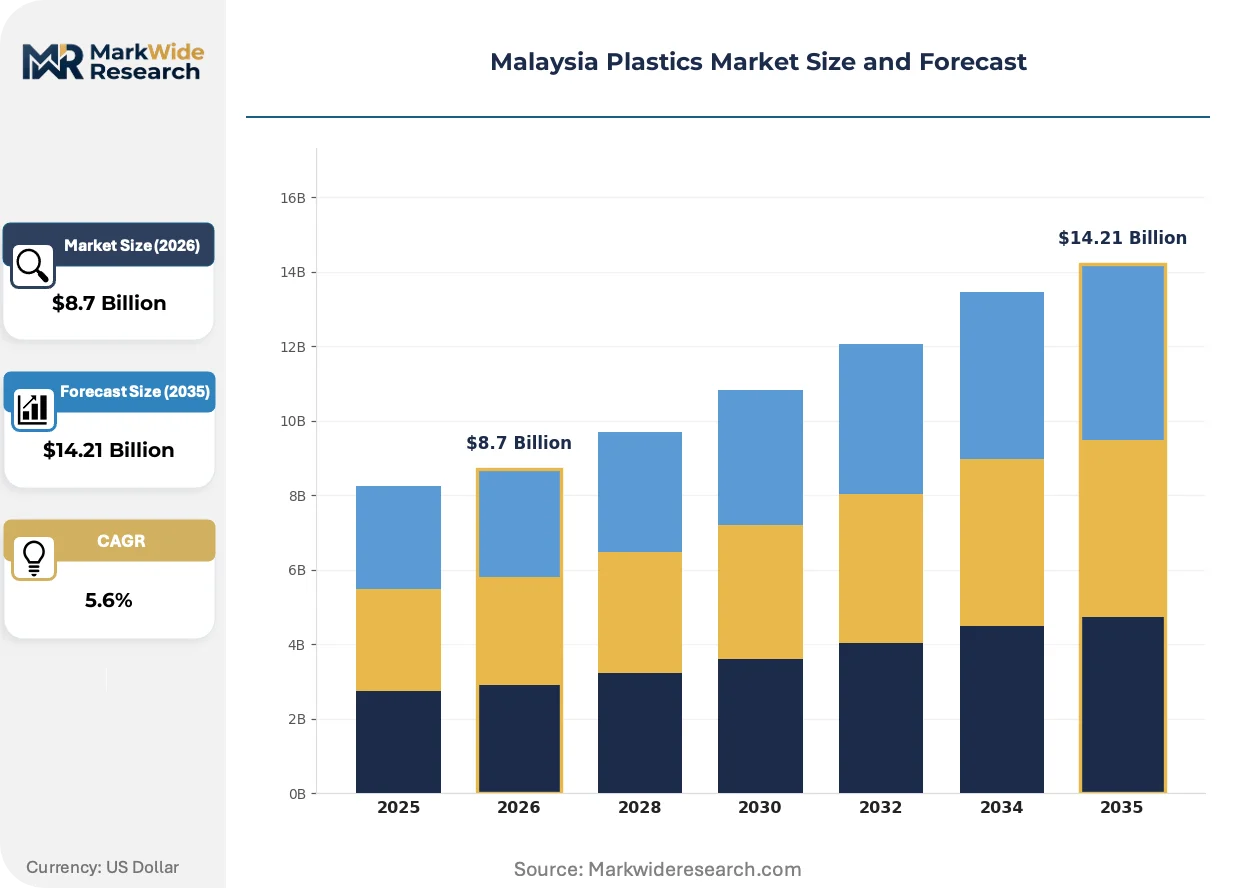
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Packaging, Automotive Parts, Consumer Goods, Construction Form: Film, Sheet, Rod, Granules Application: Medical Supplies, Home Appliances, Electrical Insulation, Toys |
| Companies Covered | Polyplastics Asia Pacific Sdn Bhd, Behn Meyer Polymers Sdn Bhd, Scientex Berhad, SLP Resources Berhad, BASF Sdn Bhd, LOTTE Chemical Titan Holding Berhad, Toray Plastics Sdn Bhd, Malayan Electro-Chemical Industry Co Sdn Bhd, BP Plastics Holding Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Plastics Market Strategic Shifts
Malaysian plastics manufacturing is absorbing simultaneous pressures from regulatory phase-outs and material science advances, with extrusion technology and feedstock chemistry converging to redefine converter competitiveness.
Biodegradable polymer formulations are absorbing capital allocation from conventional blown film extruders as converters retool for compostable substrate production. Food and beverage processors in Selangor and Kuala Lumpur are qualifying these alternatives under Roadmap compliance deadlines. The structural consequence is absorbing technical staff toward formulation chemistry and away from traditional process engineering.
The Roadmap Towards Zero Single-Use Plastics imposes phased bans on straws and carrier bags through the Department of Environment. This regulatory architecture forces extrusion houses to certify compostable alternatives or absorb compliance penalties. Flexible packaging converters serving FMCG brands face the most compressed transition timelines.
Buyer concentration among Klang Valley food processors is compressing supplier qualification cycles and unbundling after-sales technical support from resin supply contracts. Distributors like Behn Meyer Polymers are responding with embedded application engineering teams. This pattern is most visible in automotive tier supply chains where engineering polymer specification demands intensive joint development.
Malaysia Plastics Market Segmentation
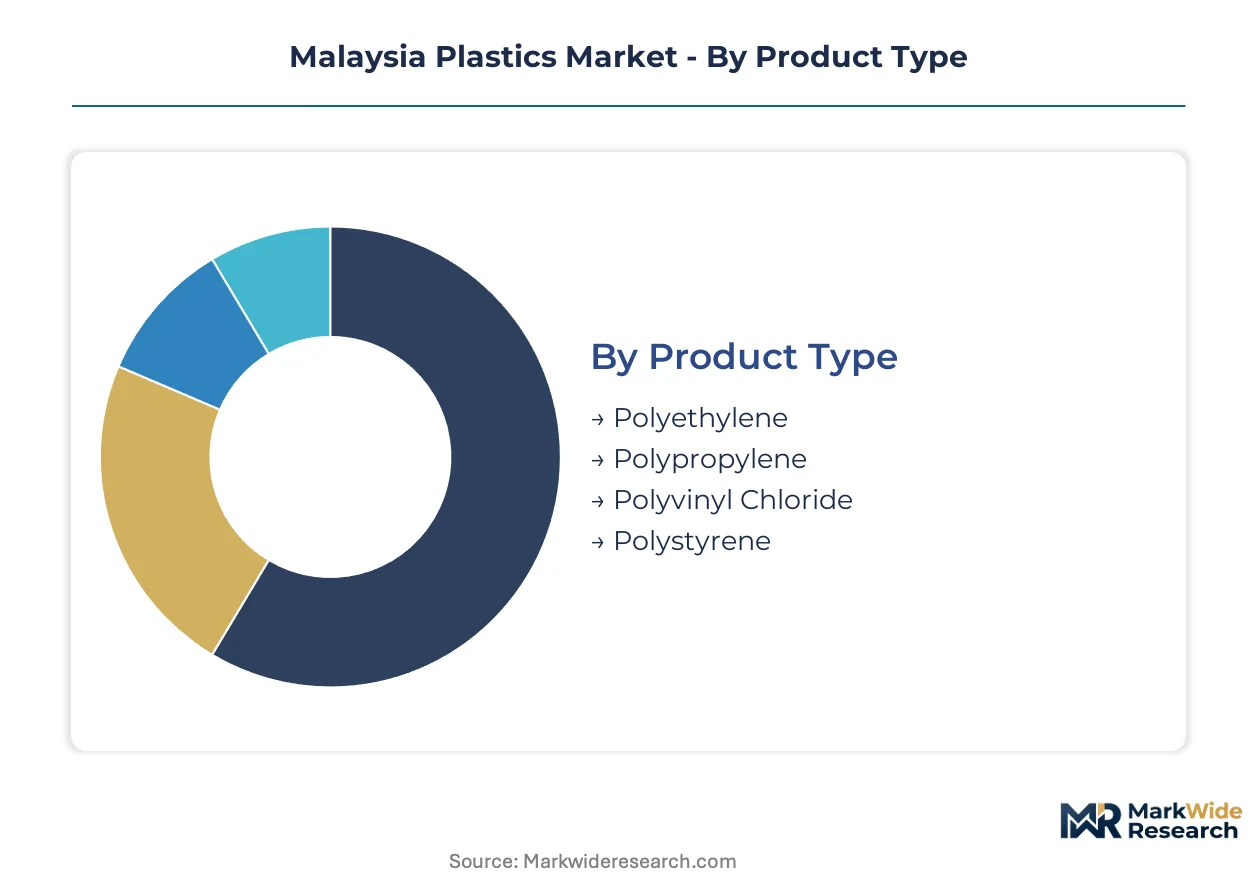
Malaysia's plastics market segments reflect divergent compliance burdens under the Roadmap Towards Zero Single-Use Plastics. Each category demands distinct certification pathways from the Department of Standards Malaysia and the Department of Environment, reshaping converter investment priorities across resin grades and end-use applications.
Product Type:
Polyethylene and polypropylene formulations require BIS-equivalent compostable certification for food-contact applications, while polyvinyl chloride faces medical-grade validation for tubing segments. Polystyrene encounters the stiffest phase-out timelines under carrier bag prohibitions.
- Polyethylene:Blown film extrusion dominates flexible packaging substrates for Klang Valley beverage processors. Selangor converters are hardening order volumes despite Roadmap pressure to certify compostable alternatives or absorb compliance penalties.
- Polypropylene:Automotive interior parts and appliance housings in Peninsular Malaysia absorb granule formulations as lightweighting mandates intensify across ASEAN assembly plants. Pasir Gudang polyolefin complexes anchor domestic resin availability.
- Polyvinyl Chloride:Medical-grade tubing and blood bag specifications offer margin expansion beyond mature construction piping, with Department of Standards Malaysia certification filtering out commodity converters.
- Polystyrene:Rigid foam and disposable food service applications face accelerated phase-out under Environmental Quality Act enforcement, forcing rapid formulation pivots.
Polyethylene sits at the top of the volume ranking, with polypropylene climbing the fastest.
End User:
Packaging converters bear the heaviest certification load for compostable alternatives, while automotive tier suppliers demand intensive joint development for engineering polymer specifications. Construction and consumer goods segments split between commodity resins and technical grades.
- Packaging:Flexible film demand from food and beverage processors across Selangor and Kuala Lumpur concentrates procurement power. FMCG brands compress supplier qualification cycles while unbundling after-sales technical support from resin contracts.
- Automotive Parts:Engineering polymer distribution flows through specialized distributors like Behn Meyer Polymers, exposing converters to currency fluctuation and lead-time extension for technical resin imports.
- Consumer Goods:Appliance housings absorb polypropylene granules as regional manufacturing shifts toward Peninsular Malaysia production bases.
- Construction:PVC piping maintains mature demand though margin pools are compressing under feedstock volatility from naphtha cracking economics.
Packaging commands the dominant revenue share, with automotive parts expanding most quickly on lightweighting mandates.
Form:
Film and sheet formats absorb capital reallocation toward biodegradable extrusion lines, while granule processing requires less thermal modification. Rod formats serve niche industrial applications with minimal regulatory exposure.
- Film:Blown film extruders at Scientex Berhad and regional converters retool for compostable substrate production, absorbing technical staff toward formulation chemistry.
- Sheet:Thermoforming applications for food trays and medical packaging require modified temperature control systems to process biodegradable resins at thermal profiles distinct from conventional polyolefin ranges.
- Rod:Machined components for industrial equipment represent stable demand with limited Roadmap compliance exposure.
- Granules:Injection molding feedstock for automotive and appliance segments benefits from established polyolefin supply chains at integrated Pasir Gudang complexes.
Film leads form-specific volume, with sheet gaining share fastest on food packaging qualification timelines.
Application:
Medical supplies demand the most stringent certification pathways, while home appliances and electrical insulation serve volume markets with established specifications. Toys face evolving safety standards alongside material substitution pressures.
- Medical Supplies:Blood bag and tubing applications command premium positioning beyond commodity segments, with Department of Environment protocols and Department of Standards Malaysia medical-grade validation creating entry barriers.
- Home Appliances:Polypropylene housings for washing machines and refrigerators absorb regional manufacturing shifts, with appliance brands qualifying Malaysian converters for ASEAN supply contracts.
- Electrical Insulation:PVC formulations for wire and cable maintain steady demand from construction and infrastructure projects across Peninsular Malaysia.
- Toys:Safety standards and phthalate restrictions under consumer protection frameworks are redirecting formulation choices toward compliant polymer grades.
Home appliances anchor application volume, with medical supplies recording the steepest expansion trajectory on certification-filtered margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity across Southeast Asian plastics markets is shifting as Malaysia's Roadmap Towards Zero Single-Use Plastics raises compliance costs, redirecting some flexible packaging investment toward jurisdictions with extended transition timelines.
Indonesia
Food and beverage processors in Java are absorbing capacity from converters exiting Malaysia's stricter certification environment. The Ministry of Environment and Forestry maintains slower phase-out schedules for single-use plastics. Jakarta and Surabaya industrial corridors attract blown film extrusion investment from regional FMCG suppliers.
Thailand
Automotive polymer demand from Rayong and Chonburi assembly plants is accelerating polypropylene granule consumption. The Thailand Board of Investment offers tax incentives for bioplastic production under its Bio-Circular-Green economy model. Eastern Economic Corridor chemical complexes expand compounding capacity for ASEAN vehicle lightweighting programs.
Vietnam
Export-oriented packaging converters in Binh Duong and Dong Nai provinces benefit from EU trade preferences while avoiding Malaysia's compostable certification requirements. The Ministry of Natural Resources and Environment has delayed nationwide single-use plastic bans until 2026. Ho Chi Minh City logistics hubs concentrate flexible film distribution for European retail chains.
Singapore
Specialty resin trading and technical polymer distribution anchor Singapore's role despite negligible domestic manufacturing. The National Environment Agency enforces strict waste reduction targets without mandating biodegradable alternatives. Jurong Island petrochemical infrastructure supports regional feedstock arbitrage for Malaysian converters.
Philippines
Extended producer responsibility legislation under the Extended Producer Responsibility Act of 2022 lags Malaysia's implementation timeline, preserving conventional polyethylene demand. Cavite and Laguna industrial zones attract packaging investment from brands seeking supply chain continuity. Metro Manila beverage processors maintain rigid plastic bottle specifications without compostable mandates.
Malaysia Plastics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated resin producers commanding polyolefin supply chains while independent converters compete on formulation agility. The Malaysian market exhibits moderate concentration at the resin production tier and fragmentation among extrusion houses serving food packaging. Three archetypes dominate: backward-integrated petrochemical complexes controlling feedstock economics, flexible packaging specialists with blown film scale, and technical polymer distributors bridging engineering resin imports. Capacity expansion and portfolio diversification toward biodegradable alternatives represent the dominant competitive vectors as Roadmap compliance deadlines approach.
Among integrated producers, LOTTE Chemical Titan Holding Berhad anchors polyolefin availability through its Pasir Gudang manufacturing position. Scientex Berhad exemplifies the flexible packaging specialist archetype with regional FMCG supply relationships. Behn Meyer Polymers Sdn Bhd occupies the technical distribution tier, managing engineering polymer flows to automotive and industrial accounts.
| Leading Market Players |
|---|
| Polyplastics Asia Pacific Sdn Bhd |
| Behn Meyer Polymers Sdn Bhd |
| Scientex Berhad |
| SLP Resources Berhad |
| BASF Sdn Bhd |
| LOTTE Chemical Titan Holding Berhad |
| Toray Plastics Sdn Bhd |
| Malayan Electro-Chemical Industry Co Sdn Bhd |
| BP Plastics Holding Bhd |
| Others |
Value Chain & Pricing Dynamics
The Roadmap Towards Zero Single-Use Plastics gates qualified supply access and premium-tier pricing power for Malaysian converters, with Department of Environment compostable certification separating certified biodegradable substrate producers from commodity polyethylene suppliers facing margin compression.
Pricing Analysis
Distributor margin layers stratify across three tiers: direct-to-OEM polyolefin contracts command volume discounts from Pasir Gudang integrated producers, while independent converters absorb naphtha cracking cost volatility without backward integration. Price differentiation rests on certification grade under Department of Standards Malaysia protocols and geographic delivery cost to Klang Valley food processors. Pricing pressure intensifies in commodity polyethylene as Indonesian and Vietnamese converters capture FMCG brand volume with lower compliance burdens. Automotive tier suppliers exhibit lowest price sensitivity due to engineering polymer specification lock-in, while flexible packaging buyers for beverage processors negotiate aggressively on resin pass-through terms.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs and multinational FMCG brands mandate multi-supplier qualification for engineering polymers and food-contact films, forcing distributors like Behn Meyer Polymers to maintain parallel technical resin pipelines. Geographic supply concentrates in South Korea, Japan, and Singapore for specialty polyolefin grades and compounded engineering resins. Raw material dependencies center on naphtha feedstock from regional petrochemical complexes, imported masterbatch additives, and biodegradable polymer formulations from Thai and Indonesian compounders. Single-source vulnerability runs through LOTTE Chemical Titan's Pasir Gudang polyolefin monopoly for domestic base resin. Distribution runs through Klang Valley logistics hubs serving Selangor and Kuala Lumpur converters, with secondary flows reaching Peninsular Malaysia plantation and automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Malaysia Plastics Market functions as a regulatory compounder where Roadmap compliance deadlines force capital reallocation toward certified biodegradable capacity, creating demand inflection for compostable substrate producers ahead of carrier bag and straw prohibition phases.
For Market Incumbents: Anchor backward integration into naphtha cracking or secure long-term offtake agreements with Pasir Gudang producers to defend margin position against feedstock volatility. Incumbent flexible packaging specialists must accelerate extrusion line reconfiguration for biodegradable thermal profiles before Department of Environment certification bottlenecks intensify, while embedding application engineering teams to unbundle technical support from commodity resin supply contracts facing price erosion.
For New Entrants and Emerging Players: Agricultural mulching film buyers across Peninsular Malaysia plantations represent an underserved buyer archetype with limited Roadmap compliance exposure and unconsolidated supplier relationships. New entrants should target medical-grade PVC tubing qualification for blood bag applications, where Department of Standards Malaysia certification filters out commodity competition and commands premium positioning. Joint development partnerships with Selangor-based automotive tier suppliers offer qualification pathways for engineering polymer distribution without integrated resin production assets.
For Investors and Strategic Acquirers: Roll-up economics work for technical polymer distributors because engineering resin import dependency fragments procurement leverage across Malaysian automotive and industrial accounts. Five-to-ten year viability favors platforms consolidating compounding capability for biodegradable formulations ahead of Roadmap phase-out acceleration. Acquisition targets should exhibit embedded application engineering teams and multi-source procurement frameworks. The signal to watch is Department of Environment certification queue length for compostable alternatives, which indicates converter transition velocity and premium capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Pasir Gudang integrated producers capture margin pools denied to independent converters facing feedstock volatility. |
| Biodegradable Formulation Certification | Department of Environment compostable validation opens premium positioning against conventional polyethylene facing phase-out penalties. |
| Medical-Grade PVC Pivot | Department of Standards Malaysia tubing certification filters commodity competition for blood bag applications with margin expansion potential. |
| Application Engineering Embedding | Behn Meyer Polymers demonstrates how technical staff integration unbundles support from resin contracts for automotive tier supply chains. |
| Agricultural Mulching Film Expansion | Peninsular Malaysia plantation sector offers underpenetrated volume against saturated Klang Valley food packaging procurement concentration. |
Study Parameters
Direct dialogue with extrusion plant managers, procurement leads at Klang Valley food and beverage processors, technical R&D directors at compounders, and distribution channel partners grounded qualitative findings. Secondary validation drew from Department of Standards Malaysia certification records, Department of Environment compliance filings, customs and trade data for resin imports, and SEC disclosures from listed petrochemical producers. Bottom-up triangulation across converter capacity assessments and top-down reconciliation against national polymer consumption estimates ensured cross-verified volume and value outputs.
Bottom-up modeling segmented the market across resin grade tiers, end-use industries from packaging to automotive, geographic production clusters centered on Selangor and Pasir Gudang, and form factors from film to granules. CAGRs were derived from regression analysis of historical consumption patterns and projected Roadmap compliance-driven substitution rates. Industry-specific forecast inputs included naphtha cracking margin forecasts from regional petrochemical complexes and biodegradable polymer formulation adoption curves tied to certification queue data.
Underlying measurement precision varies by segment; polyethylene film consumption for flexible packaging carries tighter precision through established converter relationships than emerging biodegradable substrate volumes. Forecasts reflect assumptions regarding Roadmap enforcement consistency, naphtha price trajectory stability, and ASEAN automotive lightweighting program continuity. Deviation in Department of Environment certification timeline acceleration or Indonesian regulatory relaxation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
South-East Asia (SEA) Plastics Market