
 North America Recycled Plastics Market | 2026-2036
North America Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Recycled Plastics Market Intelligence
Post-industrial collection networks across the Midwest and Southeast are reshaping how resin flows into compounding operations. WM Recycle America LLC leverages its integrated hauling and sorting infrastructure to control feedstock access across major metropolitan corridors. KW Plastics anchors high-volume polypropylene reprocessing through proprietary washing and extrusion systems in the southeastern United States. Green Line Polymers specializes in custom-compounded recycled polyethylene for film and sheet applications, differentiating through formulation precision rather than commodity scale.
Recycled plastics encompass post-consumer and post-industrial polymer streams that undergo sorting, washing, size reduction, and re-extrusion to achieve melt flow indices and contamination thresholds suitable for re-manufacturing. These materials substitute virgin resin in applications where performance specifications permit reduced mechanical properties or where aesthetic uniformity is secondary to cost and sustainability targets. Polyethylene dominates volume flows due to its prevalence in packaging films and rigid containers, though polypropylene commands margin premiums in automotive underhood components and durable consumer goods. Pellet form leads processing efficiency for injection molding operations, while flakes retain cost advantages in blow molding and extrusion lines where in-house re-pelletizing integrates with existing equipment.
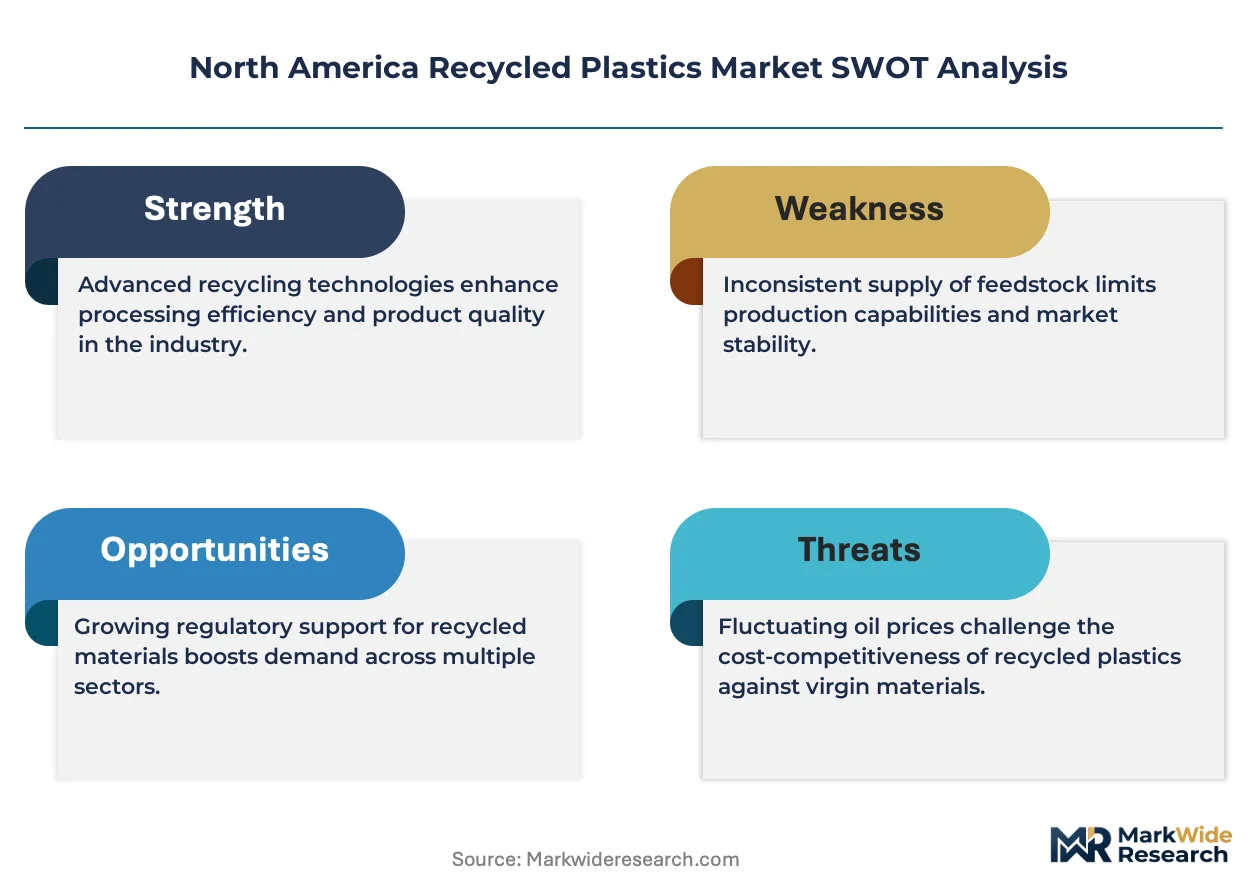
The EPA administers recycled content guidelines under the National Recycling Strategy, while state-level extended producer responsibility frameworks in California, Oregon, and Maine mandate minimum post-consumer resin thresholds in packaging. FDA food-contact certifications for recycled polymers constrain which feedstocks qualify for beverage and food packaging applications, creating a dual-track market between food-grade and non-food-grade resin pools. Stakeholders must monitor how chemical recycling regulatory pathways develop under individual state environmental agency frameworks, as pyrolysis and depolymerization outputs seek alignment with existing mechanical recycling standards or carve out separate classification systems.
Market Dynamics
The EPA's National Recycling Strategy is compressing virgin resin economics by mandating post-consumer content thresholds across packaging supply chains. State-level extended producer responsibility frameworks in California, Oregon, and Maine are forcing brand owners to secure certified recycled feedstocks or face compliance penalties.
Growth Catalysts
- Mechanical recycling infrastructure:New sorting and washing capacity in the Great Lakes corridor is unlocking previously contaminated feedstock streams for food-grade applications.
- California's SB 54 mandate:The state's plastic pollution reduction law requires 30% recycled content in single-use packaging by 2028, pulling resin demand forward.
- Automotive lightweighting:Underhood polypropylene components in electric vehicles are specifying post-industrial recycled grades to meet sustainability targets without sacrificing thermal performance.
Market Restraints
- Natural gas price volatility:Fluctuating feedstock costs for virgin polyethylene production create pricing instability that undercuts recycled resin premiums during low-cycle periods.
- Midwest collection concentration:Post-industrial scrap generation clusters in Michigan, Ohio, and Indiana, leaving southeastern and western compounders dependent on long-haul logistics.
- FDA food-contact certification timelines:Letter of no objection approvals for post-consumer resin in beverage packaging stretch 18-24 months, blocking rapid market entry.
Strategic Opportunities
- Chemical recycling regulatory clarity:Pyrolysis and depolymerization outputs in Texas and Louisiana seek alignment with existing mechanical recycling standards or separate classification under state environmental agency frameworks.
- Mexico manufacturing integration:Nearshoring of automotive and appliance production to Baja California and Nuevo León creates demand for cross-border recycled resin supply chains.
- Film-to-film closed loops:Agricultural stretch film and retail bag collection programs in the Corn Belt are enabling circular polyethylene streams with traceable chain-of-custody documentation.
Industry Challenges
- Polymer identification technician shortage:Near-infrared spectroscopy and robotic sorting operations require skilled operators that recycling facilities struggle to recruit in rural Midwest labor markets.
- Legacy ERP integration:Batch-level traceability systems for post-consumer resin conflict with existing manufacturing execution software in injection molding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Recycled Plastics Market |
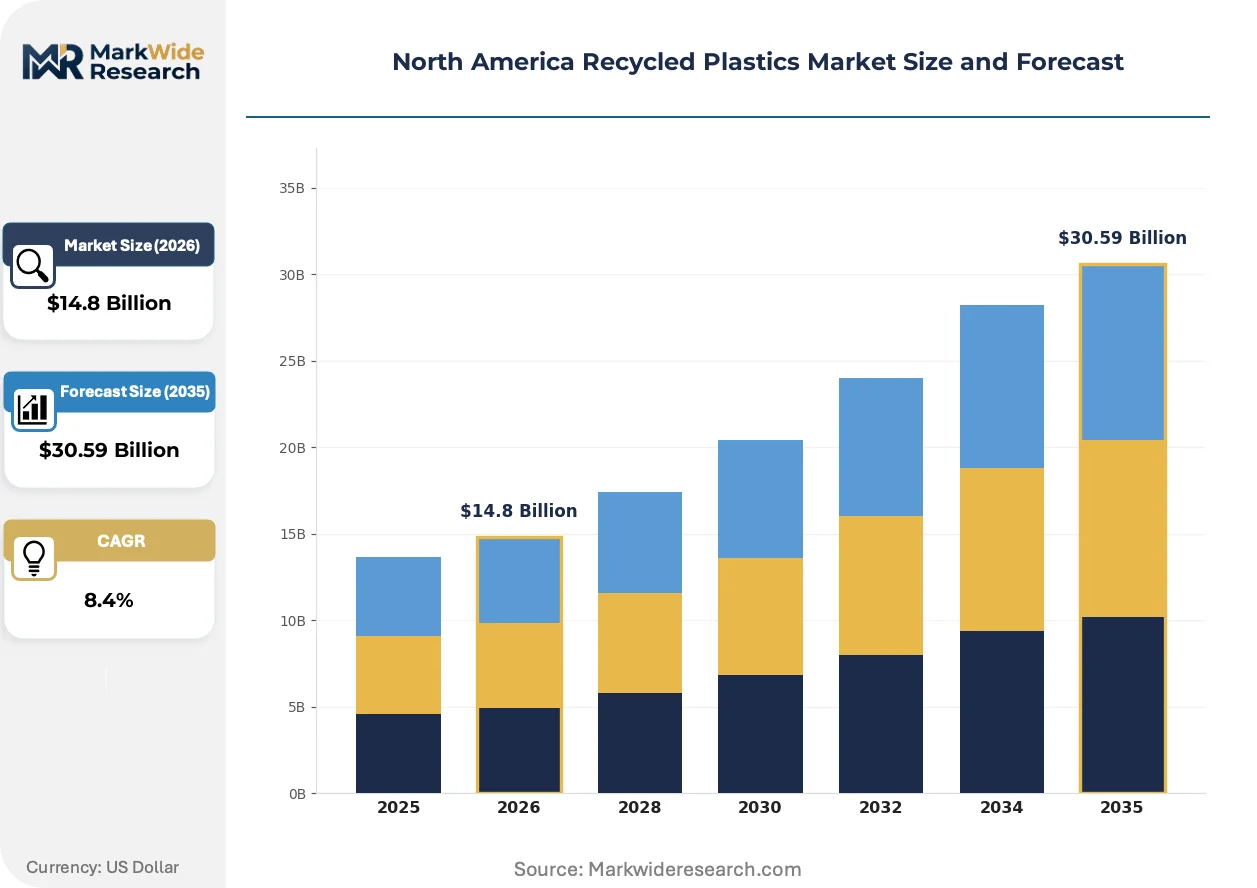
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride End User: Building & Construction, Automotive, Consumer Goods, Packaging Form: Flakes, Pellets, Sheets, Granules Application: Injection Molding, Blow Molding, Extrusion, Coating |
| Companies Covered | Green Line Polymers, B. Schoenberg & Co., Inc., KW Plastics, Clean Tech Inc., Plastics Recycling Inc., Merlin Plastics Supply Inc., WM Recycle America LLC, CarbonLite Industries, Envision Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Recycled Plastics Market Strategic Shifts & Innovations
Processing technology is compressing quality variance between post-consumer and virgin resin grades. Regulatory pressure on packaging producers is forcing rapid adoption of certification systems. Buyer procurement models are pivoting from spot-market purchasing toward long-term offtake agreements with traceability requirements.
Advanced optical sorting systems are migrating from pilot installations to production-scale deployment across material recovery facilities. Food and beverage packagers in the Northeast are adopting these systems to secure FDA-certified polyethylene terephthalate streams. The technology is migrating from niche high-value applications to commodity-scale polypropylene sorting, enabling broader substitution in durable goods manufacturing.
The EPA's National Recycling Strategy is establishing recycled content benchmarks that cascade into state procurement rules. Packaging producers must now document post-consumer percentages across their entire product portfolios. California, Oregon, and Maine are responding by accelerating their extended producer responsibility implementation timelines ahead of federal guidance.
Brand owner purchasing is consolidating around multi-year resin offtake contracts with third-party certification requirements. Spot-market buying for recycled polyethylene is contracting as CPG companies secure volume guarantees to meet 2025-2028 compliance deadlines. This pattern is most visible in the Great Lakes manufacturing corridor where automotive and packaging buyers compete for limited food-grade polypropylene supply.
North America Recycled Plastics Market Segmentation
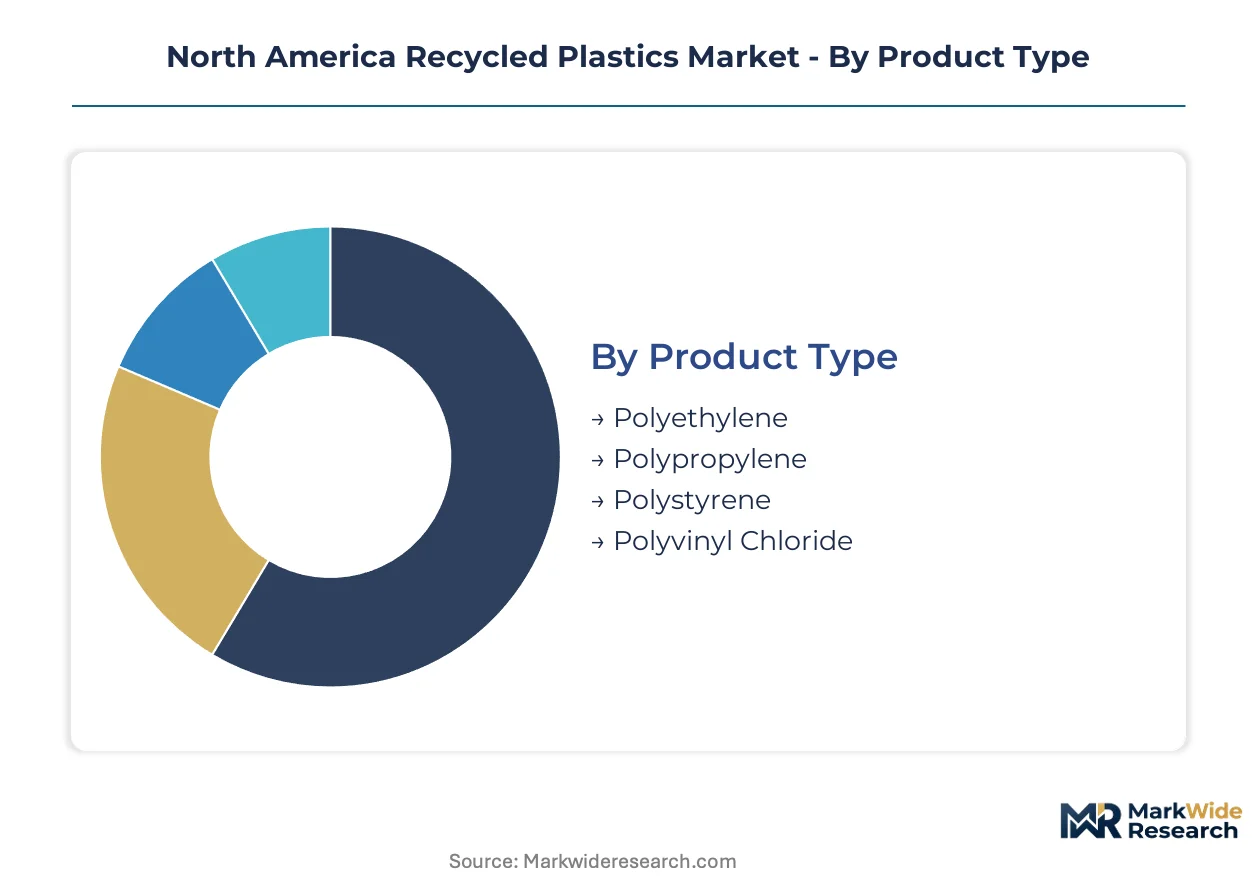
Segmentation in the North America Recycled Plastics Market reveals how resin specifications, processing requirements, and regulatory compliance create distinct commercial channels. Buyers select grades based on melt flow indices, contamination thresholds, and end-use performance demands rather than commodity pricing alone.
Product Type:
After-sales service intensity varies sharply across polymer categories, with food-grade certifications and technical support requirements driving supplier differentiation.
- Polyethylene:Post-consumer and post-industrial streams from packaging films and rigid containers dominate volume flows. Demand concentrates in the Great Lakes corridor where beverage bottlers and film extruders seek FDA-certified high-density grades for food-contact applications under EPA National Recycling Strategy benchmarks.
- Polypropylene:Automotive underhood components and durable consumer goods command margin premiums due to thermal performance requirements. Michigan and Ohio compounders specify post-industrial recycled grades for electric vehicle lightweighting targets without sacrificing heat resistance.
- Polystyrene:Construction insulation and protective packaging applications utilize expanded and extruded forms with lower mechanical property requirements.
- Polyvinyl Chloride:Building products and piping applications leverage rigid scrap streams with established collection networks in the southeastern United States.
Polyethylene holds the largest share; momentum sits with polypropylene.
End User:
Application-specific certification requirements segment buyers by compliance burden and volume scale.
- Packaging:California SB 54 mandates pull 30% recycled content thresholds into single-use packaging by 2028. Brand owners in the Northeast are locking multi-year offtake agreements with traceability documentation to secure polyethylene terephthalate and polypropylene supply ahead of compliance deadlines.
- Automotive:Electric vehicle manufacturers in Michigan and Ontario specify post-industrial recycled polypropylene for underhood components to meet sustainability targets while maintaining thermal performance. Tier 1 suppliers integrate batch-level traceability systems with existing manufacturing execution software.
- Building & Construction:PVC piping and polyethylene drainage systems utilize lower-grade recycled streams where aesthetic uniformity is secondary to cost and durability.
- Consumer Goods:Durable products and appliances incorporate recycled resins where mechanical specifications permit reduced properties or where sustainability labeling drives purchasing decisions.
Packaging commands the deepest supplier relationships; automotive is expanding most quickly.
Form:
Processing efficiency and equipment integration determine form selection across manufacturing operations.
- Pellets:Standardized melt flow indices and contamination controls enable direct injection molding integration. Great Lakes compounders prefer pellets for high-volume automotive and packaging production where consistency minimizes downtime.
- Flakes:Cost advantages persist in blow molding and extrusion lines where in-house re-pelletizing integrates with existing equipment. Agricultural stretch film processors in the Corn Belt utilize flake-to-film closed loops with chain-of-custody documentation.
- Sheets:Thermoforming operations for retail and food service packaging specify calibrated thickness and clarity grades.
- Granules:Intermediate sizing serves specialty compounding operations requiring custom formulation precision rather than commodity scale.
Pellets hold the largest share; flakes are gaining share fastest in regional processing hubs.
Application:
Processing technology compatibility segments demand by equipment investment and quality tolerance.
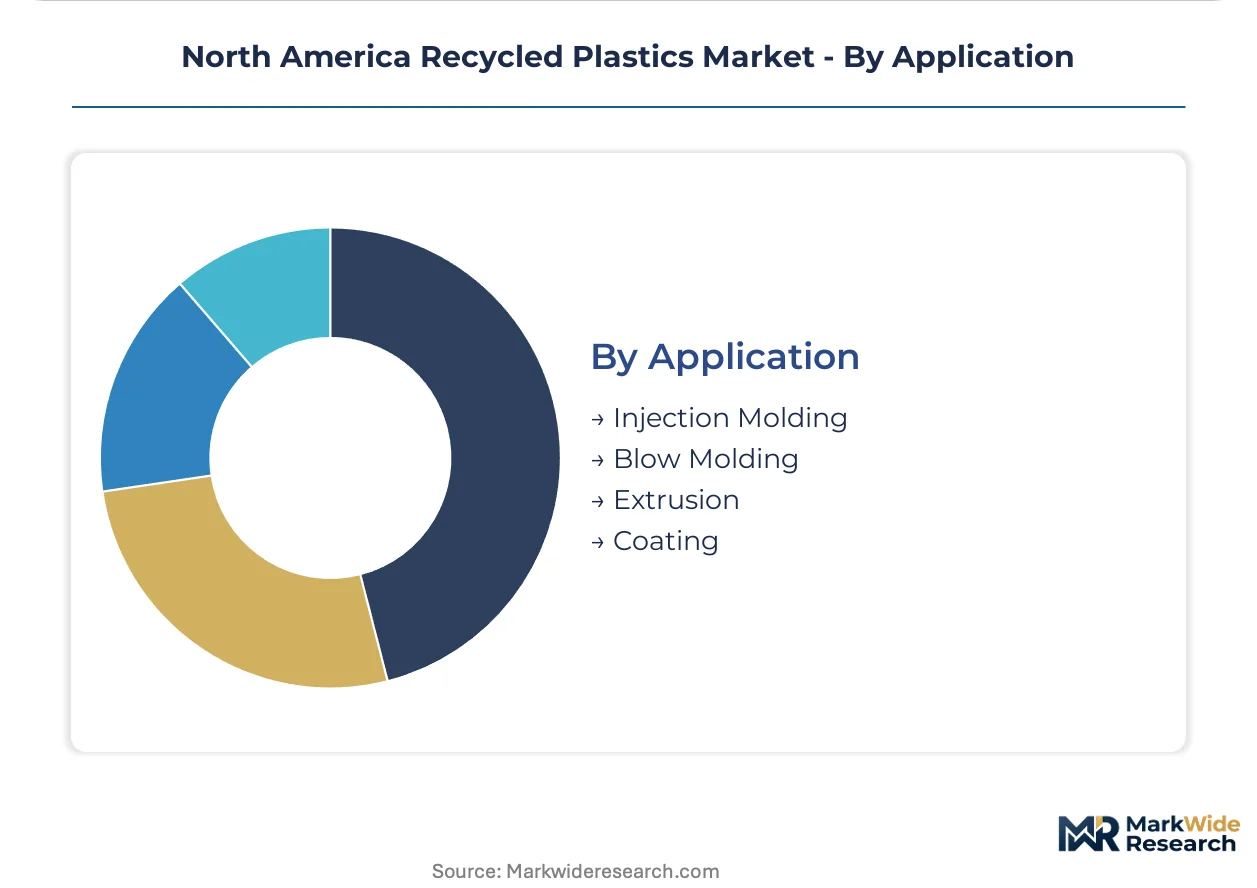
- Injection Molding:Pelletized resins with tight melt flow variance enable high-cavity tooling for automotive and consumer goods. Michigan and Ohio molders specify post-industrial polypropylene grades for electric vehicle component production.
- Blow Molding:Bottle and container production favors high-density polyethylene with controlled moisture content. FDA food-contact certifications constrain which post-consumer feedstocks qualify for beverage packaging applications.
- Extrusion:Film, sheet, and profile lines integrate flake or pellet feedstocks depending on in-house reprocessing capabilities. Green Line Polymers differentiates through custom-compounded recycled polyethylene formulation precision.
- Coating:Lower-volume applications utilize recycled resin streams where performance specifications permit higher contamination thresholds.
Injection molding holds the largest share; blow molding shows the steepest expansion trajectory under packaging compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes corridor commands pricing leverage over southeastern compounders due to concentrated post-industrial scrap generation and integrated sorting infrastructure. California's regulatory mandates pull resin demand forward, creating a coastal premium distinct from Midwest supply economics.
United States
California's SB 54 mandate requires 30% recycled content in single-use packaging by 2028, forcing brand owners to lock multi-year offtake agreements. The EPA's National Recycling Strategy establishes benchmarks that cascade into state procurement rules. Michigan and Ohio anchor automotive demand as electric vehicle manufacturers specify post-industrial recycled polypropylene for underhood components.
Canada
Ontario's manufacturing corridor competes with US Great Lakes buyers for limited food-grade polypropylene supply. Health Canada and the Canadian Food Inspection Agency administer food-contact certifications that align with FDA timelines but maintain separate approval pathways. Toronto-Windsor industrial clusters concentrate film extrusion and blow molding operations serving beverage packaging demand.
Mexico
Nearshoring of automotive and appliance production to Baja California and Nuevo León generates cross-border recycled resin demand. Mexico's environmental regulator SEMARNAT develops extended producer responsibility frameworks that lag California implementation by 3-5 years. Querétaro and Guanajuato emerging manufacturing hubs seek traceable polyethylene supply chains for export-oriented packaging.
Regional Supply Dynamics
The Corn Belt's agricultural stretch film collection programs enable circular polyethylene streams with chain-of-custody documentation. Texas and Louisiana chemical recycling facilities seek regulatory clarity on pyrolysis output classification under state environmental agency frameworks. Southeastern compounders in Georgia and the Carolinas absorb logistics premiums to access Midwest post-industrial scrap.
North America Recycled Plastics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling feedstock access and formulation precision. The market structures around three tiers: integrated waste management platforms with hauling and sorting infrastructure, high-volume mechanical reprocessors with proprietary washing systems, and custom compounders differentiating through technical service. Consolidation pressures concentrate among mid-scale reprocessors lacking either backward integration into collection or forward integration into compounding. Capacity expansion and strategic partnerships dominate competitive moves as players secure volume guarantees ahead of 2025-2028 compliance deadlines.
Within the integrated platform tier, WM Recycle America LLC leverages captive hauling infrastructure to control metropolitan feedstock corridors. KW Plastics anchors high-volume polypropylene reprocessing through southeastern US operations. Green Line Polymers occupies the custom compounding position, specializing in formulation precision for film and sheet applications rather than commodity scale. These three represent distinct archetypes: waste-to-resin integration, volume-scale mechanical recycling, and technical differentiation.
| Leading Market Players |
|---|
| Green Line Polymers |
| B. Schoenberg & Co., Inc. |
| KW Plastics |
| Clean Tech Inc. |
| Plastics Recycling Inc. |
| Merlin Plastics Supply Inc. |
| WM Recycle America LLC |
| CarbonLite Industries |
| Envision Plastics |
| Others |
Cost & Logistics Intelligence
Great Lakes rail corridors from Chicago to Detroit absorb logistics premiums that compound price differentiation between food-grade compounders and commodity reprocessors. California's SB 54 compliance deadlines pull coastal buyers into long-term offtake contracts at 15-20% premiums over spot polyethylene, while Midwest automotive molders leverage proximity to post-industrial scrap generation for cost-stable polypropylene supply.
Pricing Analysis
The customization-premium spread between FDA-certified food-grade resin and standard industrial grades runs 25-35% across the Great Lakes corridor. Contract-based long-term offtake agreements dominate as California, Oregon, and Maine extended producer responsibility frameworks force brand owners to secure volume guarantees. Price differentiation rests on certification tier and geographic delivery cost, with coastal compounders absorbing rail freight from Midwest scrap concentration. Cost compression in non-food-grade polyethylene is intensifying because virgin resin pricing tracks volatile natural gas feedstocks. Tier 1 automotive suppliers show least price sensitivity due to sustainability-linked procurement mandates, while commodity film extruders remain most exposed to spot-market volatility.
Supply Chain Analysis
Tariff exposure between the United States and Canada disrupts cross-border polyethylene terephthalate flows through Ontario-Toronto manufacturing clusters. Geographic supply concentrates in the United States, Canada, and emerging Mexican processing hubs near Querétaro. Raw material dependencies center on post-consumer bale supply from municipal collection systems, post-industrial scrap from automotive stamping operations, and agricultural film retrieval programs across the Corn Belt. Single-source vulnerability pervades FDA-certified food-grade polypropylene, where limited reprocessors control washing and extrusion capacity. Distribution runs through integrated waste management platforms with captive hauling infrastructure, compounders with direct OEM relationships, and regional distributors serving smaller injection molding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation customization and FDA certification support expand faster than commodity resin tonnage, creating recurring revenue layers that compound customer lifetime value. Compounders bundling traceability documentation with pellet supply capture margin premiums unavailable to spot-market sellers.
For Market Incumbents: Pre-empt capacity constraints in food-grade polypropylene by securing exclusive bale supply agreements with Great Lakes material recovery facilities. Chemical recycling entrants threaten mechanical reprocessors with regulatory pathway advantages; backward integration into collection infrastructure defends feedstock access against pyrolysis competitors scaling in Texas and Louisiana. Invest in near-infrared spectroscopy technician training programs to resolve operational bottlenecks constraining sorting throughput. For New Entrants and Emerging Players: Pursue agricultural stretch film closed-loop programs in Iowa, Illinois, and Indiana where traceable chain-of-custody documentation commands buyer premiums. Mexico's nearshoring automotive expansion offers the most penetrable geography, with SEMARNAT regulatory frameworks lagging California implementation. Lead with flake-to-pellet toll processing services that integrate with existing Corn Belt extrusion equipment rather than competing for capital-intensive compounding scale. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated waste management platforms seeking to monetize non-core resin processing assets. Five-to-ten-year viability favors compounders with proprietary washing systems and established FDA letter-of-no objection portfolios over commodity reprocessors lacking certification depth. Monitor EPA chemical recycling guidance development as the inflection signal separating mechanical recycling margin compression from regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | WM Recycle America LLC's captive hauling networks demonstrate feedstock control advantages over non-integrated compounders. |
| FDA Food-Contact Certification Investment | Letter-of-no-objection approvals unlock 25-35% pricing premiums in beverage packaging under California SB 54 mandates. |
| Long-term Resin Offtake Agreements | Multi-year contracts with traceability documentation secure volume guarantees ahead of 2025-2028 compliance deadlines. |
| Chemical Recycling Regulatory Alignment | Pyrolysis output classification under state environmental agency frameworks determines competitive parity with mechanical recycling. |
| Mexico Manufacturing Integration | Cross-border supply chains to Baja California and Nuevo León automotive plants expand addressable demand beyond US Great Lakes concentration. |
Research Approach
A standing panel of resin procurement directors at Tier 1 automotive suppliers, beverage packaging brand managers, material recovery facility operations heads, and FDA regulatory affairs consultants provided ongoing calibration across the study period. Primary interviews with compounder technical service teams and secondary validation against EPA National Recycling Strategy implementation documents, state extended producer responsibility filings, and American Chemistry Council trade flow data established demand-side triangulation. Bottom-up volume estimates from individual reprocessor capacity expansions reconciled with top-down resin consumption projections across packaging, automotive, and construction end-uses.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning polymer type, form factor, end-use industry, and geographic manufacturing cluster. CAGRs derived from regression analysis against historical resin pricing spreads, virgin polyethylene cost curves, and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated California SB 54 implementation pacing, electric vehicle production ramp rates in Michigan and Ontario, and chemical recycling facility commissioning schedules in Texas and Louisiana.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, freight rail rates, or extended producer responsibility penalty structures would shift the trajectory. Forecasts reflect documented assumptions regarding FDA certification approval timelines, pyrolysis output regulatory classification, and post-consumer bale quality improvements from advanced optical sorting deployment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Myanmar Plastics Market