
 Global Lipid Regulators Market | 2026-2036
Global Lipid Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lipid Regulators Market Foresight
Aftermarket patient support programs is tilting toward outcome-based contracting models that tie reimbursement to LDL reduction metrics. Pfizer leverages its manufacturing scale to supply generic atorvastatin across emerging markets. Novartis AG differentiates through its inclisiran RNA interference platform. AstraZeneca anchors its position with the Epanova omega-3 franchise and integrated cardiovascular portfolios.
Lipid regulators comprise pharmacological agents that modulate cholesterol synthesis, absorption, or clearance through hepatic enzyme inhibition, intestinal transporter blockade, or PCSK9 pathway suppression, with potency measured by LDL-C reduction percentage and therapeutic efficacy validated through long-term cardiovascular outcome trials. Statins occupy the mature volume base as first-line therapy, while PCSK9 inhibitors capture the fastest-growing margin pool in severe familial hypercholesterolemia. Omega-3 fatty acids compete in the residual cardiovascular risk segment where triglyceride elevation persists despite statin therapy.
The FDA mandates cardiovascular outcome trials for novel lipid-lowering mechanisms, while the EMA enforces post-authorization safety studies through its pharmacovigilance framework and the EU MDR tightens device-drug combination requirements for delivery systems. China's NMPA accelerates reviews for innovative biologics under its priority review pathway. Stakeholders must monitor how payer consolidation across Medicare Advantage plans and European health technology assessment bodies reshapes pricing power for next-generation therapies.
Market Dynamics
Outcome-based contracting is reshaping how lipid regulators reach patients, with payers now conditioning reimbursement on measured LDL-C reduction rather than simple prescription volume. This structural shift rewards therapies demonstrating superior real-world efficacy while compressing margins for commoditized statin portfolios.
Growth Catalysts
- Familial Hypercholesterolemia Prevalence:Genetic screening programs in Germany and the United States are identifying untreated severe cases, expanding the addressable population for PCSK9 inhibitors and combination regimens.
- EU MDR Device-Drug Framework:The tightened requirements for delivery systems are accelerating investment in integrated auto-injector platforms that improve adherence in home settings.
- Preventive Cardiology Expansion:China's NMPA priority review pathway for innovative biologics is shortening time-to-market for RNA interference therapies targeting previously untreatable patient subsets.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70% of generic statin API supply originates from a concentrated manufacturing base in India, creating vulnerability to export restrictions or quality enforcement actions.
- CVOT Cost Burden:The FDA's cardiovascular outcome trial mandate for novel mechanisms imposes $500M-$1B development costs that exclude all but the largest developers from mechanistic innovation.
- Biosimilar Substitution:European health technology assessment bodies increasingly favor cost-equivalent biosimilars over originator PCSK9 inhibitors, compressing pricing power for first-movers.
Strategic Opportunities
- Residual Risk Targeting:Omega-3 fatty acid combinations addressing persistent triglyceride elevation in statin-treated patients represent an underserved segment with limited mechanistic competition.
- Japan's Aging Demographics:METI's preventive care incentives are expanding reimbursement for proactive cholesterol management in patients over 65, creating volume expansion in a high-compliance market.
- Digital Therapeutic Convergence:Integration of continuous lipid monitoring wearables with automated dosing algorithms is enabling personalized titration protocols that improve outcomes and reduce adverse events.
Industry Challenges
- Specialized Field Force Requirements:PCSK9 and RNA therapies require reimbursement specialists capable of navigating prior authorization complexity, creating talent scarcity in emerging markets.
- Legacy System Interoperability:Electronic health record fragmentation across United States hospital networks impedes automated risk stratification and therapy selection algorithms.
- Pharmacovigilance Scale:EMA's post-authorization safety study requirements demand real-world evidence infrastructure that mid-cap developers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lipid Regulators Market |
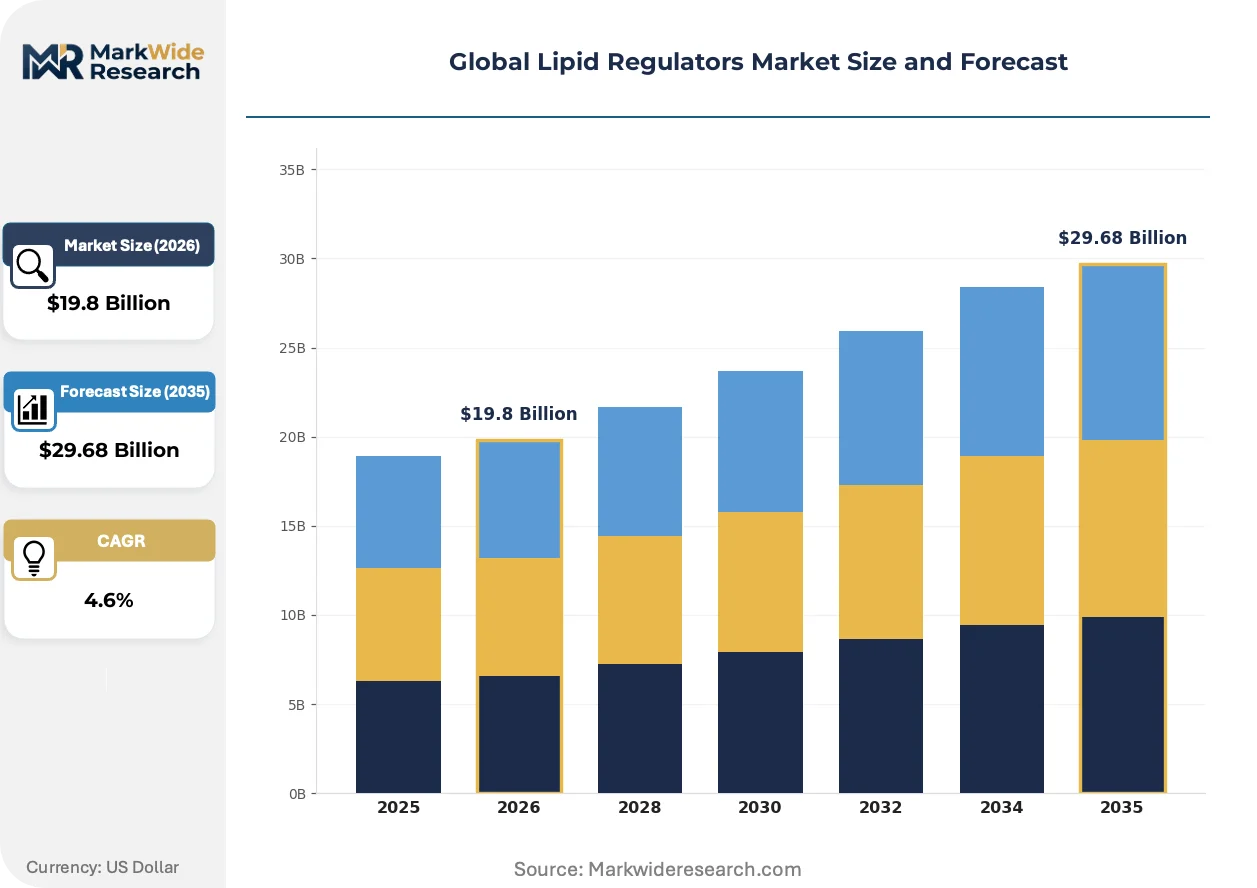
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, Fibrates, Niacin, Cholesterol Absorption Inhibitors, PCSK9 Inhibitors, Omega-3 Fatty Acids Therapy Area: Hypercholesterolemia, Hypertriglyceridemia, Mixed Dyslipidemia, Familial Hyperlipoproteinemia, Atherosclerosis, Coronary Heart Disease End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Cardiology Centers, Diagnostic Laboratories Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Drug Stores, Wholesalers |
| Companies Covered | Pfizer, Novartis AG, AstraZeneca, Amgen Inc, AbbVie Inc, Merck & Co., Bristol-Myers Squibb, Sanofi, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lipid Regulators Market Shifts & Advancements
RNA interference platforms are disrupting the small-molecule dominance of lipid management, enabling sustained LDL reduction through infrequent dosing that alters patient compliance economics and competitive positioning.
Small interfering RNA constructs targeting PCSK9 synthesis are hybridizing with established statin protocols, creating combination regimens that cardiology centers in Germany and the United States are adopting for severe familial hypercholesterolemia cases. Hospital formularies are expanding preferred status for these integrated approaches, compressing the market for high-intensity statin monotherapy in refractory patients.
REACH regulatory alignment across European member states is harmonizing substance authorization timelines for novel excipients used in extended-release formulations. The industrial consequence is reduced regulatory friction for developers pursuing differentiated delivery mechanisms. Manufacturers are responding by accelerating filings in Germany and France as reference markets for subsequent mutual recognition procedures.
Hospital procurement committees are consolidating vendor relationships around integrated cardiovascular portfolios rather than discrete lipid products, displacing standalone statin suppliers in favor of partners offering outcome guarantees across the full risk spectrum. This concentration is most visible in United States Medicare Advantage plans, where pharmacy benefit managers are narrowing therapeutic interchange lists to manufacturers willing to accept total cost-of-care accountability.
Global Lipid Regulators Market Segmentation
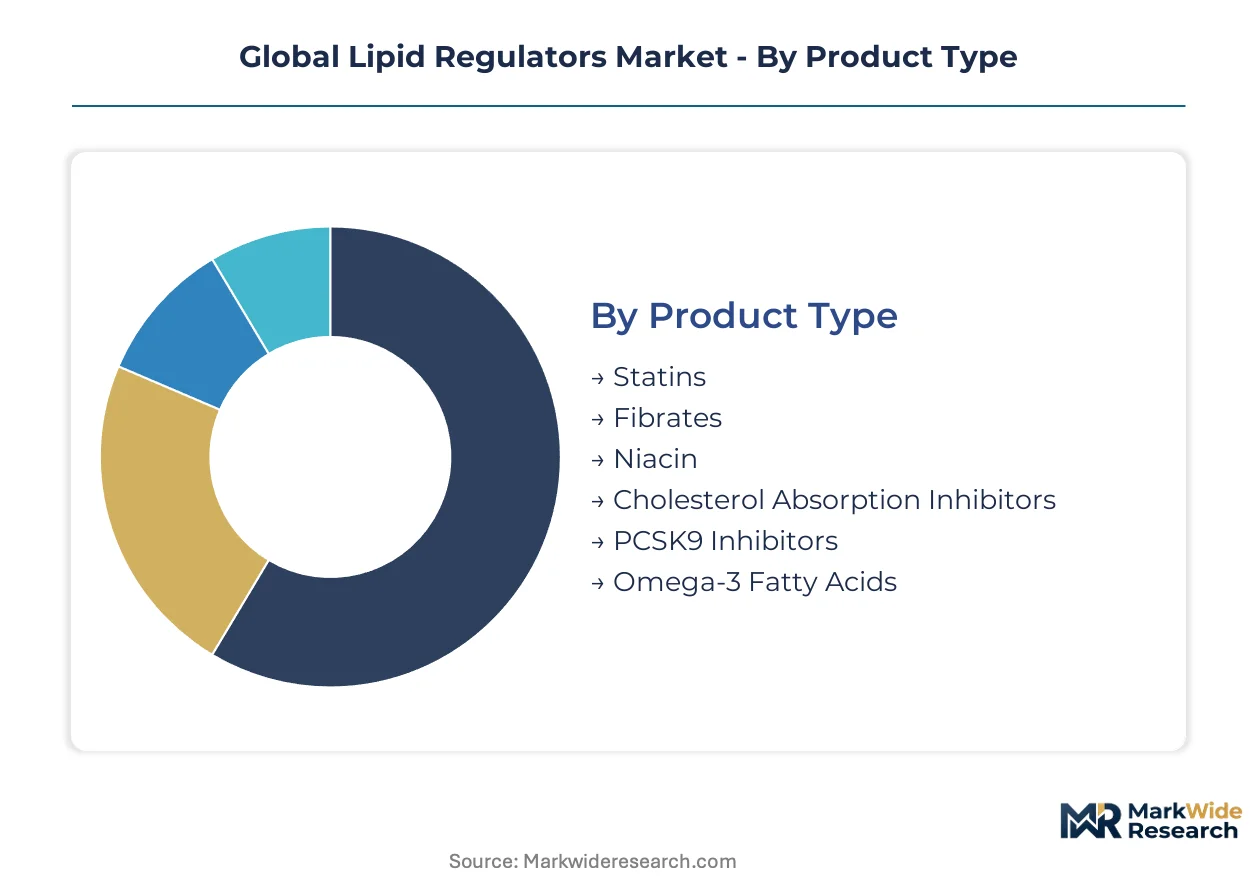
Segmentation in lipid regulators reveals how therapeutic mechanism, clinical setting, and procurement pathway determine margin structure and competitive intensity. Manufacturers calibrate portfolio investments across these dimensions based on reimbursement leverage and prescriber concentration.
Product Type:
Cost tier separates mature commodity volumes from premium innovation corridors in this market.
- Statins:HMG-CoA reductase inhibitors ranging from low-intensity pravastatin to high-intensity rosuvastatin dominate prescription volumes. Demand concentrates in Germany and the United States where generic substitution has compressed unit economics to pennies per dose.
- PCSK9 Inhibitors:Monoclonal antibodies and RNA interference therapies targeting PCSK9 protein degradation deliver 50-60% LDL-C reduction. Severe familial hypercholesterolemia cases in United States cardiology centers drive adoption where prior authorization hurdles filter for highest-risk patients.
- Fibrates:Peroxisome proliferator-activated receptor agonists modulating triglyceride metabolism.
- Niacin:Vitamin B3 derivatives at pharmacological doses affecting lipoprotein synthesis.
- Cholesterol Absorption Inhibitors:Ezetimibe-class compounds blocking intestinal NPC1L1 transporters.
- Omega-3 Fatty Acids:EPA/DHA formulations addressing residual cardiovascular risk.
Statins command the established base. The steepest expansion runs through PCSK9 inhibitors.
Therapy Area:
Application severity determines whether first-line protocols or escalation pathways capture patient volume.
- Hypercholesterolemia:Elevated LDL-C representing the broadest addressable population. United States preventive cardiology programs and German statutory health insurance preventive checkups sustain volume for statin-first protocols.
- Familial Hyperlipoproteinemia:Genetic defects in LDL receptor or apolipoprotein B-100 creating extreme cholesterol elevation. Specialized lipid clinics in Germany and academic medical centers in the United States concentrate demand for combination regimens including PCSK9 inhibitors.
- Hypertriglyceridemia:Isolated or mixed elevation of triglyceride levels.
- Mixed Dyslipidemia:Concurrent LDL-C and triglyceride abnormalities.
- Atherosclerosis:Established arterial plaque disease requiring aggressive lipid lowering.
- Coronary Heart Disease:Symptomatic ischemic disease with guideline-mandated targets.
Hypercholesterolemia anchors volume scale. Familial hyperlipoproteinemia is climbing the fastest.
End User:
Customer type dictates field force specialization and formulary access requirements.
- Hospitals:Inpatient initiation of high-intensity therapy and formulary-controlled outpatient prescribing. United States integrated delivery networks and German hospital chains are consolidating procurement around cardiovascular portfolio partners.
- Cardiology Centers:Specialized outpatient facilities managing complex dyslipidemia. Centers in Germany and the United States are expanding combination therapy protocols for statin-intolerant or refractory patients.
- Specialty Clinics:Dedicated lipid or endocrinology practices.
- Ambulatory Surgical Centers:Pre-operative cardiovascular risk assessment venues.
- Diagnostic Laboratories:Testing facilities with limited direct prescribing authority.
Hospitals control the volume base. Cardiology centers are gaining share fastest.
Distribution Channel:
Supply concentration shapes pricing power and patient access friction.
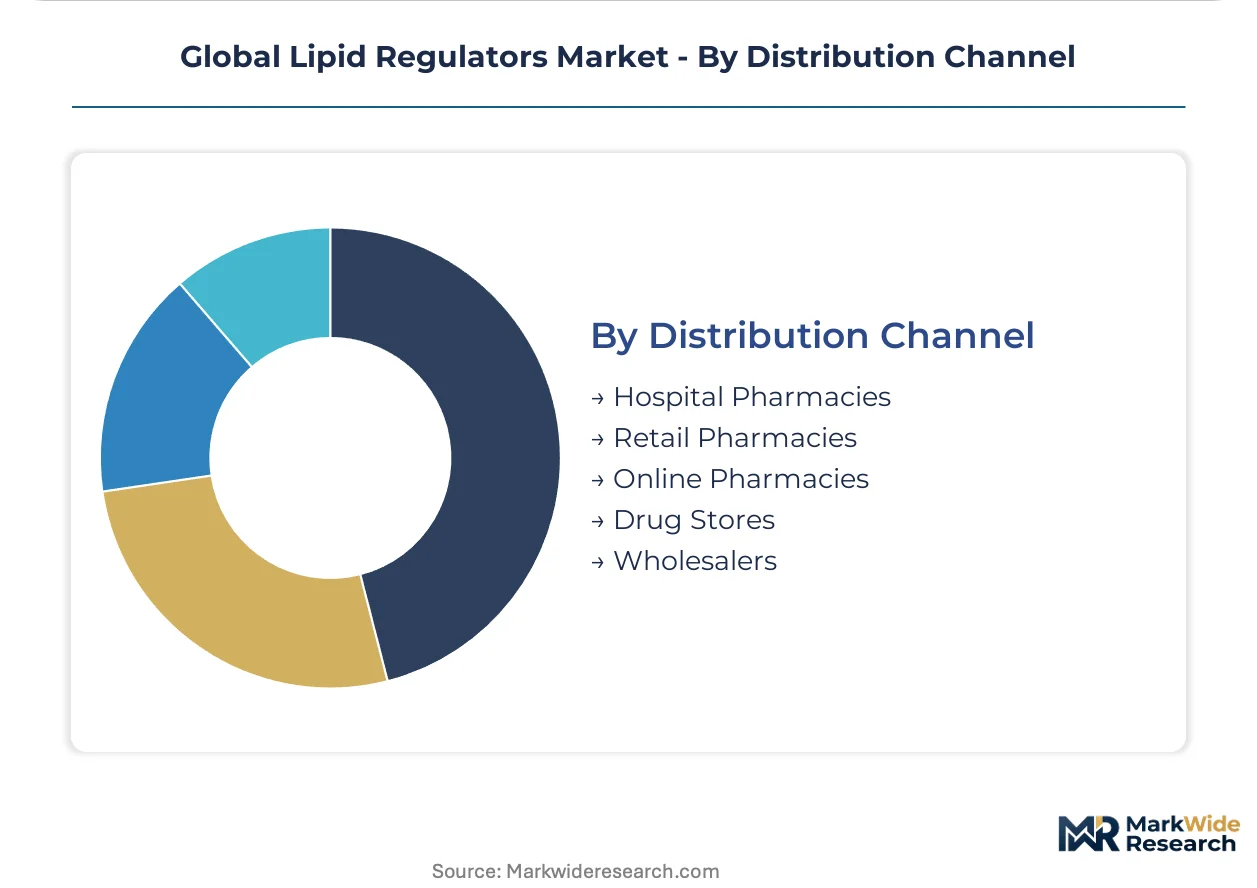
- Hospital Pharmacies:Captive dispensing within integrated health systems. United States Medicare Advantage plans and German hospital pharmacies are narrowing supplier lists to manufacturers accepting outcome-based contracts.
- Retail Pharmacies:Community-based dispensing with high generic substitution rates. Chains in Germany and the United States drive volume for established statin portfolios through 90-day fills and automatic refill programs.
- Online Pharmacies:Direct-to-patient delivery platforms.
- Drug Stores:Convenience-focused retail with limited clinical services.
- Wholesalers:Three-tier distribution intermediaries stocking inventory.
Hospital pharmacies concentrate the premium segment. Retail pharmacies anchor the volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across major markets. Germany and the United States absorb premium PCSK9 therapies through outcome-based contracts, while India and Brazil remain volume-driven generic statin markets where pennies per dose determine procurement winners.
United States
Medicare Advantage plans and integrated delivery networks drive demand for combination regimens in severe familial hypercholesterolemia. FDA cardiovascular outcome trial mandates shape the approval pathway for novel mechanisms. Boston and Cleveland academic medical centers anchor PCSK9 adoption through specialized lipid clinics.
Germany
Statutory health insurance preventive checkups sustain high-intensity statin volumes across primary care networks. EMA pharmacovigilance frameworks enforce post-authorization safety studies for RNA interference platforms. Berlin and Munich hospital chains consolidate procurement around cardiovascular portfolio partners accepting total cost-of-care accountability.
China
Rising cardiovascular disease burden expands the addressable population for lipid management in tier-one cities. NMPA priority review pathways accelerate market entry for innovative biologics targeting refractory patients. Shanghai and Beijing specialty hospitals pilot integrated auto-injector platforms to improve home adherence.
Japan
Aging demographics above 65 years create volume expansion for proactive cholesterol management protocols. METI preventive care incentives expand reimbursement for early intervention therapies. Osaka and Nagoya cardiology centers adopt digital therapeutic convergence with continuous lipid monitoring wearables.
India
Generic statin manufacturing concentrates API supply for export markets across emerging economies. The country's national pharmaceutical regulator enforces quality standards that determine export eligibility. Hyderabad and Ahmedabad industrial clusters house concentrated active pharmaceutical ingredient production serving global demand.
Global Lipid Regulators Market Competitive Landscape
Capability concentration sits with RNA interference and monoclonal antibody developers; scale advantage sits with generic statin manufacturers. The market structures around three tiers: originator biologics commanding premium pricing, biosimilar challengers compressing margins, and commoditized small molecules competing on manufacturing efficiency. Strategic archetypes include integrated cardiovascular portfolio builders, specialized biologic developers, and API-to-formulation vertical integrators. Dominant competitive moves encompass outcome-based contracting negotiations with pharmacy benefit managers and auto-injector platform investments to differentiate delivery convenience.
Among originator biologics developers, Pfizer, Novartis AG, and AstraZeneca occupy positions spanning the capability spectrum. Pfizer exemplifies scale-driven manufacturing reach across emerging markets. Novartis AG represents RNA interference platform specialization. AstraZeneca anchors integrated cardiovascular portfolio positioning through omega-3 franchise assets.
| Leading Market Players |
|---|
| Pfizer |
| Novartis AG |
| AstraZeneca |
| Amgen Inc |
| AbbVie Inc |
| Merck & Co. |
| Bristol-Myers Squibb |
| Sanofi |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Single-source dependency on Indian API manufacturing for generic statins determines both the extreme compression of economy-tier pricing and the geographic concentration of upstream supply chains. FDA import alerts and CDSCO quality enforcement actions cascade through contract manufacturing networks, forcing buyers toward qualified alternative sources at higher landed costs.
Pricing Analysis
Patient support program contracts drive lifetime value through outcome-based reimbursement tied to LDL-C reduction metrics. Three-tier pricing structure across premium RNA interference therapies, mid-tier branded statins, and economy generic volumes reflects differentiation by cardiovascular outcome trial validation and manufacturing scale. Cost compression in the statin tier intensifies because Medicare Advantage plans and German statutory insurers enforce therapeutic interchange. Hospital procurement committees exhibit lowest price sensitivity for PCSK9 inhibitors with proven real-world efficacy, while retail pharmacy chains drive pennies-per-dose competition for established small molecules.
Supply Chain Analysis
Upstream fermentation and chemical synthesis of HMG-CoA reductase inhibitor precursors draws from industrial clusters in Hyderabad, Ahmedabad, and select Chinese manufacturing zones. Active pharmaceutical ingredient production rests on concentrated fermentation capacity, specialized solvent recovery systems, and cold-chain logistics for biologic finished goods. Single-source vulnerability concentrates in Indian API export permits subject to DGFT restriction. Distribution runs through three-tier wholesaler networks in developed markets and direct hospital contracting in integrated United States delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA interference platform economics are creating winner-take-most dynamics where interoperable auto-injector ecosystems determine formulary access. The convergence of continuous lipid monitoring with automated dosing algorithms shifts competitive advantage toward integrated cardiovascular portfolio builders.
For Market Incumbents: Pre-empt biosimilar substitution pressure by locking cardiology centers into multi-year outcome-based contracts with total cost-of-care accountability. Deepen backward integration into API manufacturing to reduce exposure to Indian supply concentration. Accelerate filings for extended-release formulations under REACH harmonization to capture mutual recognition procedure advantages in Germany and France.
For New Entrants and Emerging Players: Pursue residual cardiovascular risk segments where omega-3 combinations address persistent triglyceride elevation with limited mechanistic competition. Target Japan's aging demographic expansion under METI preventive care incentives for volume growth in a high-compliance market. Lead with digital therapeutic convergence offerings that integrate continuous monitoring wearables to differentiate from established pharmacological competitors.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors integrated cardiovascular portfolio builders with captive delivery device capabilities. Long-term viability over the next decade hinges on outcome-based contracting infrastructure and real-world evidence generation. Watch for inflection signals in Medicare Advantage plan pharmacy benefit manager consolidation that narrows therapeutic interchange lists to manufacturers accepting total cost-of-care risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Contracting | Medicare Advantage plans tie reimbursement to measured LDL-C reduction metrics. |
| Auto-Injector Platform Investment | Integrated delivery systems improve home adherence under EU MDR requirements. |
| RNA Interference Pipeline Expansion | Sustained LDL reduction through infrequent dosing alters compliance economics. |
| API Manufacturing Backward Integration | Captive supply reduces vulnerability to Indian export restriction risk. |
| Digital Therapeutic Convergence | Continuous lipid monitoring wearables enable personalized titration protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, formulary directors, payer access specialists, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation cross-checked segmentation outputs across mechanism of action, patient population severity, and regional regulatory clusters.
Forecast inputs considered therapy line positioning, dosage form differentiation, administration route convenience, and regional reimbursement pathway maturity across the analysis window. CAGRs were derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Modeled outputs incorporated cardiovascular outcome trial completion timelines, NMPA priority review pathway acceleration effects, and biosimilar entry dynamics in European markets.
Sensitivities concentrate around FDA cardiovascular outcome trial mandate enforcement, EMA pharmacovigilance study requirement expansion, and Indian API supply disruption scenarios. Forecasts reflect documented assumptions on patient screening program expansion rates and outcome-based contract adoption curves. Cross-checking against CMS Medicare Part D formulary placement data and IQVIA prescription audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Detox Products Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Pediatric Supplements Market
Dietary Supplements
Magnesium Glycinate Market