
 Asia-Pacific Healthcare Staffing Market | 2026-2036
Asia-Pacific Healthcare Staffing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Healthcare Staffing Market Insights
Tier-one credential verification is redrawing competitive boundaries in Asia-Pacific healthcare staffing. AMN Healthcare leverages its cross-border licensing infrastructure to place specialized nurses across Australian and Japanese facilities. Adecco Group anchors its regional position through permanent placement dominance in Singapore's private hospital sector. TeamHealth differentiates by concentrating physician locum tenens within India's expanding tertiary care networks.
Healthcare staffing encompasses the sourcing, credentialing, and deployment of clinical and non-clinical personnel to medical facilities on temporary, permanent, or travel-based arrangements, governed by jurisdiction-specific licensing reciprocity and patient-ratio mandates. Its commercial purpose centers on matching verified workforce supply against fluctuating patient census demands without fixed employment overhead. Temporary staffing commands the largest revenue pool across service types, reflecting seasonal disease burdens and pandemic-response protocols that hospitals cannot address through permanent hires alone. Allied health professionals represent the fastest-expanding staff category, driven by rehabilitation center expansion and home healthcare diversification across the region's aging societies.
Japan's PMDA collaborates with METI on foreign nurse equivalency assessments, while Australia's Aged Care Quality and Safety Commission enforces mandatory staff-to-resident ratios that directly inflate agency demand. India's CDSCO and state nursing councils impose varying registration requirements that fragment cross-state deployment efficiency. Stakeholders must monitor regulatory harmonization progress between national credentialing bodies and sub-national licensing authorities to anticipate workforce mobility bottlenecks.
Market Dynamics
Credential verification infrastructure is fragmenting deployment velocity across Asia-Pacific healthcare staffing, as Australia's Aged Care Quality and Safety Commission ratios and Japan's PMDA foreign nurse equivalency protocols impose divergent compliance burdens on regional agencies.
Growth Catalysts
- Australia's mandatory staff-to-resident ratios:The Aged Care Quality and Safety Commission enforces minimum nursing hours per resident, forcing facilities to supplement permanent staff with agency personnel during census spikes and regulatory audit windows.
- Rehabilitation center expansion:Post-acute care networks across South Korea and Thailand are scaling allied health professional headcount to serve aging populations recovering from orthopedic and cardiovascular procedures.
- Home healthcare diversification:Japan's community-based integrated care system is redirecting chronic disease management from hospitals to domiciliary settings, creating demand for mobile nursing and therapy staffing pools.
Market Restraints
- Cross-state registration friction:India's state nursing councils impose non-uniform documentation requirements that fragment multi-state deployment efficiency for traveling nurse programs.
- Specialized skill scarcity:Intensive care and operating theater nurses command premium placement fees that compress agency margins during competitive bidding for hospital network contracts.
- Digital platform substitution:Direct-to-clinician matching applications are disintermediating traditional staffing intermediaries in metropolitan Australian and Singaporean markets.
Strategic Opportunities
- Vietnam's private hospital buildout:Ho Chi Minh City and Hanoi medical corridors are adding tertiary beds faster than domestic nursing schools can supply graduates, opening placement channels for cross-border Filipino and Indonesian professionals.
- Telehealth-integrated staffing:Remote patient monitoring platforms are converging with on-site clinical deployment, enabling hybrid care models that extend nurse reach across rural Australian and Japanese prefectures.
- Malaysia's medical travel rebound:Penang and Kuala Lumpur specialist centers are restoring pre-pandemic international patient volumes, requiring surge-capable surgical and anesthesia staffing arrangements.
Industry Challenges
- Credential reciprocity timelines:PMDA equivalency assessments for Philippine and Indonesian nursing qualifications extend placement lead times beyond hospital budget cycles.
- Legacy workforce management integration:Hospital HR systems lack API connectivity with agency scheduling platforms, forcing manual shift reconciliation and payment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Healthcare Staffing Market |
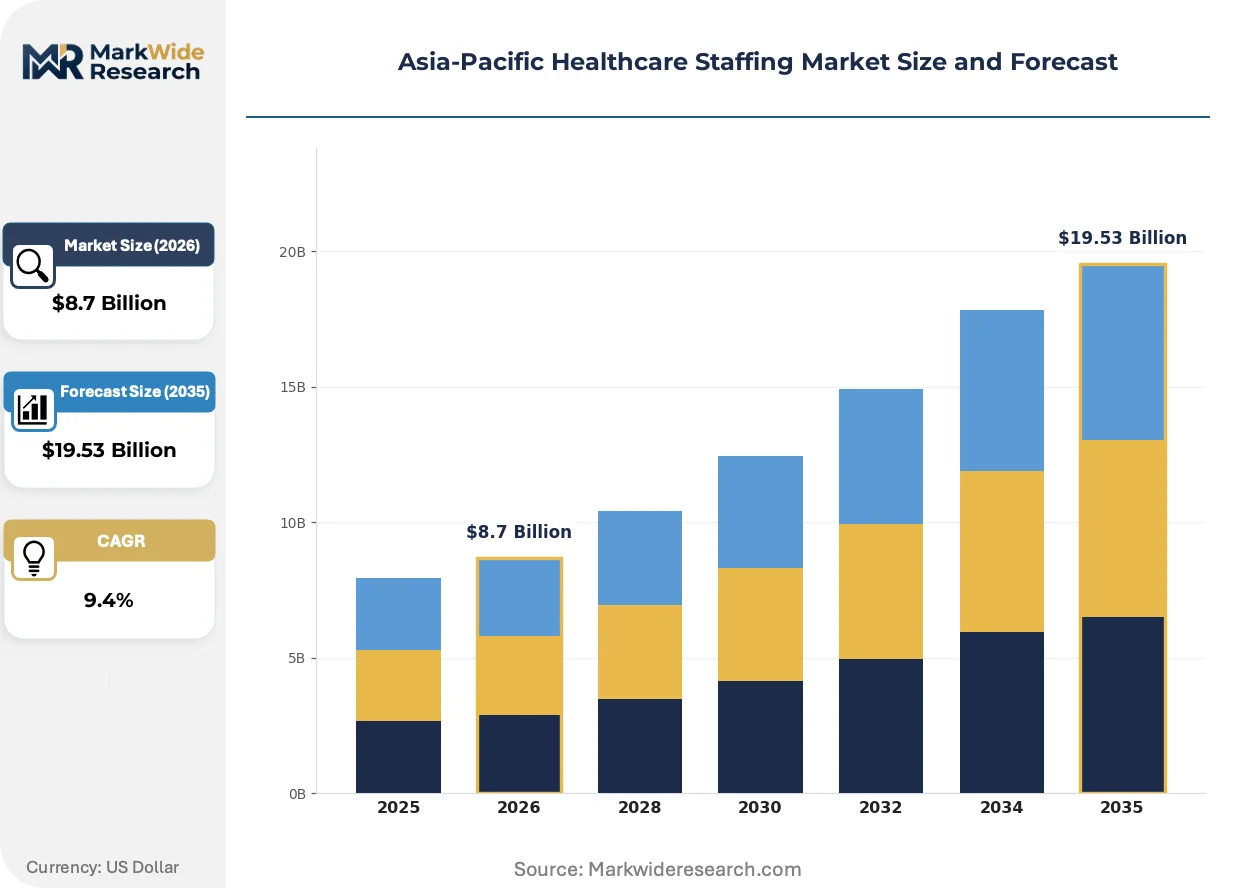
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Temporary Staffing, Permanent Placement, Travel Nursing, Locum Tenens End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Staff Type: Nurses, Physicians, Allied Health Professionals, Support Staff Recruitment Channel: Online Job Portals, Staffing Agencies, Referrals, Social Media |
| Companies Covered | AMN Healthcare, Cross Country Healthcare, Adecco Group, Envision Healthcare Corporation, TeamHealth, Aya Healthcare, Maxim Healthcare Services, NurseFly, Acara Solutions India, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Healthcare Staffing Market Trends and Innovations
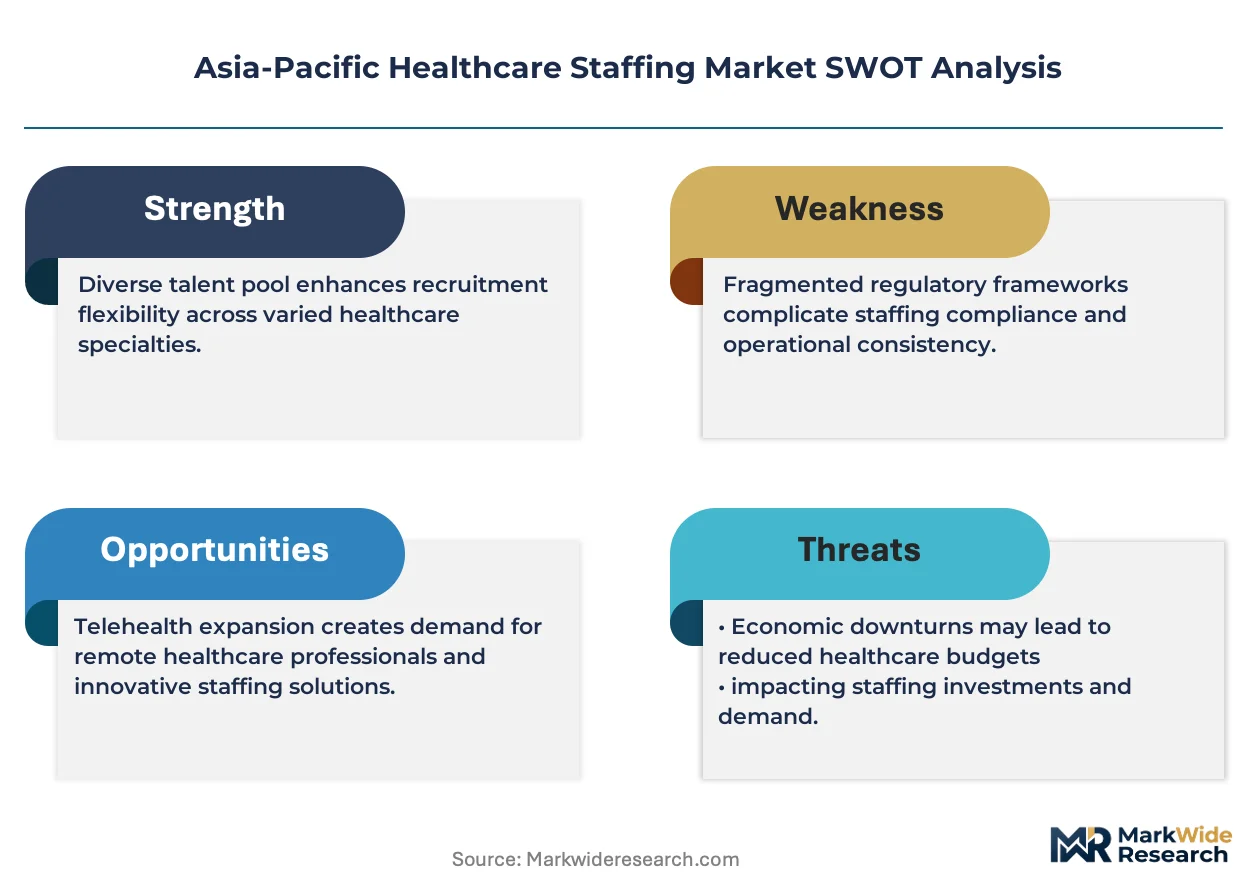
Digital credential verification and workforce matching platforms are compressing placement cycles while regulatory divergence between national and sub-national authorities is hardening compliance architecture across the region.
Blockchain-enabled credential wallets are bifurcating verification pathways between automated instant validation and prolonged manual review. Singapore's private hospital networks and Australian aged care chains are piloting interoperable digital identity standards that reduce onboarding from weeks to hours. This compression is enabling same-week deployment for emergency staffing requests while marginalizing agencies lacking API-connected verification infrastructure.
Japan's METI-PMDA collaborative framework on foreign nurse equivalency is tightening assessment protocols for Southeast Asian nursing qualifications. The industrial consequence is a tiered placement market where pre-certified candidates command priority placement while uncertified applicants face extended evaluation queues. Australian and Japanese tertiary facilities are responding by front-loading recruitment relationships with Philippine schools holding pre-approved accreditation status.
Hospital procurement departments are consolidating vendor panels to reduce administrative overhead from fragmented agency relationships. Australia's metropolitan health networks and India's corporate hospital chains are replacing open-market bidding with preferred-provider agreements covering multi-year staffing commitments. This concentration is most visible in Bengaluru and Mumbai, where Apollo and Fortis networks have reduced active agency partnerships from dozens to single-digit panels with volume-guarantee clauses.
Asia-Pacific Healthcare Staffing Market Segmentation
Regulatory fragmentation across Asia-Pacific jurisdictions forces staffing providers to align service architectures with divergent licensing reciprocity rules and patient-ratio mandates. Segmentation reveals where compliance complexity concentrates margin pressure and where standardization enables scale.
Service Type:
Australia's Aged Care Quality and Safety Commission ratios and Japan's PMDA foreign nurse equivalency protocols create divergent compliance burdens that reshape service profitability across deployment models.
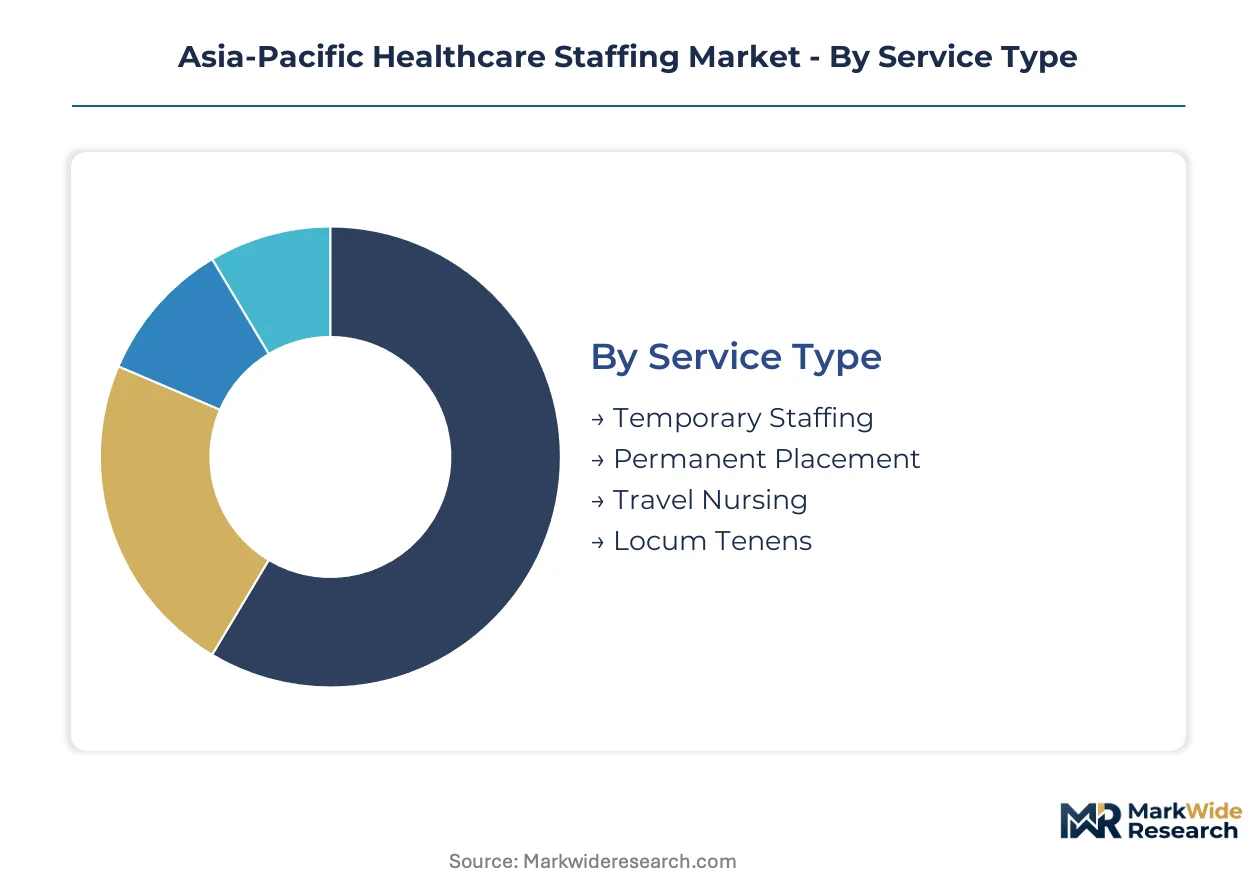
- Temporary Staffing:Seasonal census spikes and pandemic-response protocols drive hospital reliance on shift-based clinical personnel without fixed employment overhead. Australian metropolitan networks deploy temporary nurses during regulatory audit windows, while Indian corporate hospital chains activate surge pools for monsoon-related infectious disease burdens.
- Travel Nursing:Cross-state and cross-border deployment of credentialed nurses to tier-one cities and regional hubs where domestic supply falls short. India's state nursing council fragmentation forces agencies to maintain parallel documentation systems, compressing margins on multi-state contracts despite premium placement fees.
- Permanent Placement:Full-time clinical and administrative hiring with extended credential verification timelines. Singapore's private hospital sector concentrates demand here as foreign-trained specialists pursue long-term accreditation pathways.
- Locum Tenens:Short-term physician coverage for specialty gaps in surgical and anesthesia departments. Malaysian medical travel corridors in Penang and Kuala Lumpur activate these arrangements during international patient volume rebounds.
Temporary Staffing handles the majority of throughput; Travel Nursing is the fastest mover on share.
End User:
Patient acuity and reimbursement models determine whether facilities build permanent headcount or outsource workforce flexibility to agency intermediaries.
- Hospitals:Tertiary and secondary acute care facilities with the highest clinical complexity and regulatory scrutiny. Southeast Asian hospital expansion programs in Vietnam's Ho Chi Minh City corridor generate concentrated demand for cross-border nursing deployment.
- Home Healthcare:Domiciliary nursing and therapy services for chronic disease management. Japan's community-based integrated care system redirects demand from institutional settings, requiring mobile staffing pools with vehicle-based credential verification.
- Rehabilitation Centers:Post-acute facilities scaling allied health professional headcount. South Korean and Thai orthopedic recovery networks drive expansion here as aging populations undergo joint replacement procedures.
- Clinics:Outpatient and primary care settings with lower credential complexity but higher volume turnover. Metropolitan Australian and Singaporean markets see direct-to-clinician digital platforms disintermediating traditional agency relationships in this segment.
Hospitals absorb the dominant share of agency revenue; Home Healthcare is expanding most quickly as aging-in-place policies mature.
Staff Type:
Specialized skill scarcity and licensing reciprocity timelines stratify placement economics across clinical categories.
- Nurses:The largest deployed category spanning general ward, intensive care, and operating theater specializations. Philippine and Indonesian nursing qualifications face extended PMDA equivalency assessments, creating tiered candidate pools with divergent placement velocities.
- Allied Health Professionals:Physical therapists, occupational therapists, and diagnostic technicians representing the steepest expansion trajectory. Rehabilitation center buildouts across South Korea and Thailand concentrate demand for these roles.
- Physicians:Specialist and generalist medical doctors deployed through locum tenens or permanent placement. India's tertiary care networks in Bengaluru and Mumbai compete aggressively for surgical and anesthesia specialists.
- Support Staff:Administrative, technical, and ancillary personnel with lower regulatory barriers but higher volume requirements. Singapore's private hospital sector sources these roles through permanent placement dominance.
Nurses command the largest placement volume; Allied Health Professionals are gaining share fastest on rehabilitation network expansion.
Recruitment Channel:
Digital infrastructure maturity determines whether sourcing concentrates through algorithmic matching or relationship-based agency networks.
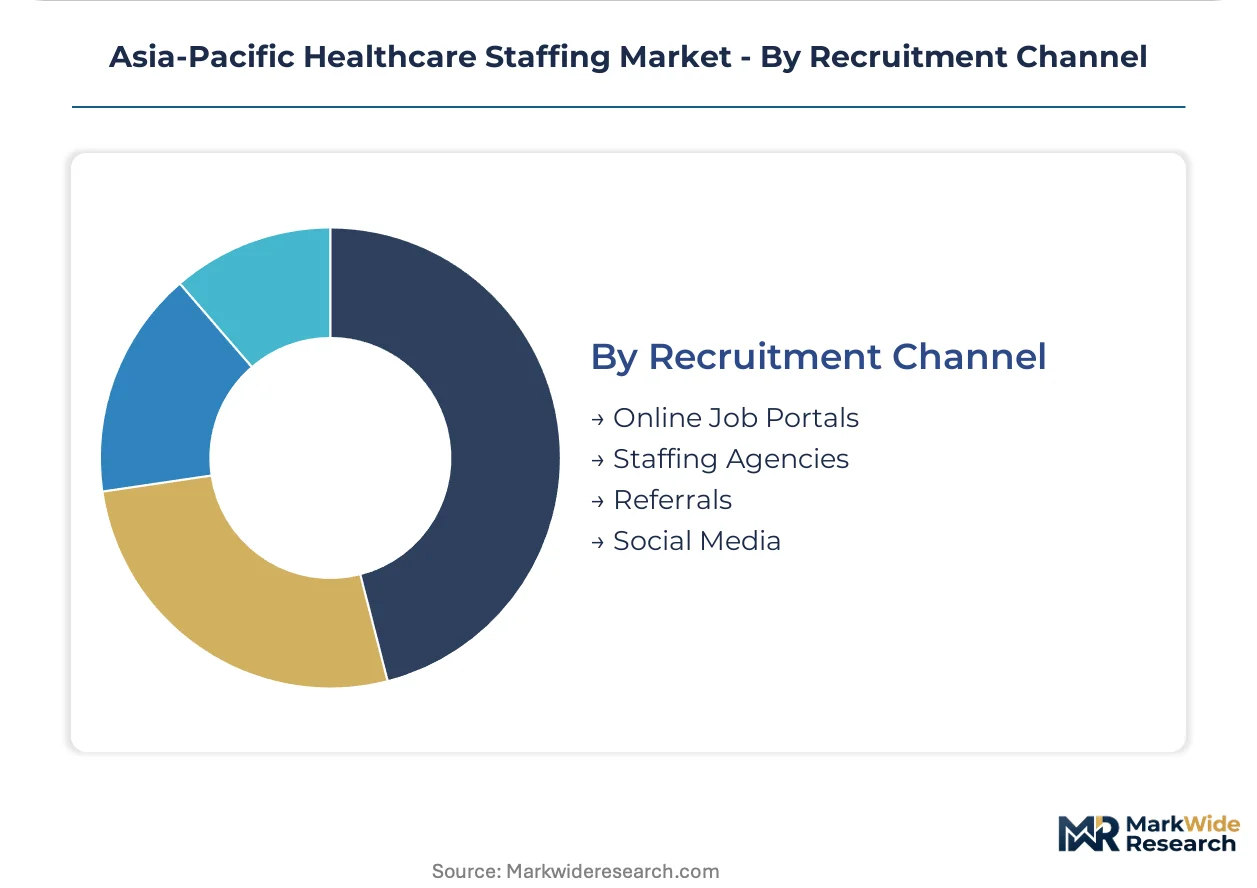
- Staffing Agencies:Traditional intermediaries with credential verification infrastructure and hospital contract relationships. Preferred-provider panel consolidation in Australia's metropolitan health networks and India's Apollo and Fortis chains reduces active agency partnerships to volume-guaranteed single-digit panels.
- Online Job Portals:Digital platforms enabling direct employer-candidate matching with automated screening. These channels are compressing placement cycles where API-connected verification infrastructure exists.
- Referrals:Network-based sourcing through professional relationships and existing staff recommendations. Retains importance in specialized clinical categories where trust and credential reliability outweigh speed.
- Social Media:Emerging channel for passive candidate engagement and employer branding. Limited penetration in regulated clinical categories due to verification complexity.
Staffing Agencies still process the majority of verified placements; Online Job Portals are climbing the fastest on digital credential wallet adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Asia-Pacific healthcare staffing markets. Australian aged care operators absorb premium agency rates to meet mandatory staff-to-resident ratios, while Indian hospital networks negotiate volume discounts for traveling nurse deployments across state lines.
Australia
Metropolitan health networks in Sydney and Melbourne activate surge staffing during regulatory audit windows mandated by the Aged Care Quality and Safety Commission. The Commission's minimum nursing hours per resident rule forces facilities to supplement permanent rosters with agency personnel. Queensland's regional hospitals extend this demand pattern into rural catchments where domestic supply falls short.
Japan
Prefecture-level integrated care systems redirect chronic disease management from hospitals to domiciliary settings, creating demand for mobile nursing pools. METI collaborates with PMDA on foreign nurse equivalency assessments that extend placement lead times for Philippine and Indonesian candidates. Osaka's tertiary facilities front-load recruitment with Philippine schools holding pre-approved accreditation status to bypass assessment queues.
India
Corporate hospital chains in Bengaluru and Mumbai consolidate agency panels from dozens to single-digit preferred-provider agreements with volume-guarantee clauses. State nursing councils impose non-uniform documentation requirements that fragment multi-state deployment efficiency for traveling nurse programs. Apollo and Fortis networks drive this procurement concentration in metropolitan corridors.
Vietnam
Ho Chi Minh City and Hanoi medical corridors add tertiary beds faster than domestic nursing schools can supply graduates. Private hospital buildouts open placement channels for cross-border Filipino and Indonesian professionals. The Ministry of Health's facility licensing expansion outpaces local workforce development capacity.
Singapore
Private hospital sector concentrates permanent placement demand as foreign-trained specialists pursue long-term accreditation pathways. The Ministry of Manpower's employment pass framework governs clinical workforce inflows. Raffles Medical Group and Parkway Pantai anchor agency relationships through multi-year staffing commitments in the city-state's compact metropolitan market.
Asia-Pacific Healthcare Staffing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Asia-Pacific healthcare staffing. Cross-border licensing infrastructure and digital credential verification separate premium-tier agencies from commodity intermediaries. Three archetypes dominate: integrated staffing platforms with proprietary verification systems, relationship-driven permanent placement specialists, and volume-focused temporary staffing brokers. Competitive moves concentrate on preferred-provider panel consolidation and API-connected workforce management integration with hospital HR systems.
Within the integrated platform tier, AMN Healthcare and Aya Healthcare exemplify archetypes combining cross-border licensing infrastructure with digital deployment capabilities. Adecco Group anchors the permanent placement specialization vector in Singapore's private hospital sector. TeamHealth occupies a position exemplifying physician locum tenens concentration within India's tertiary care networks. These three represent divergent strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| AMN Healthcare |
| Cross Country Healthcare |
| Adecco Group |
| Envision Healthcare Corporation |
| TeamHealth |
| Aya Healthcare |
| Maxim Healthcare Services |
| NurseFly |
| Acara Solutions India |
| Others |
Pricing and Supply Chain Analysis
Japan's PMDA foreign nurse equivalency protocols gate both supply qualification and price differentiation simultaneously, as agencies bearing pre-certified candidate relationships command placement premiums while uncertified applicants compress margins through extended assessment timelines. Australian Aged Care Quality and Safety Commission ratios and India's state nursing council fragmentation create divergent compliance cost structures that stratify agency profitability across deployment models.
Pricing Analysis
After-sales revenue from extended credential verification contracts and multi-year preferred-provider agreements drives lifetime value for established agencies. Three-tier pricing structure across premium, standard, and economy levels separates pre-certified Philippine nurses with PMDA-approved school credentials from standard-tier candidates requiring equivalency assessment and economy-tier domestic supply without cross-border licensing. Cost compression in standard-tier placements is intensifying because hospital procurement departments consolidate vendor panels and demand volume-guarantee clauses. Metropolitan Australian aged care chains exhibit least price sensitivity due to regulatory audit penalties, while Indian corporate hospital networks negotiate most aggressively on multi-state traveling nurse contracts.
Supply Chain Analysis
The Philippines and Indonesia anchor cross-border nursing supply through accredited training institutions that feed Japan's PMDA equivalency pipeline and Vietnam's private hospital buildout. Deployment velocity draws from blockchain-enabled credential wallet infrastructure, API-connected verification systems, and manual documentation pathways for fragmented regulatory environments. Single-source vulnerability concentrates in Philippine pre-certified candidate pools where Osaka's tertiary facilities front-load recruitment relationships. Distribution runs through preferred-provider panel agreements with Australia's metropolitan health networks and India's Apollo and Fortis chains, supplemented by direct-to-clinician digital platforms disintermediating traditional intermediaries in Singaporean and Australian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific healthcare staffing operates through cyclical recovery patterns tied to pandemic-response protocol activation and seasonal disease burden spikes that reset hospital census forecasting and agency surge capacity planning.
For Market Incumbents: Fortify credential verification infrastructure through API-connected workforce management integration with hospital HR systems, eliminating manual shift reconciliation delays that erode preferred-provider status. Deepen backward integration into Philippine and Indonesian nursing school accreditation relationships to secure pre-certified candidate pipelines before PMDA equivalency assessment queues lengthen. Digital platform substitution from direct-to-clinician matching applications threatens traditional agency intermediation in metropolitan Australian and Singaporean markets. For New Entrants and Emerging Players: Anchor in Vietnam's Ho Chi Minh City and Hanoi medical corridors where tertiary bed expansion outpaces domestic nursing school graduate supply, creating placement channels for cross-border Filipino and Indonesian professionals. Target telehealth-integrated staffing hybrid models that converge remote patient monitoring with on-site clinical deployment across rural Australian and Japanese prefectures. Malaysia's medical travel rebound in Penang and Kuala Lumpur specialist centers offers surge-capable surgical and anesthesia staffing arrangements with lower incumbent saturation than established markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital credential verification infrastructure as blockchain-enabled credential wallets and interoperable digital identity standards reduce onboarding from weeks to hours. Long-term viability over the next decade rests on agencies combining cross-border licensing infrastructure with proprietary verification systems rather than relationship-driven permanent placement specialists or volume-focused temporary staffing brokers. Acquisition target archetype: integrated staffing platforms with API-connected hospital HR system integration and pre-certified candidate pipelines from Philippine schools holding PMDA-approved accreditation status. Signal to watch: regulatory harmonization progress between national credentialing bodies and sub-national licensing authorities indicating workforce mobility bottleneck resolution or hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Preferred-Provider Panel Consolidation | Apollo and Fortis networks reduce active agency partnerships to volume-guaranteed single-digit panels, compressing intermediary margins. |
| Blockchain Credential Wallet Deployment | Singapore's private hospital networks pilot interoperable digital identity standards that compress onboarding from weeks to hours. |
| Cross-Border School Accreditation Front-Loading | Osaka's tertiary facilities secure recruitment relationships with Philippine schools holding PMDA pre-approved status to bypass assessment queues. |
| API-Connected HR System Integration | Legacy workforce management integration gaps force manual shift reconciliation and payment delays that API connectivity eliminates. |
| Telehealth-Integrated Staffing Hybrid Models | Remote patient monitoring platforms converge with on-site clinical deployment to extend nurse reach across rural Australian and Japanese prefectures. |
Research Methodology
The analysis maps temporary staffing, travel nursing, permanent placement, and locum tenens deployment models, each validated through hospital procurement managers, agency credential verification officers, nursing school accreditation directors, and GPO contracts specialists. Primary interviews with staffing agency executives and hospital workforce planning directors combined with secondary validation from PMDA equivalency assessment filings, Australian Aged Care Quality and Safety Commission audit reports, Indian state nursing council registration databases, and hospital procurement contract disclosures. Bottom-up deployment volume modeling and top-down market sizing triangulated against regulatory filing aggregates.
Consistency checks validated volume and value outputs against external benchmarks including hospital bed expansion permits, nursing school graduate projections, and agency revenue disclosures across the projection horizon. Segmentation dimensions modeled encompass service type, end-user facility category, staff clinical specialization, and recruitment channel infrastructure maturity. CAGRs derived from regression analysis against historical deployment velocity, regulatory change timelines, and hospital capital expenditure cycles. Industry-specific forecast inputs include PMDA equivalency assessment queue lengths and state nursing council documentation requirement fragmentation indices.
Decision-makers should treat outputs as directional under base assumptions of continued regulatory divergence between national credentialing bodies and sub-national licensing authorities; material harmonization progress would warrant model refresh. Specific risk factors that could revise forecasts include sudden PMDA protocol tightening extending Philippine and Indonesian nurse placement lead times beyond hospital budget cycles, or accelerated digital platform substitution disintermediating traditional agency relationships in metropolitan Australian and Singaporean markets. Recalibration cycles align with material shifts in regulatory harmonization progress, hospital procurement department consolidation waves, and blockchain credential wallet adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
US Hospice Care Market
Healthcare Services
US Healthcare Staffing Market