
 Clinical Trial Logistics Market | 2026-2036
Clinical Trial Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Logistics Market Analytics
The EU Green Deal is expanding compliance obligations for temperature-controlled pharmaceutical shipments across European trade lanes. Marken leverages its specialized cold-chain infrastructure to sustain leadership in cell-and-gene therapy logistics. Thermo Fisher Scientific anchors North American capacity through integrated clinical supply networks. CEVA Logistics competes on global airline partnerships for time-critical trial material movements.
Clinical trial logistics encompasses the specialized coordination, storage, and distribution of investigational drugs, biological samples, and clinical supplies under validated temperature conditions, typically requiring maintenance within 2-8°C, -20°C, or cryogenic ranges to preserve molecular stability. The discipline serves primarily to ensure chain-of-custody integrity and patient safety across multi-site research protocols. Packaging services dominate current revenue contribution due to complex serialization and labeling demands, while track-and-trace technology represents the fastest-expanding segment as regulators mandate real-time visibility. Contract research organizations constitute a maturing demand pool with established vendor relationships, whereas biotech firms offer concentrated margin opportunities through specialized handling requirements.
FDA oversight of current good manufacturing practice (cGMP) and good distribution practice (GDP) standards shapes operational requirements for cross-border trial material movements. EMA's Clinical Trials Regulation harmonizes submission and safety reporting across EU member states, compressing approval timelines and accelerating logistics preparation cycles. WHO prequalification programs for temperature monitoring devices further standardize equipment procurement across emerging research markets. Stakeholders must evaluate whether their quality management systems can absorb simultaneous compliance with divergent FDA, EMA, and national pharmacopeia standards without fragmenting operational efficiency.
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles for temperature-controlled transport fleets while biotech pipelines expand demand for cryogenic handling capabilities. These dual pressures force logistics operators to absorb capital-intensive infrastructure upgrades against tightening margin structures.
Growth Catalysts
- Cell-and-gene therapy pipelines:Advanced therapy medicinal products require validated cryogenic chains at -150°C or below, creating specialized service tiers with premium economics.
- EMA Clinical Trials Regulation:Harmonized submission timelines across EU member states accelerate trial initiation and compress logistics preparation windows.
- Germany's pharmaceutical corridor:Concentrated biopharma manufacturing in Hesse and Baden-Württemberg generates dense demand for integrated clinical supply networks.
Market Restraints
- Refrigerant cost volatility:Phase-down schedules under F-Gas Regulation inflate replacement costs for transport refrigeration units and stationary cold stores.
- Qualified personnel scarcity:GDP-certified drivers and supply chain managers concentrate in established logistics hubs, limiting expansion into secondary markets.
- Intermodal handoff complexity:Temperature excursions multiply at airport tarmac transfers and customs clearance points, elevating insurance and remediation costs.
Strategic Opportunities
- Indian clinical trial expansion:CDSCO streamlines approval pathways for bioequivalence studies, opening demand for temperature-validated distribution to investigator sites.
- Real-time visibility platforms:Integration of IoT sensors with blockchain-based chain-of-custody records reduces dispute resolution costs and accelerates regulatory audit response.
- Decentralized trial models:Direct-to-patient shipping bypasses site-based inventory holding, requiring last-mile cold-chain capabilities in residential delivery networks.
Industry Challenges
- Multi-jurisdictional quality system alignment:Simultaneous compliance with FDA cGMP, EMA GDP, and national pharmacopeia standards fragments operational protocols and audit preparation.
- Legacy warehouse management integration:Temperature monitoring systems must interface with existing ERP platforms without disrupting validated state controls or creating data integrity gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Logistics Market |
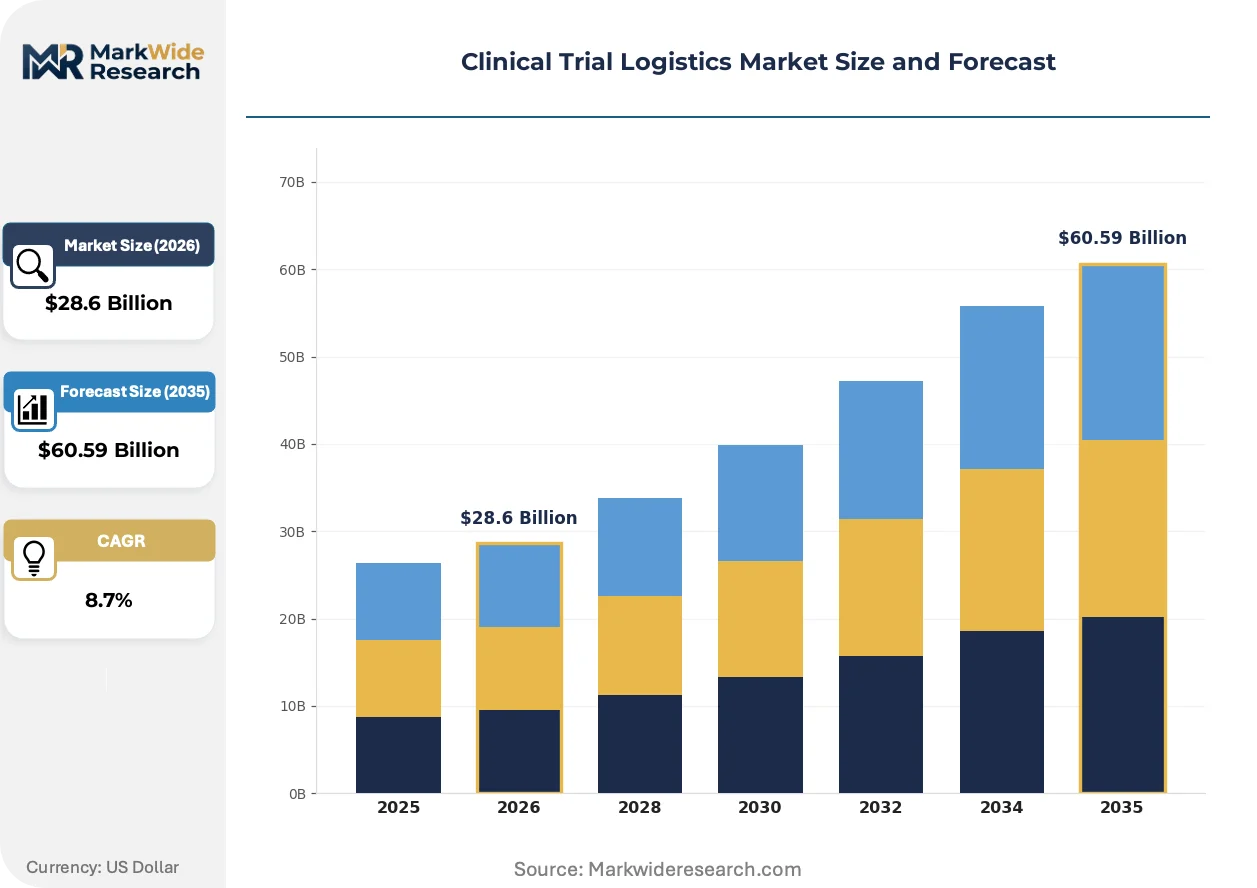
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Packaging, Transportation, Storage, Distribution Technology: Track & Trace, Temperature Control, Data Analytics, Automation End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Research Organizations Application: Drug Development, Patient Recruitment, Supply Chain Management, Regulatory Compliance |
| Companies Covered | Marken, Biocair International, Parexel International Corporation, CEVA Logistics, Catalent, Almac Group, Thermo Fisher Scientific, ICON, DHL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Logistics Market Evolving Landscape
Digital traceability infrastructure is displacing paper-based chain-of-custody documentation across temperature-sensitive shipments. This shift compresses investigation timelines for temperature excursions and enables predictive intervention before product compromise occurs.
Passive thermal packaging systems with phase-change materials are integrating active monitoring electronics to provide autonomous temperature assurance without external power. Biotech sponsors with complex stability requirements adopt these hybrid systems for international investigator site shipments. The technology is integrating cryogenic and controlled-ambient capabilities within single shipment configurations, reducing packaging inventory complexity.
EMA's F-Gas Regulation is mandating lower-global-warming-potential refrigerants in all new transport equipment placed on the EU market from 2025. Cold-chain fleet operators face accelerated depreciation schedules and retrofit obligations. German and Dutch logistics providers are responding with pilot programs for liquid nitrogen-powered transport units in cell-therapy distribution.
Biopharma procurement functions are consolidating vendor panels to reduce qualification overhead and capture volume-based service commitments. Large sponsors now mandate integrated packaging, distribution, and clinical returns management from single providers. This concentration is most pronounced among mid-cap biotech firms in the Boston-Cambridge cluster seeking to outsource non-core supply chain functions.
Clinical Trial Logistics Market Segmentation
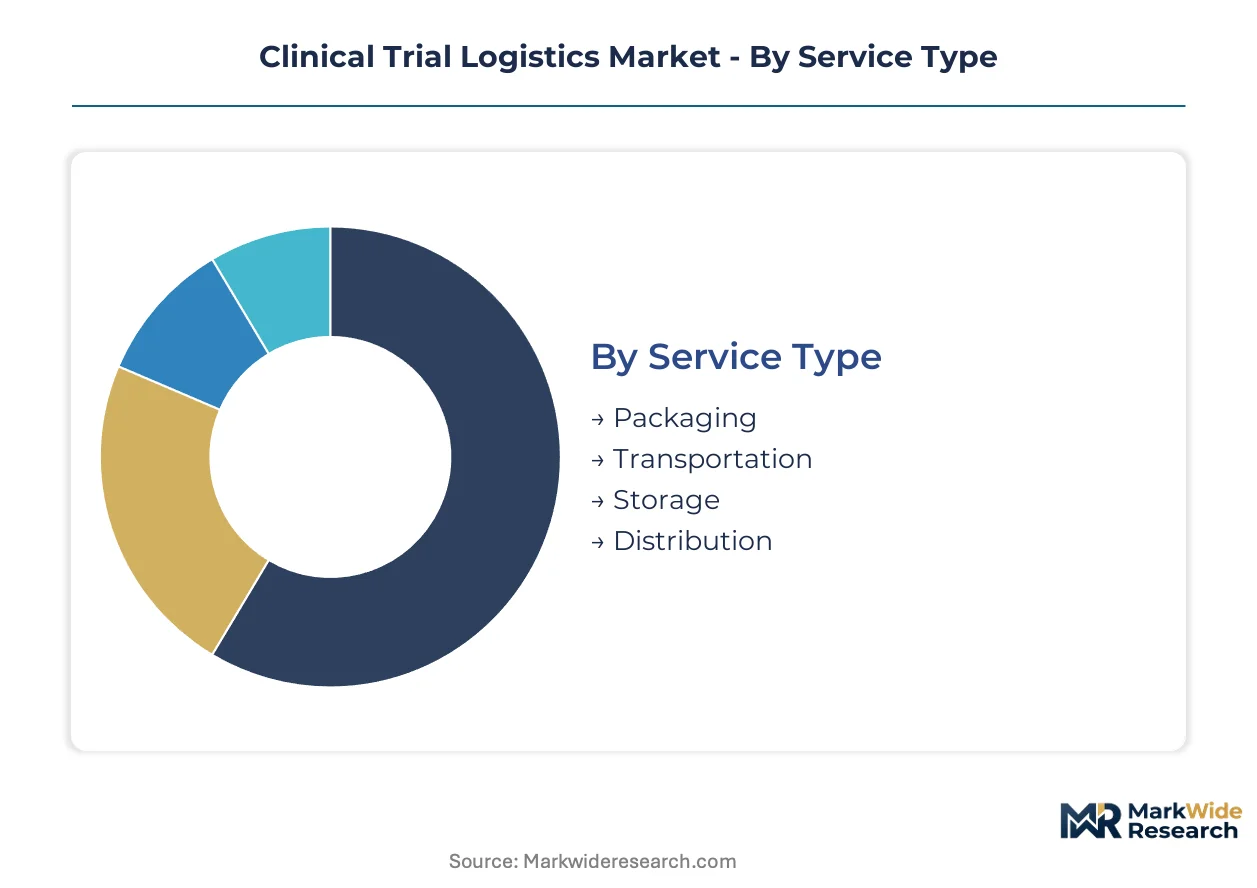
Service differentiation in clinical trial logistics determines vendor selection criteria and margin capture. Technology integration separates premium providers from commodity handlers. End-user concentration shapes regional infrastructure investments.
Service Type:
Temperature specification and chain-of-custody complexity define service tiering across operational modules.
- Packaging:Validated thermal containers with phase-change materials maintain 2-8°C, -20°C, or cryogenic ranges for investigational products. Serialization and labeling requirements under FDA cGMP and EMA GDP drive specialized demand from biotech firms in Germany's pharmaceutical corridor.
- Transportation:Cold-chain fleet operations with GDP-certified drivers execute time-critical movements between manufacturing sites, depots, and investigator locations. The EU F-Gas Regulation is compressing equipment replacement cycles while expanding biotech pipelines force capital-intensive upgrades against tightening margins.
- Storage:GMP-compliant warehousing with continuous temperature monitoring preserves investigational drug stability through validated environmental controls.
- Distribution:Multi-site inventory positioning and clinical returns management coordinate supply availability across decentralized trial networks.
Packaging leads on scale; Transportation leads on momentum.
Technology:
Digital infrastructure investment separates compliance-capable providers from operational laggards.
- Track & Trace:IoT-enabled sensors with blockchain-based chain-of-custody documentation deliver real-time visibility across international shipments. EMA's Clinical Trials Regulation mandates accelerated logistics preparation windows, compressing investigation timelines for temperature excursions.
- Temperature Control:Active refrigeration systems and passive thermal packaging with integrated monitoring electronics maintain molecular stability without external power. Biotech sponsors with complex stability requirements adopt hybrid configurations for international investigator site shipments.
- Data Analytics:Predictive algorithms identify excursion risks before product compromise occurs.
- Automation:Robotic handling systems reduce human error in high-throughput clinical supply operations.
Temperature Control anchors current revenue; Track & Trace is climbing the fastest.
End User:
Customer sophistication and outsourcing maturity determine service bundling and pricing power.
- Pharmaceutical Companies:Large sponsors consolidate vendor panels to reduce qualification overhead and capture volume commitments. Mid-cap biotech firms in the Boston-Cambridge cluster increasingly outsource non-core supply chain functions to integrated providers.
- Biotech Firms:Cell-and-gene therapy developers require validated cryogenic chains at -150°C or below, creating premium service tiers with specialized handling economics. CDSCO's streamlined approval pathways for bioequivalence studies in India open demand for temperature-validated distribution.
- Research Institutions:Academic medical centers with established cold-chain infrastructure represent price-sensitive demand.
- Contract Research Organizations:Maturing relationships with established vendor networks limit switching flexibility.
Pharmaceutical Companies dominate procurement volume; Biotech Firms generate the steepest expansion trajectory.
Application:
Regulatory intensity and patient proximity shape operational complexity across use cases.
- Drug Development:Investigational product logistics from preclinical through Phase III trials demands validated temperature controls and audit-ready documentation. WHO prequalification programs for temperature monitoring devices standardize equipment procurement across emerging research markets.
- Patient Recruitment:Direct-to-patient shipping models bypass site-based inventory holding, requiring last-mile cold-chain capabilities in residential delivery networks.
- Supply Chain Management:Inventory optimization and demand forecasting coordinate multi-site trial material availability.
- Regulatory Compliance:Multi-jurisdictional quality system alignment with FDA cGMP, EMA GDP, and national pharmacopeia standards fragments operational protocols.
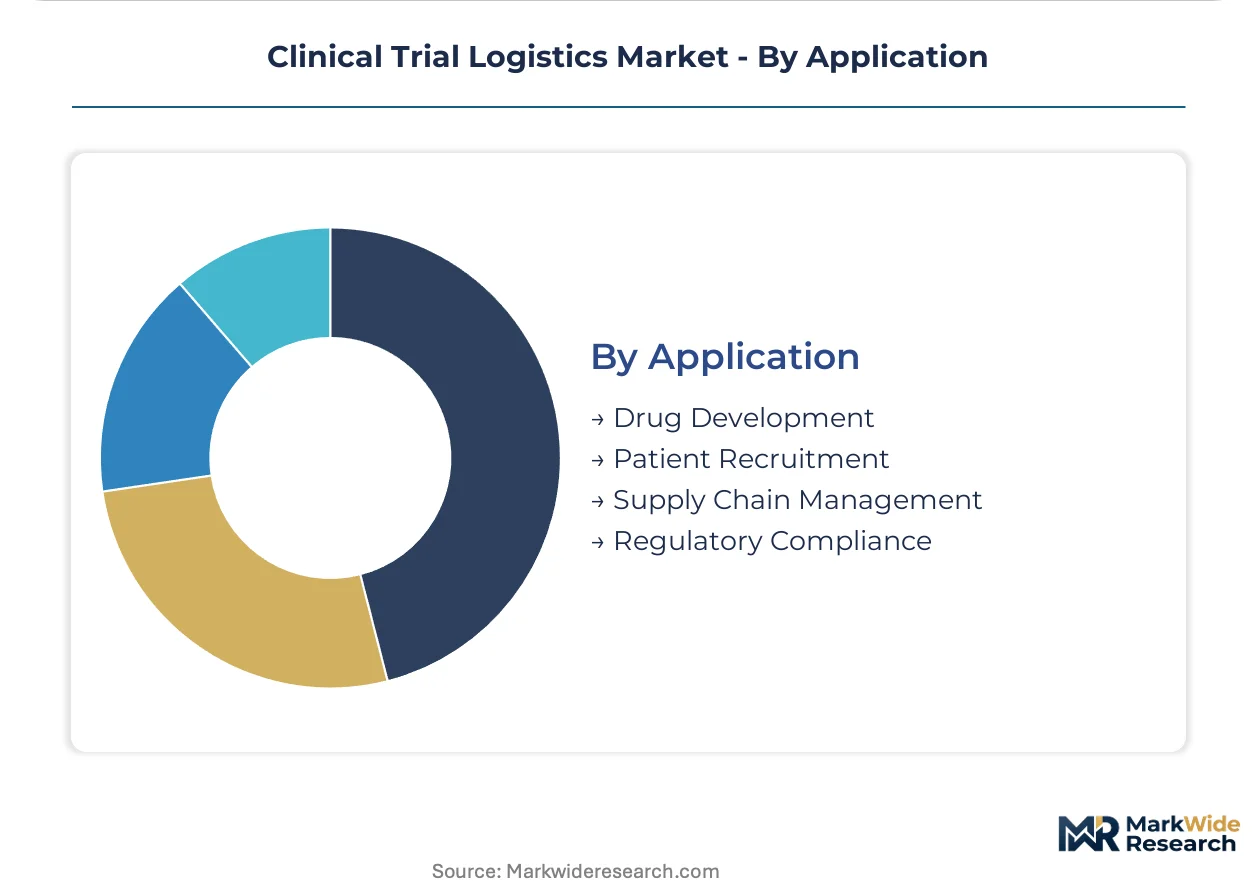
Drug Development captures the largest service spend; Patient Recruitment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial logistics originated in North American and Western European pharmaceutical clusters, where early Good Distribution Practice frameworks established the temperature-validated infrastructure now replicated worldwide. The industry's geographic footprint now tracks biopharma manufacturing concentration and regulatory harmonization progress across three continents.
United States
FDA cGMP enforcement shapes operational standards for cross-border trial material movements. The Boston-Cambridge biotech corridor generates concentrated demand for cryogenic chain services supporting cell-and-gene therapy development. Mid-cap sponsors in this cluster increasingly outsource integrated supply chain functions to specialized logistics providers.
Germany
Hesse and Baden-Württemberg host Europe's densest pharmaceutical manufacturing infrastructure, driving demand for validated cold-chain distribution networks. The EU F-Gas Regulation compresses equipment replacement cycles for transport refrigeration units operating across German trade lanes. Frankfurt's cargo hub anchors continental air freight connections for time-critical biological shipments.
India
CDSCO streamlined approval pathways for bioequivalence studies, accelerating trial initiation timelines and logistics preparation windows. Temperature-validated distribution networks expand to serve investigator sites in Hyderabad and Bangalore's clinical research zones. Domestic logistics operators invest in GDP-certified capabilities to capture sponsor outsourcing from Western multinationals.
United Kingdom
EMA's Clinical Trials Regulation harmonizes submission timelines across EU member states, compressing logistics preparation cycles for UK-based sponsors. London's financial and regulatory infrastructure supports contract research organization concentration with established vendor relationships. Post-Brexit customs complexity elevates demand for specialized cross-border documentation services.
Japan
PMDA's stringent stability requirements for biological products mandate validated temperature controls throughout distribution chains. The Kanto region's pharmaceutical manufacturing base generates demand for integrated clinical supply networks with real-time monitoring capabilities. Japanese sponsors consolidate vendor panels to reduce qualification overhead and capture volume-based service commitments.
Clinical Trial Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across temperature specification complexity and regulatory certification depth. The vendor base stratifies between integrated life sciences conglomerates with captive logistics divisions and specialized cold-chain operators with dedicated pharmaceutical infrastructure. Three archetypes dominate: full-service clinical supply integrators, temperature-specialized niche operators, and global freight forwarders with pharmaceutical certifications. Consolidation pressures favor acquisition of GDP-certified regional operators by scale players seeking geographic density.
Within the temperature-specialized tier, Marken and Biocair International exemplify operators built around validated cold-chain infrastructure rather than general freight capabilities. CEVA Logistics occupies a position among global forwarders that have acquired pharmaceutical certifications to compete in time-critical trial material movements. Thermo Fisher Scientific anchors the integrated conglomerate archetype, leveraging laboratory and manufacturing relationships to capture clinical supply outsourcing decisions.
| Leading Market Players |
|---|
| Marken |
| Biocair International |
| Parexel International Corporation |
| CEVA Logistics |
| Catalent |
| Almac Group |
| Thermo Fisher Scientific |
| ICON |
| DHL |
| Others |
Value Network & Pricing Analysis
Mid-cap biotech firms in the Boston-Cambridge cluster concentrate procurement decisions for cryogenic chain services, anchoring project-based pricing models that bundle packaging, transport, and returns management under single-provider contracts. Their outsourcing maturity compresses vendor qualification timelines while elevating premium tiers for specialized handling capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cryogenic chain specialists from GDP-certified generalists and commodity freight handlers. Price differentiation hinges on EMA GDP certification depth and real-time visibility integration, with premium tiers commanding substantial markups for validated -150°C capabilities. Cost compression in standard-tier transportation is intensifying because EU F-Gas Regulation retrofit obligations inflate fleet depreciation schedules. Research institutions exhibit highest price sensitivity, while cell-and-gene therapy developers accept premium positioning without volume negotiation.
Supply Chain Analysis
GDP certification density gates supplier participation, with qualified cold-chain infrastructure concentrating in Germany, the United States, and India. Equipment procurement draws from specialized transport refrigeration manufacturers, phase-change material suppliers, and IoT sensor providers. Single-source vulnerability runs through liquid nitrogen supply for cryogenic units, exposing operators to refrigerant cost volatility. Distribution runs through Frankfurt, Boston, and Hyderabad as primary consolidation hubs for time-critical biological shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical trial logistics functions as a late-cycle quality market where sponsor demand has shifted decisively toward cryogenic-validated infrastructure and real-time chain-of-custody documentation. Premium specification requirements now separate viable competitors from margin-compressed generalists.
For Market Incumbents: Lock in cryogenic chain certification density through accelerated fleet retrofit programs ahead of EU F-Gas Regulation phase-down deadlines. Consolidate regional GDP-certified operators in Germany's pharmaceutical corridor to defend against specialized niche entrants capturing cell-and-gene therapy accounts. Vertical integration into passive-active hybrid packaging manufacturing secures margin control against equipment cost inflation. For New Entrants and Emerging Players: The pricing gap between premium cryogenic specialists and GDP-certified standard handlers creates entry space for mid-tier providers with targeted -20°C to -80°C capabilities. White-space concentrates in Indian clinical trial expansion zones where CDSCO streamlined approvals outpace domestic cold-chain infrastructure development. A compliance-first positioning emphasizing rapid EMA GDP qualification distinguishes new entrants from established forwarders with pharmaceutical certifications. For Investors and Strategic Acquirers: Integrated life sciences conglomerates with captive logistics divisions are the most active acquirers in this space, seeking GDP-certified regional operators to fill geographic density gaps. Long-term viability favors platforms with validated cryogenic infrastructure as cell-and-gene therapy pipelines mature toward commercial scale. The signal to watch is sponsor consolidation of vendor panels to single-provider integrated contracts, accelerating competitive differentiation between full-service integrators and temperature-specialized operators.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Fleet Retrofit Program | EU F-Gas Regulation compliance preserves market access for temperature-validated transport operators. |
| GDP Certification Acceleration | EMA harmonized submission timelines compress qualification windows for new market entrants. |
| Real-Time Visibility Platform Integration | IoT-blockchain documentation reduces dispute resolution costs for cross-border biological shipments. |
| Regional Operator Acquisition | Geographic density in Germany's pharmaceutical corridor captures sponsor vendor consolidation decisions. |
| Hybrid Packaging System Development | Passive-active thermal containers address biotech sponsor inventory complexity for international trials. |
Research Methodology
Bottom-up biotech sponsor demand modeling reconciled against top-down cold-chain capacity tracking forms the analytical core of this study. Primary interviews with clinical supply chain directors, regulatory affairs leads, GDP-certified logistics operators, and hospital procurement managers combined with secondary validation against FDA cGMP inspection databases, EMA Clinical Trials Regulation submission portals, WHO prequalification device listings, and customs trade flow records. Triangulation across these sources isolates volume and pricing signals from reporting bias.
Historical trendline analysis of service revenue and fleet capacity expansion established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type, temperature specification tier, technology integration level, end-user sophistication, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of validated demand indicators and supply-side investment cycles, with cryogenic pipeline progression and decentralized trial adoption patterns serving as primary forecast inputs.
Caveats apply where refrigerant cost volatility under EU F-Gas Regulation or sponsor vendor consolidation acceleration could materially shift the outlook. Forecasts reflect assumptions regarding EMA Clinical Trials Regulation implementation pace and CDSCO approval pathway efficiency. A model refresh is warranted upon material change in biotech cryogenic pipeline conversion rates or regulatory harmonization progress across major research markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Biomarker Discovery Outsourcing Services Market